
 Cardiology PACS Market | 2026-2036
Cardiology PACS Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiology PACS Market Analysis
The EU Medical Device Regulation is recalibrating conformity requirements for diagnostic imaging software across European hospital networks. Fujifilm Healthcare leverages its endoscope-to-PACS integration to dominate cardiac cath lab workflows in Japan. GE Healthcare anchors its position through deep backward integration into CT and MRI hardware ecosystems. Philips Healthcare competes via AI-augmented echocardiography pipelines that feed directly into its cardiology PACS architecture.
Cardiology PACS denotes a specialized picture archiving and communication system engineered to store, retrieve, and distribute cardiac imaging modalities including angiography, echocardiography, and cardiac MRI at frame rates exceeding standard radiology PACS. These systems integrate DICOM 3.0 protocols with HL7 interfaces to synchronize hemodynamic data from cath labs with imaging archives for longitudinal patient tracking. Cloud PACS is capturing the fastest expansion as hospital IT departments abandon capital-intensive on-premises server farms for subscription-based deployment models. Diagnostic centers represent a concentrated margin pool where workflow optimization applications reduce report turnaround times and enable teleradiology services across distributed cardiac networks.
The FDA's software pre-certification program and the EU MDR's clinical evaluation requirements for Class IIa medical device software are tightening validation standards for AI-integrated cardiac analysis modules. HIPAA security rules in the United States and GDPR data localization mandates in Europe impose divergent architectural constraints on cross-border image exchange platforms. Stakeholders must monitor how jurisdictional fragmentation in cybersecurity certification reshapes vendor roadmaps and customer procurement criteria.
Market Dynamics
Cloud-native architectures are displacing on-premises cardiology PACS installations as hospital IT departments prioritize operational expenditure models over capital-intensive server infrastructure, compressing deployment timelines from months to weeks.
Growth Catalysts
- FDA Software Pre-Certification:The FDA's streamlined validation pathway accelerates AI-integrated cardiac analysis module approvals, reducing time-to-market for algorithm-enhanced diagnostic tools.
- HL7 FHIR Interoperability Mandates:Healthcare systems in Germany and Japan enforce standardized data exchange protocols, forcing PACS vendors to modernize interface architectures.
- Cath Lab Modernization Waves:Hospital networks across the United States replace aging angiography suites with integrated imaging ecosystems requiring real-time hemodynamic synchronization.
Market Restraints
- GDPR Data Localization:European patient imaging archives face architectural constraints that fragment cross-border teleradiology networks and inflate compliance costs.
- DICOM 3.0 Legacy Migration:Decades of proprietary image formats in installed base systems create technical debt that slows cloud transition timelines.
- Specialized Cardiac Informaticist Shortage:Healthcare facilities lack personnel trained to bridge clinical cardiology workflows with PACS administration functions.
Strategic Opportunities
- Diagnostic Center Networks:Independent cardiac imaging centers in the United States seek workflow optimization tools that enable distributed reporting across metropolitan catchment areas.
- AI-Augmented Echocardiography:Automated ventricular function analysis converges with PACS archives to create longitudinal cardiac monitoring datasets.
- Subscription-Based Deployment:SaaS pricing models open procurement to mid-tier hospitals previously excluded by capital budget constraints.
Industry Challenges
- HIPAA Security Rule Compliance:Cloud PACS vendors must architect multi-tenant environments that satisfy state-level breach notification variations.
- EU MDR Clinical Evaluation:Class IIa software certification demands retrospective validation studies that extend product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiology PACS Market |
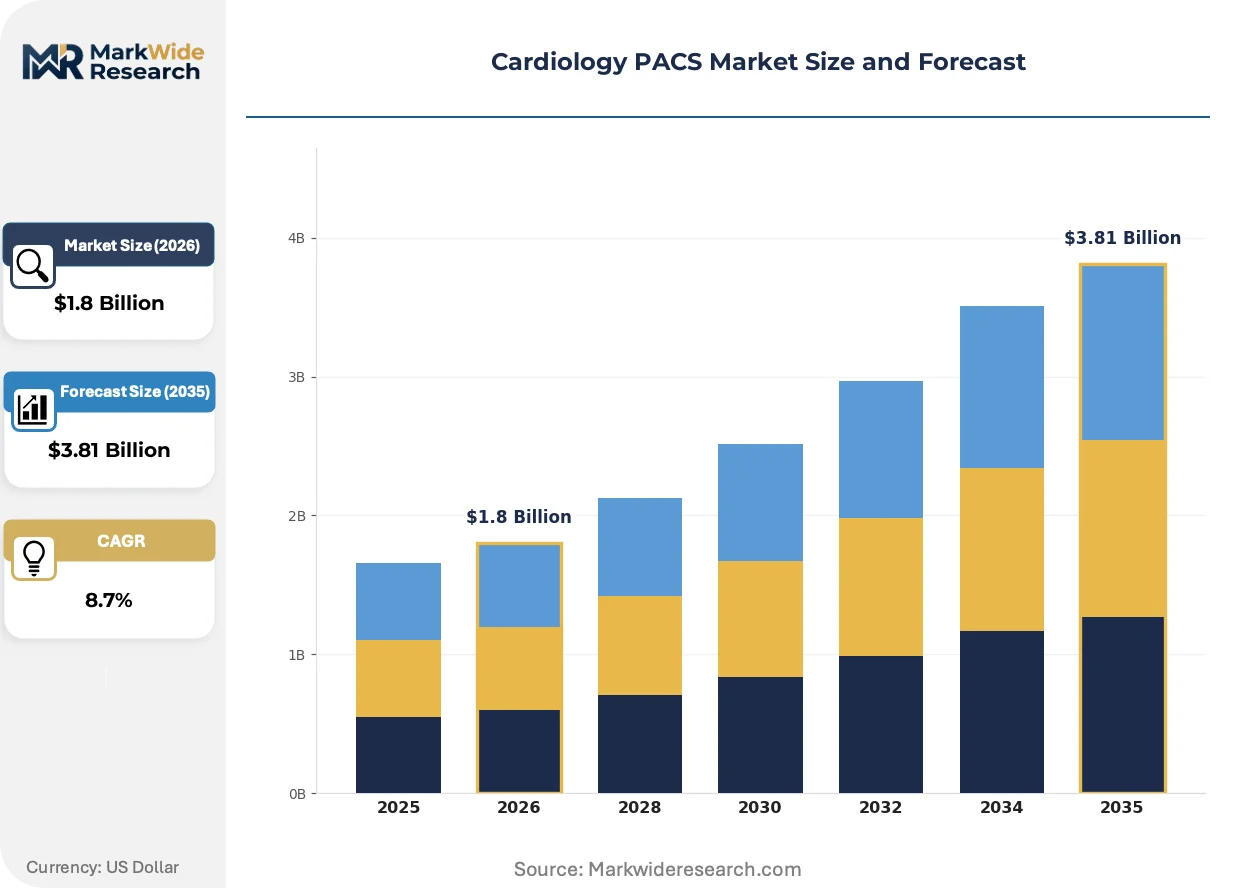
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web-Based PACS, Cloud PACS, Mobile PACS, On-Premises PACS End User: Hospitals, Diagnostic Centers, Clinics, Research Institutions Technology: DICOM, HL7, AI Integration, Data Security Application: Cardiac Imaging, Remote Monitoring, Data Management, Workflow Optimization |
| Companies Covered | Fujifilm Healthcare, INFINITT Healthcare, GE Healthcare, Carestream Health, Intelerad Medical Systems, Philips Healthcare, Sectra AB, Agfa HealthCare, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiology PACS Market Emerging Trajectories
Cardiology PACS is undergoing architectural transformation driven by three converging forces: virtualization of compute infrastructure, algorithmic automation of image interpretation, and restructuring of vendor-customer contractual relationships.
Edge computing nodes deployed within cath lab environments are consolidating image preprocessing workloads that previously required dedicated on-site servers. Hospital systems in Japan and Germany are installing these compact units to reduce latency between acquisition and archival. This distributed architecture is consolidating the traditional distinction between modality workstations and central PACS servers into unified edge-to-cloud pipelines.
The EU Medical Device Regulation's Class IIa classification for diagnostic imaging software imposes clinical performance documentation requirements that reshape product development roadmaps. Vendors must now maintain post-market surveillance systems tracking algorithm performance across diverse patient populations. Cardiac MRI analysis modules face the steepest compliance burden due to the complexity of volumetric reconstruction validation.
Hospital procurement departments are unbundling PACS acquisition from multi-year service contracts, compressing vendor switching cycles from decade-long lock-ins to renewable three-year terms. This behavioral shift forces suppliers to demonstrate continuous platform improvement rather than front-loaded feature differentiation. The United States exhibits the most aggressive contract restructuring as health system consolidation creates centralized purchasing leverage.
Cardiology PACS Market Segmentation
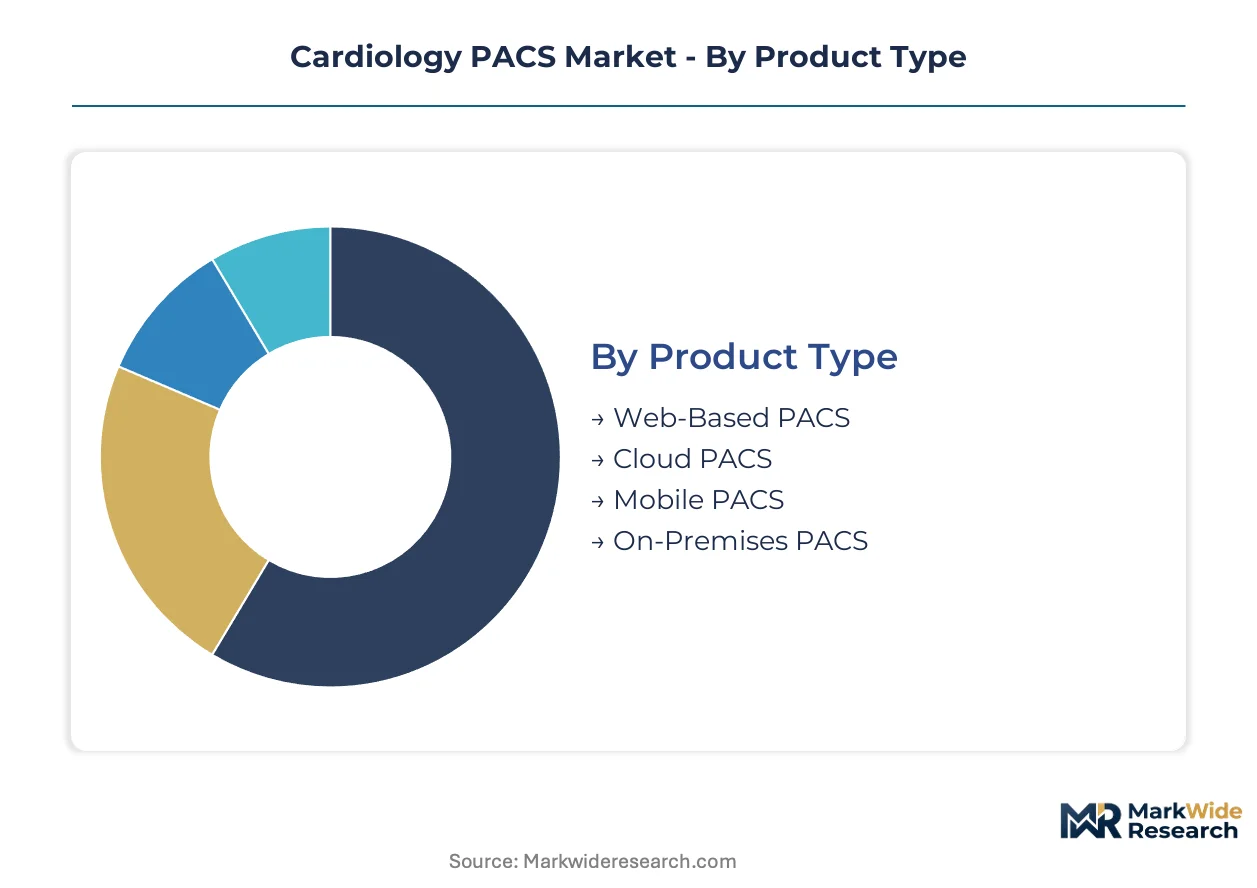
Cardiology PACS segmentation reveals how procurement priorities diverge across infrastructure maturity levels and clinical workflow requirements. Deployment architecture choices determine integration complexity, regulatory compliance pathways, and total cost of ownership trajectories for cardiac imaging networks.
Product Type:
Deployment model selection separates capital-constrained buyers seeking operational expenditure flexibility from institutions prioritizing data sovereignty and latency control.
- Cloud PACS:Subscription-based architectures eliminate server hardware procurement cycles and compress deployment timelines from months to weeks. Hospital systems in the United States and Germany are migrating cath lab infrastructure to multi-tenant environments that satisfy HIPAA and GDPR requirements through region-locked data residency configurations.
- On-Premises PACS:Capital-intensive installations retain full data control within institutional firewalls, appealing to academic medical centers with established IT operations teams. Japanese hospital networks maintain significant installed base of these systems due to historical preference for localized hardware ecosystems and PMDA validation pathways for software modifications.
- Web-Based PACS:Browser-accessible platforms enable thin-client deployment across distributed cardiac networks without dedicated workstation installation.
- Mobile PACS:Tablet-optimized interfaces support point-of-care image review during catheterization procedures and emergency department consultations.
Volume sits with On-Premises PACS; growth tilts toward Cloud PACS.
End User:
Facility scale dictates workflow complexity requirements and integration depth with existing electronic health record ecosystems.
- Hospitals:Integrated delivery networks demand enterprise-scale platforms synchronizing hemodynamic data from multiple cath labs with centralized imaging archives. These buyers prioritize HL7 FHIR interoperability and AI-augmented echocardiography pipelines that feed longitudinal patient tracking systems.
- Diagnostic Centers:Independent cardiac imaging facilities concentrate procurement of workflow optimization tools enabling distributed reporting across metropolitan catchment areas. Teleradiology service expansion in the United States drives demand for rapid report turnaround applications and cloud-native subscription pricing.
- Clinics:Outpatient cardiology practices require lightweight PACS configurations with streamlined DICOM routing to external specialists.
- Research Institutions:Academic centers prioritize volumetric reconstruction capabilities and multi-site data aggregation for clinical trial imaging cores.
Revenue concentrates in Hospitals; Diagnostic Centers are expanding most quickly.
Technology:
Technical architecture choices determine interoperability boundaries and regulatory classification under medical device software frameworks.
- AI Integration:Algorithm-augmented cardiac analysis modules automate ventricular function quantification and flag pathological findings for priority review. FDA software pre-certification pathways and EU MDR Class IIa clinical evaluation requirements impose validation documentation burdens that extend product launch schedules for these components.
- Data Security:Encryption protocols and access control architectures must satisfy divergent jurisdictional mandates including HIPAA security rules in the United States and GDPR data localization requirements in Europe.
- DICOM:Standardized imaging format protocols ensure modality compatibility across vendor equipment generations.
- HL7:Health information exchange interfaces synchronize PACS archives with electronic health record systems and hemodynamic monitoring devices.
Adoption concentrates in DICOM; AI Integration is gaining share fastest.
Application:
Functional use case segmentation aligns vendor development roadmaps with specific clinical productivity pain points and reimbursement optimization strategies.
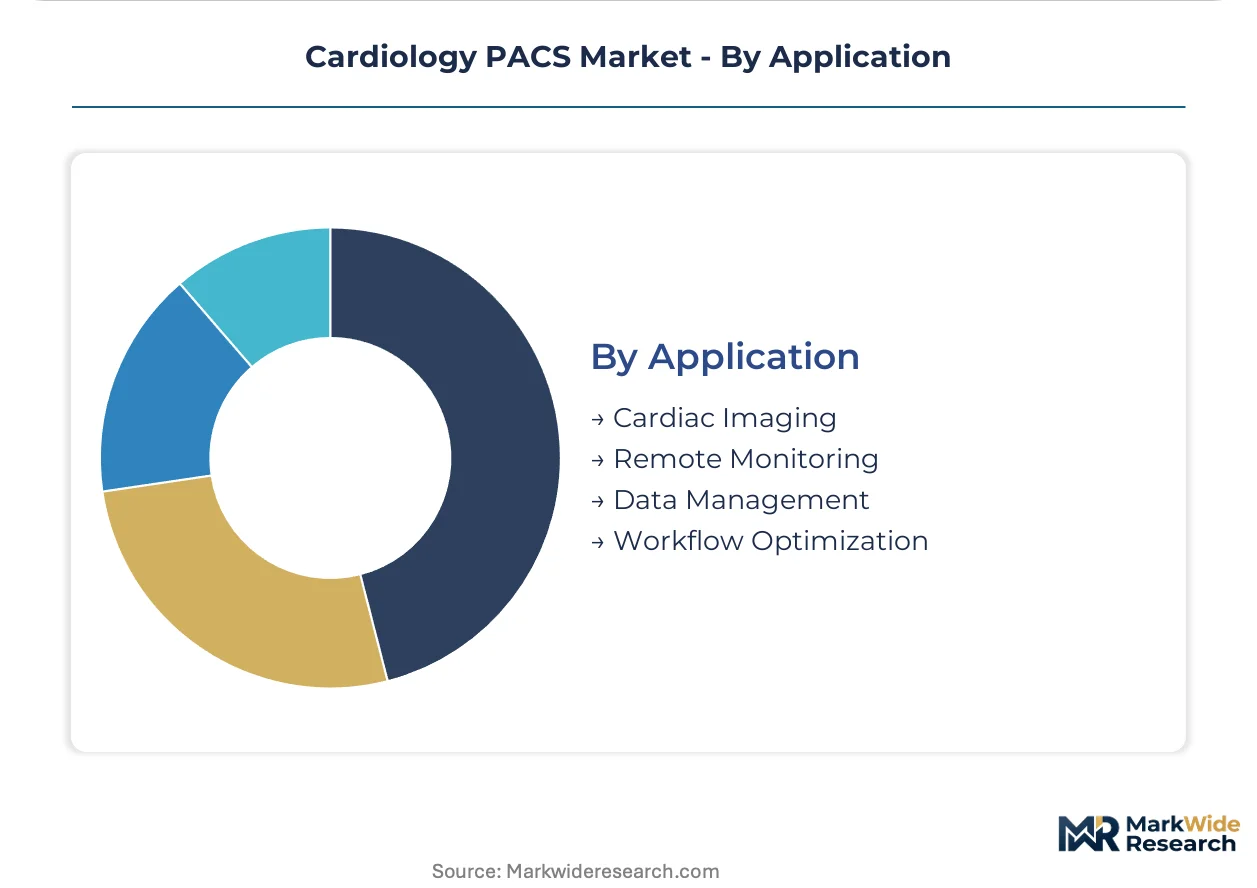
- Cardiac Imaging:Core PACS functionality encompasses angiography, echocardiography, and cardiac MRI at frame rates exceeding standard radiology systems. Demand concentrates in cath lab modernization waves across the United States, Germany, and Japan as hospital networks replace aging angiography suites.
- Workflow Optimization:Automated worklist management and structured reporting templates reduce cardiologist interpretation time and enable standardized quality metrics. Diagnostic center networks in the United States prioritize these tools to support distributed reading models across multiple metropolitan sites.
- Remote Monitoring:Cloud-based image access enables specialist consultation across geographic distances and after-hours coverage arrangements.
- Data Management:Longitudinal archiving and retrieval systems support population health analytics and retrospective research dataset assembly.
Deployment concentrates in Cardiac Imaging; Workflow Optimization is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's cardiac imaging corridor anchors procurement intensity for integrated cath lab ecosystems, with hospital networks across the Kanto region accelerating cloud-native PACS migration to synchronize hemodynamic data with enterprise archives.
United States
Hospital systems in Texas and California drive cath lab modernization waves, replacing aging angiography suites with AI-augmented imaging platforms. The FDA's software pre-certification program accelerates validation timelines for algorithm-enhanced cardiac analysis modules. The Cleveland Clinic corridor concentrates deployment of edge computing nodes that compress latency between acquisition and archival.
Germany
Integrated delivery networks in Bavaria and North Rhine-Westphalia enforce HL7 FHIR interoperability mandates across multi-site cardiac networks. The EU MDR's Class IIa clinical evaluation requirements impose retrospective validation burdens on diagnostic imaging software vendors. Berlin's Charité hospital cluster leads adoption of subscription-based deployment models that eliminate capital-intensive server procurement cycles.
Japan
Academic medical centers in Osaka and Nagoya maintain significant installed base of on-premises PACS due to PMDA validation pathways for software modifications. METI's digital health infrastructure subsidies accelerate edge computing deployment within cath lab environments. The Keiyō Industrial Belt concentrates manufacturing of modality workstations with backward integration into CT hardware ecosystems.
United Kingdom
NHS Trusts in London and the Midlands unbundle PACS acquisition from decade-long service contracts, compressing vendor switching cycles to renewable three-year terms. GDPR data localization mandates fragment cross-border teleradiology networks and inflate compliance costs for cloud archive configurations. The Oxford-Cambridge arc concentrates research institution procurement of volumetric reconstruction capabilities for clinical trial imaging cores.
Switzerland
Swiss university hospitals in Zurich and Geneva prioritize enterprise-scale platforms synchronizing hemodynamic data from multiple cath labs with centralized archives. Swissmedic's software-as-medical-device framework tightens validation standards for AI-integrated cardiac analysis modules. The Basel pharmaceutical corridor drives demand for longitudinal cardiac monitoring datasets that converge automated ventricular function analysis with PACS archives.
Cardiology PACS Market Vendor Landscape
Premium-margin players sit above commodity-margin players across deployment architecture sophistication, with consolidated tier-one vendors controlling enterprise-scale hospital networks while specialized mid-tier suppliers capture diagnostic center workflow optimization demand. The vendor base stratifies into three archetypes: imaging hardware incumbents with backward integration into modality manufacturing, pure-play PACS software specialists with cloud-native subscription models, and teleradiology platform operators with distributed reporting networks. Dominant competitive moves include strategic partnerships between AI algorithm developers and archive platform vendors, plus geographic expansion through regional data residency configurations that satisfy HIPAA and GDPR requirements.
Among diversified imaging hardware suppliers, GE Healthcare and Siemens Healthineers exemplify the integrated-systems archetype through captive supply of CT and MRI ecosystems that anchor cardiology PACS procurement decisions. Philips Healthcare occupies a position within the AI-augmented diagnostic tier, representing vendors that converge automated image analysis with longitudinal patient tracking architectures. Fujifilm Healthcare anchors the endoscope-to-PACS integration segment, exemplifying specialists that dominate cardiac cath lab workflows through modality-to-archive pipeline control.
| Leading Market Players |
|---|
| Fujifilm Healthcare |
| INFINITT Healthcare |
| GE Healthcare |
| Carestream Health |
| Intelerad Medical Systems |
| Philips Healthcare |
| Sectra AB |
| Agfa HealthCare |
| Siemens Healthineers |
| Others |
Supply Flow & Price Mechanics
Backward integration into modality hardware manufacturing anchors pricing power for imaging equipment incumbents while compressing margins for pure-play software vendors competing on subscription economics. Cloud-native deployment models are displacing capital-intensive server procurement, forcing suppliers to recapture value through recurring revenue streams rather than front-loaded license fees.
Pricing Analysis
Outcome-based pricing tied to report turnaround time and diagnostic accuracy metrics anchors value propositions for AI-augmented cardiac analysis modules. Three-tier pricing structure across premium, standard, and economy levels separates enterprise hospital networks from mid-tier diagnostic centers and outpatient clinics. Price differentiation centers on HL7 FHIR interoperability depth and FDA software pre-certification status. Cost compression in the standard tier is intensifying because cloud infrastructure commoditization erodes hardware-linked premiums. Diagnostic center networks exhibit highest price sensitivity due to thin operating margins, while academic medical centers prioritize data sovereignty over cost optimization.
Supply Chain Analysis
Specialized cardiac informaticist shortages in the United States, Germany, and Japan constrain deployment velocity for complex cath lab integration projects. Hardware component sourcing draws from Taiwan for edge computing nodes, Germany for precision modality workstations, and Japan for endoscope manufacturing integration. Cloud infrastructure provisioning rests on hyperscaler data residency configurations satisfying HIPAA and GDPR constraints. Single-source vulnerability concentrates in AI algorithm training datasets requiring diverse patient population representation. Distribution runs through direct hospital system contracts, GPO procurement channels, and regional value-added resellers serving diagnostic center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive control over CT and MRI hardware ecosystems determines PACS procurement decisions. Players are pursuing downstream leverage through AI-augmented diagnostic pipelines that lock longitudinal patient data into proprietary archives.
For Market Incumbents: Extend AI-augmented echocardiography capabilities to create switching costs that resist cloud-native challengers. Defend against pure-play SaaS vendors by bundling hemodynamic synchronization with hardware refresh cycles. Invest in FDA software pre-certification pathways to accelerate algorithm module approvals ahead of emerging entrants.
For New Entrants and Emerging Players: Mid-tier diagnostic centers in the United States represent the most penetrable buyer archetype due to capital budget constraints and distributed reporting needs. Target workflow optimization applications that reduce cardiologist interpretation time across metropolitan catchment areas. Pursue teleradiology platform partnerships as the primary go-to-market angle, bypassing entrenched hospital system procurement committees.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by imaging hardware incumbents seeking AI capabilities and cloud-native architectures. Long-term viability hinges on demonstrating post-market surveillance systems that satisfy EU MDR Class IIa clinical evaluation requirements. Watch FDA software pre-certification expansion as the signal indicating accelerated consolidation timelines for algorithm-augmented diagnostic tools.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Subscription pricing opens procurement to mid-tier hospitals previously excluded by capital constraints. |
| AI Algorithm Integration | FDA pre-certification pathways accelerate validation timelines for automated ventricular function analysis modules. |
| HL7 FHIR Interoperability Investment | German and Japanese mandates force modernization of interface architectures for multi-site cardiac networks. |
| Edge Computing Deployment | Tokyo and Cleveland clinic corridors compress latency between cath lab acquisition and cloud archival. |
| EU MDR Compliance Infrastructure | Post-market surveillance systems satisfy Class IIa clinical evaluation requirements for diagnostic imaging software. |
Methodological Framework
Independent corroboration across hospital CIO interviews, cath lab administrator surveys, and GPO contract databases underwrites the qualitative findings in this analysis. Primary fieldwork engaged cardiac imaging directors, biomedical engineers, and health system procurement managers across integrated delivery networks in the United States, Germany, and Japan. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, hospital capital expenditure disclosures, and CMS Medicare reimbursement data. Bottom-up deployment model sizing triangulates against top-down imaging modality installation base estimates.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. The analytical framework models deployment architecture, end-user facility scale, technology integration depth, and clinical application intensity. CAGRs derive from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporate cath lab modernization wave timing, HL7 FHIR interoperability mandate compliance deadlines, and AI algorithm regulatory approval velocity.
Revisions become necessary when FDA software pre-certification scope expansion, EU MDR enforcement intensity shifts, or hyperscaler data residency configuration changes materialize. Forecasts reflect documented assumptions regarding hospital IT budget allocation patterns and cloud infrastructure adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Medical Imaging Informatics Market
Medical Imaging
Breast MRI Screening Market
Medical Imaging
Open Magnetic Resonance Imaging System Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
Mexico Computed Tomography Market
Medical Imaging
C-Arms Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
Asia Pacific Nuclear Imaging Devices Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
Perfusion Imaging Market
Medical Imaging
Global Orthopedic Imaging Equipment Market
Medical Imaging
Multiphoton Microscopy Market
Medical Imaging
Global MRI Scanner Market