
 Bilirubin Meters Market | 2026-2036
Bilirubin Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Bilirubin Meters Market Outlook
German precision sensor manufacturing is decoupling from legacy invasive testing supply chains. Siemens Healthineers leverages its Heidelberg-based diagnostic imaging heritage to anchor transcutaneous bilirubin measurement platforms. Dragerwerk AG & Co. KGaA sustains neonatal care equipment dominance through Lübeck engineering centers. Natus Medical Incorporated competes in North American distribution channels for pediatric monitoring devices.
Bilirubin meters quantify serum or transcutaneous bilirubin concentration using reflectance photometry or colorimetry, typically operating within measurement ranges of 0.3 to 30 mg/dL to support jaundice management decisions. These devices serve neonatal care units where kernicterus prevention demands rapid, non-invasive screening at the point of care. Handheld devices command the largest installed base due to ward mobility requirements, while continuous monitors represent the fastest-expanding segment as intensive care protocols shift toward real-time bilirubin trend monitoring. Transcutaneous measurement technology leads technology preference rankings among neonatal nurses seeking to minimize heel-stick blood draws.
The US FDA 510(k) clearance framework governs device market entry, while the EU Medical Device Regulation imposes post-market surveillance obligations on manufacturers serving European hospitals. China's NMPA enforces GB standard compliance for imported diagnostic equipment, creating separate technical file requirements. Stakeholders must monitor evolving harmonization between FDA breakthrough device designation criteria and EU MDR clinical evidence expectations to optimize dual-market registration strategies.
Market Dynamics
Neonatal intensive care protocols are pivoting from episodic heel-stick sampling to continuous transcutaneous monitoring, compressing device replacement cycles and forcing manufacturers to embed wireless telemetry into handheld platforms.
Growth Catalysts
- EU MDR post-market surveillance mandates:European hospitals must document clinical outcomes for Class II diagnostic devices, creating replacement demand for legacy meters lacking connectivity audit trails.
- Transcutaneous photometry advancement:Multi-wavelength LED arrays now match laboratory spectrophotometry accuracy at point-of-care, eliminating blood draw workflows in maternity wards.
- Germany's Rhineland precision manufacturing cluster:Concentrated optoelectronics foundries in Heidelberg-Stuttgart corridor supply calibrated sensor modules to meter assemblers at scale.
Market Restraints
- Optical component supply concentration:Narrowband interference filters and silicon photodiodes depend on Japanese and German specialty foundries with limited surge capacity.
- Calibration drift in continuous monitors:Ambient light interference and skin temperature variation degrade measurement stability, requiring frequent recalibration protocols that strain nursing workflows.
- FDA 510(k) substantial equivalence barriers:Predicate device limitations constrain algorithm innovations, forcing developers to validate against decades-old reference methods.
Strategic Opportunities
- India's expanding NICU infrastructure:Government-funded neonatal care networks in Maharashtra and Tamil Nadu lack point-of-care bilirubin screening, creating first-mover openings for portable device distributors.
- Integration of pulse oximetry with bilirubin sensing:Dual-parameter neonatal monitors reduce bedside equipment clutter, appealing to space-constrained intensive care units.
- Cloud-connected meter fleets:Subscription-based device management with automated quality control reporting addresses hospital procurement committees prioritizing total cost of ownership metrics.
Industry Challenges
- Firmware validation for FDA cybersecurity guidance:Premarket submissions now require documented threat modeling and software bill of materials, extending development timelines for connected devices.
- Biomedical engineering talent scarcity:Cross-disciplinary expertise combining neonatal physiology, photonics, and embedded systems concentrates in Boston, Basel, and Singapore hiring markets.
- Legacy meter obsolescence management:Hospital capital equipment depreciation cycles lag technology refresh rates, creating stranded asset conflicts with quality improvement initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bilirubin Meters Market |
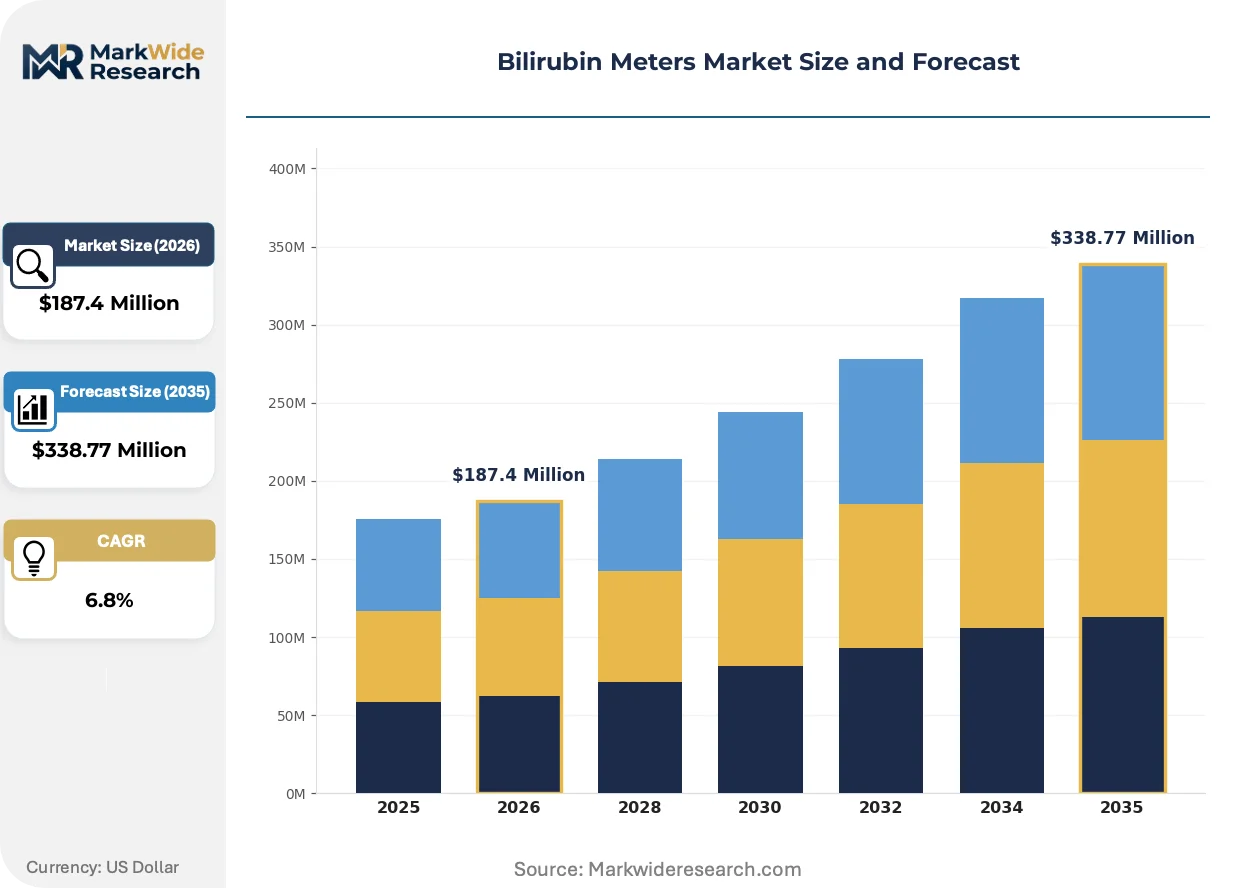
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Portable Meters, Laboratory Instruments, Continuous Monitors End User: Hospitals, Clinics, Home Care, Diagnostic Laboratories Technology: Transcutaneous Measurement, Invasive Measurement, Reflectance Photometry, Colorimetry Application: Neonatal Care, Liver Function Testing, Blood Testing, Pediatric Monitoring |
| Companies Covered | Abbott Laboratories, APEL Co. Ltd., Dragerwerk AG & Co. KGaA, Ningbo David Medical Device Co. Ltd., Natus Medical Incorporated, Siemens Healthineers AG, Koninklijke Philips N.V., Mennen Medical Ltd., F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bilirubin Meters Market Strategic Shifts
Device architecture is fragmenting into interchangeable sensor heads and wireless base units, enabling hospitals to standardize platforms while swapping measurement modalities. This modularity is compressing upgrade costs and accelerating technology refresh adoption curves.
Multi-spectral LED engines are modularizing transcutaneous measurement hardware. Neonatal nurse practitioners in tertiary care centers are adopting these platforms within eighteen-month replacement windows. The technology is modularizing supply chains, allowing meter manufacturers to source calibrated optical subassemblies from specialized photonics foundries rather than maintaining captive fabrication.
The FDA's 2023 cybersecurity premarket guidance is reshaping device architecture requirements. Manufacturers must now embed software update mechanisms and cryptographic authentication, adding firmware complexity but reducing post-market vulnerability exposure. Handheld meter segments face the steepest compliance cost increases as these units lack the processing headroom of cart-based systems.
Hospital procurement committees are unbundling device acquisition from calibration service contracts. Group purchasing organizations negotiate meter purchases separately from annual maintenance agreements, pressuring manufacturers to compete on hardware margins while defending recurring revenue streams. This bifurcation is most pronounced in US health systems consolidating vendor panels under regional purchasing alliances.
Bilirubin Meters Market Segmentation
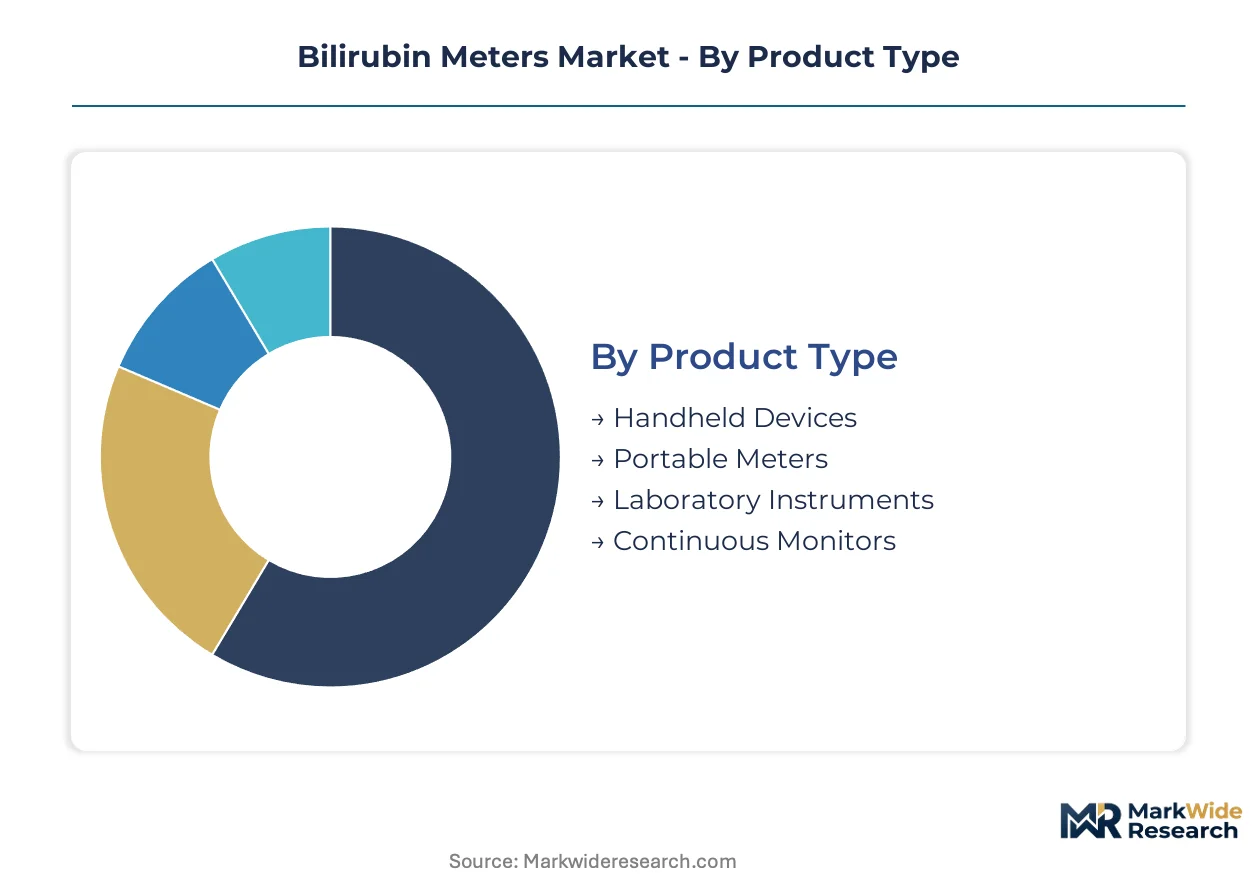
Bilirubin meter procurement splits sharply between high-volume ward mobility tools and premium continuous monitoring platforms. Understanding where each segment commands price premiums versus where scale economies dominate purchasing decisions clarifies manufacturer positioning strategies across hospital networks.
Product Type:
Volume concentration sits with handheld units deployed at bedside, while premium pricing attaches to continuous monitoring systems integrating with electronic health records.
- Handheld Devices:Compact photometry units weighing under 500 grams enable neonatal nurses to perform transcutaneous screening across maternity wards without transporting infants. German Rhineland manufacturing clusters supply calibrated LED modules to assemblers serving hospital networks in Bavaria and Baden-Württemberg, where NICU bed density drives replacement demand every 24-36 months.
- Continuous Monitors:Multi-sensor platforms stream real-time bilirubin trends to central nursing stations via wireless telemetry, eliminating episodic heel-stick workflows. Tertiary care centers in Heidelberg and Stuttgart corridors are adopting these systems fastest as intensive care protocols shift toward automated surveillance.
- Portable Meters:Cart-based systems bridge handheld mobility with laboratory-grade accuracy for intermediate care settings.
- Laboratory Instruments:High-throughput spectrophotometers process batch serum samples in hospital core labs and reference facilities.
Mature deployment sits with handheld devices. Newer deployment is concentrated in continuous monitors.
End User:
Procurement authority concentrates with hospital materials management departments, while cost sensitivity intensifies as purchasing decisions devolve to outpatient and home settings.
- Hospitals:Neonatal intensive care units command the dominant installed base, with procurement committees prioritizing wireless connectivity and FDA 510(k) clearance documentation. Academic medical centers in Massachusetts and California drive early adoption of multi-parameter platforms integrating bilirubin sensing with pulse oximetry.
- Diagnostic Laboratories:Centralized testing facilities maintain serum-based reference methods for complex cases, purchasing high-volume spectrophotometry systems with automated sample handling. These operations concentrate in metropolitan hospital networks where economies of scale justify dedicated bilirubin testing lines separate from general chemistry analyzers.
- Clinics:Outpatient pediatric practices favor portable transcutaneous meters for same-day jaundice screening.
- Home Care:Post-discharge monitoring programs in select health systems deploy simplified handheld units for parent-operated screening.
Revenue concentration rests with hospital networks. Fastest expansion is occurring in diagnostic laboratories consolidating testing volumes.
Technology:
Transcutaneous methods are displacing invasive workflows in point-of-care settings, while reference laboratories preserve serum-based techniques for medico-legal documentation.
- Transcutaneous Measurement:Multi-wavelength LED arrays press against infant skin to quantify bilirubin concentration through optical reflectance, eliminating blood draws. Maternity wards across Rhineland-Palatinate and Hesse have standardized on these platforms to reduce iatrogenic anemia risks in preterm infants.
- Reflectance Photometry:Benchtop analyzers measure light absorption across calibrated wavelengths for serum samples, maintaining gold-standard accuracy for contested clinical decisions. Reference laboratories in Berlin and Munich metropolitan areas retain these systems for secondary confirmation of borderline transcutaneous readings.
- Invasive Measurement:Direct serum bilirubin quantification via venipuncture or heel-stick sampling persists for hyperbilirubinemia cases requiring exchange transfusion decisions.
- Colorimetry:Diazotization-based chemical reactions produce color intensity proportional to bilirubin concentration in processed samples.
Installed base dominance belongs to transcutaneous measurement. Reflectance photometry maintains reference-standard status in laboratory settings.
Application:
Neonatal applications command premium pricing due to kernicterus prevention urgency, while liver function testing competes within broader metabolic panel commoditization.
- Neonatal Care:Point-of-care screening within 24 hours of birth prevents neurotoxicity from unconjugated hyperbilirubinemia, driving demand for non-invasive meters with sub-minute measurement cycles. Level III NICUs in Tamil Nadu and Maharashtra are expanding meter procurement as government-funded neonatal networks reach district hospital tiers.
- Liver Function Testing:Adult hepatology departments incorporate bilirubin measurement within comprehensive metabolic panels, limiting standalone meter demand. German university hospitals integrate these readings into automated liver fibrosis scoring algorithms alongside elastography and serum markers.
- Blood Testing:General chemistry analyzers process bilirubin as one parameter among dozens in routine health screenings.
- Pediatric Monitoring:Post-neonatal follow-up programs track resolving jaundice in outpatient settings.
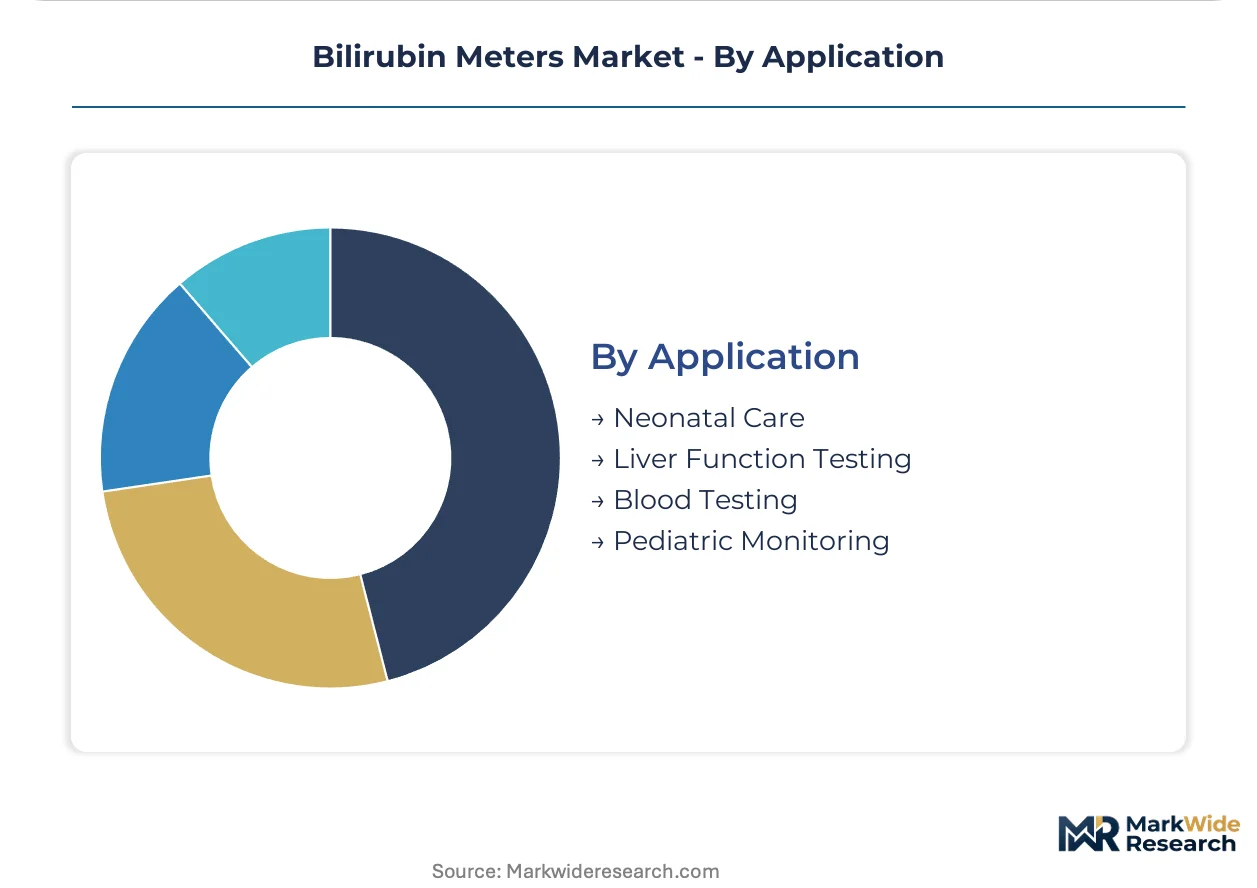
Technology maturity clusters in neonatal care. Liver function testing represents the fastest-climbing application as non-alcoholic fatty liver disease screening expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical sensor foundries in Japan's Kansai region supply narrowband interference filters that calibrate transcutaneous measurement accuracy. German Rhineland photonics clusters and US FDA-regulated device corridors anchor finished meter production.
United States
Massachusetts and California academic medical centers drive multi-parameter platform adoption integrating bilirubin sensing with pulse oximetry. FDA 510(k) premarket notification requirements govern device clearance timelines and predicate device selection. Greater Boston biomedical engineering talent pools support firmware development for wireless telemetry integration.
Germany
Bavaria and Baden-Württemberg NICU bed density generates replacement demand every 24-36 months for calibrated LED modules. EU MDR post-market surveillance obligations mandate connectivity audit trails for Class II diagnostic devices. Heidelberg-Stuttgart corridor optoelectronics foundries supply sensor modules to meter assemblers at scale.
China
Government-funded neonatal care networks in district hospital tiers lack point-of-care bilirubin screening infrastructure. NMPA enforces GB standard compliance for imported diagnostic equipment, creating separate technical file requirements. Yangtze River Delta manufacturing hubs assemble portable meters for domestic distribution.
India
Maharashtra and Tamil Nadu government-funded neonatal networks are expanding meter procurement as care reaches district hospital tiers. CDSCO medical device regulations govern import licensing and clinical evaluation requirements for diagnostic equipment. Bangalore medical device distributors target first-mover positioning in underserved NICU infrastructure.
Japan
Tokyo metropolitan tertiary care centers adopt continuous monitoring systems for automated bilirubin surveillance protocols. PMDA pharmaceutical and medical device agency reviews premarket submissions for optical measurement accuracy claims. Kansai region specialty foundries manufacture silicon photodiodes with limited surge capacity.
Bilirubin Meters Market Competitive Environment
Global majors compete with regional champions across regulatory clearance capabilities and photonics supply chain access. Market structure concentrates around diversified health technology conglomerates with diagnostic imaging heritage and specialized neonatal care equipment fabricators. Three archetypes dominate: precision sensor-integrated platform builders, neonatal monitoring specialists, and diversified laboratory instrumentation houses. Competitive moves center on wireless telemetry embedding and cloud-connected fleet management service layering.
Among German-based health technology conglomerates, Siemens Healthineers AG and Dragerwerk AG & Co. KGaA occupy positions anchoring transcutaneous measurement platform development. Natus Medical Incorporated represents North American distribution channel competition for pediatric monitoring devices. These three exemplify the geographic clustering of neonatal care equipment expertise across Rhineland engineering centers and US coastal medical technology corridors.
| Leading Market Players |
|---|
| Abbott Laboratories |
| APEL Co. Ltd. |
| Dragerwerk AG & Co. KGaA |
| Ningbo David Medical Device Co. Ltd. |
| Natus Medical Incorporated |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| Mennen Medical Ltd. |
| F. Hoffmann-La Roche Ltd. |
| Others |
Value Chain & Pricing Dynamics
Silicon photodiode wafer costs cascade through German and Japanese specialty foundries into three distinct pricing tiers downstream, with calibration-intensive continuous monitors commanding premium positioning against commoditized handheld units where procurement committees unbundle hardware from service contracts.
Pricing Analysis
Warranty and calibration service bundling separates premium continuous monitoring platforms from unbundled handheld procurement. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier and optical sensor accuracy grade. Cost compression in economy handheld tiers is intensifying because group purchasing organizations negotiate meter purchases separately from annual maintenance agreements. Diagnostic laboratories exhibit lowest price sensitivity due to batch throughput economics, while district hospital networks in emerging markets drive hardest hardware margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with Japanese Kansai region foundries manufacturing narrowband interference filters with limited surge capacity. German Rhineland and Japanese Kansai clusters anchor calibrated optical subassembly production, while Chinese Yangtze River Delta hubs assemble finished portable meters. Supply chain risk centers on tariff exposure for silicon photodiodes crossing from Japanese specialty foundries into German meter assembly operations. Distribution runs through hospital group purchasing organizations and regional medical device distributors serving NICU procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-spectral LED transcutaneous platforms are displacing legacy heel-stick blood draw workflows, compressing replacement cycles and forcing architectural shifts toward wireless telemetry integration across installed meter fleets.
For Market Incumbents: Cement sensor module supply relationships with Heidelberg-Stuttgart corridor photonics foundries to defend against optical component bottlenecks. Deepen backward integration into calibrated LED array fabrication to preserve margin structure as procurement committees unbundle hardware from service contracts. Prioritize firmware cybersecurity validation investments to maintain FDA 510(k) clearance velocity against emerging connected device entrants. For New Entrants and Emerging Players: Regional distributors in Maharashtra and Tamil Nadu offer first-mover positioning as government-funded NICU networks reach district hospital tiers. Target India's expanding neonatal infrastructure with simplified handheld units priced for capital-constrained procurement committees. Pursue CDSCO import licensing partnerships with established Bangalore medical device distributors to accelerate market entry timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-connected meter fleet operators with recurring revenue service layers in North American hospital networks. Long-term viability hinges on software subscription attach rates rather than hardware shipment volumes. Watch FDA breakthrough device designation awards as inflection indicators for algorithm innovation premiums translating into pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Cybersecurity Compliance Pathway | Premarket submissions now require documented threat modeling and software bills of materials for connected handheld platforms. |
| Heidelberg-Stuttgart Photonics Cluster Partnership | Calibrated sensor module sourcing from Rhineland foundries secures optical accuracy specifications for transcutaneous measurement. |
| Cloud-Connected Fleet Management Service | Subscription-based device management with automated quality control reporting addresses hospital total cost of ownership metrics. |
| India CDSCO Import Licensing Acceleration | Clinical evaluation requirements for diagnostic equipment create partnership opportunities with established regional distributors. |
| Pulse Oximetry-Bilirubin Dual-Parameter Integration | Multi-sensor platforms reduce bedside equipment clutter in space-constrained Level III NICU environments. |
Study Parameters
Multi-period observation of FDA 510(k) clearance timelines and EU MDR post-market surveillance compliance patterns anchored the trend analysis, supplemented by interviews with neonatal intensive care unit directors, biomedical engineering managers, hospital procurement committee leads, and group purchasing organization contract specialists. Secondary validation drew from FDA premarket notification databases, EU MDR technical documentation filings, hospital capital equipment procurement records, and photonics industry trade association reports. Bottom-up meter shipment estimates triangulated against top-down healthcare expenditure allocations for neonatal diagnostic equipment.
Input-output matrices mapped transcutaneous measurement technology adoption curves across handheld, continuous monitor, portable meter, and laboratory instrument segments, with deployment model, end-user facility tier, and regional regulatory framework as cross-cutting dimensions. CAGRs were derived from installed base replacement cycle compression and real-time monitoring protocol penetration trajectories across the projection horizon. Forecast inputs incorporated optical sensor foundry capacity utilization rates and NICU bed density expansion plans in target geographies.
Caveats apply where FDA cybersecurity guidance evolution or EU MDR clinical evidence requirement harmonization shifts could materially shift the outlook. Forecasts reflect documented assumptions regarding wireless telemetry adoption velocity and cloud-connected fleet management service attach rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Interatrial Shunt Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Liposuction Devices Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
Neuromodulation Devices Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
Centrifugation-Free Sperm Separation Systems Market
Medical Devices
United States Aesthetic Devices Market
Medical Devices
Neurovascular Stent Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
Bone Conduction Hearing Devices Market
Medical Devices
North America C-Arms Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market