
 Portable Ultrasound Bladder Scanner Market | 2026-2036
Portable Ultrasound Bladder Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Ultrasound Bladder Scanner Market Outlook
Home care and diagnostic centers are rebalancing the traditional hospital-centric demand profile for portable bladder scanners. GE Healthcare leverages its imaging platform breadth to sustain institutional channel dominance across acute care networks. Verathon Inc. anchors the North American point-of-care segment through specialized urological device expertise. Laborie Medical Technologies competes in pelvic floor and urodynamics adjacencies that extend bladder scanner utility into outpatient settings.
A portable ultrasound bladder scanner is a battery-powered diagnostic instrument that emits high-frequency sound waves to compute bladder volume without catheterization, typically operating at 2-5 MHz with measurement accuracy within 15 percent of true volume. The device serves primary clinical purposes of preventing unnecessary catheterization, monitoring post-void residual volumes, and guiding treatment decisions in urinary retention management. Handheld and wireless product configurations lead unit shipments due to nursing staff mobility requirements and reduced disinfection protocols between patients. 3D imaging technology captures premium positioning and margin pools by delivering superior anatomical visualization compared with conventional 2D B-mode systems. Cloud-based and mobile app integrated delivery modes represent the fastest-growing architecture as health systems prioritize electronic health record connectivity and remote monitoring capabilities.
FDA 510(k) premarket notification requirements and IEC 60601-1 third-edition electrical safety standards shape product development timelines and international market access for manufacturers. The EU Medical Device Regulation imposes additional clinical evidence burdens on bladder scanner OEMs seeking CE marking for European distribution. Stakeholders must monitor evolving cybersecurity guidance from FDA for networked diagnostic devices and prepare for post-market surveillance obligations that will intensify across multiple jurisdictions.
Market Dynamics
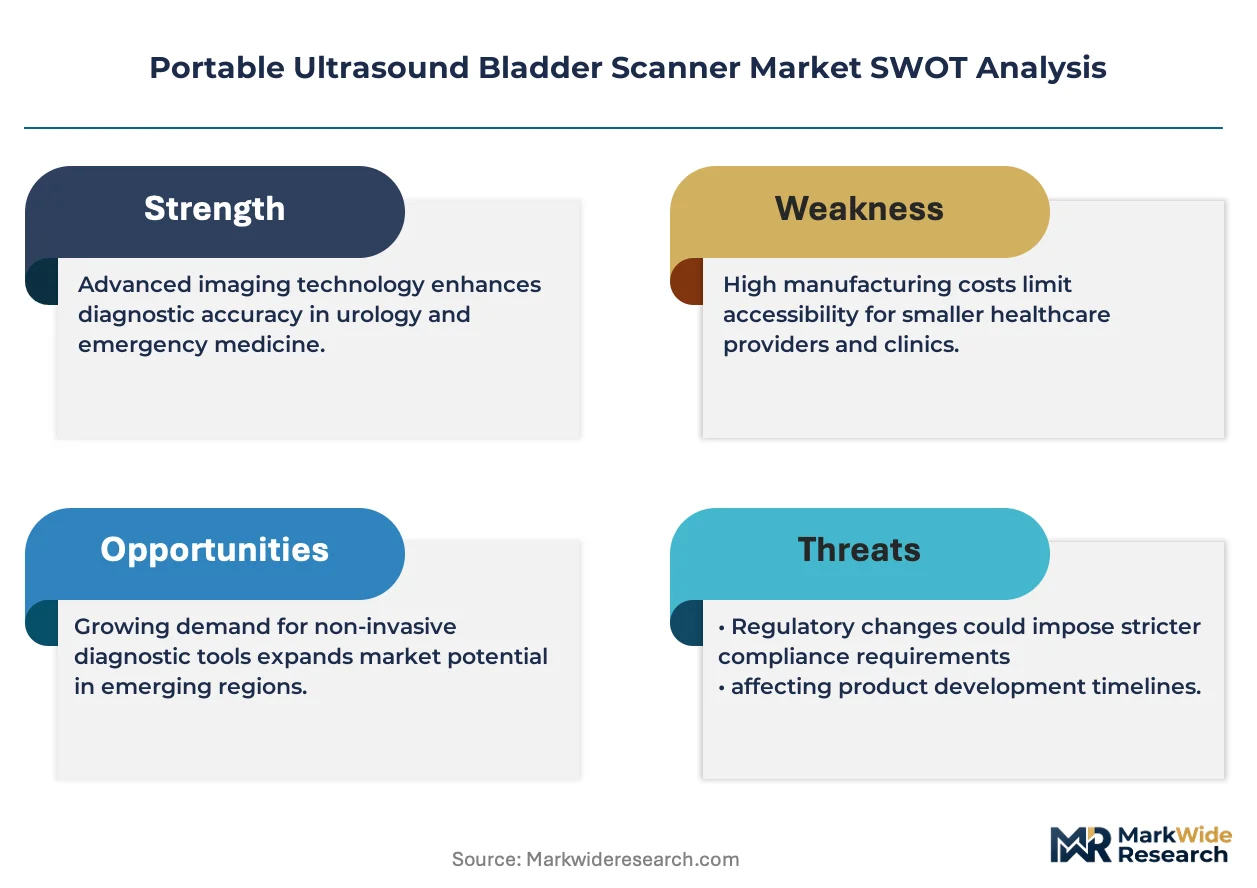
Point-of-care bladder volume assessment is displacing catheter-based protocols across acute and post-acute settings, with cloud-connected handheld devices capturing procurement preference from wired cart-based systems.
Growth Catalysts
- CAUTI Prevention Mandates:Hospital-acquired infection reduction programs in the United States and Germany mandate non-invasive bladder monitoring before catheter insertion, directly stimulating scanner deployment in emergency departments and rehabilitation units.
- 3D Imaging Algorithms:Automated bladder contour recognition reduces operator dependence and measurement variability, enabling wider nursing staff adoption without specialized sonography training.
- Home Care Expansion:Post-discharge monitoring protocols for benign prostatic hyperplasia and neurogenic bladder patients extend device utility beyond institutional walls into skilled nursing facilities and residential care.
Market Restraints
- Transducer Cost Concentration:Piezoelectric crystal supply chains cluster in Japanese and German component manufacturers, exposing OEMs to single-source vulnerability and input price volatility.
- Reimbursement Code Fragmentation:CPT coding gaps for bladder scanner use in outpatient settings create payment uncertainty that dampens capital equipment investment by independent diagnostic centers.
- Smartphone-Based Substitutes:Low-cost ultrasound peripherals paired with consumer tablets threaten standard scanner price points in budget-constrained long-term care facilities.
Strategic Opportunities
- Telehealth Integration:Remote bladder monitoring for spinal cord injury patients combines scanner hardware with synchronous video consultation platforms, opening recurring revenue streams beyond device sales.
- Pediatric Voiding Dysfunction:Underpenetrated pediatric urology practices in France and the United Kingdom lack child-appropriate probe designs, creating first-mover advantage for anatomically optimized form factors.
- EU MDR Clinical Evidence Pathways:Stricter post-market surveillance requirements favor established manufacturers with robust clinical data libraries, accelerating consolidation among smaller CE-marked competitors.
Industry Challenges
- Cybersecurity Validation Burden:FDA premarket guidance for networked diagnostic devices demands penetration testing and software bill of materials documentation that extends 510(k) clearance timelines.
- Legacy EHR Interoperability:HL7 FHIR implementation gaps between scanner middleware and hospital information systems force costly custom integration projects that erode margin on institutional contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Ultrasound Bladder Scanner Market |
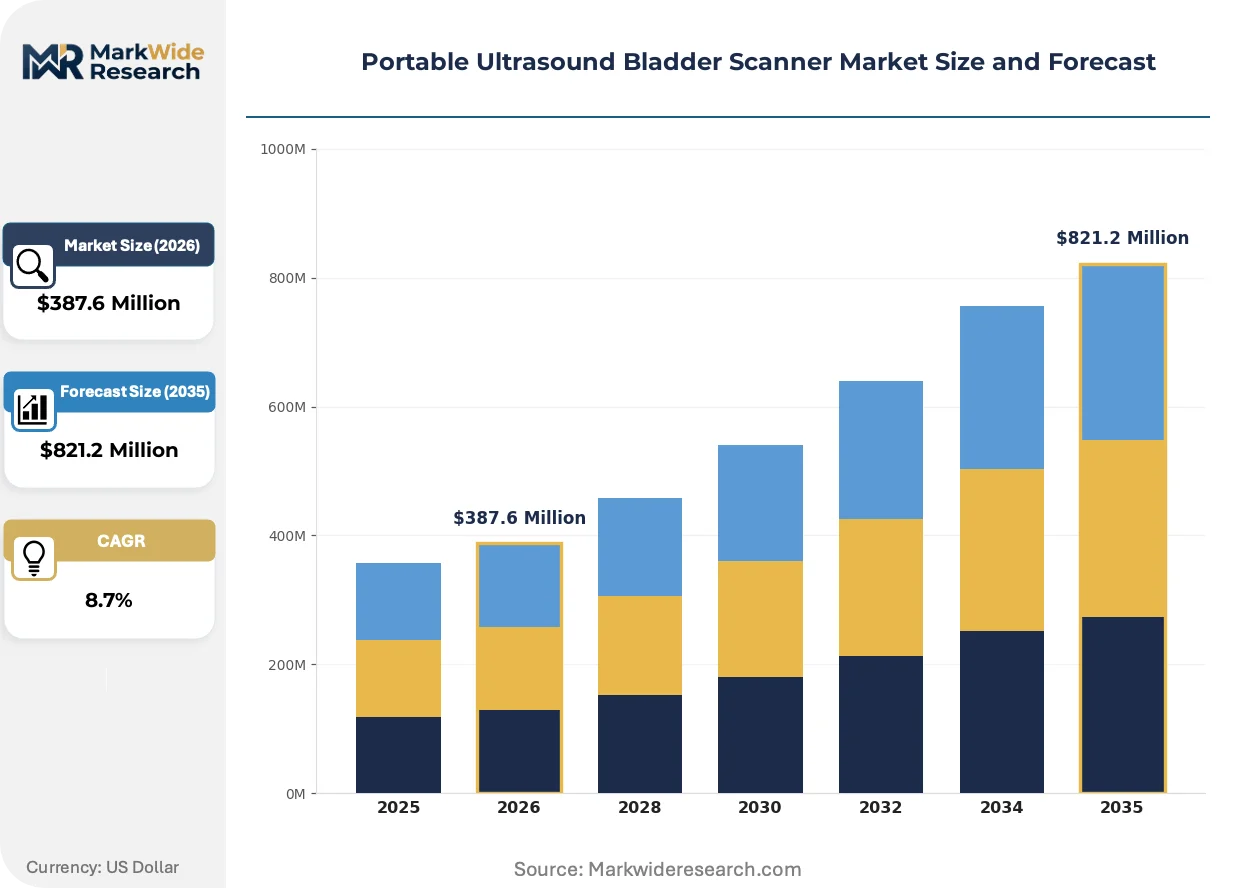
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Cart-based, Console, Wireless Technology: 2D Imaging, 3D Imaging, Doppler Ultrasound, B-Mode End User: Hospitals, Clinics, Home Care, Diagnostic Centers Delivery Mode: Mobile App Integration, Cloud-based, Standalone, Telemedicine |
| Companies Covered | GE Healthcare, Philips Healthcare, Siemens Healthineers, Verathon Inc., Laborie Medical Technologies, Becton, Dickinson and Company, SRS Medical Systems, Caresono Technology Co., Ltd., Infinium Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Ultrasound Bladder Scanner Market Strategic Shifts
Artificial intelligence inference at the edge is compressing measurement latency and enabling real-time quality feedback, while regulatory frameworks for software-as-medical-device classification reshape product architecture decisions.
Deep learning-based bladder segmentation is integrating into handheld scanner firmware to automate volume calculation without manual probe positioning. Community hospitals and skilled nursing facilities in the United States are adopting these systems to reduce training burden on rotating nursing staff. The technology is integrating point-of-care ultrasound into standard urinary retention order sets previously reserved for catheterization.
The EU Medical Device Regulation imposes clinical evidence requirements on bladder scanner software updates that trigger re-certification for algorithm modifications. Manufacturers must maintain post-market clinical follow-up studies that document real-world diagnostic accuracy across diverse patient populations. European distributors are consolidating around OEMs with established quality management systems and notified body relationships.
Subscription-based device-as-a-service models are replacing capital purchase arrangements in United States health systems seeking operational expenditure flexibility. Independent service organizations and manufacturer direct channels are disintermediating traditional durable medical equipment distributors. This shift is most visible in integrated delivery networks in Texas and Florida where procurement committees prioritize total cost of ownership metrics over upfront capital allocation.
Portable Ultrasound Bladder Scanner Market Segmentation
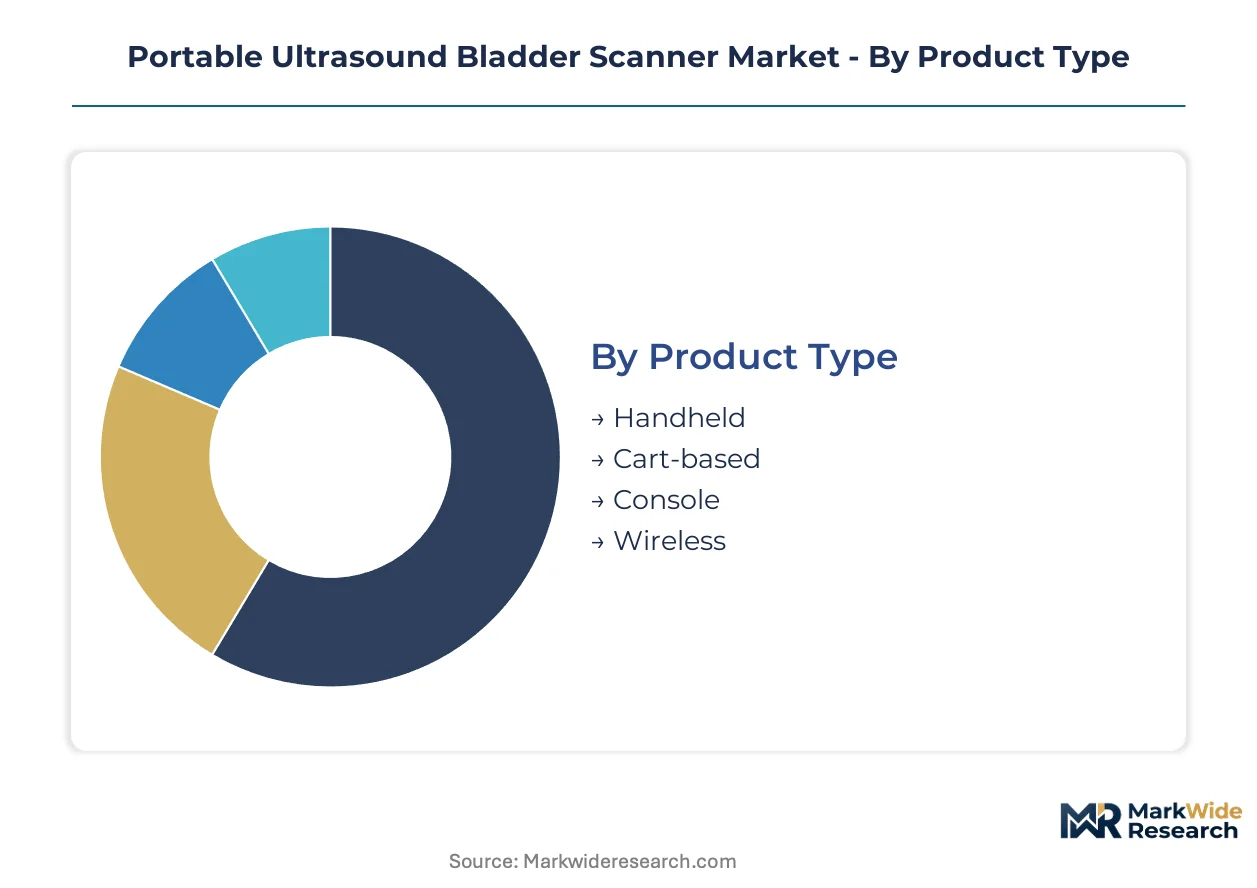
Portable bladder scanner procurement decisions pivot on clinical workflow integration, with nursing staff mobility requirements and electronic health record connectivity driving form factor selection. Device architecture choices directly impact capital expenditure profiles and operational training burdens across acute and post-acute care settings.
Product Type:
Form factor selection hinges on point-of-care mobility requirements versus measurement precision needs in institutional environments.
- Handheld:Battery-powered units weighing under 2 kg enable single-operator bladder assessment at bedside without patient transport. Emergency departments in the United States and rehabilitation units in Germany prioritize these devices for catheterization avoidance protocols. Demand concentrates where nursing staff rotation rates exceed sonography specialist availability.
- Cart-based:Wheeled configurations with larger transducer arrays deliver superior imaging depth for obese patient populations and complex anatomical presentations. Academic medical centers in Japan deploy these systems within urodynamics laboratories where measurement accuracy within 10 percent of true volume justifies higher capital outlay.
- Console:Fixed-station systems integrate with hospital information systems through DICOM middleware, serving centralized diagnostic departments with high patient throughput.
- Wireless:Bluetooth-enabled probes paired with tablet displays eliminate cable disinfection protocols between patients, gaining traction in infection control-conscious long-term care facilities.
Volume sits with handheld configurations; growth tilts toward wireless architectures.
Technology:
Imaging modality selection determines operator training requirements and diagnostic confidence in non-specialist clinical settings.
- 3D Imaging:Automated bladder contour reconstruction algorithms reduce measurement variability between operators without requiring manual plane alignment. Skilled nursing facilities in Florida and Texas adopt these systems to standardize post-void residual assessment across rotating nursing staff. The technology commands premium positioning where liability exposure from catheter-associated urinary tract infections drives procurement budgets.
- 2D Imaging:Conventional B-mode systems with manual probe positioning remain standard in budget-constrained community hospitals where capital replacement cycles extend beyond seven years. These devices require sonography training that limits deployment to specialized units.
- Doppler Ultrasound:Blood flow assessment capabilities extend utility into urological oncology screening applications, though bladder volume measurement represents secondary functionality.
- B-Mode:Fundamental grayscale imaging underlies all portable scanner architectures, with firmware variations distinguishing commercial offerings rather than hardware differentiation.
Installed base concentrates in 2D B-mode systems; capability expansion favors 3D imaging adoption curves.
End User:
Site-of-care economics reshape traditional hospital-centric demand patterns toward distributed diagnostic models.
- Hospitals:Acute care networks represent the dominant procurement channel, with emergency departments and post-anesthesia care units driving replacement demand. Infection prevention committees in the United States mandate bladder scanner availability before indwelling catheter insertion.
- Home Care:Post-discharge monitoring for neurogenic bladder and benign prostatic hyperplasia patients extends device utility beyond institutional walls. Reimbursement code development for remote patient monitoring services accelerates capital deployment in skilled nursing facilities.
- Clinics:Outpatient urology practices in Germany leverage portable scanners for same-day diagnostic workups, reducing referral delays to hospital-based imaging departments.
- Diagnostic Centers:Independent imaging facilities integrate bladder volume assessment into comprehensive pelvic ultrasound protocols, though CPT coding fragmentation creates payment uncertainty.
Procurement volume clusters in hospital networks; addressable market expansion tilts toward home care channels.
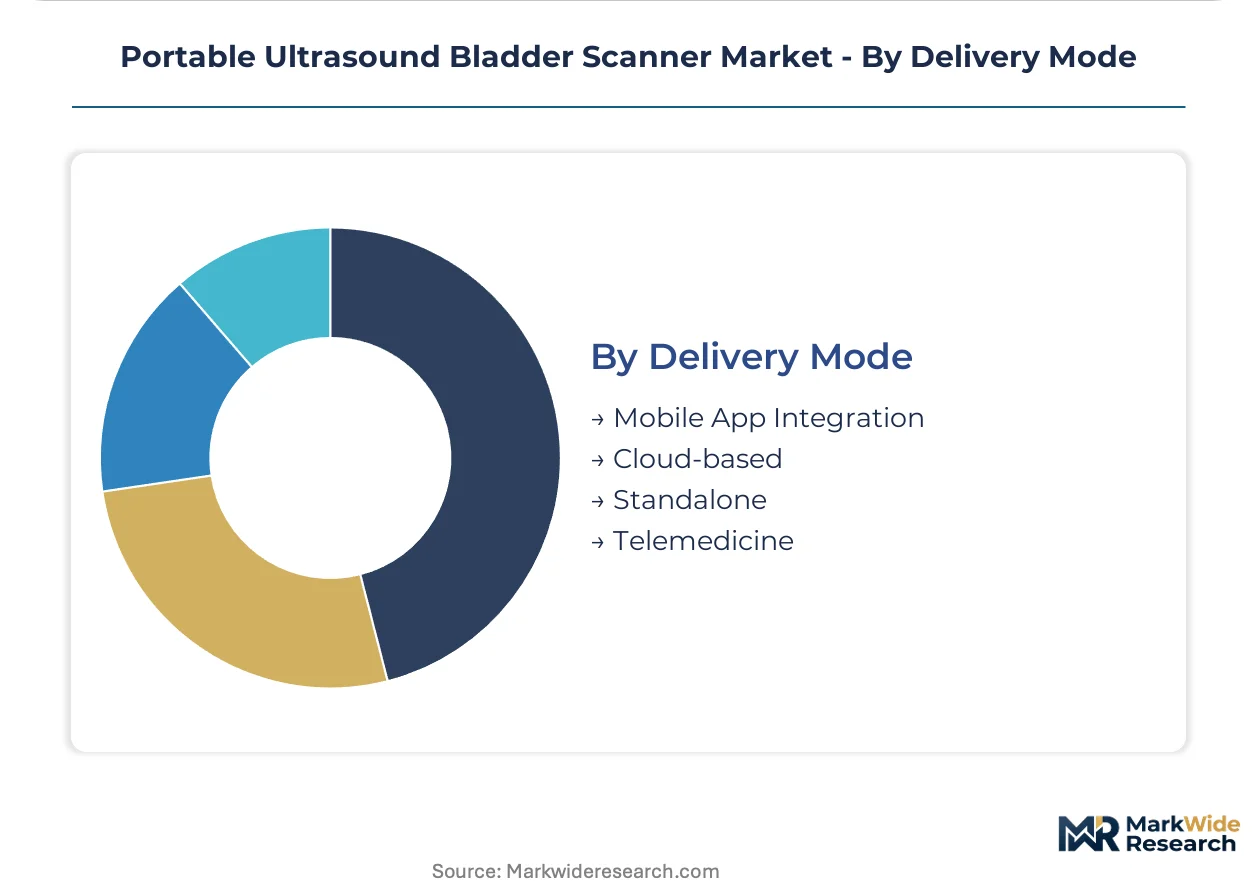
Delivery Mode:
Software architecture decisions increasingly determine competitive positioning as health systems prioritize interoperability investments.
- Cloud-based:Centralized data repositories enable multi-site volume trending and predictive analytics for urinary retention patterns. Integrated delivery networks in Texas prioritize these systems for population health management initiatives spanning acute and post-acute settings.
- Mobile App Integration:Native iOS and Android applications streamline nursing workflow through single-sign-on authentication and barcode patient identification. These architectures face heightened FDA cybersecurity scrutiny for networked diagnostic devices.
- Standalone:Offline operation without network connectivity serves facilities with limited IT infrastructure or heightened data sovereignty requirements in certain European jurisdictions.
- Telemedicine:Synchronous video consultation platforms combined with remote scanner operation enable specialist oversight of bladder assessment in rural and underserved regions.
Current deployment favors standalone configurations; connectivity investment priorities favor cloud-based architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Massachusetts and Minnesota concentrate bladder scanner R&D and manufacturing infrastructure, with tax incentives drawing OEMs to these established healthcare technology corridors.
United States
CAUTI prevention mandates from the Centers for Medicare & Medicaid Services drive hospital procurement of non-invasive bladder monitoring devices. FDA 510(k) premarket notification pathways govern device commercialization timelines for domestic manufacturers. The Minneapolis-St. Paul corridor hosts contract manufacturing operations serving major OEMs with transducer assembly capabilities.
Germany
Aging demographics and catheter-associated infection reduction programs in Bavarian and North Rhine-Westphalian hospital networks stimulate point-of-care diagnostic deployment. IEC 60601-1 third-edition electrical safety standards shape product development for EU market access. The MedTech cluster around Tübingen and Freiburg concentrates urological device engineering talent and regulatory consulting services.
Japan
Super-aging society protocols and long-term care insurance expansion extend bladder scanner utility into residential care settings. PMDA regulatory frameworks align with international harmonization initiatives for medical device approval. The Kansai region around Osaka maintains precision manufacturing capabilities for piezoelectric crystal components critical to transducer production.
United Kingdom
NHS infection prevention targets and catheter reduction initiatives in acute trusts drive emergency department procurement. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining UK-specific approval pathways. The Cambridge-Oxford-London golden triangle concentrates medical imaging AI development firms partnering with scanner OEMs.
China
Domestic medical device substitution policies and hospital procurement localization targets favor indigenous manufacturers. NMPA Class II medical device registration requirements govern commercialization for bladder volume assessment systems. The Yangtze River Delta around Shanghai hosts contract electronics manufacturers supplying transducer modules to regional OEMs.
Portable Ultrasound Bladder Scanner Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with imaging conglomerates dominating institutional channels while focused urological device firms capture point-of-care niches. The vendor base concentrates around three strategic archetypes: diversified medical imaging platforms, dedicated urological diagnostic specialists, and regional contract manufacturers serving private-label requirements. Competitive moves center on M&A for algorithm capabilities and strategic partnerships for EHR interoperability.
Among diversified imaging platforms, GE Healthcare and Philips Healthcare exemplify the scale-driven archetype with institutional channel breadth. Verathon Inc. represents the specialized urological device segment with point-of-care focus. Siemens Healthineers occupies a position bridging hospital imaging departments and outpatient diagnostic workflows.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Siemens Healthineers |
| Verathon Inc. |
| Laborie Medical Technologies |
| Becton, Dickinson and Company |
| SRS Medical Systems |
| Caresono Technology Co., Ltd. |
| Infinium Medical |
| Others |
Value Chain & Pricing Dynamics
Sonography-trained biomedical engineering talent concentrates in the Minneapolis-St. Paul corridor and the Kansai region around Osaka, with labor-cost differentials between these clusters driving tiered pricing spreads across handheld, cart-based, and wireless scanner configurations.
Pricing Analysis
Short lead-time premiums attach to 3D imaging systems with automated bladder contour recognition, while spot inventory discounts emerge for legacy 2D B-mode devices in extended replacement cycles. A three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared 510(k) devices with cloud connectivity from standalone units and private-label alternatives. Pricing pressure stems from smartphone-based ultrasound peripherals threatening standard scanner price points in long-term care facilities. Independent diagnostic centers exhibit highest price sensitivity due to CPT coding fragmentation, while integrated delivery networks in Texas and Florida prioritize total cost of ownership over upfront capital allocation.
Supply Chain Analysis
Dual-sourcing requirements for piezoelectric crystal transducers mandate multi-supplier qualification across Japanese and German component manufacturers, protecting OEMs from single-source vulnerability. Manufacturing concentration centers on the United States, Germany, and Japan for final device assembly, with the Yangtze River Delta supplying contract electronics for regional OEMs. Raw material dependencies span lithium-ion battery cells, medical-grade polymers, and precision-machined acoustic lenses. Tariff exposure on Chinese-sourced electronic modules presents structural risk to margin structures. Distribution runs through independent service organizations and manufacturer direct channels disintermediating traditional durable medical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transducer manufacturing capacity constraints in precision piezoelectric crystal production prop pricing power for incumbent OEMs with qualified supplier relationships.
For Market Incumbents: Deploy algorithm acquisition strategies to secure AI-enabled bladder segmentation capabilities before EU MDR clinical evidence requirements harden competitive moats. Backward integration into transducer component supply insulates margin structures from Japanese and German supplier concentration. Channel control through direct hospital system partnerships defends against independent service organization disintermediation. For New Entrants and Emerging Players: Direct-to-clinic digital sales platforms bypass traditional durable medical equipment distributor markups and accelerate pediatric urology penetration in France and the United Kingdom. White-space opportunity concentrates in child-appropriate probe designs for underpenetrated pediatric voiding dysfunction practices. Telehealth-integrated subscription models for spinal cord injury remote monitoring offer recurring revenue beyond device sales. For Investors and Strategic Acquirers: Re-rating potential sits with established CE-marked manufacturers given EU MDR post-market surveillance obligations accelerating consolidation among smaller competitors. Long-term viability favors firms with robust clinical data libraries spanning diverse patient populations. Watch FDA cybersecurity guidance enforcement for networked diagnostic devices as inflection indicator for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathways govern commercialization timelines for domestic and international manufacturers seeking US market access. |
| CE Marking Pathway | EU MDR clinical evidence requirements favor OEMs with established notified body relationships and quality management systems. |
| Hospital System Partnership | Integrated delivery networks in Texas and Florida prioritize total cost of ownership metrics in procurement committee decisions. |
| Software Companion Development | Cloud-based architectures with HL7 FHIR interoperability capture preference from health systems prioritizing EHR connectivity. |
| Reimbursement Strategy | CPT code development for remote patient monitoring services accelerates capital deployment in skilled nursing facilities. |
Study Parameters
Document review covered FDA 510(k) premarket notification databases, EU MDR technical documentation requirements, and hospital procurement records, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and urology department heads. Secondary sources included CMS Medicare reimbursement data, IEC 60601-1 electrical safety standards filings, and medical device trade flow statistics. Bottom-up unit shipment estimates triangulated against top-down market sizing derived from OEM revenue disclosures.
Segmentation outputs span product type, imaging technology, end-user site of care, and delivery mode architecture across the projection horizon. CAGRs were computed from annualized growth trajectories applied to base-year market value estimates. Industry-specific forecast inputs incorporated CAUTI prevention mandate adoption curves, long-term care insurance expansion rates, and cloud connectivity penetration assumptions.
The model holds under stable regulatory enforcement and supply chain continuity conditions; deviation in FDA cybersecurity guidance stringency or piezoelectric crystal supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Molecular Breast Imaging Market
Medical Imaging
Japan Mammography Market
Medical Imaging
Image-Guided Biopsy Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Treatment Planning Systems and Advanced Image Processing Market
Medical Imaging
Argentina Mammography Market
Medical Imaging
Digital Breast Tomosynthesis (DBT) Equipment Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
US Magnetic Resonance Imaging Market
Medical Imaging
Point-Of-Care Medical Imaging Market
Medical Imaging
Breast MRI Screening Market
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
Mexico Diagnostic Imaging Equipment Market
Medical Imaging
US Digital Radiology Market
Medical Imaging
Mexico Nuclear Imaging Market