
 Argentina Mammography Market | 2026-2036
Argentina Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Mammography Market Outlook
Public hospital procurement channels across Argentina's provincial health ministries is reshaping how equipment manufacturers reach end-users. Hologic Inc leverages its established service infrastructure to sustain long-term contracts with major public oncology centers. Siemens Healthineers AG anchors its position through localized technical support teams that reduce equipment downtime for diagnostic centers. Canon Inc differentiates by competing on total cost of ownership for budget-constrained outpatient clinics in secondary cities.
Mammography systems are specialized X-ray imaging devices designed to detect breast tissue anomalies at resolutions below 0.1 millimeter, utilizing low-dose ionizing radiation and compression paddles to optimize image contrast. These systems serve the primary commercial purpose of enabling early-stage breast cancer detection in clinical screening and diagnostic workflows. Digital Mammography dominates installed base volume across Argentine public and private facilities, while 3D Mammography represents the fastest-expanding technology segment as diagnostic centers upgrade to tomosynthesis capability for improved lesion characterization. Portable Mammography occupies a niche but strategically important position for mobile screening campaigns targeting rural provinces with limited fixed infrastructure.
ANMAT, Argentina's national medical device regulator, enforces registration and quality standards that all imported mammography equipment must satisfy before commercial distribution, directly influencing product approval timelines and market access conditions. The Superintendency of Health Services oversees reimbursement frameworks that determine how diagnostic centers recover capital investments in imaging technology through patient coverage schemes. Stakeholders must monitor evolving radiological safety protocols and provincial budget allocations to anticipate where equipment replacement cycles and new installation opportunities will materialize.
Market Dynamics
ANMAT's tightened quality certification requirements for imported imaging equipment is compressing approval timelines and forcing manufacturers to restructure their Argentina market entry strategies around localized compliance infrastructure.
Growth Catalysts
- Buenos Aires Province screening expansion:Public hospital networks are scaling breast cancer detection programs, creating sustained equipment procurement pipelines for diagnostic centers.
- 3D tomosynthesis adoption:Diagnostic centers are upgrading from digital mammography to three-dimensional imaging systems for improved lesion characterization accuracy.
- Mobile screening campaigns:Portable mammography systems are penetrating rural provinces with limited fixed infrastructure, extending service reach beyond metropolitan clusters.
Market Restraints
- Import certification friction:ANMAT's quality verification protocols extend equipment registration timelines, delaying revenue recognition for distributors.
- Metropolitan demand concentration:Diagnostic center density in Buenos Aires and Córdoba City leaves secondary cities underserved, constraining volume scalability.
- Radiologist workforce scarcity:Specialized breast imaging interpretation expertise concentrates in major oncology institutes, creating diagnostic bottlenecks.
Strategic Opportunities
- Secondary city outpatient clinics:Budget-constrained facilities in Rosario, Mendoza, and La Plata present untapped demand for total-cost-optimized digital systems.
- Superintendency of Health Services reimbursement evolution:Coverage framework adjustments could expand patient access and accelerate capital recovery cycles for equipment investors.
- AI-assisted image analysis integration:Machine learning algorithms paired with digital mammography systems promise workflow efficiency gains for understaffed provincial facilities.
Industry Challenges
- Service technician certification gaps:ANMAT-mandated technical qualifications for maintenance personnel limit field support scalability outside major urban centers.
- Legacy system interoperability:Provincial public hospitals operate heterogeneous imaging archives, complicating picture archiving and communication system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Mammography Market |
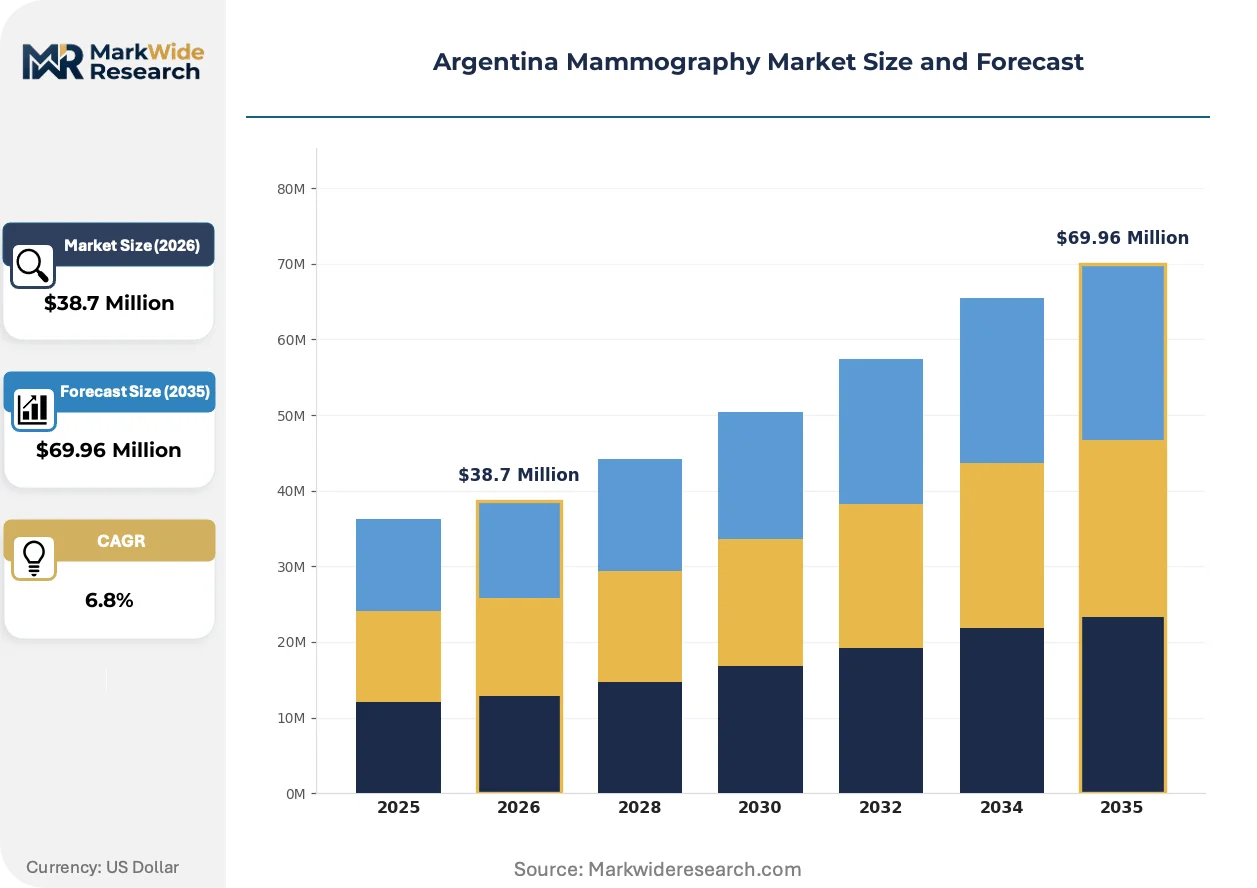
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $69.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Mammography, Digital Mammography, 3D Mammography, Portable Mammography Technology: X-Ray, Tomosynthesis, MRI, Ultrasound End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Research Facilities Installation: Fixed Installation, Mobile Units, Temporary Installations, Dedicated Suites |
| Companies Covered | Hologic Inc, GE HealthCare Technologies Inc, Siemens Healthineers AG, FUJIFILM Holdings Corp, Canon Inc, Koninklijke Philips NV, Planmed, Metaltronica, Toshiba Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Mammography Market Strategic Shifts
Digital breast tomosynthesis is compressing the technology replacement cycle across Argentine diagnostic centers, while regulatory compliance automation and procurement centralization reshape how equipment reaches end-users.
Three-dimensional mammography systems capture multiple low-dose projection images during a single compression cycle, reconstructing slice-separated breast volumes that reduce tissue overlap artifacts. Major oncology institutes in Buenos Aires are prioritizing tomosynthesis capability in replacement tenders, accelerating obsolescence of two-dimensional digital systems. This shift is rendering obsolete the installed base of conventional digital mammography across high-volume screening centers.
ANMAT's medical device registration framework now mandates localized quality management system audits for foreign manufacturers seeking commercial distribution authorization. The industrial consequence is a compliance cost barrier that favors established suppliers with dedicated Argentina regulatory affairs personnel. Diagnostic centers importing directly from non-established vendors face extended approval timelines, pushing procurement toward distributors with pre-certified product portfolios.
Provincial health ministries are consolidating equipment acquisition through centralized tender processes rather than facility-level purchasing. This concentration shifts bargaining power toward public procurement offices and compresses margins for vendors accustomed to decentralized sales relationships. The restructuring is most visible in Buenos Aires Province, where the ministry coordinates breast imaging fleet standardization across its hospital network.
Argentina Mammography Market Segmentation
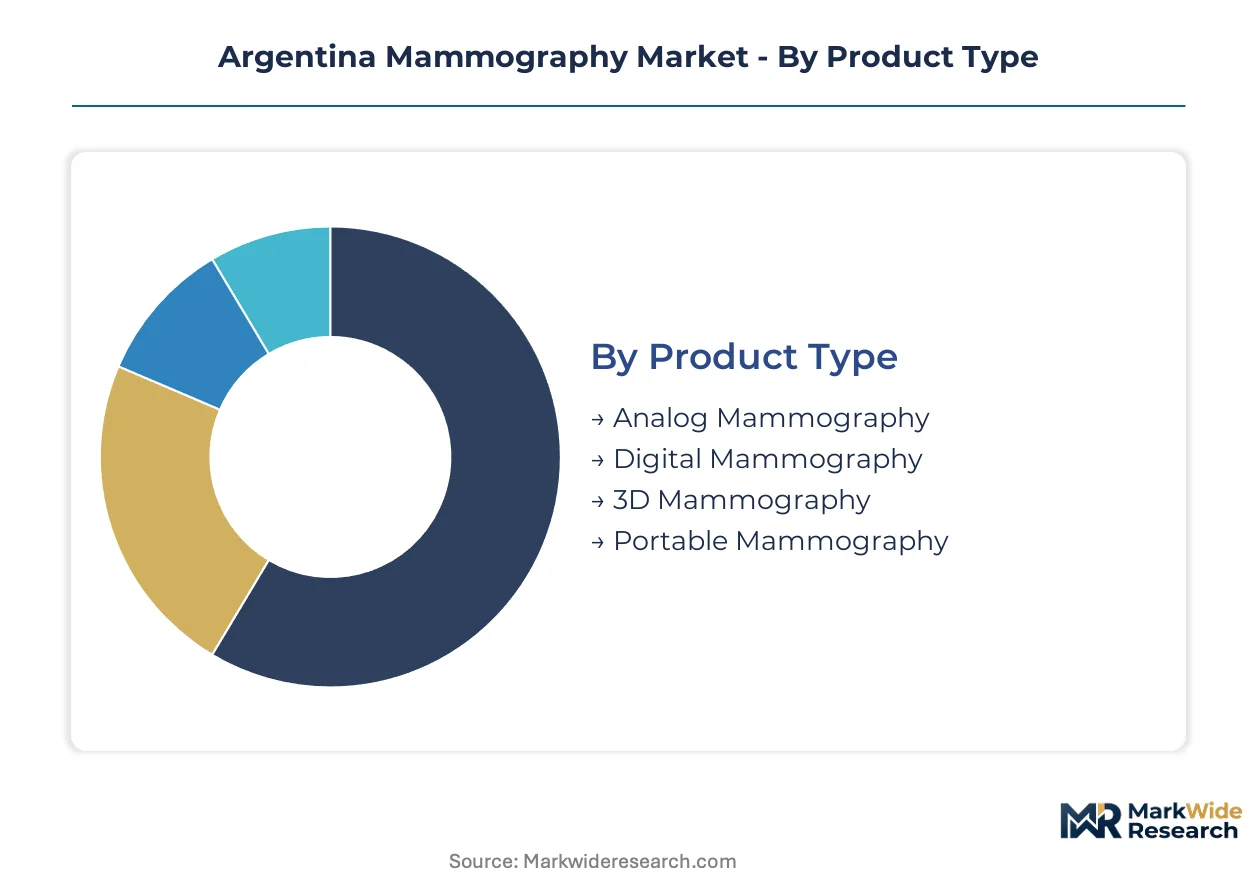
Equipment segmentation in Argentina's mammography market reveals distinct service infrastructure requirements and procurement channel patterns. Each category maps to specific regulatory pathways, reimbursement frameworks, and technical support demands that shape vendor positioning strategies.
Product Type:
After-sales service intensity varies sharply across product categories, with tomosynthesis systems demanding specialized field engineering capabilities that only established suppliers maintain in Buenos Aires and Córdoba City.
- Analog Mammography:Legacy film-based systems requiring chemical processing infrastructure and darkroom facilities. Demand persists in underfunded provincial hospitals awaiting capital replacement cycles, constrained by ANMAT's phased equipment retirement guidelines.
- Digital Mammography:Computed radiography and direct digital capture systems dominate installed base volume across Argentine public and private facilities. Buenos Aires Province screening programs prioritize these systems for their workflow integration and lower per-exam operational costs.
- 3D Mammography:Tomosynthesis-capable platforms generating multi-planar reconstructions. Major oncology institutes in metropolitan centers are accelerating replacement tenders toward this capability.
- Portable Mammography:Compact battery-powered units designed for mobile screening deployment. Rural province health ministries in Mendoza and Tucumán are procuring these for community outreach campaigns.
Digital Mammography holds the largest share; momentum sits with 3D Mammography.
Technology:
Cost tier differentiation separates premium tomosynthesis platforms from budget digital X-ray configurations, with reimbursement rates determining which technology provincial facilities can justify.
- X-Ray:Conventional projection radiography using low-dose ionizing radiation and compression paddles. Public hospital networks across Buenos Aires Province standardize procurement around digital X-ray mammography for screening program cost containment.
- Tomosynthesis:Three-dimensional image reconstruction from multiple low-angle projections. Private diagnostic centers in Córdoba City are adopting this technology to differentiate their breast imaging services.
- MRI:Magnetic resonance imaging for high-risk patient screening and implant evaluation. Demand concentrates in specialized breast imaging centers with dedicated MRI suites.
- Ultrasound:Supplementary imaging for dense breast tissue and biopsy guidance. Outpatient clinics deploy handheld units as adjunct diagnostic tools.
X-Ray technology maintains dominant installed base; Tomosynthesis is expanding most quickly among upgrade cycles.
End User:
Customer type determines procurement authority structure, with provincial health ministries centralizing hospital acquisitions while diagnostic centers retain decentralized purchasing autonomy.
- Hospitals:Acute care institutions with integrated oncology departments. ANMAT registration requirements and centralized tender processes govern equipment acquisition across public hospital networks.
- Diagnostic Centers:Specialized imaging facilities serving referred patients. These entities in Buenos Aires and Córdoba City drive technology upgrade demand for competitive differentiation.
- Outpatient Clinics:Community-based primary care facilities with limited capital budgets. Secondary cities present untapped demand for cost-optimized digital systems.
- Research Facilities:Academic medical centers conducting clinical trials and imaging protocol development. Limited volume but influence technology adoption patterns.
Hospitals command the largest equipment volume; Diagnostic Centers are gaining share fastest through private investment.
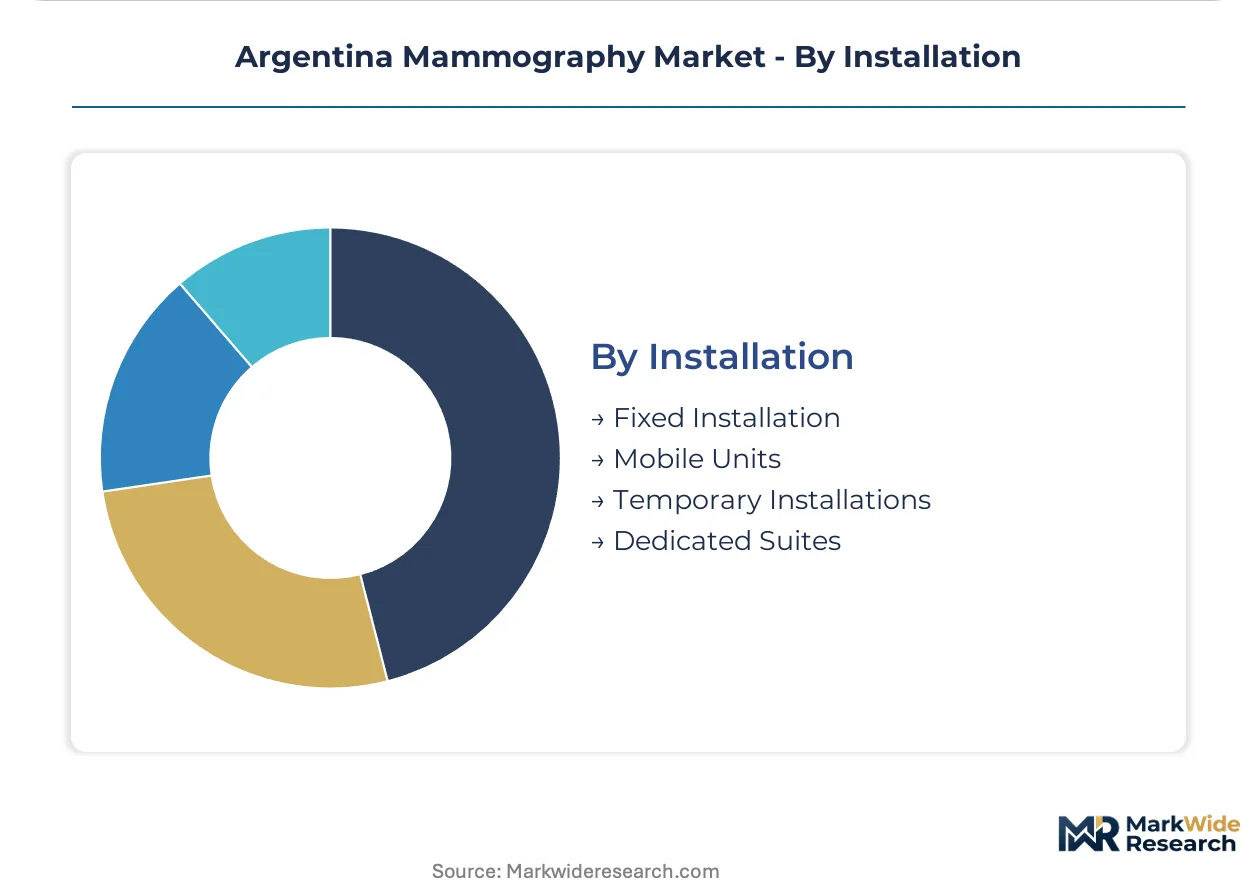
Installation:
Supply concentration in fixed installation infrastructure leaves mobile unit deployment dependent on specialized logistics providers with provincial service coverage.
- Fixed Installation:Permanent room-based systems with dedicated electrical and climate control infrastructure. High-volume screening centers in metropolitan Buenos Aires require this configuration for throughput optimization.
- Mobile Units:Vehicle-mounted or transportable systems for temporary deployment. Provincial health ministries are expanding mobile screening fleets to reach underserved rural populations.
- Temporary Installations:Short-term leased or rented equipment for campaign-based screening. Budget-constrained facilities in La Plata and Rosario utilize this model for peak demand periods.
- Dedicated Suites:Custom-designed imaging environments with integrated workflow systems. Premium private oncology institutes invest in these configurations for patient experience differentiation.
Fixed Installation retains dominant position; Mobile Units are climbing the fastest on rural access priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Retiro-Mendoza railway corridor underwrites Argentina's internal medical equipment distribution network, connecting Buenos Aires manufacturing and import hubs to provincial diagnostic centers across the country's western spine.
Buenos Aires Province
Public hospital networks are scaling breast cancer screening programs across La Plata, Mar del Plata, and Bahía Blanca. ANMAT's quality certification requirements govern equipment procurement through centralized provincial tenders. The Greater Buenos Aires corridor concentrates diagnostic center density and drives technology upgrade demand for 3D tomosynthesis systems.
Córdoba Province
Private diagnostic investment is expanding in Córdoba City and surrounding municipalities. The provincial health ministry coordinates reimbursement frameworks with the Superintendency of Health Services. High-volume oncology institutes in the capital district are prioritizing digital breast tomosynthesis capability in replacement cycles.
Santa Fe Province
Rosario's outpatient clinic network presents untapped demand for cost-optimized digital mammography systems. Provincial budget allocations for breast imaging equipment lag behind Buenos Aires and Córdoba. The Paraná River logistics corridor facilitates equipment import through the Port of Rosario.
Mendoza Province
Mobile screening campaigns are penetrating rural Andean departments with limited fixed infrastructure. The provincial health ministry procures portable mammography units for community outreach in San Rafael and Malargüe. Mountain geography constrains permanent installation feasibility outside the capital district.
Tucumán Province
Secondary city diagnostic centers in San Miguel de Tucumán operate budget-constrained digital systems awaiting capital replacement cycles. Federal health program transfers support equipment acquisition in smaller provincial facilities. The Northwest regional hub serves surrounding Salta and Catamarca provinces.
Argentina Mammography Market Competitive Environment
On the supply side, the industry is consolidating around established imaging equipment multinationals with dedicated Argentina regulatory affairs infrastructure. Three strategic archetypes dominate: premium-tier tomosynthesis specialists, total-cost-optimized digital system providers, and portable unit fabricators for mobile screening deployment. Competitive positioning hinges on ANMAT pre-certification status and localized technical service coverage rather than price alone.
Among North American-dominant imaging conglomerates, Hologic Inc and GE HealthCare Technologies Inc exemplify the premium-tier archetype with established Buenos Aires service infrastructure. Siemens Healthineers AG anchors the European multinational position through localized technical support teams. Canon Inc occupies the cost-optimization vector for budget-constrained provincial facilities. These three entities represent distinct competitive positioning strategies: long-term public oncology contracts, field engineering density, and total cost of ownership reduction respectively.
| Leading Market Players |
|---|
| Hologic Inc |
| GE HealthCare Technologies Inc |
| Siemens Healthineers AG |
| FUJIFILM Holdings Corp |
| Canon Inc |
| Koninklijke Philips NV |
| Planmed |
| Metaltronica |
| Toshiba Corporation |
| Others |
Value Chain & Pricing Dynamics
The Retiro-Mendoza railway corridor carries imported imaging equipment from Buenos Aires port facilities to provincial diagnostic centers, with freight cost differentials between metropolitan and Andean destinations reinforcing price stratification across installation types. ANMAT's quality certification requirements add compliance layers that concentrate supply among pre-certified distributors, compressing margins for non-established vendors while enabling premium pricing for service-integrated offerings.
Pricing Analysis
Volume-discount tiering structures separate procurement through Buenos Aires Province's centralized tenders from facility-level purchases in secondary cities. Pricing stratifies across premium tomosynthesis platforms, standard digital mammography configurations, and economy analog systems awaiting replacement. Price differentiation rests on ANMAT pre-certification status and localized technical support coverage. Cost compression in the economy tier is intensifying because provincial budget constraints extend replacement cycles. Outpatient clinics in Rosario and Mendoza exhibit highest price sensitivity; major oncology institutes in Buenos Aires demonstrate lowest sensitivity due to reimbursement recovery mechanisms.
Supply Chain Analysis
Tariff exposure between the United States and Argentina dominates supply chain risk planning for North American imaging equipment manufacturers. Manufacturing concentration centers on the United States, Germany, and Japan for core system assembly, with Argentina drawing from these hubs for complete unit import. Critical component dependencies include flat-panel detectors from South Korea, X-ray tubes from Germany, and image reconstruction software from the United States. Distribution runs through ANMAT-authorized distributors with established regulatory affairs infrastructure rather than direct manufacturer-to-hospital relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
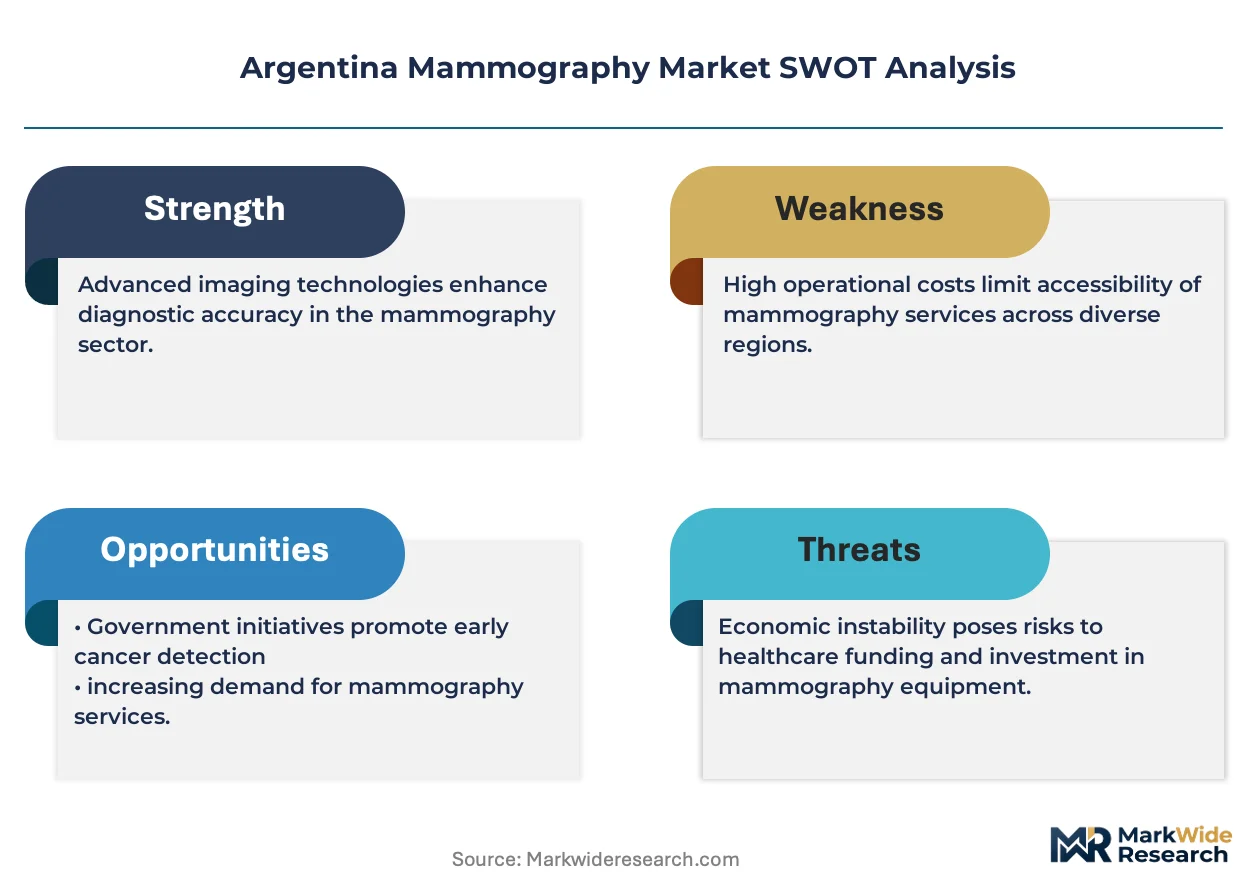
Argentina's mammography market demands substitution defense against ultrasound-based breast screening alternatives that provincial health ministries may adopt for cost containment. Incumbents must demonstrate superior lesion detection accuracy to justify capital investment against these lower-cost modalities.
For Market Incumbents: Harden service infrastructure density in Córdoba City and Mendoza to defend against portable ultrasound system encroachment. Secure long-term maintenance contracts with Buenos Aires Province's centralized procurement office. Prioritize AI-assisted image analysis integration as a defensive capability against substitute screening technologies.
For New Entrants and Emerging Players: Secondary city outpatient clinics in La Plata and San Miguel de Tucumán represent the most penetrable entry point for cost-optimized digital mammography systems. Mobile screening fleet operators in Tucumán Province present partnership opportunities for portable unit deployment. Position through ANMAT regulatory consulting bundled with equipment supply to compress market entry timelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational imaging conglomerates seeking to divest non-core Latin American service operations. Long-term viability hinges on provincial health ministry budget sustainability and reimbursement framework evolution. Monitor Superintendency of Health Services coverage adjustments as the critical signal for capital recovery cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ANMAT Pre-Certification Investment | Compressed approval timelines unlock Buenos Aires Province tender participation before competitors complete registration. |
| Localized Technical Support Expansion | Field engineering density in Córdoba City reduces equipment downtime and secures replacement cycle preference. |
| AI-Assisted Image Analysis Integration | Machine learning workflow tools address radiologist scarcity in provincial facilities and differentiate premium offerings. |
| Mobile Screening Fleet Partnerships | Provincial health ministry outreach campaigns in Mendoza and Tucumán create recurring portable unit demand. |
| Centralized Procurement Office Engagement | Buenos Aires Province's consolidated tender process requires direct ministry relationship investment for volume access. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of ANMAT registration databases, provincial health ministry procurement records, and Superintendency of Health Services reimbursement filings. Primary interviews engaged biomedical engineers at major oncology institutes, hospital purchasing committee members, GPO contracts managers, and aftermarket service heads at established distributors. Secondary validation incorporated customs import data, hospital equipment procurement databases, and regulatory submission tracking. Bottom-up installation base modeling triangulated against top-down market value reconstruction.
Forecast inputs span technology replacement cycle timing, provincial budget allocation trajectories, and reimbursement framework evolution across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user category, and installation configuration. CAGRs derived from equipment unit shipment projections valued at average selling prices by tier. Radiology workforce growth rates and screening program expansion targets informed demand-side assumptions.
Macroeconomic conditions sit as an overlay; deviation in peso exchange rate volatility and provincial fiscal capacity would shift the trajectory. Forecasts reflect documented assumptions regarding ANMAT regulatory stability and continued federal health program transfer levels. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Urology Imaging Systems Market
Medical Imaging
Teleradiology Services Market
Medical Imaging
Asia-Pacific Nuclear Medicine Market
Medical Imaging
Nuclear Imaging Devices Market
Medical Imaging
CT Guided Intervention Market
Medical Imaging
France Digital Radiology Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
Americas Interventional Radiology Market
Medical Imaging
Europe Portable X-Ray Devices Market
Medical Imaging
Global Computer Vision in Healthcare Market
Medical Imaging
South America MRI Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
Treatment Planning Systems and Advanced Image Processing Market
Medical Imaging
Medical Imaging Market
Medical Imaging
Open Magnetic Resonance Imaging System Market