
 Mexico Diagnostic Imaging Equipment Market | 2026-2036
Mexico Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Diagnostic Imaging Equipment Market Foresight
Software-defined imaging subscriptions is repositioning capital equipment into recurring revenue relationships across Mexican healthcare facilities. GE Healthcare leverages its installed base of CT and MRI platforms to sustain long-term service contracts. Siemens Healthineers anchors its position through R&D intensity in hybrid imaging architectures. Koninklijke Philips N.V. differentiates via channel control across private hospital networks in Monterrey and Mexico City.
Diagnostic imaging equipment encompasses electromagnetic and acoustic systems engineered to visualize internal anatomical structures for clinical diagnosis, with magnetic field strengths in MRI typically ranging from 1.5 to 3.0 Tesla and CT systems employing X-ray tube voltages between 80 and 140 kVp. These technologies enable non-invasive detection of tumors, vascular abnormalities, and musculoskeletal pathologies across outpatient and inpatient settings. CT scanners occupy the largest revenue pool among product types due to emergency department throughput requirements, while 3D imaging technology captures the fastest expansion as surgical planning and interventional radiology advance. Digital imaging dominates installed capacity though hybrid imaging systems command premium pricing from integrated PET-CT and PET-MRI configurations.
COFEPRIS governs medical device registration and post-market surveillance, with NOM standards mandating electrical safety and electromagnetic compatibility for all imported imaging systems. The Secretaría de Salud coordinates public sector procurement through centralized tender processes that shape volume allocation across state health systems. BIS-equivalent metrology standards ensure calibration traceability for diagnostic accuracy. Stakeholders must monitor evolving reimbursement pathways under INSABI and IMSS frameworks as these determine hospital capital allocation priorities.
Market Dynamics
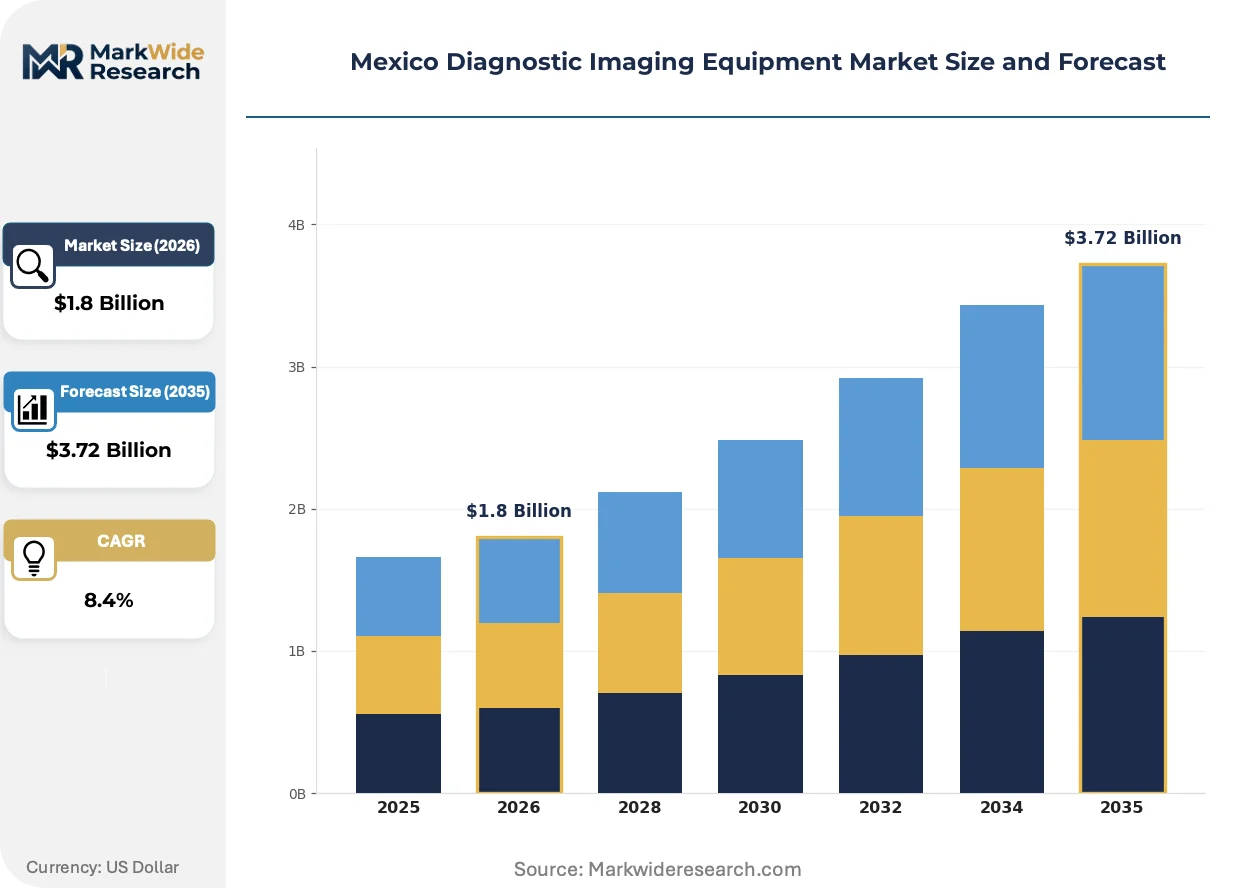
Software-defined imaging subscriptions are converting capital-intensive equipment purchases into recurring revenue streams across Mexican healthcare facilities, restructuring vendor-customer relationships and procurement cycles throughout the sector.
Growth Catalysts
- COFEPRIS regulatory streamlining:Accelerated medical device registration timelines reduce equipment approval delays, enabling faster deployment of MRI and CT systems into hospital networks.
- Oncology application concentration:Rising cancer incidence across central Mexican states drives demand for advanced imaging modalities capable of early tumor detection and treatment monitoring.
- Public hospital network expansion:Mexico City and Guadalajara procurement programs prioritize diagnostic imaging infrastructure upgrades, channeling government investment into radiology departments.
Market Restraints
- Import dependency for high-field MRI magnets:Concentrated global supply of superconducting magnet components creates vulnerability to international shipping disruptions and currency fluctuations.
- Specialized radiologist workforce constraints:Limited training pipeline for interventional radiologists and MRI specialists restricts operational capacity expansion regardless of equipment availability.
- Reimbursement pathway fragmentation:Divergent coverage frameworks between IMSS, INSABI, and private insurers complicate hospital ROI calculations for premium imaging investments.
Strategic Opportunities
- Hybrid imaging architecture penetration:PET-CT and PET-MRI integration addresses unmet demand for simultaneous functional and anatomical assessment in cardiac and oncological diagnostics.
- 3D imaging surgical planning:Orthopedic and neurosurgical programs in Monterrey private hospitals are adopting volumetric reconstruction for preoperative modeling, opening premium service tiers.
- Service contract unbundling:Independent service organizations can capture maintenance revenue from aging installed bases as manufacturers face pressure to decouple hardware from service pricing.
Industry Challenges
- Biomedical engineer certification bottlenecks:COFEPRIS technical personnel requirements for imaging system validation create workforce recruitment delays that extend deployment timelines.
- Legacy PACS integration complexity:Hospital information system heterogeneity forces costly middleware development for seamless image archiving and retrieval across multi-vendor environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Diagnostic Imaging Equipment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MRI Machines, CT Scanners, Ultrasound Devices, X-ray Systems End User: Hospitals, Imaging Centers, Research Laboratories, Clinics Technology: Digital Imaging, Analog Imaging, Hybrid Imaging, 3D Imaging Application: Cardiology, Oncology, Neurology, Orthopedics |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems, Fujifilm Holdings Corp., Carestream Health, Hologic, Inc., Shimadzu, Mindray Medical International Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Diagnostic Imaging Equipment Market Shifts & Advancements
Artificial intelligence deployment in image reconstruction and diagnostic assistance is compressing scan times and reducing contrast agent requirements, fundamentally altering throughput economics for Mexican radiology departments.
Photon-counting CT detector technology is unifying spectral imaging capabilities with conventional anatomical scanning, eliminating the need for separate dual-energy protocols. Tertiary care centers in Mexico City are piloting these systems for cardiovascular and pulmonary applications. This convergence is compressing capital allocation decisions by collapsing multiple equipment categories into single-platform investments.
COFEPRIS post-market surveillance mandates are tightening adverse event reporting requirements for Class III medical devices, compelling manufacturers to strengthen local quality management systems. Imaging equipment distributors must now maintain dedicated regulatory affairs personnel in-country. The private hospital segment is responding by demanding enhanced traceability documentation and extended warranty terms as risk mitigation.
Subscription-based equipment access models are displacing traditional capital purchase arrangements among mid-tier private clinics. Radiology-as-a-service providers in Guadalajara and Puebla are offering per-scan pricing that bundles maintenance, software updates, and technologist training. This shift is most visible in outpatient imaging centers seeking to minimize balance sheet exposure while maintaining competitive modality availability.
Mexico Diagnostic Imaging Equipment Market Segmentation
Equipment replacement cycles and technology refresh timelines vary sharply across Mexican healthcare infrastructure. Public hospital networks prioritize CT scanner upgrades for emergency throughput, while private imaging centers favor MRI and hybrid systems for premium service differentiation. Understanding these segment-specific procurement patterns reveals where capital allocation concentrates and where vendor relationships reshape.
Product Type:
Replacement urgency differs by modality age and maintenance burden across Mexican hospital networks.
- CT Scanners:X-ray tube systems operating at 80-140 kVp generate cross-sectional anatomical images with sub-millimeter resolution. Mexico City public hospitals and Guadalajara trauma centers drive procurement volume as emergency department throughput requirements mandate rapid scan completion. Aging installed bases from 2012-2015 purchases are reaching end-of-life, forcing replacement decisions.
- MRI Machines:Superconducting systems utilizing 1.5 to 3.0 Tesla magnetic fields excel in soft tissue contrast without ionizing radiation. Monterrey private hospital networks and oncology centers in central Mexican states concentrate demand for high-field systems capable of functional neuroimaging and cardiac perfusion studies.
- Ultrasound Devices:Portable and cart-based acoustic imaging systems serve point-of-care diagnostics across rural clinics and urban outpatient facilities.
- X-ray Systems:Conventional radiography and fluoroscopy equipment retains installed base dominance in primary care clinics and smaller municipal hospitals.
CT scanners sit at the top of the volume ranking, with MRI machines climbing the fastest as oncology and cardiac applications expand.
End User:
Capital availability and reimbursement rates create tiered procurement behavior across facility types.
- Hospitals:Acute care institutions with 24-hour emergency services and surgical programs require multi-modality imaging suites. IMSS and INSABI procurement frameworks channel government investment toward radiology infrastructure in Mexico City, Guadalajara, and Monterrey hospital networks, with centralized tender processes shaping vendor selection.
- Imaging Centers:Dedicated outpatient facilities compete on scan accessibility and report turnaround time. Subscription-based equipment access models are gaining traction among mid-tier operators in Puebla and Querétaro seeking to minimize capital exposure while maintaining competitive modality portfolios.
- Research Laboratories:Academic medical centers and clinical trial sites in Mexico City deploy specialized imaging for protocol-driven studies.
- Clinics:Primary care and specialty outpatient practices rely on ultrasound and basic X-ray for initial diagnostic screening.
Hospitals command the largest capital deployment share, though imaging centers are expanding capacity most aggressively through alternative financing structures.
Technology:
Digital transition maturity and integration complexity determine upgrade sequencing for Mexican facilities.
- Digital Imaging:Computed radiography and direct digital radiography systems dominate installed capacity across Mexican healthcare facilities. COFEPRIS electrical safety and electromagnetic compatibility standards under NOM frameworks mandate compliance for all imported digital systems, creating regulatory friction for legacy analog replacements.
- Hybrid Imaging:PET-CT and PET-MRI configurations integrate functional and anatomical assessment in single sessions. Tertiary care centers in Mexico City pilot these systems for cardiovascular and oncological diagnostics, commanding premium pricing from integrated clinical workflows.
- Analog Imaging:Film-based radiography persists in under-resourced municipal hospitals and rural health posts.
- 3D Imaging:Volumetric reconstruction capabilities enable surgical planning and interventional guidance.
Digital imaging holds dominant installed base position, while hybrid imaging gains share fastest through premium service tier penetration.
Application:
Disease burden distribution and specialist availability shape modality demand across clinical domains.
- Oncology:Tumor detection, staging, and treatment monitoring applications require multi-parametric MRI and contrast-enhanced CT protocols. Rising cancer incidence across central Mexican states concentrates demand in Guadalajara and Mexico City oncology centers, with COFEPRIS streamlining registration timelines for advanced imaging systems targeting this therapeutic area.
- Cardiology:Cardiac MRI, CT angiography, and stress imaging address coronary artery disease and structural heart evaluation. Monterrey private hospital networks invest in dedicated cardiac imaging suites to capture elective procedure volume from cross-border patients and domestic medical tourism.
- Neurology:Stroke imaging and neurodegenerative disease assessment drives CT and MRI utilization in emergency and outpatient settings.
- Orthopedics:Musculoskeletal trauma and joint replacement planning generates consistent radiography and MRI demand.
Oncology sits at the top of the volume ranking, with cardiology climbing the fastest as specialized cardiac centers expand in northern Mexico.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico trails the United States in installed imaging density per capita, yet outpaces Brazil in hybrid imaging adoption rates across its tertiary hospital networks. Central Mexican states concentrate procurement volume while northern border regions attract cross-border medical tourism demand.
Mexico City Metro
IMSS and ISSSTE hospital networks drive CT and MRI procurement through centralized tenders, with oncology and emergency applications dominating capital allocation. COFEPRIS regulatory streamlining accelerates equipment registration timelines for Class III devices. Tertiary care centers in the capital pilot photon-counting CT and PET-MRI hybrid systems for cardiovascular diagnostics.
Nuevo León
Monterrey private hospital networks invest in cardiac imaging suites to capture elective procedure volume from domestic and cross-border patients. State health authorities coordinate with federal INSABI frameworks to expand public radiology infrastructure. The Monterrey medical corridor concentrates premium MRI installations serving medical tourism from Texas and California.
Jalisco
Guadalajara trauma centers and public hospital networks prioritize CT scanner replacements for emergency department throughput. State procurement programs channel federal health investment into radiology departments serving central-western Mexico. The Guadalajara metropolitan area anchors hybrid imaging adoption for oncological staging protocols.
Bajío Region
Querétaro and Puebla imaging centers adopt subscription-based equipment access models to minimize capital exposure. Mid-tier private clinics deploy per-scan pricing arrangements bundling maintenance and technologist training. The region's outpatient imaging market expands fastest through alternative financing structures.
Northern Border States
Tijuana and Ciudad Juárez facilities serve cross-border patients seeking faster scan access and lower out-of-pocket costs. Baja California and Chihuahua health systems balance federal IMSS procurement with private investment in premium modalities. Border corridor imaging centers compete on report turnaround time and English-language service delivery.
Mexico Diagnostic Imaging Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational OEMs commanding premium-tier installations while regional distributors capture mid-market service relationships. The vendor base concentrates around imaging system integrators with established COFEPRIS registration capabilities and nationwide service networks. Three archetypes dominate: full-platform OEMs with direct hospital relationships, specialized modality distributors focusing on ultrasound and X-ray, and independent service organizations unbundling maintenance from hardware sales. Competitive moves center on strategic partnerships with local biomedical engineering firms and portfolio diversification into AI-assisted diagnostic software.
Among the full-platform OEM tier, GE Healthcare, Siemens Healthineers, and Koninklijke Philips N.V. occupy positions defined by installed base scale and long-term service contract penetration across Mexican hospital networks. These entities exemplify the capital-to-recurring-revenue transition reshaping vendor-customer relationships, with each anchoring distinct geographic strongholds—GE Healthcare leveraging CT and MRI platforms in Mexico City public networks, Siemens Healthineers driving hybrid imaging architecture adoption, and Koninklijke Philips N.V. maintaining channel control across Monterrey and Mexico City private institutions.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems |
| Fujifilm Holdings Corp. |
| Carestream Health |
| Hologic, Inc. |
| Shimadzu |
| Mindray Medical International Limited |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up imaging service organizations are consolidating maintenance contracts across Mexican hospital networks, tightening pricing discipline while reshaping vendor procurement toward bundled subscription models that compress capital outlays into recurring operational expenses.
Pricing Analysis
Capacity additions in Guadalajara and Puebla are reshaping price floors for mid-tier CT and MRI installations as subscription-based radiology-as-a-service providers proliferate. Three-tier pricing structure across premium, standard, and economy levels separates photon-counting CT configurations from refurbished 1.5T MRI systems and basic digital radiography platforms. Price differentiation hinges on COFEPRIS registration tier and after-sales service bundling. Cost compression in the economy tier is intensifying because independent service organizations are unbundling maintenance from OEM hardware sales. Public hospital procurement committees under IMSS frameworks exhibit highest price sensitivity, while Monterrey private cardiac centers demonstrate lowest sensitivity due to cross-border patient revenue.
Supply Chain Analysis
Domestic-content mandates under Mexican federal procurement guidelines are reshaping sourcing patterns for imaging system installation and validation services, though superconducting magnet cores and photon-counting detector arrays remain exempt. Manufacturing concentrates in Germany, Japan, and the United States for high-field MRI platforms, with China and South Korea supplying digital radiography components and ultrasound transducers. The supply chain rests on helium-3 isotope availability for magnet cooling, rare-earth elements for gradient coils, and semiconductor substrates for detector fabrication. Single-source vulnerability concentrates in superconducting wire supply from Japanese specialty metals producers. Distribution runs through authorized distributors with COFEPRIS registration capabilities, who maintain regional service depots in Mexico City, Monterrey, and Guadalajara.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mexico diagnostic imaging equipment market functions as a stable compounder, with software-defined imaging subscriptions converting capital equipment relationships into recurring revenue streams that smooth hospital budget cycles and extend vendor cash flow visibility.
For Market Incumbents: Lock in long-term service contracts across aging installed bases in Mexico City public hospital networks before independent service organizations capture maintenance revenue. Deepen backward integration into AI-assisted diagnostic software development to differentiate hybrid imaging platforms from commodity CT configurations. Counter the threat of subscription-based radiology-as-a-service entrants by unbundling hardware from service pricing for mid-tier private clinics. For New Entrants and Emerging Players: The price-point gap between premium PET-MRI configurations and refurbished economy-tier MRI systems creates entry space for independent service organizations targeting COFEPRIS technical personnel bottlenecks. Capture white-space in Querétaro and Puebla outpatient imaging centers seeking per-scan pricing models. Penetrate fastest through partnerships with local biomedical engineering firms that accelerate deployment timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among independent service organizations with established COFEPRIS registration capabilities and regional service depot networks. The five-to-ten year viability window favors acquisition targets with concentrated installed base relationships in central Mexican states. Monitor COFEPRIS post-market surveillance mandate enforcement as the signal indicating when quality management system investments become competitive differentiators versus compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Registration Streamlining | Accelerated Class III device approvals compress deployment timelines for MRI and CT systems in oncology centers. |
| Software-Defined Imaging Subscription | Per-scan pricing models bundle maintenance and training, minimizing balance sheet exposure for mid-tier clinics. |
| Hybrid Imaging Architecture Deployment | PET-CT and PET-MRI integration commands premium pricing from integrated cardiac and oncological workflows. |
| Independent Service Organization Expansion | Maintenance unbundling from OEM hardware captures revenue from aging installed bases across public networks. |
| AI-Assisted Diagnostic Software Development | Image reconstruction algorithms reduce scan times and contrast agent requirements, altering throughput economics. |
Research Methodology
Direct dialogue with hospital purchasing committee members, biomedical engineering directors, COFEPRIS regulatory affairs specialists, and GPO contracts managers grounded the qualitative assessment, supplemented by validation against hospital procurement databases, GPO contract disclosures, COFEPRIS medical device registration filings, and IMSS centralized tender records. Bottom-up and top-down triangulation cross-checked equipment shipment data with federal health budget allocations across Mexican state health systems.
Bottom-up modeling aggregated modality-specific installation forecasts across CT, MRI, ultrasound, and X-ray platforms, while top-down analysis anchored total market sizing to federal health infrastructure investment programs. Segmentation dimensions spanned product type, end-user facility tier, technology maturity, and application concentration, with CAGRs derived from historical replacement cycle analysis and technology refresh timelines. Forecast inputs incorporated COFEPRIS regulatory streamlining pace and public hospital network expansion commitments across Mexico City, Guadalajara, and Monterrey.
The model assumes a particular technology adoption path; alternative pathways for photon-counting CT detector deployment would alter the outlook if reimbursement frameworks fail to recognize spectral imaging value. Forecasts reflect assumptions regarding INSABI and IMSS reimbursement stability, superconducting magnet supply continuity, and radiologist workforce pipeline expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Breast Imaging Market
Medical Imaging
Radiology As a Service Market
Medical Imaging
Medical Imaging Management Market
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
Smart X-Ray Detectors Market
Medical Imaging
Contrast Media Market
Medical Imaging
Italy Digital X-Ray Market
Medical Imaging
China Digital Radiology Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
France Magnetic Resonance Imaging Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
Image Guided Systems Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
France Mammography Market
Medical Imaging
Teleradiology Services Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market