
 Tracheostomy Tray Market | 2026-2036
Tracheostomy Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Tracheostomy Tray Market Analytics
Polypropylene is realigning cost structures in tray fabrication as manufacturers phase out PVC in response to leaching concerns and disposal regulations. Medtronic plc leverages its integrated sterilization networks to secure hospital contracts across North America. Smiths Group plc anchors its position through specialized pediatric configurations that meet neonatal ICU protocols. TRACOE Medical GmbH competes on precision-molded silicone interfaces that reduce periprocedural trauma.
A tracheostomy tray is a sterile, pre-packaged collection of instruments and consumables—including dilators, tracheal hooks, suction catheters, and securing devices—designed to support percutaneous or surgical airway access and subsequent stoma maintenance. Standard trays dominate hospital procurement due to volume pricing and simplified inventory management, while custom trays capture premium margins by accommodating physician-specific instrument preferences and complex airway algorithms. Disposable plastic trays are displacing reusable stainless steel sets in ambulatory surgical centers where turnover speed and infection control protocols prioritize single-use workflows.
FDA 510(k) clearance requirements and EU MDR Class IIa designation govern tray sterilization validation and biocompatibility testing, creating compliance thresholds that filter smaller contract manufacturers from institutional supply chains. ISO 13485 quality management certification has become a de facto prerequisite for Original Equipment Manufacturer partnerships with major distributors. Stakeholders must monitor evolving EPA guidance on medical plastics recycling, as sustainability mandates threaten to impose extended producer responsibility costs on single-use tray manufacturers.
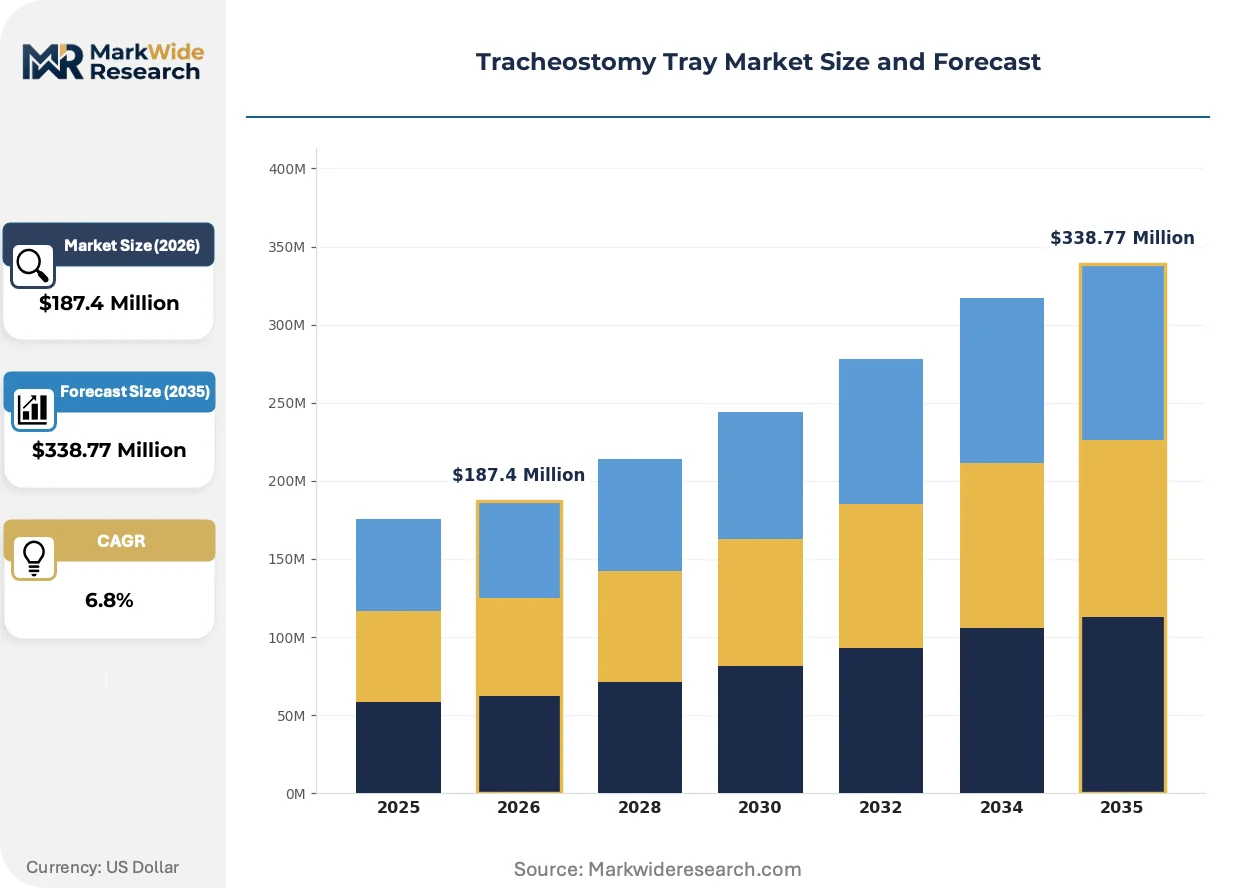
Market Dynamics
Polypropylene substitution for PVC is compressing material costs while EU MDR sterilization mandates force tray manufacturers to revalidate barrier specifications, creating simultaneous cost pressure and compliance burden across fabrication networks.
Growth Catalysts
- Critical care infrastructure expansion:Hospital ICU bed additions in the United States, Germany, and Japan are expanding procedural volumes for airway management kits.
- FDA 510(k) pathway standardization:Clearer sterilization validation requirements are streamlining market entry for compliant manufacturers.
- Single-use workflow preference:Ambulatory surgical centers are phasing out reusable stainless steel sets in favor of disposable plastic trays to accelerate turnover.
Market Restraints
- Petrochemical input volatility:Polypropylene resin prices fluctuate with crude oil benchmarks, squeezing margin predictability for tray fabricators.
- Contract manufacturer concentration:ISO 13485-certified sterilization capacity clusters in Germany and the United States, creating geographic supply risk.
- Reusable set residual demand:Academic medical centers with in-house sterilization infrastructure continue purchasing stainless steel configurations.
Strategic Opportunities
- Neonatal ICU specialization:Underserved pediatric airway protocols present white space for precision-scaled tray configurations.
- EPA extended producer responsibility frameworks:Early compliance with medical plastics recycling mandates positions manufacturers for preferred procurement status.
- Direct-to-hospital digital channels:E-procurement platforms are disintermediating traditional distributor markups in North American health systems.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity validation for new barrier materials extends product development cycles by 12-18 months.
- Sterilization network integration:Tray manufacturers must coordinate gamma or ethylene oxide capacity with component suppliers across fragmented contract sterilizer networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tracheostomy Tray Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tray, Pediatric Tray, Disposable Tray, Custom Tray End User: Hospitals, Home Care, Ambulatory Surgical Centers, Long-term Care Facilities Material: Plastic, Stainless Steel, Silicone, Rubber Application: Emergency Care, Elective Surgery, Critical Care, Post-operative Care |
| Companies Covered | Medtronic plc, Smiths Group plc, Teleflex Incorporated, Cook Group, TRACOE Medical GmbH, ConvaTec Group PLC, Boston Medical Products Inc., Fisher & Paykel Healthcare Limited, Intersurgical Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tracheostomy Tray Market Evolving Landscape
Sterile kit design is pivoting toward modularity and sustainability compliance. Material science advances and regulatory tightening are converging to reshape fabrication priorities.
Silicone interface molding is consolidating trauma-reduction performance in percutaneous insertion kits. Neonatal ICUs in Japan and Germany are adopting these precision-molded components at accelerated rates. The technology is consolidating competitive differentiation around procedural safety metrics rather than commodity pricing.
EU MDR Class IIa designation is elevating clinical evidence requirements for tray sterilization validation. Manufacturers must now submit biocompatibility documentation beyond prior CE-marking thresholds. Pediatric and long-term care configurations face the steepest compliance cost increases.
Hospital buying cooperatives are centralizing tracheostomy tray procurement through standardized SKU agreements. Group purchasing organizations are displacing individual hospital negotiations in the United States. This concentration is most visible in multi-hospital health systems seeking volume-based unit cost reductions.
Tracheostomy Tray Market Segmentation
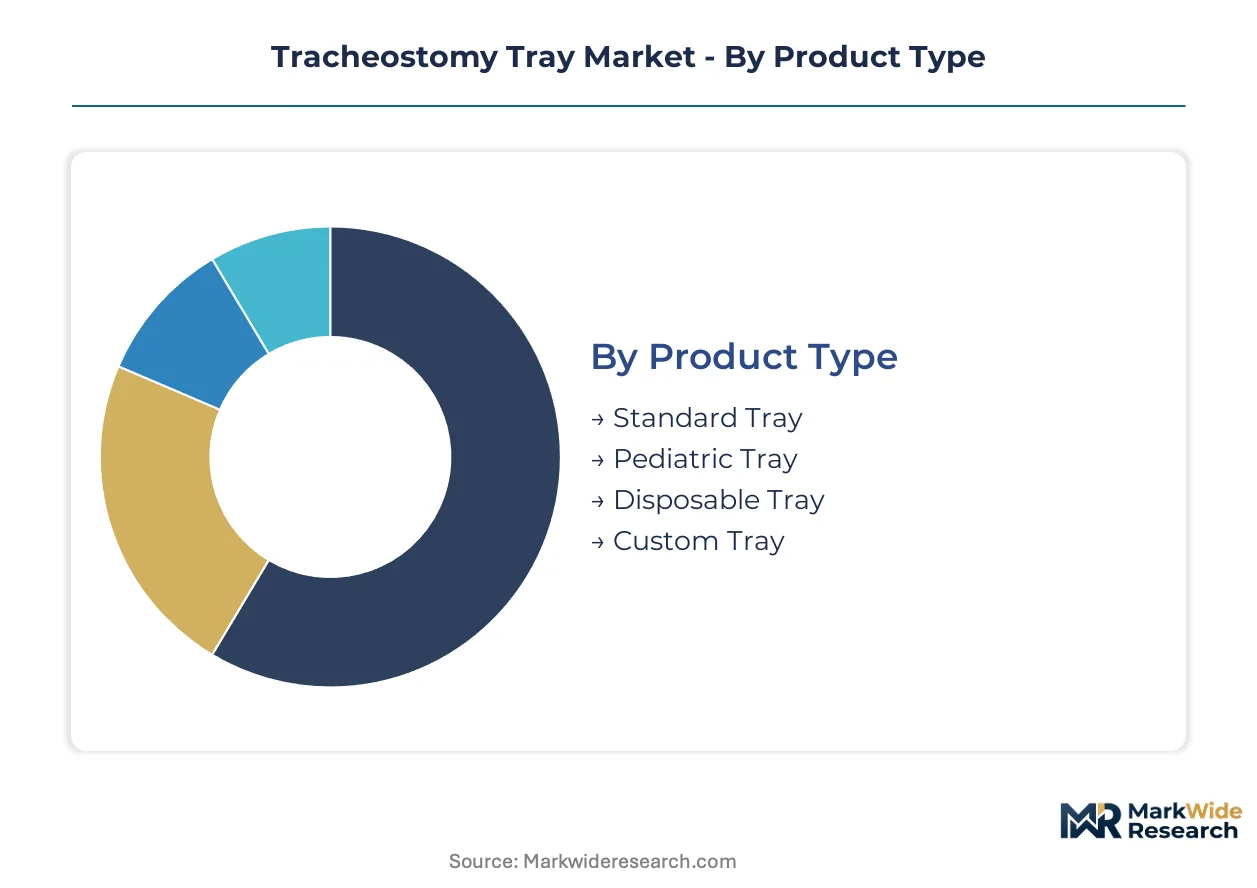
Tray configuration choices directly determine sterilization validation costs and procurement contract structures. Manufacturers align production capacity with specific segment requirements to secure institutional purchasing agreements.
Product Type:
Supply concentration clusters around tray formats that minimize sterilization complexity and maximize hospital purchasing volume.
- Standard Tray:Pre-configured instrument sets containing dilators, tracheal hooks, suction catheters, and securing devices in fixed arrangements. Hospital intensive care units in the United States and Germany drive procurement volume through group purchasing organization contracts that prioritize SKU standardization.
- Disposable Tray:Single-use polypropylene configurations designed for immediate disposal after percutaneous or surgical airway procedures. Ambulatory surgical centers in Japan are accelerating uptake as turnover speed requirements override capital equipment sterilization investments.
- Pediatric Tray:Precision-scaled instruments meeting neonatal ICU protocols for low-birth-weight patients.
- Custom Tray:Physician-specific instrument selections accommodating complex airway algorithms and specialized procedural preferences.
Standard Tray absorbs the bulk of installed capacity; Disposable Tray is expanding most quickly.
End User:
Customer type dictates pricing tier and distribution channel intensity across procurement networks.
- Hospitals:Multi-bed institutions with dedicated intensive care units and in-house sterilization infrastructure. Academic medical centers in Germany retain reusable stainless steel preferences while community hospitals in the United States convert to disposable formats under group purchasing mandates.
- Ambulatory Surgical Centers:Same-day procedure facilities prioritizing single-use workflows and rapid room turnover. Japanese ASC networks are consolidating procurement through direct manufacturer contracts that bypass traditional distributor markups.
- Home Care:Long-term ventilator-dependent patients requiring stoma maintenance supplies outside institutional settings.
- Long-term Care Facilities:Skilled nursing environments managing chronic airway support with limited on-site clinical staff.
Hospitals command the deepest volume discounts; Ambulatory Surgical Centers are converting to single-use formats fastest.
Material:
Fabrication substrate determines biocompatibility testing burden and regulatory pathway complexity.
- Plastic:Polypropylene and medical-grade polymers replacing PVC in response to leaching concerns and EU MDR disposal regulations. Tray manufacturers in the United States are compressing material costs while revalidating barrier specifications under elevated sterilization mandates.
- Silicone:Precision-molded interfaces reducing periprocedural trauma in percutaneous insertion kits. Neonatal ICUs in Japan and Germany are adopting these components at accelerated rates as procedural safety metrics override commodity pricing.
- Stainless Steel:Reusable instrument configurations retained by academic medical centers with captive sterilization capacity.
- Rubber:Legacy securing devices and gasket materials facing displacement by silicone alternatives.
Plastic dominates production volume; Silicone is climbing the fastest on trauma-reduction performance.
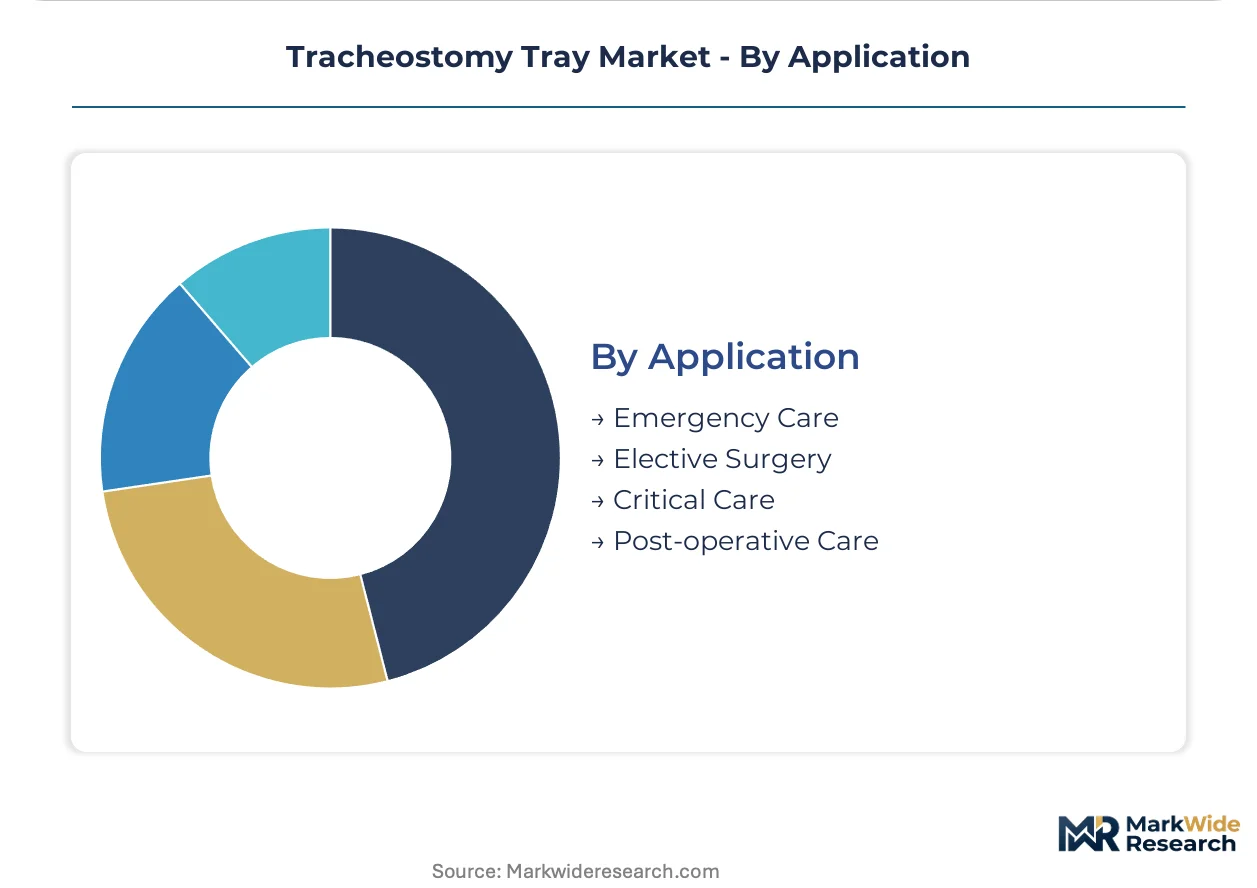
Application:
Clinical setting determines instrument complexity and regulatory scrutiny intensity.
- Critical Care:Intensive care unit airway management for prolonged mechanical ventilation. Hospital bed expansion in the United States, Germany, and Japan is expanding kit utilization as procedural volumes track ICU infrastructure investment.
- Emergency Care:Time-critical airway access in trauma and acute respiratory failure scenarios. Emergency departments prioritize complete instrument visibility and rapid deployment speed over cost minimization.
- Elective Surgery:Scheduled tracheostomy procedures with pre-operative planning and controlled environments.
- Post-operative Care:Stoma maintenance and decannulation protocols following initial airway establishment.
Critical Care absorbs the majority of tray consumption; Emergency Care is gaining share fastest on throughput requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device manufacturing parks in Costa Rica and Puerto Rico attract tray fabricators through decade-long tax holidays on export revenues. These zones concentrate sterile packaging operations serving North American hospital networks.
United States
ICU bed expansion in Texas and Florida drives procedural volume for disposable tray configurations. FDA 510(k) pathway standardization accelerates sterilization validation timelines for compliant manufacturers. Minneapolis-St. Paul hosts Medtronic's integrated sterilization networks that secure multi-hospital contracts across the Upper Midwest.
Germany
Academic medical centers in Bavaria and Baden-Württemberg retain reusable stainless steel preferences despite single-use conversion trends. EU MDR Class IIa designation elevates biocompatibility documentation requirements beyond prior CE-marking thresholds. The Stuttgart industrial corridor clusters ISO 13485-certified contract sterilizers serving tray component suppliers.
Japan
Ambulatory surgical centers in Tokyo and Osaka accelerate uptake of disposable polypropylene trays to meet turnover speed requirements. METI medical device reimbursement reforms incentivize procedural safety investments over commodity pricing. The Nagoya medical technology district concentrates precision-molded silicone interface production for neonatal ICU applications.
United Kingdom
NHS procurement consolidation drives volume-based unit cost reductions for standard tray configurations. MHRA post-Brexit regulatory alignment maintains EU MDR sterilization standards while streamlining domestic approval pathways. The Cambridge-Oxford-London golden triangle anchors pediatric tray specialization for complex airway algorithms.
India
Private hospital chains in Maharashtra and Karnataka expand critical care infrastructure to capture medical tourism flows. CDSCO medical device rules harmonize with ISO 13485 quality management prerequisites for Original Equipment Manufacturer partnerships. The Hyderabad medical device cluster attracts contract manufacturers serving European distributor networks.
Tracheostomy Tray Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated device companies commanding hospital procurement contracts and regional fabricators capturing ambulatory surgical center volume. The vendor base concentrates around sterilization network access rather than raw production scale. Three archetypes dominate: diversified medtech conglomerates with captive sterilization infrastructure, precision-molded component specialists, and disposable plastics converters serving high-turnover facilities. Competitive moves center on sterilization capacity expansion and direct-to-hospital digital channel development.
Among diversified medtech conglomerates, Medtronic plc and Smiths Group plc exemplify the integrated infrastructure archetype. Medtronic leverages North American sterilization networks to secure multi-year hospital contracts. Smiths anchors positioning through specialized configurations that address protocol-specific requirements. TRACOE Medical GmbH represents the precision-component specialist tier, occupying a position defined by trauma-reduction performance metrics rather than commodity pricing. These three companies illustrate how competitive differentiation fragments across sterilization integration, clinical specialization, and material science expertise.
| Leading Market Players |
|---|
| Medtronic plc |
| Smiths Group plc |
| Teleflex Incorporated |
| Cook Group |
| TRACOE Medical GmbH |
| ConvaTec Group PLC |
| Boston Medical Products Inc. |
| Fisher & Paykel Healthcare Limited |
| Intersurgical Ltd. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up sterilization specialists have consolidated contract manufacturing capacity across Germany and the United States, tightening pricing discipline for tracheostomy tray fabricators while compressing margin buffers for mid-scale producers without captive gamma or ethylene oxide networks.
Pricing Analysis
Premium pricing for short lead times dominates procurement negotiations, with hospital group purchasing organizations extracting volume discounts against standard tray configurations while ambulatory surgical centers pay spot premiums for rapid-turnover disposable formats. Price differentiation rests on ISO 13485 certification tier and sterilization validation completeness, with FDA 510(k) cleared products commanding measurable premiums over CE-marked equivalents. Pricing pressure stems from polypropylene resin volatility tracking crude benchmarks, squeezing fabricators without backward integration into polymer sourcing. Academic medical centers with in-house sterilization infrastructure exhibit lowest price sensitivity; Japanese ASC networks demonstrate highest elasticity.
Supply Chain Analysis
Freight cost inflation has reconfigured component sourcing patterns, with tray fabricators shifting from Asian polymer suppliers to regional Mexican and Canadian resin distributors to mitigate trans-Pacific container exposure. Geographic supply concentration clusters in Germany, the United States, and Costa Rica, where medical device manufacturing parks offer decade-long tax holidays on export revenues. Raw material dependencies center on polypropylene resin, medical-grade silicone, and sterilization packaging films. Single-source vulnerability concentrates in ISO 13485-certified gamma sterilization capacity. Distribution runs through hospital buying cooperatives and group purchasing organizations in North America, direct manufacturer contracts in Japan, and regional distributor networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into sterilization infrastructure represents the decisive competitive race, with incumbents acquiring contract gamma facilities and new entrants securing ethylene oxide partnerships to bypass capacity bottlenecks.
For Market Incumbents: Lock in multi-year sterilization capacity reservations with German and United States contract providers before capacity constraints intensify under EU MDR revalidation demands. Acquire precision-molded silicone specialists in Japan's Nagoya district to defend trauma-reduction positioning against emerging component specialists. Prioritize GPO contract renewals in Texas and Florida ICU expansion corridors. For New Entrants and Emerging Players: Silicone interface molding expertise offers the most penetrable technology-first wedge, with neonatal ICU protocols in Germany and Japan underserved by incumbent trauma-reduction portfolios. Target direct-to-hospital digital procurement channels in North American ASC networks, bypassing traditional distributor markups. Lead with EPA recycling compliance positioning to capture sustainability-mandated procurement preferences. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale ISO 13485-certified contract manufacturers in the United States Upper Midwest facing working capital pressure from polypropylene cost volatility. Five-to-ten year viability hinges on sterilization network integration depth rather than production scale. Monitor EU MDR biocompatibility documentation backlogs as inflection signal for compliance-cost winners.| Strategic Initiative | Industry Significance |
|---|---|
| Sterilization Network Acquisition | Captive gamma or ethylene oxide capacity secures hospital contract renewals against supply-constrained competitors. |
| Silicone Interface Development | Precision-molded trauma-reduction components differentiate positioning in neonatal ICU procurement decisions. |
| Direct-to-Hospital Digital Channel | E-procurement platforms disintermediate distributor markups in North American ASC volume capture. |
| EPA Recycling Compliance Investment | Extended producer responsibility readiness positions manufacturers for preferred procurement status. |
| Pediatric Tray Specialization | Neonatal ICU protocol compliance opens white-space margins above commoditized standard configurations. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation databases, and hospital group purchasing organization contract records formed the secondary backbone, cross-referenced against primary interviews with biomedical engineers, GPO contracts managers, sterilization facility operators, and neonatal ICU clinicians. Bottom-up and top-down triangulation validated volume estimates across product type, end user, material, and application segments.
Bottom-up modeling aggregated procedural volume projections across United States, German, and Japanese ICU bed expansion corridors, while top-down analysis calibrated aggregate market sizing against medical device trade flow data. Segmentation dimensions spanned tray configuration, customer type, fabrication substrate, and clinical setting. CAGRs derived from procedure volume elasticity to critical care infrastructure investment and sterilization regulatory compliance cost trajectories. Forecast inputs incorporated polypropylene resin price volatility patterns and EU MDR revalidation timeline assumptions.
Several conditions sit outside the modeled scope, including unforeseen EPA regulatory acceleration on medical plastics recycling, abrupt sterilization facility closures from environmental compliance actions, and pandemic-scale ICU demand surges. Forecasts reflect documented assumptions subject to revision from these factors. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
Yankauer Suction Tips Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Steam Sterilizer Bag Market
Medical Supplies
Europe Hospital Supplies Market
Medical Supplies
Anaesthesia Conduction Kits Market
Medical Supplies
Saudi Arabia Medical Bandages Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
India Feminine Hygiene Market
Medical Supplies
Americas Medical Rubber and Balloon Product Market
Medical Supplies
Global IV Flush Syringe Market
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
Autoclaving Trays Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Fibrin Sealants Market