
 Polyvinyl Butyral (PVB) Resins Market | 2026-2036
Polyvinyl Butyral (PVB) Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Polyvinyl Butyral (PVB) Resins Market Analytics
The Polyvinyl Butyral (PVB) Resins Market is pivoting on a widening split between optical-grade premium tiers and commodity construction grades. Kuraray leverages its captive polyvinyl alcohol supply chain to dominate high-purity optical segments. Eastman Chemical Company anchors North American automotive laminated glass demand through long-term OEM supply agreements. Sekisui Chemical differentiates in Asian markets with specialized resin formulations for acoustic interlayers.
Polyvinyl butyral resin is a thermoplastic polymer produced by acetalization of polyvinyl alcohol with butyraldehyde, typically containing 17-20% hydroxyl groups by weight and exhibiting glass transition temperatures between 60-80°C depending on molecular architecture. It functions primarily as the binding interlayer in laminated safety glass, providing impact resistance, acoustic damping, and UV filtration when sandwiched between glass substrates. High molecular weight grades command margin premiums in automotive windscreen applications where penetration resistance and optical clarity are non-negotiable. Medium molecular weight segments sustain volume leadership in architectural laminated glass for hurricane-prone building codes. Powder and granule forms dominate industrial processing due to melt-flow consistency and storage stability advantages over solution-based alternatives.
The US NHTSA Federal Motor Vehicle Safety Standard 205 mandates laminated windscreens for occupant retention, directly governing PVB interlayer thickness and impact performance specifications. China's SAMR enforces GB 9656 automotive safety glass standards that tighten optical distortion limits and accelerate substitution of inferior resin grades. The EU REACH regulation restricts residual butyraldehyde emissions during resin synthesis, elevating compliance costs for non-integrated producers. Stakeholders must monitor evolving building energy codes in India and Southeast Asia, where laminated glass with infrared-blocking PVB interlayers is gaining specification in green certification frameworks.
Market Dynamics
Automotive laminated glass specifications are tightening across major economies, forcing resin producers to upgrade molecular weight consistency and optical clarity thresholds or lose qualification status with tier-one glass fabricators.
Growth Catalysts
- GB 9656 Standard Revision:China's SAMR mandates stricter optical distortion limits for automotive glazing, disqualifying inferior PVB grades and accelerating replacement demand.
- Hurricane-Resistant Building Codes:Coastal US states and Caribbean territories now require laminated glass in commercial construction, expanding architectural interlayer consumption.
- Acoustic Damping Specification:European premium automotive OEMs are layering specialized PVB formulations for cabin noise reduction in electric vehicle platforms.
Market Restraints
- Butyraldehyde Price Volatility:Feedstock costs fluctuate with n-butanol supply disruptions, compressing margins for non-integrated resin producers.
- Polyvinyl Alcohol Supply Concentration:Captive PVA supply chains in Japan and Germany lock out mid-scale competitors from optical-grade PVB production.
- Ethylene-Vinyl Acetate Substitution:EVA interlayers gain share in solar panel encapsulation and select architectural applications where UV resistance requirements are less stringent.
Strategic Opportunities
- India Green Building Certification:GRIHA and IGBC rating systems are specifying infrared-blocking PVB interlayers for energy-efficient commercial facades in Mumbai and Bangalore.
- Head-Up Display Windscreens:Wedge-shaped PVB interlayers for HUD compatibility represent a high-margin niche as premium automotive penetration expands.
- Recycled Content Mandates:EU Ecodesign for Sustainable Products Regulation creates pull for post-industrial PVB recovery and re-pelletization services.
Industry Challenges
- Optical Metrology Talent Scarcity:Glass fabricators struggle to hire technicians capable of operating haze-gauging and birefringence measurement equipment for incoming resin qualification.
- Multi-Site Certification Timelines:Qualifying new PVB production lines with automotive OEMs requires 18-24 month validation cycles that delay capacity monetization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyvinyl Butyral (PVB) Resins Market |
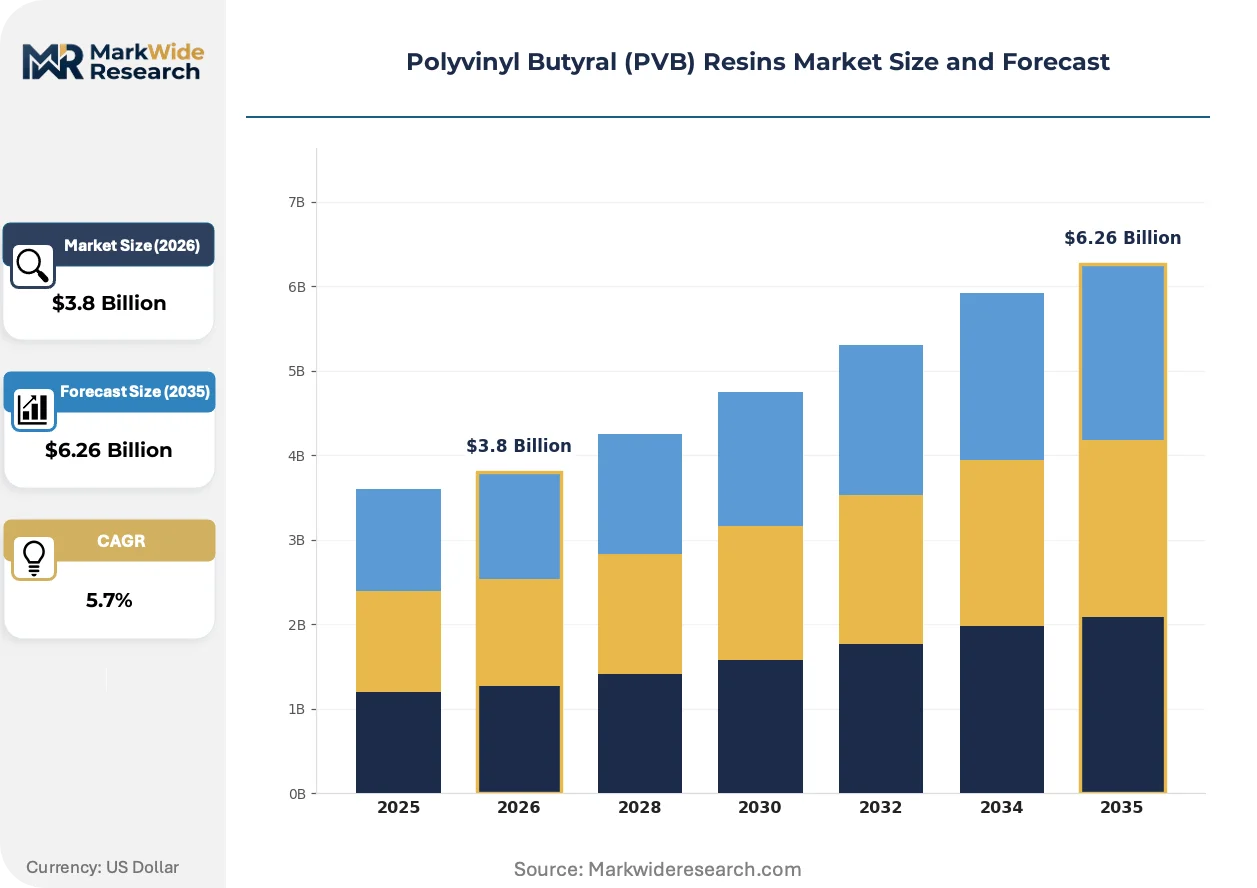
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Highly Soluble, Low Molecular Weight, Medium Molecular Weight, High Molecular Weight End Use Industry: Automotive, Construction, Furniture, Optical Application: Laminated Glass, Adhesives, Coatings, Films Form: Powder, Granules, Sheets, Solutions |
| Companies Covered | Kuraray, Eastman Chemical Company, Sekisui Chemical, Chang Chun Group, Saint-Gobain, Huakai Plastic, Kingboard Fogang Specialty Resin, Anhui Wanwei Group, Everlam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyvinyl Butyral (PVB) Resins Market Evolving Landscape
PVB resin functionality is extending beyond passive safety toward active performance attributes, with interlayer engineering now addressing thermal management, acoustic tuning, and embedded sensor compatibility.
Multilayer PVB architectures incorporating infrared-absorbing nanoparticles are converging with building energy retrofit programs, enabling glass fabricators to offer single-pane replacement solutions that meet modern thermal codes without full window replacement. European facade contractors are specifying these interlayers for heritage building renovations where structural frames cannot support triple-glazing. The technology is compressing payback periods for energy efficiency investments and displacing conventional low-emissivity coatings in certain climate zones.
EU REACH restrictions on residual aldehyde emissions are forcing resin producers to invest in closed-loop reactor designs and real-time gas chromatography monitoring. The regulation elevates capital intensity for new market entrants while rewarding incumbent producers with existing emission control infrastructure. Asian export-oriented producers are accelerating compliance investments to maintain access to German and French automotive glass supply chains.
Glass fabricators are consolidating procurement relationships around qualified resin suppliers capable of lot-to-lot consistency documentation. Long-term offtake agreements with volume commitments are displacing spot-market purchasing for automotive-grade material. This concentration is most visible in China, where leading windscreen producers are locking in three-to-five year supply contracts with domestic resin manufacturers to secure capacity ahead of export expansion.
Polyvinyl Butyral (PVB) Resins Market Segmentation
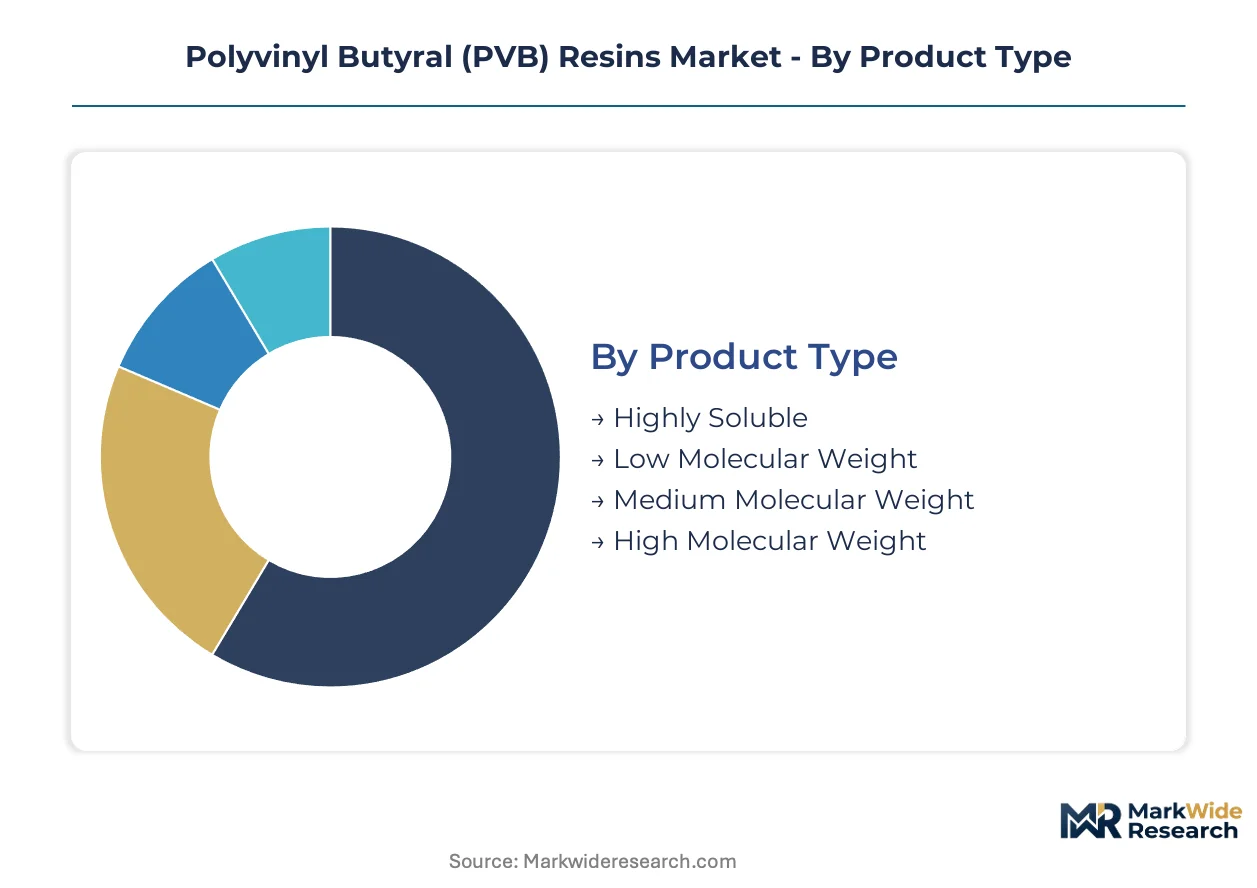
PVB resin buyers segment procurement by molecular architecture for optical clarity thresholds and by form factor for processing equipment compatibility. Glass fabricators, adhesive compounders, and coating formulators each impose distinct rheological and purity specifications that reshape supplier qualification requirements.
Product Type:
Buyers prioritize molecular weight distribution as the primary determinant of impact resistance and melt-flow behavior in lamination lines.
- High Molecular Weight:Resins with weight-average molecular weights exceeding 250,000 g/mol deliver superior penetration resistance and optical homogeneity. Automotive windscreen producers in Germany and Japan specify these grades for OEM qualification programs where haze values below 0.5% are mandatory.
- Medium Molecular Weight:Architectures ranging 150,000-250,000 g/mol balance processability with mechanical performance. Architectural laminated glass fabricators in Florida and coastal China favor these grades for hurricane-rated glazing where cost-per-square-meter competes with performance.
- Low Molecular Weight:Chains below 150,000 g/mol enable rapid dissolution in solvent-based adhesive formulations. Furniture manufacturers and DIY coating producers in Southeast Asia source these for spray-application compatibility.
- Highly Soluble:Modified hydroxyl distributions accelerate dissolution kinetics for specialty coating applications. Optical film producers in South Korea require these for precision casting operations.
Volume sits with Medium Molecular Weight; growth tilts toward High Molecular Weight.
End Use Industry:
Application-specific certification regimes fragment demand across safety-critical and aesthetic-driven sectors.
- Automotive:NHTSA FMVSS 205 and China's GB 9656 mandate laminated windscreens for occupant retention, locking resin suppliers into 18-24 month OEM validation cycles. Electric vehicle platforms are expanding acoustic interlayer specifications.
- Construction:Hurricane-resistant building codes in Florida, Texas, and Caribbean territories mandate laminated glass in commercial facades. Infrared-blocking interlayers are gaining traction in India's GRIHA-certified green buildings.
- Furniture:Decorative glass tabletops and display cases demand medium-clarity grades where cost minimization dominates supplier selection.
- Optical:Head-up display windscreens and precision lenses require ultra-low birefringence resins with sub-0.3% haze. German and Japanese optical-grade producers maintain captive PVA supply chains for this segment.
Construction commands current volume; automotive HUD applications are climbing the fastest.
Application:
Functional requirements diverge sharply between structural safety applications and surface modification uses.
- Laminated Glass:Interlayer sheets absorb impact energy and retain glass fragments during breakage. Automotive and architectural fabricators in China, Germany, and the US account for the majority of resin offtake.
- Films:Thin extruded layers serve photovoltaic encapsulation and protective packaging. Solar panel manufacturers are evaluating PVB against EVA alternatives where UV resistance is critical.
- Adhesives:Solution-grade resins bond dissimilar substrates in automotive interior assembly and furniture manufacturing.
- Coatings:Protective and decorative finishes leverage PVB's adhesion to metal, wood, and plastic surfaces.
Laminated Glass absorbs the bulk of resin volume; Films are gaining share fastest in renewable energy applications.
Form:
Processing equipment and storage logistics dictate form selection across industrial and specialty channels.
- Sheets:Calendered interlayers feed directly into glass laminating autoclaves. Major windscreen producers in China and Germany prefer sheet form for thickness consistency and contamination control.
- Powder:Free-flowing particles enable precise metering in extrusion compounding and adhesive manufacturing. Powder dominates architectural adhesive formulations in India.
- Granules:Pelletized resin reduces dust generation during handling. European coating producers favor granules for automated feeding systems.
- Solutions:Pre-dissolved resin eliminates dissolution time for small-batch coating and adhesive operations. Specialty optical film casters in Japan source solutions for viscosity-critical applications.
Sheets carry the highest volume; Powder is expanding most quickly in emerging market adhesive sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the world's densest concentration of PVB resin capacity and downstream laminated glass fabrication, with the Yangtze River Delta corridor hosting integrated supply chains from polyvinyl alcohol feedstock to automotive windscreen assembly.
China
Automotive OEMs in Shanghai and Wuhan are qualifying domestic resin grades for export windscreen programs. SAMR's tightened GB 9656 optical distortion limits are disqualifying legacy suppliers. The Yangtze River Delta corridor concentrates new extrusion capacity serving European automotive glass fabricators.
United States
Florida and Texas building codes mandate laminated glass in commercial construction for hurricane resistance. NHTSA FMVSS 205 governs windscreen penetration performance for domestic automakers. The Southeast automotive corridor around Spartanburg and Chattanooga sources resin through long-term offtake agreements with qualified suppliers.
Germany
Premium automotive OEMs in Stuttgart and Munich specify acoustic-grade interlayers for electric vehicle platforms. EU REACH restrictions on residual butyraldehyde emissions elevate compliance costs for non-integrated producers. The Rhine-Ruhr industrial cluster hosts captive polyvinyl alcohol supply chains feeding optical-grade resin production.
India
GRIHA and IGBC green building certifications are specifying infrared-blocking interlayers for commercial facades in Mumbai and Bangalore. The country's national building code regulator is evaluating laminated glass mandates for high-rise construction. Gujarat's chemical corridor is expanding domestic resin compounding capacity for architectural adhesive applications.
Japan
Head-up display windscreen specifications from Tokyo-based automakers are pulling wedge-shaped interlayer demand. METI oversees industrial chemical emissions standards affecting resin synthesis operations. The Kansai region around Osaka maintains specialized formulation capabilities for acoustic damping grades.
Polyvinyl Butyral (PVB) Resins Market Competitive Landscape
Premium-margin players sit above commodity-margin players across optical clarity certification tiers, with high-purity resin producers commanding qualification-dependent pricing while construction-grade suppliers compete on volume throughput. The vendor base stratifies into three tiers: integrated chemical conglomerates with captive feedstock, mid-scale regional compounders serving architectural channels, and specialty formulators targeting acoustic or HUD-grade niches. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing long-term automotive OEM validation cycles and glass fabricator offtake agreements.
Within the integrated chemical conglomerate tier, Kuraray and Eastman Chemical Company exemplify players with backward control over polyvinyl alcohol feedstock. Sekisui Chemical occupies a position among Japanese specialists with differentiated formulation capabilities. These three anchors demonstrate how geographic clustering of upstream chemical assets shapes competitive positioning in optical-grade segments.
| Leading Market Players |
|---|
| Kuraray |
| Eastman Chemical Company |
| Sekisui Chemical |
| Chang Chun Group |
| Saint-Gobain |
| Huakai Plastic |
| Kingboard Fogang Specialty Resin |
| Anhui Wanwei Group |
| Everlam |
| Others |
Value Network & Pricing Analysis
Optical-grade versus commodity-grade certification divergence splits PVB resin procurement into parallel pricing regimes with fundamentally different supply chain footprints. High-purity automotive windscreen grades command qualification-dependent premiums through 18-24 month OEM validation cycles, while architectural construction volumes flow through spot-market channels where butyraldehyde feedstock costs transmit directly to contract terms. This bifurcation concentrates margin capture among integrated producers with captive polyvinyl alcohol supply chains in Japan and Germany, leaving non-integrated compounders exposed to n-butanol volatility in medium molecular weight segments.
Pricing Analysis
Yield-based pricing anchors optical-grade PVB contracts, with automotive glass fabricators paying premiums tied to lot-to-lot haze consistency and penetration resistance outcomes. Three-tier pricing structure across premium, standard, and economy levels separates NHTSA-qualified automotive grades from hurricane-rated architectural tiers and DIY coating solutions. Cost compression in medium molecular weight segments is intensifying because Chinese domestic capacity expansion is eroding import premiums for Southeast Asian adhesive compounders. Tier-one automotive glass fabricators exhibit lowest price sensitivity due to embedded qualification switching costs, while furniture coating manufacturers in Vietnam and Indonesia source aggressively on spot indices.
Supply Chain Analysis
Polyvinyl alcohol feedstock supply rests on integrated chemical conglomerates in Japan, Germany, and China's Yangtze River Delta corridor. PVB resin production draws from butyraldehyde derivatives, specialized extrusion equipment, and optical metrology instrumentation for quality verification. Single-source vulnerability concentrates in high-purity PVA precursors where Kuraray and Eastman maintain captive production. Distribution runs through long-term offtake agreements with qualified automotive glass fabricators in Germany, China, and the United States, displacing spot purchasing for safety-critical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH restrictions on residual butyraldehyde emissions have erected a cost-of-compliance barrier that rewards incumbent producers with existing emission control infrastructure while elevating capital intensity beyond reach for prospective entrants. This regulatory moat deepens with each enforcement cycle as Asian export-oriented producers accelerate compliance investments to maintain German and French automotive glass supply chain access.
For Market Incumbents: Deploy captive PVA supply chain leverage to extend optical-grade certification coverage into emerging HUD-compatible wedge interlayer specifications. Add acoustic-grade formulation capacity in the Kansai region to capture electric vehicle platform demand from Tokyo-based automakers. EVA substitution threats in solar encapsulation and architectural channels require defensive specification-locking with tier-one glass fabricators through multi-year volume commitments. For New Entrants and Emerging Players: Digital channel routes through specialty coating e-procurement platforms offer lowest barrier entry for low molecular weight resin grades targeting Southeast Asian furniture manufacturers. India's GRIHA-certified commercial facade segment presents the most penetrable white-space for infrared-blocking interlayer introduction. A technical service partnership model with regional glass fabricators bypasses 18-24 month automotive OEM validation timelines entirely. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale regional compounders possessing qualified automotive supply relationships and available extrusion capacity expansion sites given China's GB 9656 standard revision accelerating domestic replacement demand. Long-term viability over a five-to-ten year horizon favors producers with demonstrated lot-to-lot consistency documentation and existing REACH compliance infrastructure. The signal to watch is qualification timeline compression by Chinese SAMR for domestic resin grades in European export windscreen programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVA Feedstock | Captive polyvinyl alcohol supply locks out competitors from optical-grade segments where haze thresholds are non-negotiable. |
| Long-term Supply Agreement with OEMs | Automotive glass fabricators in Stuttgart and Shanghai are consolidating procurement around qualified resin suppliers with documented consistency. |
| Acoustic Interlayer Formulation Development | European premium electric vehicle platforms are layering specialized PVB for cabin noise reduction, creating specification premiums. |
| Post-industrial PVB Recovery Service | EU Ecodesign for Sustainable Products Regulation creates mandated pull for re-pelletization capabilities among glass fabricators. |
| Joint Venture with Regional Glass Fabricator | China's Yangtze River Delta corridor hosts expanding windscreen capacity serving European automotive export programs. |
Research Methodology
Document review covered customs and trade flow databases, SEC 10-K filings from integrated chemical conglomerates, and automotive safety glass certification records, complemented by interviews with plant managers at resin production facilities, procurement leads at tier-one glass fabricators, distribution channel partners in Southeast Asia, and technical R&D directors specializing in interlayer formulations. Bottom-up triangulation across molecular weight grade production volumes and top-down validation against end-use industry consumption patterns ensured cross-verification of demand estimates.
Historical capacity utilization trends were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the analysis window. Segmentation modeling incorporated molecular weight architecture, end-use industry certification requirements, form factor processing compatibility, and regional production hub clustering. CAGRs were derived from slope-consistent trajectory fitting rather than endpoint anchoring, with forecast sensitivity tested against butyraldehyde price volatility scenarios and EVA substitution elasticity parameters in solar encapsulation applications.
Inputs from automotive OEM qualification databases and SAMR regulatory filing records were available through the study window; gaps in real-time glass fabricator inventory positioning introduce uncertainty bands around near-term demand inflection timing. Forecasts reflect documented assumptions regarding GB 9656 enforcement pace and REACH compliance cost pass-through rates. A small set of named triggers—including China export qualification acceleration, Florida building code expansion, and EU Ecodesign implementation timelines—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Photocure Resins Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Polyacrylamide Market
Polymers & Resins
Plastic Compounding Market
Polymers & Resins
Global Polymeric Adsorbents Market
Polymers & Resins
India Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Ethylene Acrylic Acid (EAA) Copolymers Market
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
United States Polymer Emulsion Market
Polymers & Resins
Polymer Ingredients Market
Polymers & Resins
Global Polyethylene Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Polymer Foam Market