
 Polymer Foam Market | 2026-2036
Polymer Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Foam Market Intelligence
A long-standing reliance on high-margin aerospace contractors is unwinding as demand shifts toward high-volume construction firms seeking advanced insulation. This rotation favors large-scale producers. BASF SE leverages its vast chemical production capacity to supply polyurethane foams for building insulation. Zotefoams plc, in contrast, specializes in high-performance foams for specialized applications, while Dow Inc. operates across a wide spectrum of end-user industries.
Polymer foam is a material comprising a solid polymer matrix and a gaseous phase, creating a cellular structure. These materials, characterized by either open or closed-cell configurations, provide lightweighting, thermal insulation, and energy absorption properties. Within product types, polyurethane foam and polystyrene foam constitute the largest volume segments due to their extensive use in construction. Rigid foam formats dominate thermal insulation applications, while flexible foam is essential for packaging solutions and furniture.
Regulatory frameworks significantly influence material composition and manufacturing processes. Europe's REACH regulation governs chemical usage, while the US EPA sets standards for blowing agents to limit ozone depletion potential. In parallel, China's MEE enforces stringent environmental protection laws on production facilities. Navigating these varied compliance requirements is a critical determinant of market access and cost structure for producers.
Market Dynamics
The central dynamic in the polymer foam market is the tension between cost-driven commodity production and regulation-driven material innovation. This forces a split where Chinese industrial clusters optimize for volume, while European and North American producers focus on high-performance, compliant materials.
Growth Catalysts
- Automotive Lightweighting:Vehicle manufacturers' persistent drive to reduce weight for fuel efficiency and electric vehicle range extension creates sustained demand for polypropylene and polyurethane foams in components like seating, bumpers, and headliners.
- Building Energy Efficiency Mandates:Government regulations, such as building codes in the US and Germany that require improved thermal performance, directly stimulate the use of rigid polystyrene and polyurethane insulation foams in construction.
- Circular Economy Policies:The EU Green Deal and related circularity frameworks are accelerating research and investment into foams with higher recycled content and improved end-of-life recyclability, creating new product categories.
Market Restraints
- Feedstock Price Volatility:The market's cost structure is highly sensitive to price fluctuations in petrochemical derivatives like styrene, propylene, and toluene diisocyanate (TDI), which are tied to volatile crude oil and natural gas markets.
- Regulatory Compliance Burden:Navigating the fragmented and stringent chemical regulations, including Europe's REACH and China's MEE environmental laws, increases operational costs and can delay new product introductions across geographies.
- Thermoset Recycling Challenges:The cross-linked chemical structure of dominant thermoset foams, particularly polyurethane, makes them difficult to recycle mechanically, hindering circularity goals and creating waste management challenges.
Strategic Opportunities
- Bio-Based Feedstocks:Developing and scaling foams derived from renewable sources like corn, sugarcane, or algae presents a significant opportunity to reduce carbon footprint and appeal to environmentally conscious end-users, especially in packaging.
- Advanced Recycling Technologies:Investment in chemical recycling processes, such as glycolysis and pyrolysis, that can break down complex polymer foams into their monomer constituents opens a pathway for true circularity for materials like PU and EPS.
- High-Performance Insulation:There is an opportunity for novel foam structures, like aerogels or vacuum-insulated panels incorporating foam, to address demand for ultra-high-performance insulation in specialized applications like cold chain logistics and aerospace.
Industry Challenges
- Capital-Intensive Production:Establishing new foam production lines, particularly for specialized foams or those requiring new blowing agent technologies, involves significant capital expenditure on reactors, extrusion equipment, and environmental controls.
- Supply Chain for Recycled Content:Securing a consistent, high-quality supply of post-consumer or post-industrial recycled plastic feedstock for foam production remains a major operational hurdle for manufacturers aiming to meet sustainability targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Foam Market |
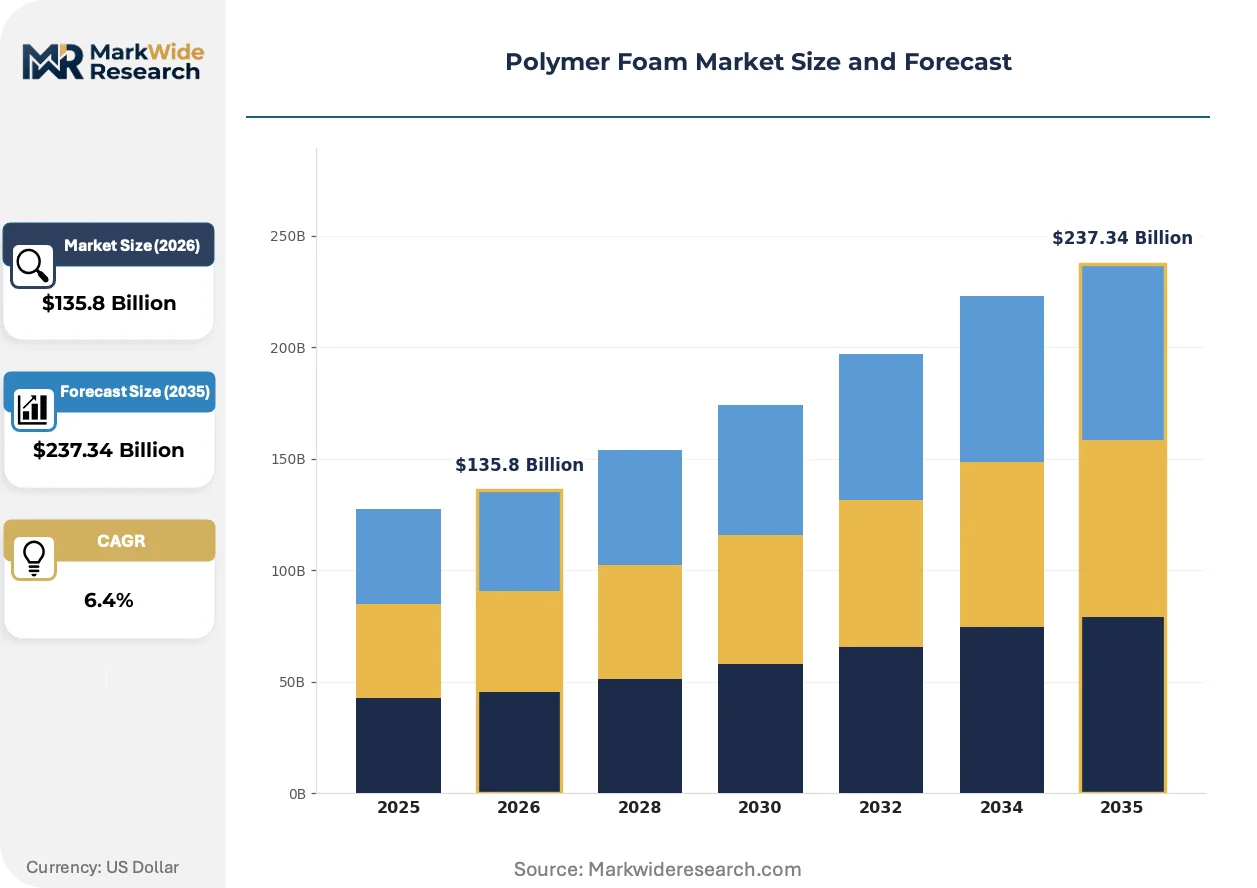
| Market Size in 2026 | $135.8 Billion |
| Market Size in 2035 | $237.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Polystyrene Foam, Polyethylene Foam, Polyvinyl Chloride Foam, Phenolic Foam Application: Thermal Insulation, Packaging Solutions, Automotive Components, Sports Equipment, Acoustic Panels End User Industry: Construction Firms, Consumer Electronics Manufacturers, Furniture Makers, Marine Equipment Builders, Aerospace Contractors Form: Rigid Foam, Flexible Foam, Spray Foam, Molded Foam, Extruded Foam |
| Companies Covered | Owens Corning, Arkema Group, BASF SE, UFP Technologies, Sekisui Chemical, Huntsman Corporation, Armacell International, Zotefoams plc, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Foam Market Strategic Shifts & Innovations
Material science advancements are fundamentally reshaping product capabilities, driven by a dual mandate for enhanced performance and verifiable sustainability. This creates a clear divergence between standard commodity foams and value-added materials designed to meet specific regulatory and application-driven requirements.
Advanced blowing agents based on hydrofluoroolefins (HFOs) and carbon dioxide provide superior insulation performance with significantly lower global warming potential. These formulations are being adopted by manufacturers of rigid insulation boards and spray polyurethane foam. The development is fragmenting the legacy market for hydrofluorocarbon (HFC) blowing agents, creating distinct performance and compliance tiers.
Europe's F-Gas Regulation imposes a strict phase-down schedule on HFCs, which have high global warming potential. This directly compels foam producers, especially in the construction sector, to reformulate their products using next-generation blowing agents. The rigid polyurethane foam segment is most affected, accelerating its transition toward HFO and water-based systems to remain compliant.
A preference for validated circularity is altering purchasing criteria, particularly in business-to-business transactions. Buyers in the automotive and electronics sectors now often require suppliers to provide products with certified recycled content, verified through standards like mass balance accounting. This shift is most visible in Germany and France, where strong Extended Producer Responsibility (EPR) schemes influence corporate procurement.
Polymer Foam Market Segmentation
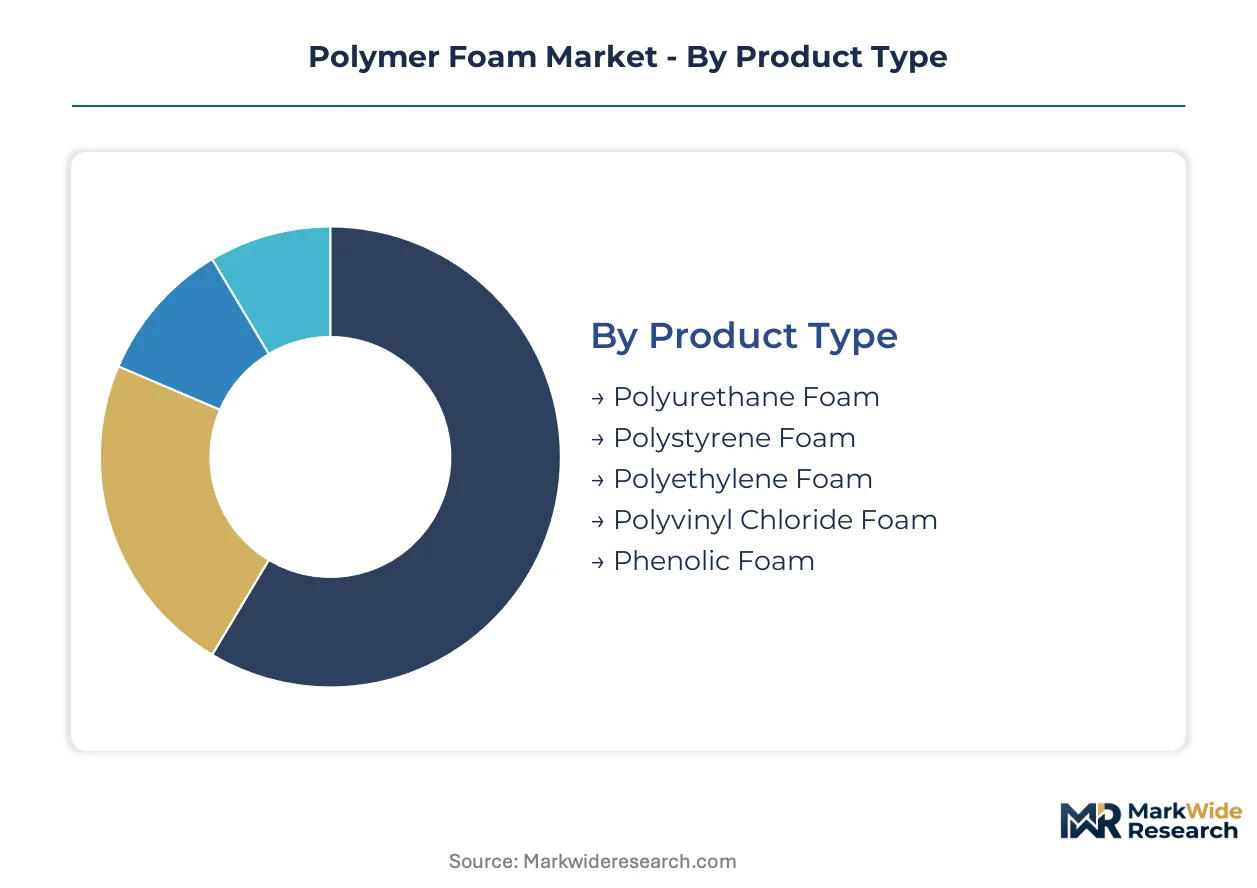
The polymer foam market exhibits diverse characteristics across its various segments, reflecting specialized material requirements and distinct end-user demands. Understanding these segmentation nuances allows manufacturers to tailor product development and optimize supply chains. This granular view highlights where value creation concentrates and where competitive pressures are most acute.
Product Type:
Product type segmentation reveals a clear distinction between domestically consumed commodity foams and specialized formulations often destined for export markets.
- Polyurethane Foam:A versatile polymer made from isocyanates and polyols, available in both rigid and flexible forms. Demand concentrates in construction for rigid insulation boards, driven by stringent building energy efficiency mandates in Germany and the US.
- Polystyrene Foam:Produced from styrene monomer, primarily as expanded (EPS) or extruded (XPS) foam, offering excellent thermal insulation. Construction firms in China and Europe drive demand for thermal insulation applications, responding to national building codes and material cost-effectiveness.
- Polyethylene Foam:A lightweight, closed-cell foam known for its cushioning and impact absorption properties. Packaging solutions and sports equipment manufacturers utilize this material for protective applications.
- Polyvinyl Chloride Foam:Characterized by its fine cell structure and chemical resistance, finding applications in marine equipment and construction. Marine equipment builders in coastal regions use PVC foam for buoyancy and structural components.
- Phenolic Foam:Offers superior fire resistance and low smoke emission, making it suitable for high-performance insulation. Specialized construction projects requiring enhanced fire safety standards use phenolic foam.
Polyurethane Foam holds the largest share; momentum sits with Polyethylene Foam.
Application:
Application segments reflect distinct cost structures, ranging from high-volume, cost-sensitive packaging to performance-critical aerospace components.
- Thermal Insulation:Utilizes rigid polymer foams to reduce heat transfer in buildings, appliances, and industrial settings. Construction firms in Europe and North America drive demand due to government mandates for improved energy efficiency in new and renovated structures.
- Packaging Solutions:Employs flexible foams for cushioning, protection, and void fill, safeguarding goods during transit. E-commerce growth and the need for lightweight, recyclable materials in consumer goods sectors accelerate demand for these protective foams.
- Automotive Components:Involves using polymer foams for lightweighting, sound dampening, and comfort in vehicles. Vehicle manufacturers seek these foams for seating, headliners, and bumper cores to enhance fuel efficiency.
- Sports Equipment:Incorporates foams for impact absorption, buoyancy, and ergonomic design in various athletic gear. Manufacturers integrate polymer foams into protective padding, flotation devices, and footwear.
- Acoustic Panels:Utilizes open-cell foams to absorb sound and reduce noise pollution in commercial and residential spaces. Construction and interior design firms specify these panels for noise control in offices and studios.
Thermal Insulation applications command significant market volume, while Packaging Solutions are expanding most quickly.
End User Industry:
End user industry segmentation highlights the scale of material consumption, from mass-market construction to niche, high-specification aerospace.
- Construction Firms:Require large volumes of rigid polymer foams for thermal insulation, structural panels, and soundproofing in buildings. Government building codes in the US and Germany mandating improved thermal performance drive substantial demand for these materials.
- Furniture Makers:Utilize flexible polyurethane foams extensively for cushioning, support, and ergonomic design in seating and bedding. Consumer demand for comfort and durability, alongside design trends, influences material selection and foam density requirements.
- Consumer Electronics Manufacturers:Employ foams for packaging, vibration dampening, and component protection within electronic devices. These manufacturers demand lightweight, anti-static, and recyclable foam solutions for sensitive products.
- Marine Equipment Builders:Integrate buoyant and water-resistant foams into boat hulls, flotation devices, and insulation for marine vessels. Material properties like closed-cell structure and chemical resistance are critical for this industry.
- Aerospace Contractors:Specify high-performance, lightweight foams for insulation, structural components, and sound absorption in aircraft. Stringent safety standards and the constant drive for weight reduction dictate material choices.
Construction Firms represent the largest consumer base, with Furniture Makers showing consistent growth.
Form:
Form segmentation indicates where production capabilities are concentrated, from continuous sheet production to specialized on-site application systems.
- Rigid Foam:Characterized by a closed-cell structure and high compressive strength, primarily used for structural support and thermal insulation. Construction applications in Europe and China drive demand for these panels due to their energy efficiency benefits and structural integrity.
- Flexible Foam:Possesses an open-cell structure, offering elasticity, cushioning, and sound absorption properties. Furniture makers and automotive manufacturers in North America and Asia demand these foams for comfort and lightweight interior components.
- Spray Foam:Applied as a liquid that expands and hardens on site, providing seamless insulation and air sealing. Building contractors use spray foam for its excellent thermal performance and ability to fill irregular spaces.
- Molded Foam:Produced by injecting foam into a mold, creating custom shapes for specific product components. Automotive and furniture industries utilize molded foam for intricate parts like seating and armrests.
- Extruded Foam:Manufactured by continuously extruding a polymer melt, resulting in uniform closed-cell sheets or boards. Packaging and construction sectors use extruded foam for insulation and protective layers.
Rigid Foam accounts for the largest share of production volume, while Flexible Foam is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Eurasian rail network, alongside major global shipping lanes, underwrites the polymer foam market by facilitating the movement of petrochemical feedstocks and finished insulation products. Regional demand patterns vary significantly, driven by distinct regulatory landscapes and construction activity levels. This global infrastructure ensures efficient material flow across continents, supporting both high-volume commodity production and specialized foam distribution.
China
Demand for polymer foams in China is primarily driven by extensive infrastructure projects and the country's position as a manufacturing hub for commodity foams. China's MEE enforces stringent environmental protection laws on production facilities, influencing manufacturing processes and material choices. Industrial clusters within the Yangtze River Delta continue to concentrate large-scale commodity foam manufacturing operations, optimizing for volume and cost efficiency.
Germany
Germany's polymer foam market benefits from robust building energy efficiency mandates and a strong automotive sector focused on lightweighting. The EU's F-Gas Regulation imposes a strict phase-down schedule on HFCs, compelling foam producers to adopt next-generation blowing agents. North Rhine-Westphalia hosts significant chemical production capabilities, supplying advanced polyurethane foams for construction and specialized industrial applications.
United States
The United States sees consistent demand from its large residential and commercial construction sectors, alongside persistent automotive lightweighting initiatives. The US EPA sets standards for blowing agents to limit ozone depletion potential, directly impacting foam formulations. The Gulf Coast region, with its extensive petrochemical infrastructure, remains a critical hub for feedstock production essential for polymer foam manufacturing.
Japan
Japanese demand for polymer foams is concentrated in high-performance insulation for energy-efficient buildings and advanced materials for its sophisticated automotive industry. METI initiatives promote energy-saving technologies, stimulating the use of innovative foam solutions in construction and appliances. The Kanto region serves as a center for advanced material research and specialized foam manufacturing, catering to high-specification applications.
India
India's polymer foam market is expanding due to rapid urbanization, significant infrastructure development, and a growing furniture industry. The Bureau of Indian Standards (BIS) sets quality benchmarks for construction materials, including insulation foams, guiding product development. Maharashtra and Gujarat are emerging as key manufacturing regions, supporting domestic demand for both flexible and rigid foam products.
Polymer Foam Market Key Industry Players
Concentration sits with large, diversified chemical conglomerates that leverage extensive raw material production and broad distribution networks. The market exhibits a tiered structure, with a few global giants dominating primary chemical inputs, while a more fragmented landscape exists among specialized foam fabricators. These large players engage in significant capacity expansion to meet rising demand, particularly in construction and automotive sectors. Technology licensing and strategic partnerships also represent common competitive moves to access new markets and advanced material formulations.
Within the diversified chemical giants, BASF SE and Dow Inc. exemplify companies with vast chemical production capabilities, allowing them to supply a wide spectrum of polymer foam types to various end-user industries. Zotefoams plc occupies a position as a specialized high-performance foam innovator, focusing on niche applications requiring advanced material properties. These companies anchor different segments of the polymer foam market, from commodity volumes to highly engineered solutions.
| Leading Market Players |
|---|
| Owens Corning |
| Arkema Group |
| BASF SE |
| UFP Technologies |
| Sekisui Chemical |
| Huntsman Corporation |
| Armacell International |
| Zotefoams plc |
| Dow Inc. |
| Others |
Cost & Logistics Intelligence
Hydrofluoroolefin (HFO) blowing agent substitution for HFCs reshapes polymer foam supply geography and pricing economics. This shift reconfigures production investments and material cost structures for insulation foams.
Pricing Analysis
Volume-discount tiering structures dominate polymer foam pricing, particularly for large-scale construction and automotive contracts. Pricing primarily follows a contract-based long-term offtake model for high-volume segments, with differentiation stemming from material quality grades and procurement volume scale. Pricing pressure stems from feedstock price volatility, tied to crude oil and natural gas markets. Construction firms exhibit high price sensitivity, while aerospace contractors prioritize performance.
Supply Chain Analysis
Petrochemical production concentration in regions like the US Gulf Coast forms a critical chokepoint for polymer foam feedstocks. Geographic supply centers include China for commodity foams and Germany for advanced polyurethane materials. The industry draws heavily from petrochemical derivatives such as styrene, propylene, and toluene diisocyanate. Supply chain risk stems from fragmented chemical regulations like Europe's REACH, impacting material flow and cost. Distribution runs primarily through direct sales to large construction and automotive manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polymer foam market presents a material lifecycle management service-attach opportunity. Demand for certified recycled content and end-of-life solutions is expanding faster than core foam material sales.
For Market Incumbents: Fortify market leadership by investing in advanced recycling technologies, particularly for thermoset foams, to address circularity challenges. Secure long-term supply agreements for bio-based feedstocks to mitigate petrochemical price volatility and meet sustainability targets. This strategy counters the threat of stringent regulatory compliance burdens and evolving buyer preferences for circular materials. Prioritize R&D in next-generation blowing agents to maintain compliance with regulations like Europe's F-Gas.
For New Entrants and Emerging Players: Differentiate on certified sustainability credentials and advanced material performance. Target white-space opportunities in high-performance insulation, such as aerogels for cold chain logistics, or packaging solutions with high recycled content. The packaging segment, driven by e-commerce growth, offers a penetrable market for bio-based or chemically recycled foams. A go-to-market angle emphasizing verifiable circularity appeals to environmentally conscious end-users.
For Investors and Strategic Acquirers: The market sits at a transformative growth phase that favors specialized material innovators and circular economy enablers. Long-term viability hinges on the successful transition to sustainable feedstocks and advanced recycling capabilities. Acquisition targets should include companies with patented chemical recycling processes or unique bio-based foam formulations. A key signal to watch is the scaling of commercial chemical recycling facilities for thermoset polymer foams.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for HFO Foams | This initiative ensures compliance with Europe's F-Gas Regulation and supports demand for rigid insulation boards. |
| Investment in Chemical Recycling | This pathway addresses thermoset recycling challenges, enabling true circularity for polyurethane and polystyrene foams. |
| Bio-Based Feedstock Partnerships | These collaborations reduce reliance on volatile petrochemical derivatives and appeal to environmentally conscious end-users. |
| Certification for Recycled Content | Validated circularity through standards like mass balance accounting meets purchasing criteria in automotive and electronics. |
| R&D for Aerogel Composites | This research develops novel foam structures for ultra-high-performance insulation in cold chain logistics and aerospace. |
Research Approach
A spread of perspectives from R&D directors, automotive procurement leads, construction firm managers, and sustainability officers converged on the working assumptions for this polymer foam analysis. The methodology combined in-depth primary interviews with robust secondary validation from regulatory filings, industry association reports, and company annual reports. This approach employed both bottom-up and top-down triangulation to ensure comprehensive data accuracy.
The forecast framework modeled market dynamics across product type, application, end user industry, form, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected shifts in demand drivers over the analysis window. Key forecast inputs included petrochemical feedstock prices and anticipated updates to global building energy efficiency codes.
The analysis sits within stated boundaries; outcomes outside significant geopolitical events or accelerated regulatory shifts would require recalibration. Forecasts reflect assumptions concerning technological advancements and economic stability. Practitioners should keep alternative scenarios live as global trade policies and environmental mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Europe Epoxy Resins Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Vinyl Acetate Homopolymer Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Asia-Pacific Super Absorbent Polymers (SAP) Market
Polymers & Resins
Polymer Reinforcing Filler Market
Polymers & Resins
Global Cyclic Olefin Copolymers Market
Polymers & Resins
Rosin Resin Market
Polymers & Resins
Polysorbate Market
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Global Polyol and Polyurethane Market
Polymers & Resins
Polyethersulfone (PES) Market