
 Polyacrylamide Market | 2026-2036
Polyacrylamide Market Size, Share, and Industry Trends Forecast 2026-2036
Polyacrylamide Market Analysis
Municipal wastewater treatment operators are redrawing procurement priorities toward high-molecular-weight cationic grades for enhanced sludge dewatering efficiency. SNF Group leverages backward integration into acrylamide monomer production across its European and Asian manufacturing bases. BASF SE sustains technology leadership in anionic polyacrylamide formulations tailored to oilfield enhanced oil recovery. Kemira anchors its competitive position through geographic dominance in Nordic and North American pulp-and-paper chemical markets.
Polyacrylamide denotes a synthetic water-soluble polymer synthesized through free-radical polymerization of acrylamide monomer, typically achieving molecular weights between 10^6 and 2×10^7 Daltons depending on initiation chemistry and crosslinker content. Its primary industrial purpose centers on particle flocculation and liquid-solid separation across water treatment, oil recovery, and mineral processing operations. Cationic product types command premium positioning in municipal sludge dewatering where charge neutralization requirements are most stringent. Anionic grades lead volume consumption in oil and gas extraction, particularly for enhanced oil recovery in mature sandstone reservoirs. Powder and emulsion forms split manufacturing investment, with emulsion capacity expanding faster due to faster dissolution kinetics and reduced dust exposure in automated dosing systems.
EPA guidelines under the Safe Drinking Water Act and OSHA permissible exposure limits constrain residual acrylamide monomer content in potable water and workplace environments, directly elevating purification costs and certification requirements for manufacturers. ECHA REACH restrictions on acrylamide classification as a suspected carcinogen impose additional testing and registration burdens on European suppliers and importers. China's MEE discharge standards for industrial wastewater tighten allowable suspended solids thresholds, indirectly stimulating polymer consumption across manufacturing zones. Stakeholders must monitor evolving monomer regulations across multiple jurisdictions while evaluating bio-based acrylamide substitutes that could disrupt conventional petrochemical supply chains.
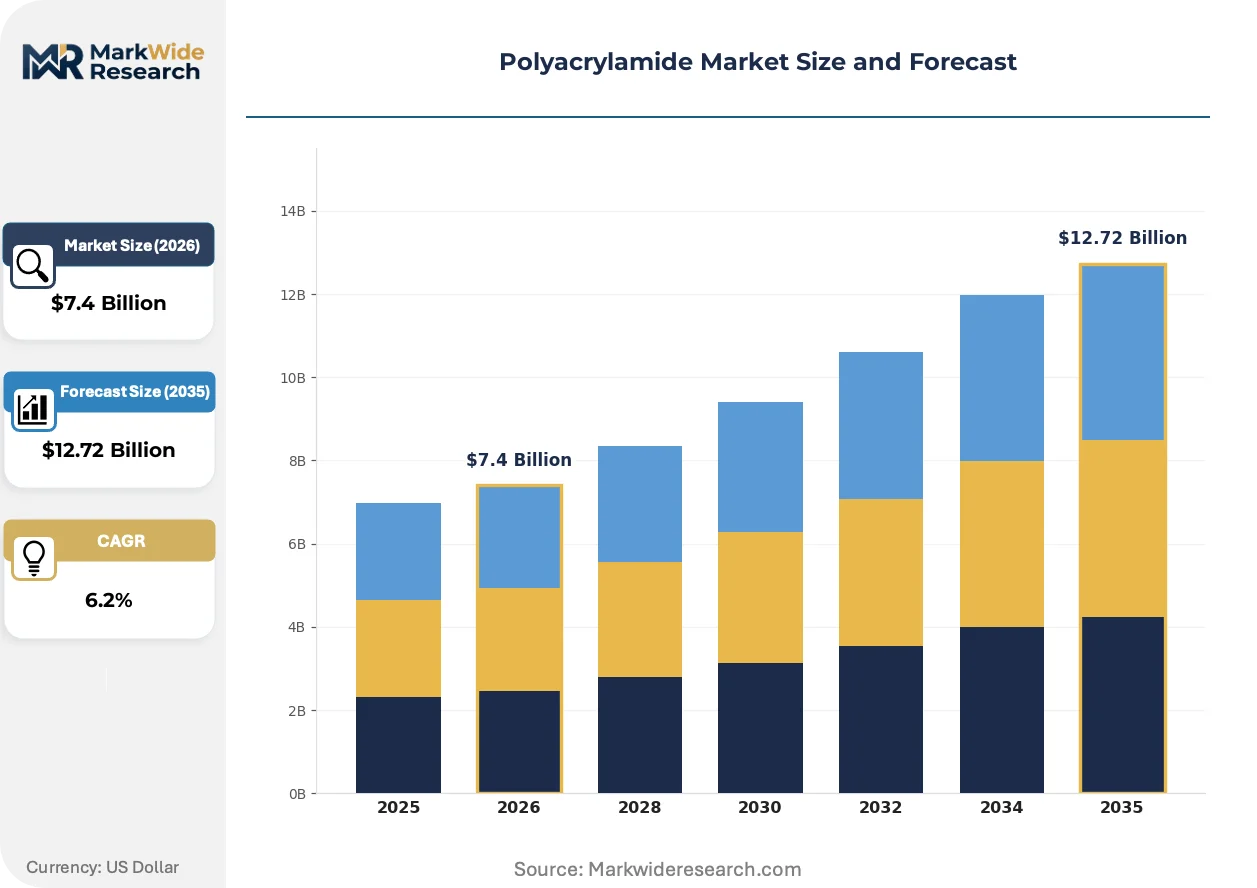
Market Dynamics
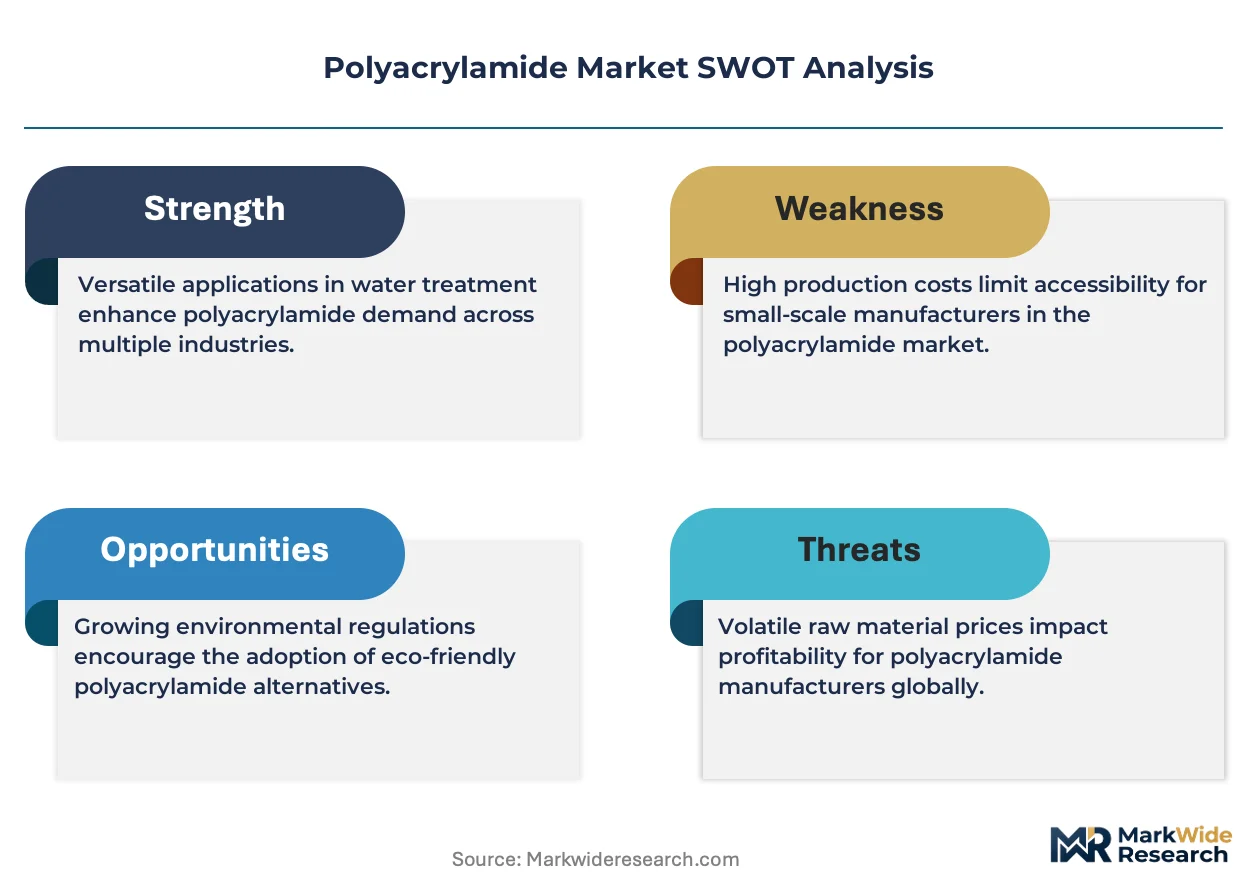
Acrylamide monomer purification costs and ECHA REACH classification pressures are compressing margins for non-integrated polyacrylamide manufacturers while rewarding producers with captive acrylamide supply chains.
Growth Catalysts
- MEE discharge standards:China's tightened suspended solids thresholds for industrial wastewater are accelerating polymer dosing across manufacturing zones in Shandong and Jiangsu provinces.
- Municipal sludge dewatering:Wastewater utilities in Germany and France are upgrading to high-molecular-weight cationic grades to reduce disposal volumes and transportation costs.
- Enhanced oil recovery:Mature sandstone reservoirs in Texas and North Dakota require anionic polyacrylamide for polymer flooding to maintain production rates.
Market Restraints
- Acrylamide monomer supply concentration:Integrated production corridors in China's Shandong province create geographic dependency risk for European and North American formulators lacking backward integration.
- ECHA carcinogen classification:REACH restrictions on acrylamide as a suspected carcinogen impose registration burdens and testing costs that disproportionately affect small European importers.
- Petrochemical feedstock volatility:Propylene and ammonia price swings directly impact acrylamide production economics, squeezing margin predictability for non-hedged manufacturers.
Strategic Opportunities
- Bio-based acrylamide pathways:Fermentation-derived acrylamide from agricultural feedstocks offers defossilization positioning ahead of EU Green Deal chemical sector targets.
- Emulsion form expansion:Automated dosing systems in Dutch and Belgian water treatment facilities favor faster-dissolving emulsion products over powder alternatives.
- Pulp-and-paper retention aids:Nordic mills are reformulating with specialized anionic grades to meet tightening effluent quality standards while maintaining production speeds.
Industry Challenges
- Residual monomer certification timelines:EPA Safe Drinking Water Act compliance testing for potable water grades extends product launch cycles by 12-18 months.
- Polymer characterization skill gaps:Molecular weight distribution analysis and charge density optimization require specialized analytical chemists in short supply across the US Gulf Coast chemical corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyacrylamide Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Ionic, Anionic, Cationic, Amphoteric End User: Water Treatment, Oil & Gas, Agriculture, Paper Manufacturing Application: Flocculant, Thickener, Stabilizer, Dispersant Form: Powder, Liquid, Emulsion, Granules |
| Companies Covered | SNF Group, BASF SE, Kemira, Anhui Jucheng Fine Chemicals Co., Ltd, Ashland Inc., Solenis, China National Petroleum Corporation, Xitao Polymer Co., Ltd, Shandong Polymer Bio-chemicals Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyacrylamide Market Emerging Trajectories
Polyacrylamide formulation science is pivoting toward rapid-dissolution architectures and bio-based feedstock pathways as regulatory pressure on petrochemical acrylamide intensifies across multiple jurisdictions.
Structured polymer architectures with controlled branching are displacing conventional linear chains in high-shear dewatering applications. Municipal sludge processors in the Netherlands and Germany are adopting these grades to achieve drier cake solids without dosage escalation. The technology is displacing legacy high-molecular-weight linear polymers in European municipal procurement specifications.
REACH authorization requirements for acrylamide monomer are tightening purity thresholds for potable water contact applications. European manufacturers face elevated analytical and documentation burdens to maintain market access. Cationic grades for drinking water treatment are bearing the heaviest compliance load, with some suppliers exiting the certification pathway entirely.
Specification-driven procurement is consolidating buyer power among large municipal utilities and oilfield service companies. Long-term framework agreements with volume commitments are replacing spot purchasing for standard anionic and cationic grades. This concentration is most pronounced in North American enhanced oil recovery chemical supply, where operators demand integrated service packages spanning product, dosing equipment, and technical support.
Polyacrylamide Market Segmentation
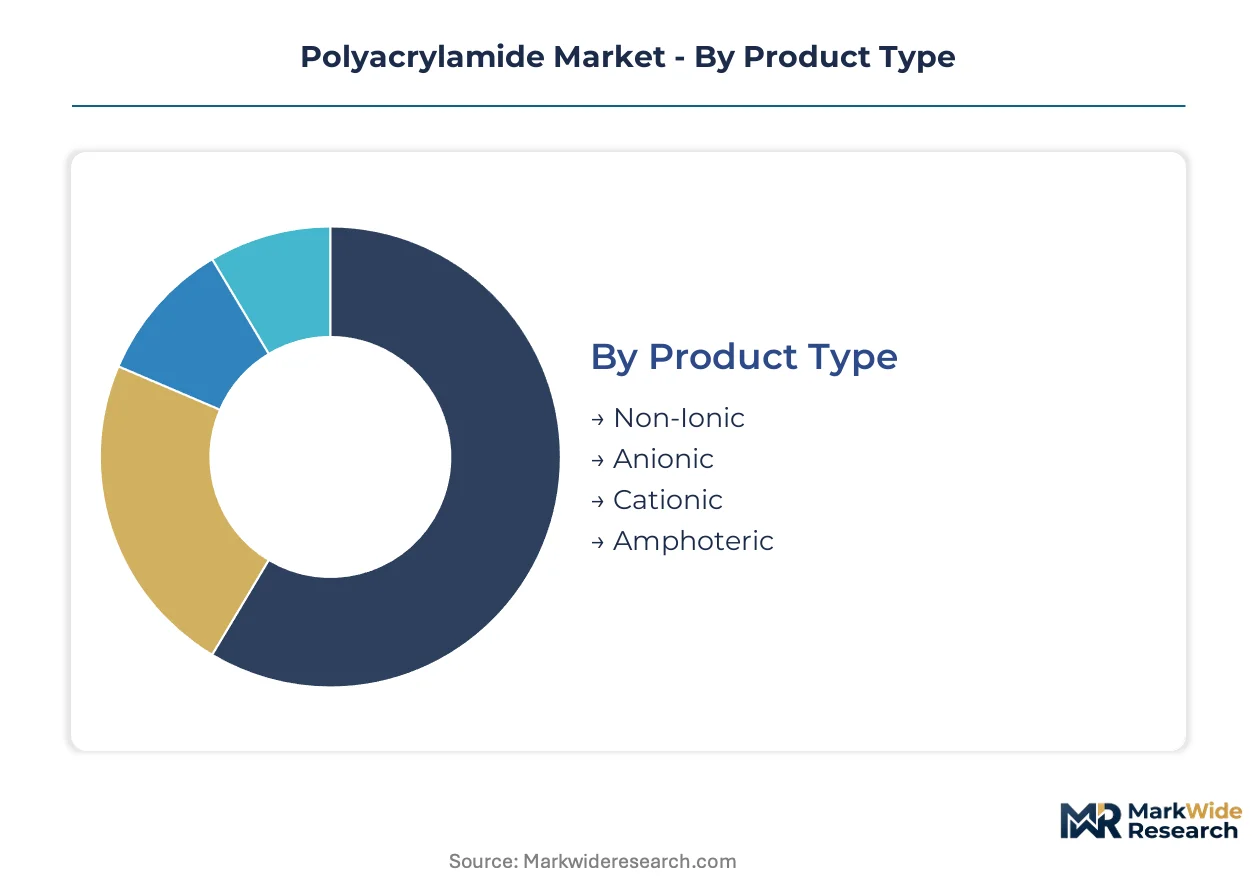
Polyacrylamide demand fragments across charge chemistry, physical form, and end-use specifications that dictate regional production footprints and export flows. Understanding these segment boundaries clarifies why integrated manufacturers in Shandong province dominate certain grades while European specialists retain pockets of technology leadership.
Product Type:
Export intensity varies sharply across charge categories, with anionic grades feeding global oilfield supply chains and cationic production clustering near municipal wastewater demand centers.
- Anionic:Carries negative charge density from hydrolyzed acrylamide units, typically deployed in mineral processing tailings and enhanced oil recovery. Texas and North Dakota oilfield operators specify high-molecular-weight variants for polymer flooding in mature sandstone reservoirs, creating transatlantic supply dependencies on Chinese manufacturing bases.
- Cationic:Incorporates quaternary ammonium functionality for charge neutralization of negatively charged organic solids. German and French municipal utilities drive specification tightening for sludge dewatering applications, favoring producers with REACH-compliant monomer purification capabilities.
- Non-Ionic:Uncharged homopolymer structures serving specialty mining and construction applications where ionic interference must be minimized.
- Amphoteric:Dual-charge architectures combining anionic and cationic moieties for complex wastewater matrices with variable pH and contaminant loads.
Anionic polyacrylamide commands the established base. The steepest expansion runs through cationic grades as European utilities upgrade dewatering infrastructure.
End User:
Customer scale and procurement sophistication create tiered margin structures, with oilfield service companies demanding integrated service packages and agricultural buyers prioritizing cost-per-hectare economics.
- Water Treatment:Municipal utilities and industrial effluent plants represent the volume anchor, with procurement consolidating around framework agreements covering polymer, dosing equipment, and technical support. China's MEE discharge standards tighten suspended solids thresholds across Shandong and Jiangsu manufacturing zones, stimulating dosing system upgrades.
- Oil & Gas:Enhanced oil recovery operations in Permian and Bakken formations require anionic grades with precise molecular weight distributions for reservoir conformance control. Operators specify integrated chemical service contracts spanning product supply, injection skids, and performance monitoring.
- Agriculture:Soil conditioning and irrigation efficiency applications favor lower-specification grades where price sensitivity limits premium positioning.
- Paper Manufacturing:Nordic mills reformulate retention and drainage aids to meet tightening effluent quality standards while maintaining production speeds, creating demand for specialized anionic variants.
Water treatment commands the established base. The steepest expansion runs through oil and gas as North American operators extend polymer flooding programs.
Application:
Functional performance requirements determine form factor selection and dissolution kinetics specifications, with automated dosing systems favoring rapid-hydration architectures.
- Flocculant:Particle aggregation mechanism relies on polymer bridging and charge neutralization. Dutch and Belgian water treatment facilities specify emulsion-based cationic flocculants for automated dosing systems requiring fast dissolution without dust exposure.
- Thickener:Viscosity-building applications in mining and construction demand precise molecular weight control to achieve target rheology without overdosing.
- Stabilizer:Colloidal suspension maintenance in drilling fluids and cosmetics requires low residual monomer certification under EPA Safe Drinking Water Act guidelines.
- Dispersant:Particle separation functionality in pigment and ceramic processing competes with alternative chemistries on cost-performance metrics.
Flocculant applications command the established base. The steepest expansion runs through thickener demand as mining operators optimize tailings management.
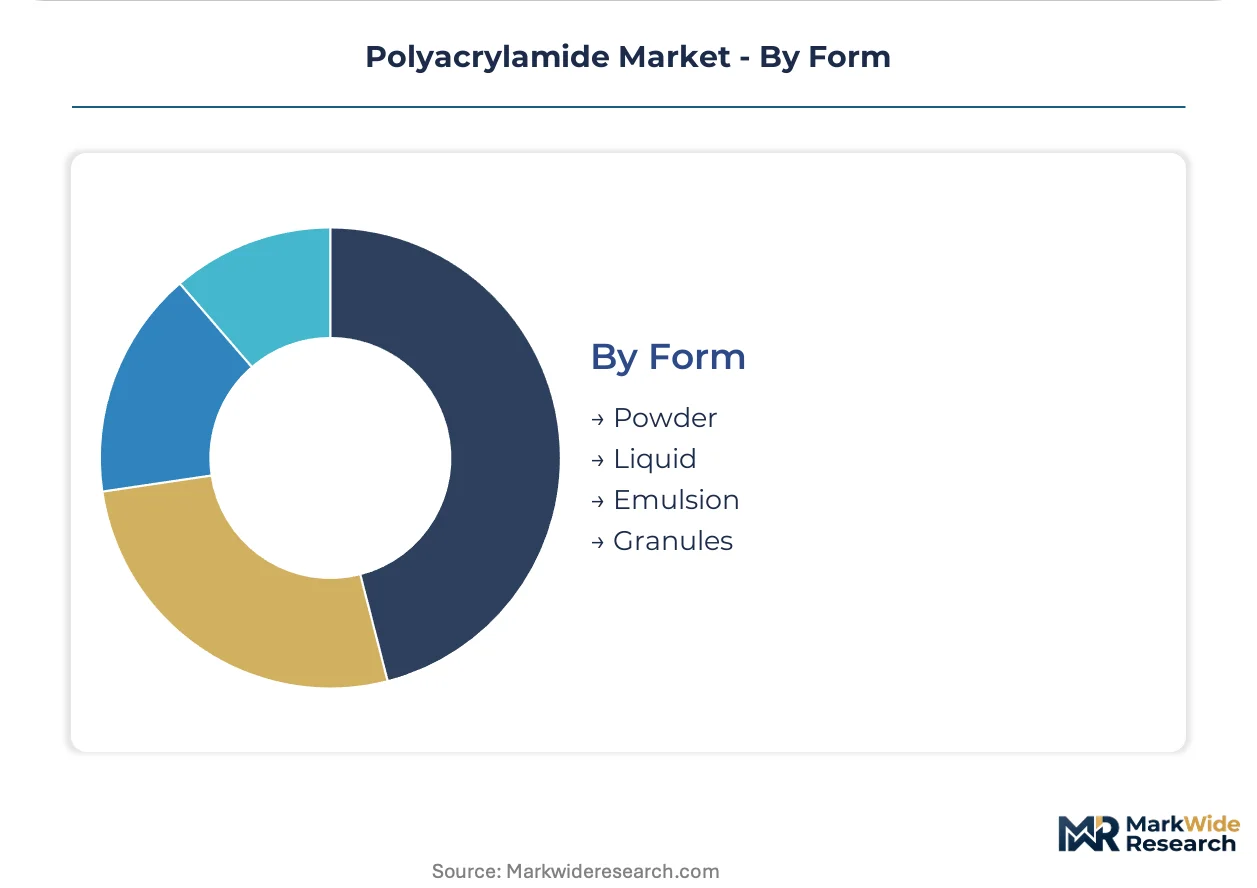
Form:
Manufacturing capital allocation tilts toward emulsion capacity as automation penetration rises in European and North American treatment facilities.
- Emulsion:Inverse-phase dispersion of polymer in hydrocarbon carrier enables rapid dissolution kinetics and reduced dust exposure. Automated dosing installations in Netherlands and Belgium specify emulsion exclusively for occupational health compliance.
- Powder:Spray-dried granules retain cost advantage in bulk mining and agricultural applications where manual handling persists and dissolution time is less critical.
- Liquid:Pre-hydrated solutions serve niche applications requiring immediate availability without dissolution equipment.
- Granules:Controlled-particle-size agglomerates bridge powder and emulsion performance characteristics for mid-tier water treatment specifications.
Powder forms command the established base. The steepest expansion runs through emulsion as automated dosing infrastructure proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao port complex in Shandong province anchors Asia-Pacific polyacrylamide trade flows, handling bulk acrylamide monomer imports and finished polymer exports to oilfield service companies across the Middle East and North America.
China
Shandong province hosts integrated acrylamide-polyacrylamide production corridors serving domestic oil recovery and water treatment demand. MEE discharge standards tighten suspended solids thresholds across manufacturing zones in Shandong and Jiangsu, accelerating polymer dosing system upgrades. Zibo and Dongying chemical clusters concentrate backward-integrated capacity that supplies both domestic utilities and export markets.
United States
Permian Basin and Bakken formation operators specify high-molecular-weight anionic grades for polymer flooding in mature sandstone reservoirs. EPA Safe Drinking Water Act guidelines constrain residual acrylamide monomer content in potable water applications, extending certification timelines for new product launches. Houston-Galveston chemical corridor hosts formulators serving North American oilfield and municipal utility procurement.
Germany
Rhine-Ruhr industrial belt utilities upgrade to high-molecular-weight cationic grades for sludge dewatering efficiency and disposal cost reduction. ECHA REACH restrictions on acrylamide classification as suspected carcinogen impose registration burdens and analytical documentation requirements. Ludwigshafen chemical complex maintains technology leadership in specialized anionic formulations.
Netherlands
Rotterdam port infrastructure enables acrylamide monomer import flows from Asian manufacturing bases to European formulators. Dutch water treatment facilities specify emulsion-based cationic flocculants for automated dosing systems requiring fast dissolution and occupational health compliance. Randstad industrial corridor concentrates procurement consolidation among large municipal utilities.
Saudi Arabia
Eastern Province oilfields require anionic polyaclamide for enhanced oil recovery in carbonate reservoir conditions distinct from North American sandstone geology. National water treatment expansion programs stimulate polymer consumption for industrial effluent and municipal wastewater applications. Jubail industrial city hosts downstream formulation capacity serving regional oilfield service demand.
Polyacrylamide Market Vendor Landscape
Concentration sits with integrated petrochemical conglomerates and specialized water treatment chemical suppliers. The vendor base spans three tiers: backward-integrated monomer producers, regional formulation specialists, and oilfield service-integrated suppliers. Two strategic archetypes dominate competitive positioning—captive acrylamide producers leveraging cost structure advantages, and application-technology specialists commanding premium positioning through formulation expertise. Capacity expansion in Shandong province and REACH compliance investments in Europe represent the primary competitive moves reshaping supplier economics.
Among integrated chemical conglomerates, BASF SE and SNF Group exemplify divergent geographic strategies while occupying comparable archetype positions. Kemira anchors the Nordic-North American pulp-and-paper chemical corridor. Chinese specialists including Anhui Jucheng Fine Chemicals Co., Ltd and Shandong Polymer Bio-chemicals Co., Ltd represent the regional formulation tier serving domestic demand and export markets. Xitao Polymer Co., Ltd occupies a position within the Shandong production corridor. These named entities illustrate how competitive positioning fragments across integration depth, geographic footprint, and end-use specialization rather than consolidating around unified global leadership.
| Leading Market Players |
|---|
| SNF Group |
| BASF SE |
| Kemira |
| Anhui Jucheng Fine Chemicals Co., Ltd |
| Ashland Inc. |
| Solenis |
| China National Petroleum Corporation |
| Xitao Polymer Co., Ltd |
| Shandong Polymer Bio-chemicals Co., Ltd |
| Others |
Supply Flow & Price Mechanics
Long-term framework agreements with volume commitments lock in supply access for municipal utilities and oilfield operators while anchoring price visibility against propylene and ammonia feedstock swings. These contracts concentrate procurement power among large buyers in Germany, Texas, and China's Shandong province, squeezing margin flexibility for non-integrated formulators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified potable water grades from industrial flocculants and bulk mining specifications. Price differentiation rests on monomer purity certification and molecular weight distribution precision, with cationic grades for municipal sludge dewatering commanding the widest spreads. Pricing pressure stems from acrylamide monomer purification cost escalation under tightening EPA and ECHA thresholds. Agricultural buyers exhibit the highest price sensitivity, while oilfield service companies prioritize performance guarantees over per-kilogram economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate European and North American formulators dependent on Asian monomer flows, while strategic stockpiling characterizes integrated producers in Shandong province. Supply concentrates in China, Germany, and the United States, with raw material flows drawing from propylene derivatives and ammonia feedstocks. Single-source vulnerability runs through Shandong's integrated production corridors, where SNF Group and domestic manufacturers control acrylamide-polyacrylamide conversion. Distribution runs through Rotterdam and Qingdao port complexes for transatlantic and Middle Eastern oilfield supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyacrylamide competitive structure fragments across integration depth and certification tiers, creating white-space openings as REACH and EPA compliance burdens force supplier exits from potable water grades.
For Market Incumbents: Shield market position in cationic municipal grades by accelerating REACH-compliant monomer purification investments before ECHA authorization timelines tighten. Deepen backward integration into acrylamide production across European manufacturing bases to offset feedstock volatility. Prioritize emulsion capacity expansion in the Netherlands and Belgium where automated dosing infrastructure proliferation favors rapid-dissolution architectures over legacy powder forms.
For New Entrants and Emerging Players: EPA Safe Drinking Water Act certification fast-tracks offer entry pathways into specialized potable water flocculant tiers where incumbent exits concentrate demand. Target Nordic pulp-and-paper retention aid segments with customized anionic grades as mills reformulate for effluent compliance. Pursue bio-based acrylamide fermentation partnerships to position ahead of EU Green Deal chemical sector defossilization targets.
For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated mid-cap specialists with captive Shandong corridor access and established oilfield service relationships. Long-term viability hinges on regulatory compliance infrastructure rather than commodity volume scale. Watch for ECHA acrylamide reclassification decisions as the inflection signal accelerating consolidation among European formulators lacking purification capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylamide Monomer | Captive supply from Shandong chemical clusters insulates margin structures against propylene volatility. |
| Emulsion Capacity Expansion | Rotterdam-area investments capture Dutch and Belgian automated dosing system procurement. |
| REACH Certification Fast-Track | Accelerated ECHA registration timelines secure potable water grade market access before competitor exits. |
| Bio-Based Acrylamide Pathway Development | Fermentation-derived feedstock positioning aligns with EU Green Deal chemical sector decarbonization mandates. |
| Long-Term Supply Agreement with Municipal Utilities | Framework contracts with German and French wastewater operators lock in volume against spot market erosion. |
Methodological Framework
A spread of perspectives from polymer plant managers, municipal procurement leads, oilfield chemical service directors, and ECHA regulatory affairs specialists converged on the working assumptions shaping demand trajectories. Primary fieldwork combined structured interviews across Shandong manufacturing corridors, Houston-Galveston formulator networks, and Rhine-Ruhr utility procurement departments with secondary validation from customs trade data, SEC chemical sector filings, and MEE discharge standard documentation. Bottom-up segment sizing triangulated against top-down macro chemical consumption patterns.
Segmentation dimensions modeled span charge chemistry tiers, physical form factors, end-use industry verticals, and regional production hub clusters across the analysis window. CAGRs derived from regression against historical polymer dosing intensity in wastewater treatment and enhanced oil recovery applications, with cross-checks against acrylamide monomer capacity expansion announcements and REACH registration timelines. Industry-specific inputs incorporated MEE suspended solids threshold enforcement schedules and EPA Safe Drinking Water Act certification pipeline data.
The analysis sits within stated boundaries; outcomes outside sustained oilfield capital expenditure levels or accelerated ECHA acrylamide reclassification would require recalibration. Forecasts assume continued propylene feedstock availability and stable tariff structures for Chinese-origin monomer imports. Revision becomes warranted when bio-based acrylamide pathway economics cross cost-competitive thresholds against petrochemical routes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyamide-Imide Resin Market
Polymers & Resins
Germany Engineering Plastics Market
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Hybrid Polymer Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Resin Dispersion Market
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
Nylon 4-6 Market
Polymers & Resins
Cross-Linked Polyethylene (XLPE) Market
Polymers & Resins
Polycyclohexylenedimethylene Terephthalate (PCT) Market
Polymers & Resins
Asia-Pacific Polyamide Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market