
 Global Polyethylene Market | 2026-2036
Global Polyethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyethylene Market Outlook
Project finance tied to cracker-to-polymer integrated complexes is reconfiguring competitive entry barriers across the polyethylene value chain. SABIC leverages its feedstock access in Saudi Arabia to sustain cost leadership in bulk HDPE exports. Dow Inc. anchors its position through proprietary solution-phase LLDPE technology that commands premium positioning in flexible packaging grades.
Polyethylene denotes a thermoplastic polymer synthesized from ethylene monomer through catalytic polymerization, with density ranging from 0.91 to 0.97 g/cm³ depending on branching architecture and crystallinity. The material functions primarily as a barrier layer, structural component, or protective coating across packaging, construction, and durable goods manufacturing. HDPE dominates volume flows into rigid containers and pipe applications where stiffness and chemical resistance justify material selection. LLDPE captures expanding share in stretch wrap and heavy-duty sacks as downgauging requirements intensify. UHMWPE occupies a specialized niche in orthopedic implants and ballistic protection where extreme molecular weight delivers abrasion resistance beyond conventional grades.
The EPA regulates volatile organic compound emissions from polyethylene resin production under Clean Air Act provisions, while REACH mandates registration and hazard communication for imported polymer formulations entering European downstream channels. China's MEE enforces dual carbon goals that constrain new steam cracker approvals and redirect investment toward bio-based feedstock pilots. FDA food-contact notifications and EU EFSA compliance requirements determine which additive packages qualify for flexible packaging serving regulated consumer categories. Stakeholders must monitor how divergent recycling infrastructure investments across Germany, Japan, and the United States reshape specifications for post-consumer recycled content mandates.
Market Dynamics
Mechanical recycling integration is forcing polyethylene producers to reconfigure additive packages and certify post-consumer recycled content for EU Green Deal compliance, while Southeast Asian e-commerce fulfillment tightens specifications for downgauged LLDPE films.
Growth Catalysts
- EU Green Deal compliance mandates:REACH chemical safety protocols pressure producers to reformulate additive packages, accelerating mechanical recycling adoption across European downstream channels.
- E-commerce fulfillment specifications:Flexible packaging converters in Vietnam, Indonesia, and Thailand are expanding orders for LLDPE films as last-mile delivery requirements tighten.
- Port-proximate converting clusters:Downstream capacity concentration near Rotterdam, Singapore, and Houston infrastructure reduces logistics friction for bulk resin offtake.
Market Restraints
- Ethylene feedstock volatility:Naphtha and ethane price swings compress margins for non-integrated producers lacking captive cracker access.
- Steam cracker approval constraints:China's MEE dual carbon goals limit new capacity additions, restricting supply expansion in the world's largest demand center.
- Polypropylene substitution in rigid containers:Improved clarity and processing economics in random copolymer grades displace HDPE in select food packaging segments.
Strategic Opportunities
- India packaging demand acceleration:FSSAI food-contact regulations and organized retail expansion create pull for certified flexible film grades in Mumbai and Delhi NCR corridors.
- Bio-based feedstock pilots:Naphtha-to-ethylene pathways using renewable feedstocks qualify for EU ETS advantages and brand-owner sustainability commitments.
- Digital inventory platforms:Resin procurement through B2B marketplaces disintermediates traditional distributor networks, reducing working capital cycles for mid-sized converters.
Industry Challenges
- Polymer certification timeline compression:FDA food-contact notification reviews and EU EFSA compliance dossiers delay new additive package commercialization by 18-24 months.
- Recycling stream contamination control:Multi-layer flexible packaging designs complicate mechanical recycling yields, requiring capital-intensive compatibilizer investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyethylene Market |
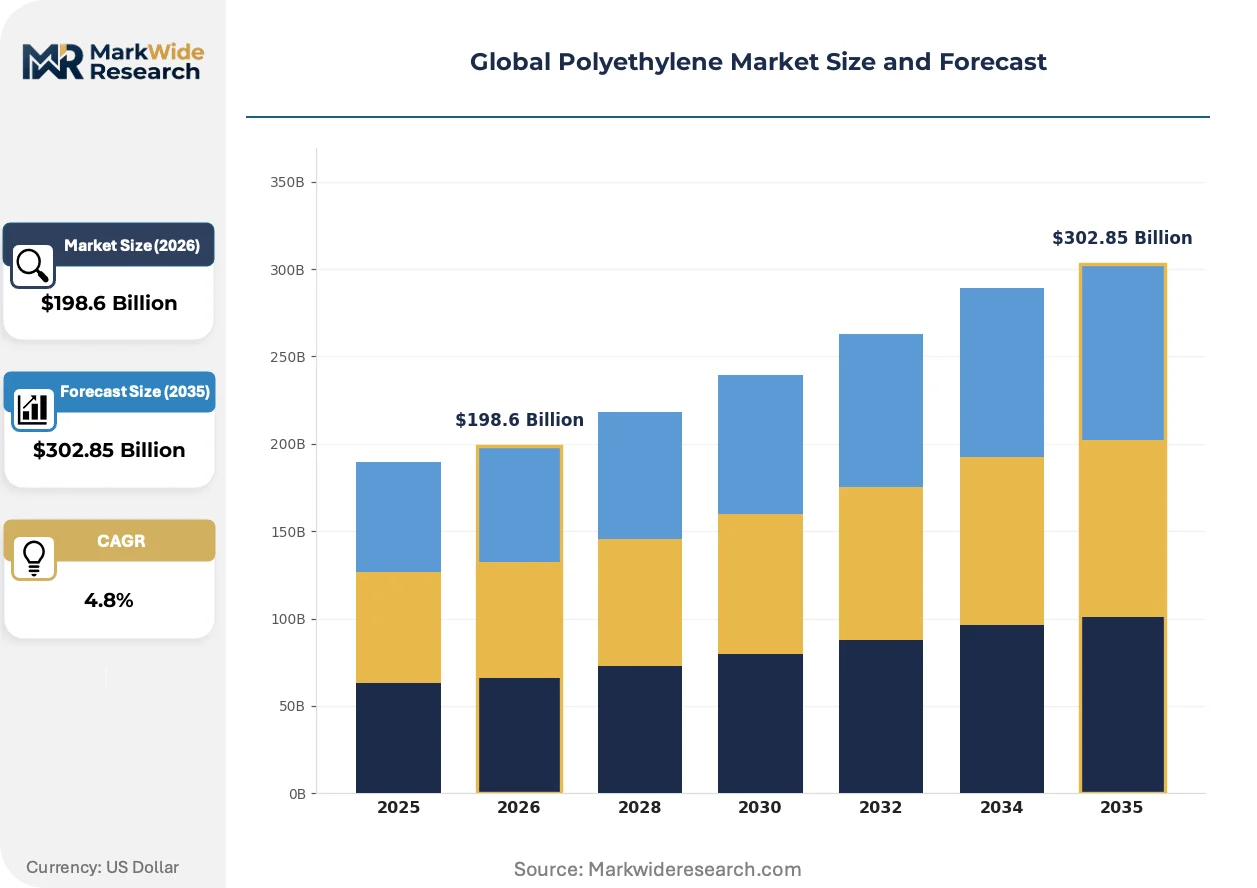
| Market Size in 2026 | $198.6 Billion |
| Market Size in 2035 | $302.85 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDPE, LDPE, LLDPE, UHMWPE Application: Packaging, Automotive, Consumer Goods, Textiles End User: Construction, Electronics, Healthcare, Agriculture Form: Granules, Films, Sheets, Coatings |
| Companies Covered | SABIC, BASF SE, ExxonMobil Chemical, Chevron Phillips Chemical, Braskem, Dow Inc., INEOS, Borealis AG, LyondellBasell Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyethylene Market Strategic Shifts
Digital twin technology is virtualizing production optimization across the polyethylene value chain, while regulatory chemistry disclosure requirements and procurement platform adoption reshape competitive access to downstream segments.
Advanced process control systems using real-time reactor modeling are virtualizing yield optimization and energy intensity reduction. Dow Inc. and SABIC deploy these platforms across solution-phase and gas-phase assets respectively. The technology is virtualizing traditional technical service relationships, compressing the value captured by standalone engineering consultancies.
REACH Article 33 substance-of-very-high-concern disclosure obligations now extend to imported polymer formulations entering European converting channels. Downstream buyers demand full additive package transparency to satisfy extended producer responsibility schemes. Flexible packaging serving regulated consumer categories faces the steepest compliance burden, with converters in Germany and France leading certification investments.
Resin procurement through integrated B2B platforms is displacing phone-and-fax distributor relationships among mid-sized Southeast Asian converters. Vietnam and Indonesia-based film producers now compare real-time pricing across multiple suppliers, compressing traditional margin structures for regional distributors. The shift is most visible in LLDPE and LDPE spot transactions, where port-proximate inventory visibility reduces emergency procurement premiums.
Global Polyethylene Market Segmentation
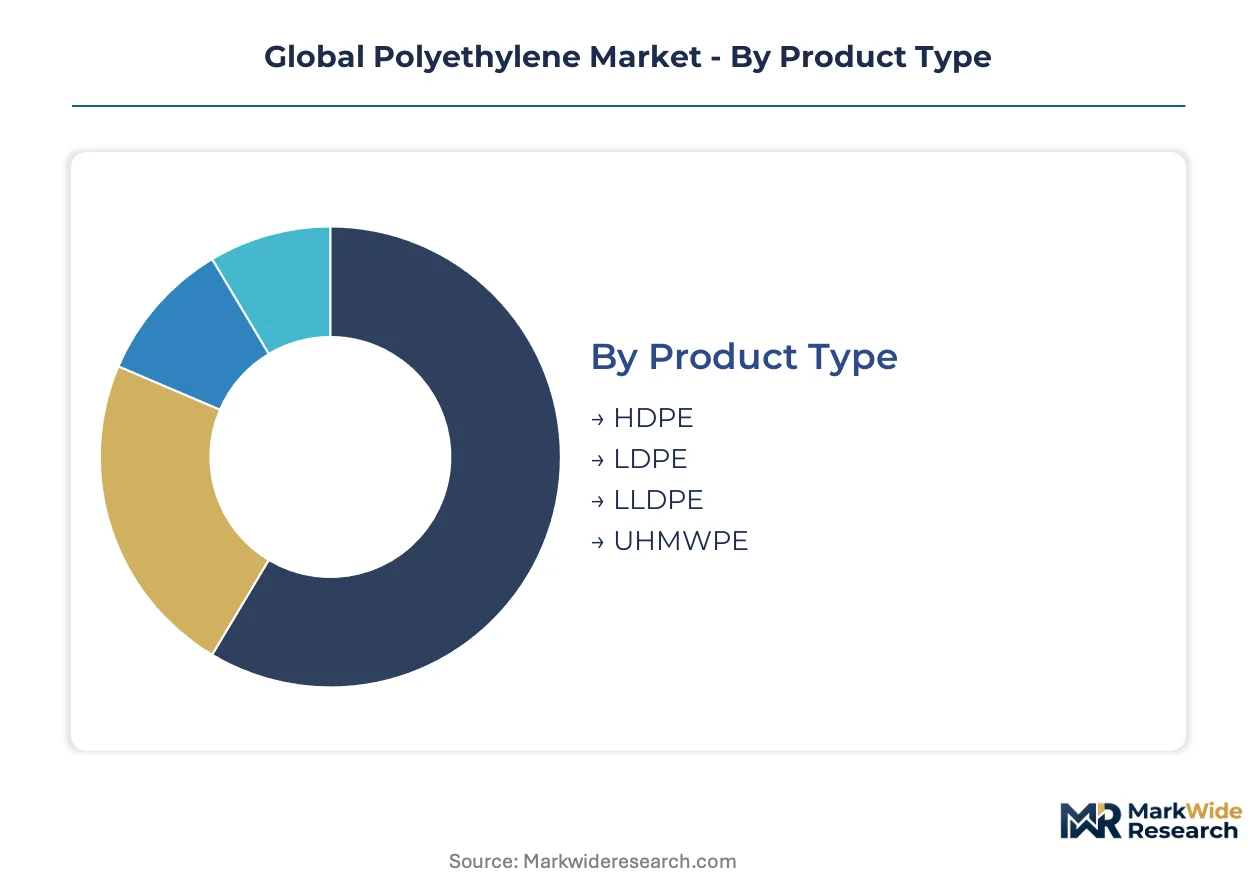
Polyethylene segmentation reveals how molecular architecture and processing form determine pricing power and customer lock-in. Producers configure product portfolios across density grades and physical forms to capture value from packaging converters, automotive tier suppliers, and construction material fabricators.
Product Type:
Mature commodity grades dominate volume flows while ultra-high molecular weight variants occupy defensible specialty positions.
- HDPE:Linear polymer chains with minimal branching yield density between 0.941 and 0.965 g/cm³. Blow-molded containers for milk and detergent in Germany and France absorb substantial European volume as EFSA compliance requirements tighten additive specifications.
- LLDPE:Copolymerized with butene or hexene to introduce controlled short-chain branching. Stretch film demand from Vietnam and Indonesia e-commerce fulfillment centers is compressing gauge specifications and accelerating orders for metallocene-catalyzed grades.
- LDPE:High-pressure radical polymerization produces extensive long-chain branching for clarity and processability. Food packaging film extruders in Mumbai and Delhi NCR corridors pull significant Indian imports.
- UHMWPE:Molecular weights exceeding 3 million g/mol deliver abrasion resistance for orthopedic implants and ballistic armor. Medical device manufacturers in Switzerland and the United States qualify suppliers through extended FDA and Swissmedic validation protocols.
HDPE retains volume leadership; UHMWPE holds the steepest expansion curve.
Application:
Application segmentation tracks how end-use performance requirements reshape procurement specifications and certification burdens.
- Packaging:Barrier layers and structural films account for the dominant demand share. Flexible converters in Thailand and Indonesia face EU Green Deal pressure to certify recycled content percentages.
- Automotive:Fuel tanks, bumper fascias, and interior trim specify HDPE and PP blends. Tier suppliers near Stuttgart and Toyota City qualify resins through OEM-specific emission and durability protocols.
- Consumer Goods:Durable housewares and toys favor HDPE stiffness and chemical resistance. Injection molders in Dongguan and Yuyao optimize cycle times through nucleated grade selection.
- Textiles:Monofilament and tape applications for woven sacks and geotextiles. Agricultural netting producers in São Paulo specify UV-stabilized grades for tropical exposure conditions.
Packaging commands the largest revenue pool; automotive applications are climbing the fastest on lightweighting mandates.
End User:
End user segmentation exposes how regulatory intensity varies across downstream verticals and reshapes supplier qualification timelines.
- Construction:Pipe, geomembrane, and insulation applications specify HDPE for hydrostatic stress resistance. Infrastructure contractors in Texas and Alberta source certified resin for pressure-rated municipal water systems.
- Electronics:Cable jacketing and semiconductor processing components demand clean-room compatible grades. Singapore and Penang-based fabs enforce ionic contamination limits below 10 ppm.
- Healthcare:Pharmaceutical packaging and medical devices trigger FDA and EMA validation requirements. Blow-fill-seal bottle producers in Ireland and North Carolina maintain drug master file registrations.
- Agriculture:Greenhouse films, silage wrap, and irrigation tubing expose material to UV and pesticide contact. Coextruded structures with EVA outer layers dominate Spanish and Italian horticultural markets.
Construction anchors volume demand; healthcare delivers the highest margin realization per ton.
Form:
Physical form determines logistics economics and converter capital requirements across the value chain.
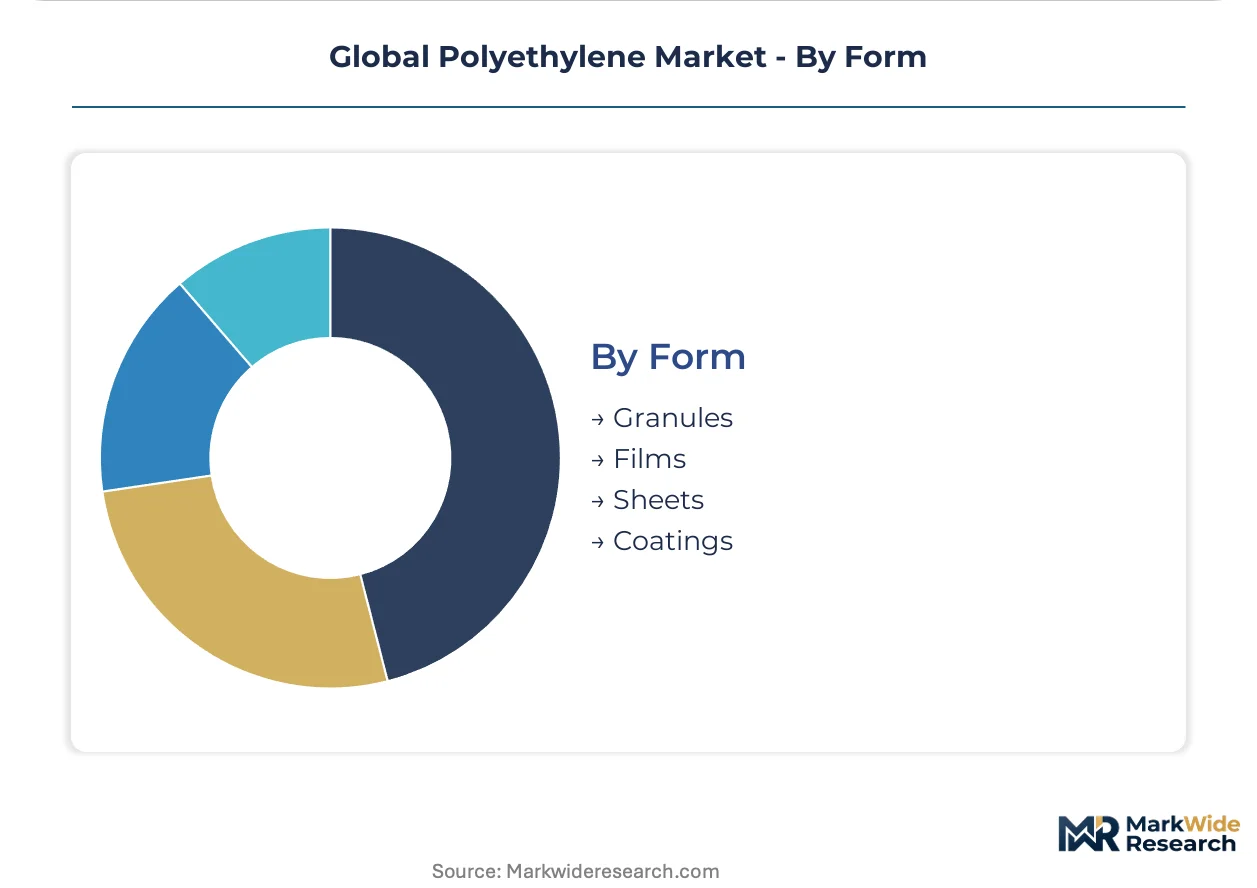
- Granules:Standard pellet form for injection molding and extrusion. Compounders in Rotterdam and Houston bulk-handle railcar quantities with automated pneumatic conveying.
- Films:Pre-extruded sheet and blown film for direct converting. Vietnamese flexible packaging mid-caps increasingly procure finished film rather than resin to bypass extruder capital constraints.
- Sheets:Thick-gauge thermoforming and fabrication feedstock. Signage and industrial tray producers in Ontario and Ohio specify custom width and surface finish.
- Coatings:Powder and liquid dispersions for substrate protection. Pipeline corrosion protection contractors in Saudi Arabia and Kazakhstan apply fusion-bonded epoxy systems.
Granules retain volume leadership; films are expanding most quickly on downstream outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across major polyethylene markets. Saudi Arabia and the United States maintain structural export surpluses through ethane cost advantages, while China and Europe absorb substantial import volumes to cover domestic demand shortfalls. Southeast Asian converting clusters are reshaping regional trade flows as downstream capacity concentrates near port infrastructure.
United States
Gulf Coast steam crackers supply HDPE and LLDPE exports to Latin America and Europe. EPA Clean Air Act enforcement tightens emission controls on Texas and Louisiana production assets. Houston-area bulk terminals handle railcar-to-vessel transfers for resin bound for Brazilian and Mexican converters.
China
Domestic consumption outpaces local cracker output despite massive capacity additions. MEE dual carbon goals restrict new steam cracker approvals and redirect investment toward bio-based feedstock pilots. Yangtze River Delta processors in Zhejiang and Jiangsu provinces import premium grades for flexible packaging applications.
Germany
REACH Article 33 disclosure obligations pressure converters to certify additive package transparency for flexible packaging. EFSA compliance requirements tighten specifications for food-contact grades serving blow-molded container markets. Rhine-Ruhr industrial corridor compounders qualify resin through extended OEM validation protocols.
Saudi Arabia
SABIC leverages feedstock access to sustain cost leadership in bulk HDPE exports to Asia and Africa. The country's national industrial development program prioritizes downstream derivative investments over raw resin expansion. Jubail industrial city hosts integrated cracker-to-polymer complexes serving export markets.
Vietnam
E-commerce fulfillment centers in Ho Chi Minh City and Hanoi accelerate orders for downgauged LLDPE stretch films. The country's ministry of industry and trade monitors resin import dependencies as converting capacity expands faster than regional supply. Port-proximate film extruders near Hai Phong bypass domestic resin shortages through direct Asian supplier relationships.
Global Polyethylene Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The polyethylene industry structures around three archetypes: integrated petrochemical majors with captive cracker access, technology licensors with proprietary catalyst systems, and regional compounders serving specialized formulation requirements. Capacity expansion and mechanical recycling integration represent the dominant competitive moves as producers respond to EU Green Deal compliance timelines.
Within the integrated major tier, SABIC, Dow Inc., and LyondellBasell Industries exemplify divergent strategic positions. SABIC represents the feedstock-advantaged exporter archetype, Dow Inc. occupies the technology-differentiated specialty position, and LyondellBasell Industries sits within the scale-driven commodity producer category. Each anchors a distinct value capture logic across the density grade spectrum.
| Leading Market Players |
|---|
| SABIC |
| BASF SE |
| ExxonMobil Chemical |
| Chevron Phillips Chemical |
| Braskem |
| Dow Inc. |
| INEOS |
| Borealis AG |
| LyondellBasell Industries |
| Others |
Value Chain & Pricing Dynamics
Houston-to-Rotterdam freight corridors transmit ethane cost advantages from Gulf Coast crackers into European spot premiums, concentrating margin capture among integrated producers while forcing non-integrated compounders toward long-term offtake contracts to stabilize input costs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across HDPE pipe and LLDPE film grades, with differentiation driven by REACH certification tiers and volume scale commitments. Cost compression in commodity grades intensifies as Middle Eastern exporters leverage feedstock access, while FDA food-contact certified resins sustain premium positioning. Mid-sized Southeast Asian converters exhibit highest price sensitivity through spot market procurement, whereas healthcare blow-fill-seal producers accept elevated pricing for validated drug master file registrations.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus, redirecting resin flows through Singapore and Vietnam transshipment hubs. Production concentrates in Saudi Arabia, the United States, and China, with naphtha and ethane feedstock costs tethered to regional energy benchmarks. Distribution runs through port-proximate bulk terminals at Rotterdam, Houston, and Singapore, where railcar-to-vessel transfers compress logistics friction for Asian and Latin American offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among e-commerce fulfillment platforms and organized retail chains, consolidating procurement volumes and compressing distributor margins across Southeast Asian converting corridors.
For Market Incumbents: Insulate margin position through backward integration into mechanical recycling assets and captive cracker expansion near Rotterdam or Singapore port infrastructure. SABIC and Dow Inc. demonstrate how feedstock access and proprietary catalyst technology respectively defend against commodity price erosion. Accelerate EU Green Deal certification timelines to lock out smaller compounders lacking capital for additive package reformulation.
For New Entrants and Emerging Players: India's FSSAI-regulated flexible packaging corridors offer underpenetrated white-space for metallocene-grade LLDPE suppliers. Target Mumbai and Delhi NCR film extruders through digital B2B procurement platforms that disintermediate legacy distributor networks. Bio-based feedstock pilots qualify for EU ETS advantages and brand-owner sustainability commitments, creating differentiated entry positioning against commodity incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical majors divesting non-core polyethylene assets to fund decarbonization investments. Mid-sized European compounders with REACH-certified additive packages and established OEM validation protocols present attractive consolidation candidates. Monitor China's MEE dual carbon enforcement intensity as the signal indicating steam cracker approval velocity and regional supply expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Integration | EU Green Deal compliance mandates post-consumer recycled content certification for flexible packaging converters in Germany and France. |
| Backward Integration into Cracker Assets | SABIC leverages Saudi ethane access to sustain cost leadership in bulk HDPE exports across Asian and African markets. |
| Digital B2B Platform Adoption | Vietnamese and Indonesian converters bypass traditional distributors through real-time resin procurement portals. |
| Bio-based Feedstock Pilot Expansion | Renewable naphtha-to-ethylene pathways qualify for EU ETS advantages and brand-owner sustainability commitments. |
| Metallocene Catalyst Technology Licensing | Dow Inc.'s solution-phase proprietary systems command premium positioning in downgauged stretch film grades. |
Study Parameters
Initial hypotheses were tested against primary input from cracker operations managers, flexible packaging procurement leads, regulatory affairs directors at compounders, and mechanical recycling technology suppliers, then refined through secondary validation against customs trade data, SEC 10-K filings, ACC and Cefic industry reports, and EPA emission disclosure records. Bottom-up volume estimates from grade-specific production capacities were triangulated against top-down demand models derived from end-use consumption patterns.
Demand-supply balance dynamics across the projection horizon were modeled through density grade, end-use industry, packaging format, and regional production hub segmentation. CAGRs were derived from historical trajectory analysis and forward-looking capacity addition schedules, incorporating ethane-naphtha spread volatility, REACH regulatory timeline compression, and Southeast Asian converting capacity clustering as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Saudi or U.S. exporters, or accelerated MEE enforcement in China, would shift outcomes beyond modeled ranges. Macroeconomic contraction in e-commerce fulfillment, regulatory delay in EU Green Deal implementation, or breakthroughs in polypropylene substitution chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Conductive Polymers Market
Polymers & Resins
Global Chromatography Resin Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Global Polyalkylene Glycol (PAG) and Esters Market
Polymers & Resins
Co-Polymer Resin Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
Polyurethane (PU) Foam Market
Polymers & Resins
Natural Oil Polyols (NOP) Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
PVDF Resin Market
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Global Vinyl Ester Market
Polymers & Resins
Aromatic Ketone Polymer Market
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
Global Polymethyl Methacrylate Market