
 India Automotive Thermoplastic Polymer Composites Market | 2026-2036
India Automotive Thermoplastic Polymer Composites Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Thermoplastic Polymer Composites Market Foresight
Automotive-grade polyamide specifications is collapsing the gap between metal replacement targets and achievable part performance in Indian passenger vehicles. BASF leverages its Ludwigshafen-derived compounding expertise to supply localized PA6 and PA66 grades for under-the-hood applications. Celanese Corporation anchors its position through backward integration into acetic acid and engineered materials, ensuring feedstock security for Mumbai-Pune belt manufacturers. DuPont de Nemours differentiates via Zytel-brand thermal stability packages that sustain performance across India's ambient temperature swings.
Automotive thermoplastic polymer composites comprise fiber-reinforced thermoplastic matrices—typically polypropylene, polyamide, or polycarbonate loaded with 20-60% glass or carbon fiber—processed through injection molding or thermoforming to yield lightweight structural and semi-structural vehicle components. These materials reduce part mass 30-50% versus stamped steel while enabling complex geometries and end-of-life recyclability. Polypropylene dominates current Indian volumes due to cost parity and established recycling infrastructure, though polycarbonate blends capture premium interior component margins where optical clarity and impact resistance converge. Electric vehicle applications expand fastest as battery tray and housing designs demand flame-retardant polyamide grades with specific gravity below 1.4.
BIS flammability protocols and the Automotive Industry Standard AIS-015 shape material qualification timelines for domestic suppliers, while state-level EV policies in Gujarat and Maharashtra create demand pull through production-linked incentive thresholds. The Central Pollution Control Board's extended producer responsibility framework for plastics is forcing compounders to certify recyclability pathways. Stakeholders must monitor how upcoming BIS revisions on fiber-reinforced plastic structural integrity will reshape supplier certification costs and OEM qualification cycles.
Market Dynamics
BIS flammability mandates and AIS-015 structural integrity protocols are compressing OEM qualification cycles while pulling compounders toward certified polyamide grades for battery enclosures and under-the-hood applications.
Growth Catalysts
- PLI scheme thresholds:Gujarat and Maharashtra state-level EV production-linked incentives are pulling demand for lightweight thermoplastic structural components through domestic assembly plants.
- Glass-mat thermoplastics:Electric vehicle manufacturers are accelerating adoption for battery tray housings requiring specific gravity below 1.4 and flame-retardant performance.
- Chennai-Coimbatore corridor concentration:Tier-1 supplier clustering around Tamil Nadu OEM plants creates localized demand density for just-in-time polyamide and polypropylene compound delivery.
Market Restraints
- Acetic acid feedstock volatility:Backward-integrated compounders face input cost pressure from petrochemical derivative pricing swings affecting PA6 and PA66 grade economics.
- Recyclability certification burden:Central Pollution Control Board extended producer responsibility frameworks force compounders to document end-of-life pathways before OEM qualification approval.
- Metal substitution ceiling:High-load structural applications in chassis and suspension components remain locked out due to fiber-reinforced plastic creep performance limitations under sustained mechanical stress.
Strategic Opportunities
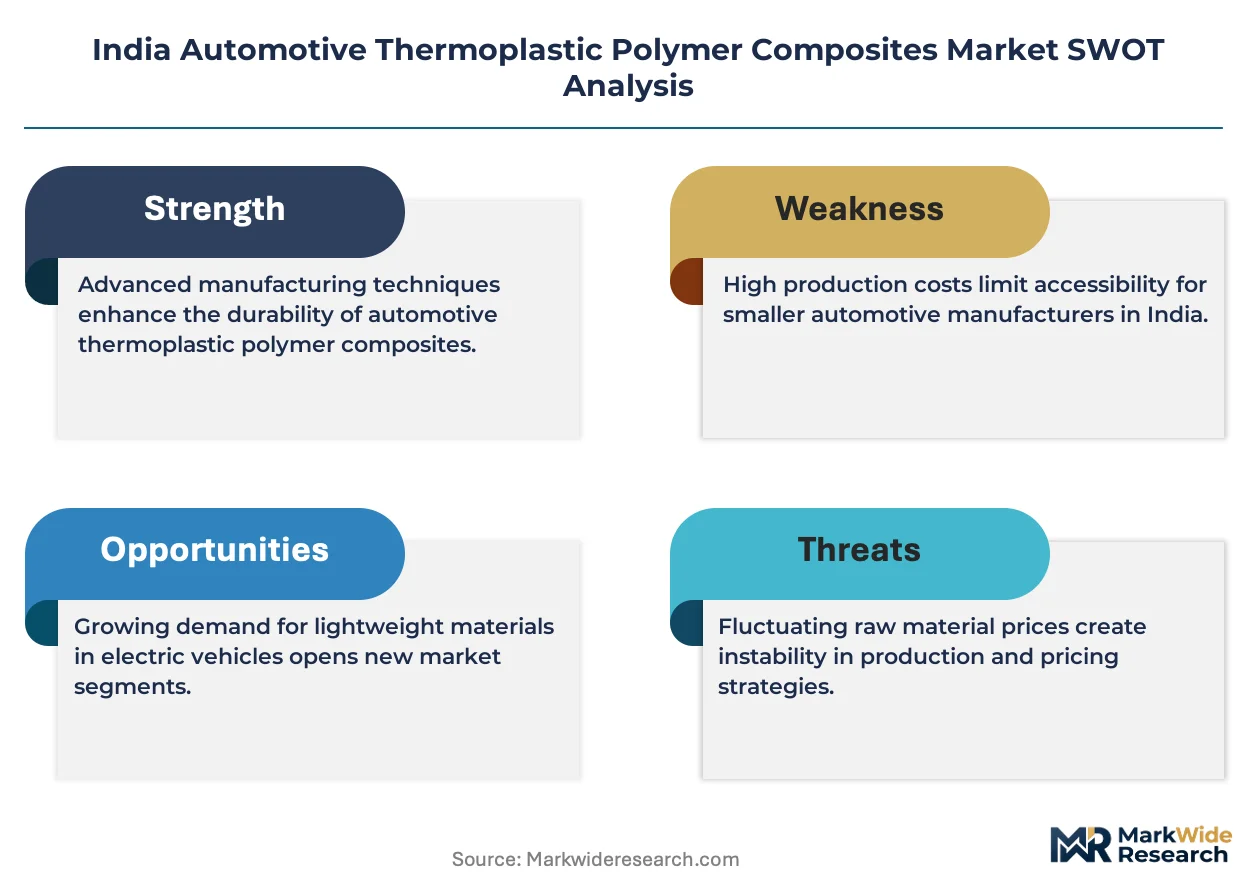
- Battery enclosure thermal management:Emerging demand for polyamide grades with integrated flame-retardant packages and thermal conductivity modifiers creates specification white space beyond commodity PP compounds.
- Mumbai-Pune belt expansion:Western India automotive manufacturing concentration offers underpenetrated territory for localized compounding operations serving passenger vehicle and two-wheeler OEMs.
- BIS structural integrity revisions:Upcoming fiber-reinforced plastic certification updates will reshape supplier qualification costs, creating first-mover advantage for pre-certified compounders.
Industry Challenges
- Material qualification timeline compression:AIS-015 automotive industry standard updates are squeezing validation windows for new polyamide grades, forcing simultaneous BIS and OEM testing cycles.
- Compounding talent scarcity:Shortage of polymer engineers with fiber-matrix interface optimization expertise limits formulation development velocity for high-performance grades.
- Legacy metal supplier integration:Tier-1 stampers transitioning to thermoplastics face tooling retooling capex and injection molding process requalification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Thermoplastic Polymer Composites Market |
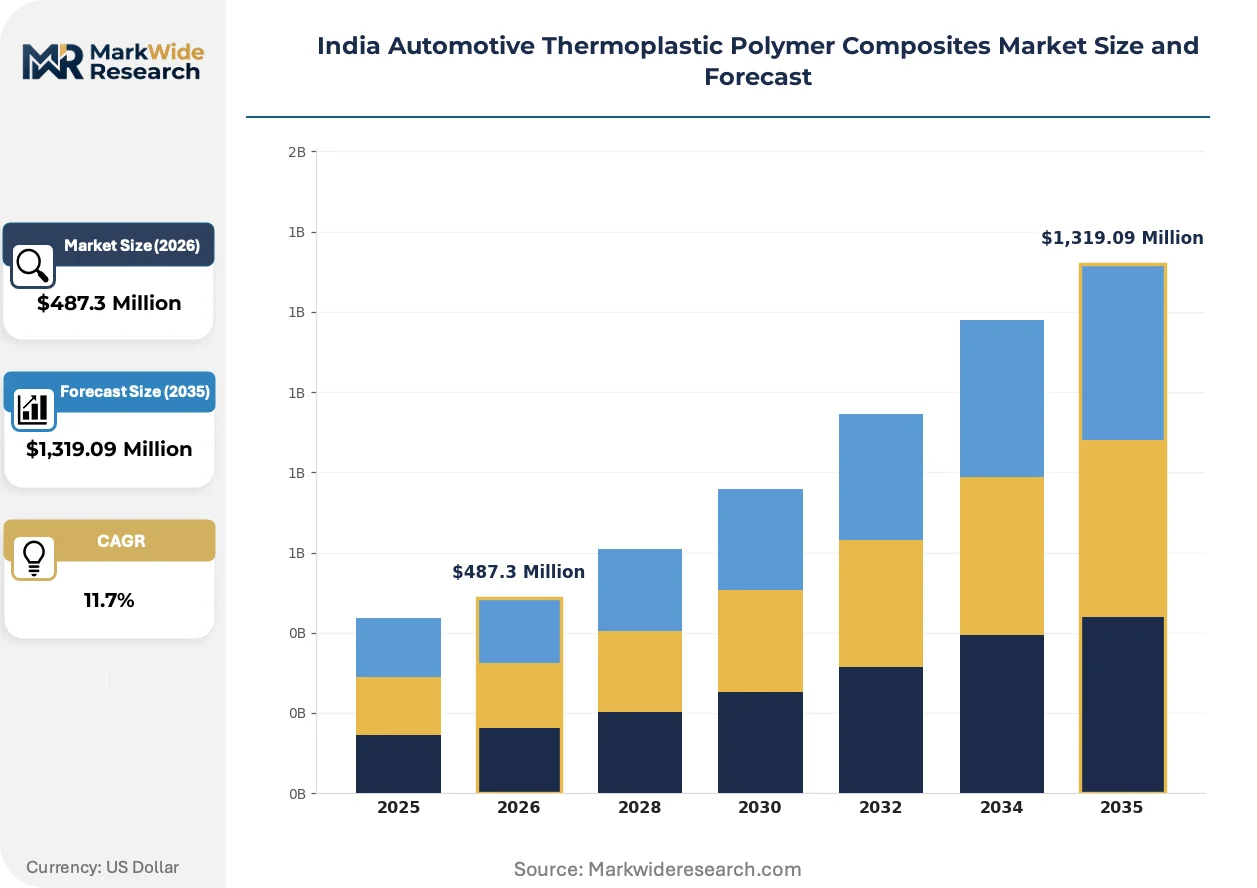
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyamide, Polycarbonate, Thermoplastic Polyurethane End User: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Electric Vehicles Application: Interior Components, Exterior Components, Structural Parts, Electrical Systems Technology: Injection Molding, Blow Molding, 3D Printing, Thermoforming |
| Companies Covered | 3B-Fiberglass, BASF, Gurit, Solvay, Arkema Group, Cytec Industries Inc, Celanese Corporation, Daicel Polymer Ltd, DuPont de Nemours, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Thermoplastic Polymer Composites Market Shifts & Advancements
Continuous fiber-reinforced thermoplastic tapes are rewriting material substitution economics while regulatory pressure on recyclability forces redesign of compound formulations and supplier certification protocols.
Long-fiber-reinforced polypropylene compounds are decomposing the traditional metal-stamping value chain in Indian passenger vehicle interior and semi-structural applications. Maruti Suzuki and Tata Motors procurement teams are qualifying these grades for instrument panel carriers and door modules at accelerated pace. This substitution dynamic is compressing tooling amortization periods and forcing tier suppliers to retool press lines for injection molding cell configurations.
BIS automotive material flammability standards revisions are tightening certification requirements for battery enclosure and under-the-hood polyamide applications. The mandate pushes OEMs toward pre-certified compound grades with documented thermal stability across ambient temperature swings. Tamil Nadu-based electric vehicle assemblers are responding fastest, embedding flame-retardant grade specifications into supplier RFQs ahead of formal enforcement deadlines.
Compound procurement patterns are consolidating around vertically integrated suppliers with captive recycling operations. Mumbai-Pune corridor manufacturers are shifting volume commitments toward compounders offering certified post-industrial regrind streams and documented EPR compliance. This preference shift is marginalizing smaller toll compounders lacking in-house recycling infrastructure or BIS certification capabilities.
India Automotive Thermoplastic Polymer Composites Market Segmentation
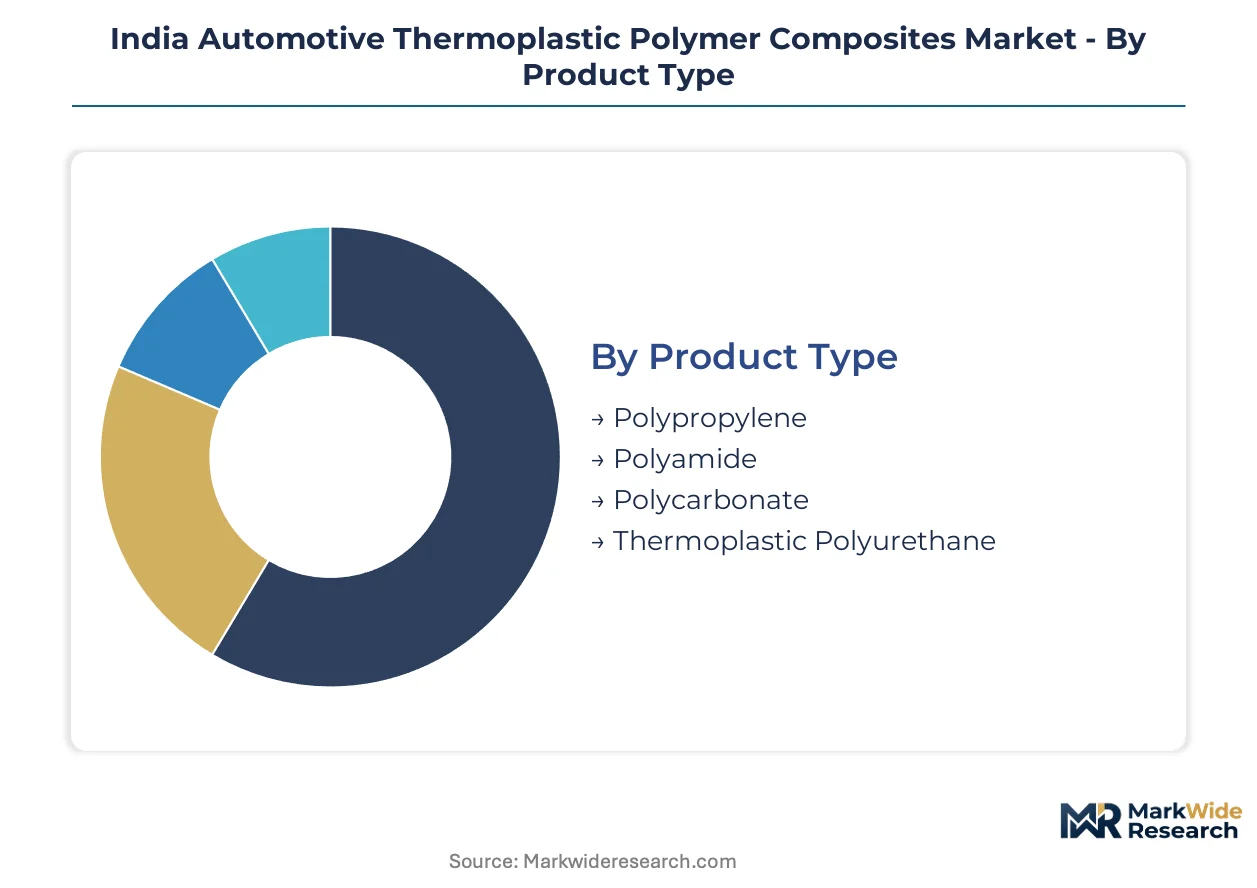
Segmentation in India's automotive thermoplastic polymer composites market reveals how substitution economics vary dramatically across resin chemistry, vehicle architecture, and manufacturing process. Understanding these fault lines exposes where compounders can defend margin and where commoditization pressure intensifies.
Product Type:
Polypropylene faces the most acute substitution threat from long-fiber-reinforced grades climbing the performance ladder, while polyamide defends position through BIS-mandated flame-retardant specifications that commodity resins cannot meet.
- Polypropylene:Glass-fiber-reinforced grades at 20-40% loading dominate current Indian volumes through cost parity with stamped steel and established mechanical recycling infrastructure. Demand clusters in Tamil Nadu's Chennai-Coimbatore corridor where Tier-1 suppliers feed Maruti Suzuki and Hyundai Motor India assembly plants with instrument panel carriers and door modules.
- Polyamide:PA6 and PA66 compounds with flame-retardant packages capture battery enclosure and under-the-hood applications where thermal stability across ambient temperature swings is non-negotiable. BASF's localized compounding operations supply certified grades meeting BIS automotive material flammability protocols ahead of formal enforcement deadlines.
- Polycarbonate:Blends with ABS or polyester deliver optical clarity and impact resistance for premium interior glazing and lighting housings in Mumbai-Pune belt luxury vehicle assembly.
- Thermoplastic Polyurethane:Elastomeric grades absorb vibration and enable soft-touch surfaces in steering wheels and shift boots for two-wheeler OEMs.
Polypropylene anchors the volume base while polyamide gains share at the steepest rate.
End User:
Vehicle electrification is restructuring demand concentration, with electric vehicle architectures consuming 3-4x the thermoplastic composite content per unit versus internal combustion platforms due to battery thermal management requirements.
- Passenger Vehicles:Instrument panel carriers, door modules, and bumper beams drive the largest absolute tonnage, with long-fiber-reinforced polypropylene displacing steel stampings at accelerating pace.
- Electric Vehicles:Battery tray housings and enclosure systems demand flame-retardant polyamide grades with specific gravity below 1.4, creating specification white space beyond commodity compounds. Gujarat and Maharashtra state-level PLI scheme thresholds are pulling dedicated capacity for this segment.
- Commercial Vehicles:Cab structures and interior trim prioritize durability over weight reduction, favoring higher glass loadings and UV-stabilized formulations.
- Two-wheelers:Body panels and fuel tank housings in polypropylene compounds serve Hero MotoCorp and Bajaj Auto assembly lines with extreme cost sensitivity.
Passenger vehicles retain the largest absolute volume while electric vehicles expand most quickly.
Application:
Structural parts command the highest technical barriers and supplier qualification burdens, insulating specialized compounders from commodity competition that erodes margins in interior components.
- Interior Components:Dashboard carriers, door panels, and console structures in long-fiber-reinforced polypropylene enable complex geometries and soft-touch integration that metal cannot replicate.
- Structural Parts:Load-bearing applications including front-end modules and underbody shields demand continuous fiber-reinforced tapes and compression-molded organosheets with validated creep performance.
- Exterior Components:Fenders, hoods, and liftgates balance aesthetics with dimensional stability, requiring UV-resistant grades and Class A surface capability.
- Electrical Systems:Connectors, housings, and high-voltage insulation components in flame-retardant polyamide face the most stringent BIS certification timelines.
Interior components dominate current procurement volumes while structural parts capture the steepest margin expansion trajectory.
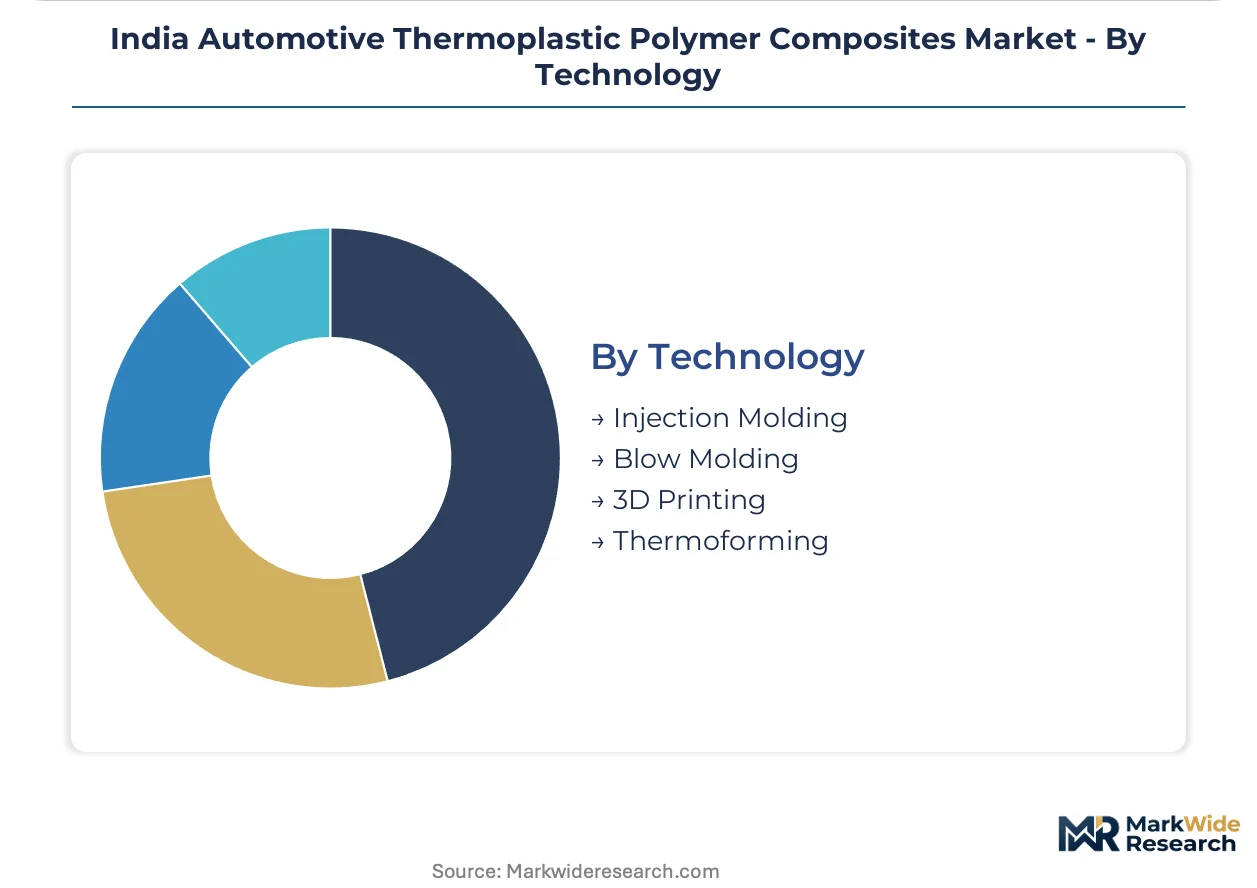
Technology:
Process selection locks in feedstock form, cycle economics, and geometric capability, with injection molding defending scale advantages against emerging additive methods in prototyping and repair.
- Injection Molding:High-pressure processing of pelletized long-fiber-reinforced compounds enables complex geometries at automotive production volumes, dominating Tamil Nadu and Maharashtra manufacturing clusters.
- Thermoforming:Glass-mat thermoplastic blanks heat and stamp into battery tray housings and large exterior panels, gaining ground as electric vehicle platforms scale.
- Blow Molding:Hollow structural sections including air ducts and fluid reservoirs exploit polypropylene cost positions in high-volume programs.
- 3D Printing:Fused filament fabrication of carbon fiber-reinforced thermoplastics serves prototyping and aftermarket repair applications with limited production penetration.
Injection molding retains the installed capacity base while thermoforming climbs fastest on electric vehicle battery enclosure demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compounders cluster along three industrial corridors where OEM assembly plants and Tier-1 suppliers create localized demand density. State-level EV policies and BIS certification timelines reshape procurement geography faster than national averages suggest.
Tamil Nadu
Chennai-Coimbatore belt hosts India's densest concentration of passenger vehicle OEMs and their thermoplastic compound suppliers. Maruti Suzuki and Hyundai Motor India assembly plants pull just-in-time polyamide and polypropylene deliveries from surrounding Tier-1 molding operations. BIS automotive material flammability protocols hit enforcement here first due to Tamil Nadu's EV production scale.
Maharashtra
Mumbai-Pune corridor anchors western India demand for premium polycarbonate blends and flame-retardant polyamide grades. State PLI scheme thresholds for electric vehicle assembly are pulling dedicated compounding capacity into Pune industrial zones. Local manufacturers face compressed AIS-015 qualification cycles as battery enclosure specifications tighten.
Gujarat
Sanand-Vadodara manufacturing belt concentrates two-wheeler and commercial vehicle OEM demand for cost-optimized polypropylene compounds. State EV policy production-linked incentives are redirecting compounder investment toward battery tray housing grades. Central Pollution Control Board extended producer responsibility frameworks force documentation of recycling pathways before supplier approval.
Haryana
Delhi-NCR satellite plants supply Hero MotoCorp and Maruti Suzuki operations with high-volume polypropylene for body panels and fuel systems. Proximity to BIS headquarters accelerates certification turnaround for new flame-retardant grades. Local compounders struggle with acetic acid feedstock volatility affecting PA6 and PA66 grade economics.
Karnataka
Bengaluru-Tumakuru corridor emerging as southern hub for electric vehicle startup assembly and their thermoplastic composite sourcing. State EV manufacturing incentives attract compounders specializing in glass-mat thermoplastics for battery enclosures. Talent scarcity in polymer engineering limits formulation development velocity for high-performance grades.
India Automotive Thermoplastic Polymer Composites Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. European chemical majors with compounding expertise occupy the specification-setting tier, while Asian compounders compete on feedstock integration and scale. Three archetypes dominate: vertically integrated petrochemical giants, specialized engineering compounders with captive recycling, and toll compounders serving regional OEM clusters. M&A activity concentrates around recycling asset acquisition, while capacity expansion focuses on flame-retardant polyamide lines for battery applications.
Within the European-origin tier, BASF and Solvay exemplify specification leadership through localized compounding operations and BIS certification pre-positioning. Celanese Corporation anchors the backward-integrated archetype with captive acetic acid supply securing feedstock economics for Mumbai-Pune belt manufacturers. DuPont de Nemours occupies the thermal stability specialization tier, with Zytel-brand positioning targeting ambient temperature swing performance requirements.
| Leading Market Players |
|---|
| 3B-Fiberglass |
| BASF |
| Gurit |
| Solvay |
| Arkema Group |
| Cytec Industries Inc |
| Celanese Corporation |
| Daicel Polymer Ltd |
| DuPont de Nemours |
| Others |
Supply & Pricing Matrix
Installed compounding capacity utilization above 85 percent across Maharashtra and Tamil Nadu clusters creates asymmetric bargaining power for backward-integrated suppliers serving flame-retardant polyamide grades. This scale concentration compresses price floors for toll compounders while elevating margin capture for BASF and Celanese Corporation operations with captive feedstock security.
Pricing Analysis
BIS automotive material flammability protocols dictate the pricing tier structure across certified and uncertified compound grades. Three-tier pricing structure across premium certified, standard industrial, and economy regrind levels separates battery enclosure specifications from interior commodity applications. Cost compression in uncertified polypropylene runs through acetic acid derivative volatility and recycled feedstock competition. Two-wheeler OEM procurement teams exhibit extreme price sensitivity versus electric vehicle platform engineers prioritizing thermal stability certification.
Supply Chain Analysis
Just-in-time inventory cycles of 7-10 days dominate Tamil Nadu Chennai-Coimbatore corridor operations where Tier-1 molders feed Maruti Suzuki and Hyundai Motor India assembly lines. Feedstock security draws from Germany, Belgium, and domestic petrochemical complexes at Dahej and Hazira. Single-source vulnerability concentrates in specialty flame-retardant additive packages imported from European chemical majors. Distribution runs through direct mill-to-mold compound delivery with minimal distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against continuous fiber-reinforced thermoplastic tapes and metal-hybrid designs climbing the performance ladder. Incumbents must navigate compressed AIS-015 qualification timelines while preserving margin in commoditized interior applications.
For Market Incumbents: Fortify BIS certification pre-positioning ahead of structural integrity protocol revisions to lock out toll compounders lacking testing infrastructure. Anchor capacity expansion in Gujarat Sanand-Vadodara belt where state EV incentives concentrate battery enclosure demand and backward integration into acetic acid secures feedstock economics against petrochemical volatility.
For New Entrants and Emerging Players: Lead with glass-mat thermoplastic specialization for electric vehicle battery tray housings where specification white space exceeds commodity polypropylene saturation. Target Karnataka Bengaluru-Tumakuru corridor startup assemblers with localized compounding operations and documented EPR compliance pathways that marginalize established suppliers lacking recycling infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with captive recycling operations and long-term OEM qualification status. Five-to-ten year viability hinges on pre-positioning for BIS structural integrity enforcement rather than spot market commodity exposure. Monitor Tamil Nadu-based electric vehicle assembler procurement patterns as inflection signal for flame-retardant grade specification embedding velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid | Celanese Corporation secures feedstock economics for Mumbai-Pune belt PA6 and PA66 grade supply. |
| BIS Certification Pre-Positioning | BASF compounds Ludwigshafen expertise into localized flame-retardant grade approval ahead of enforcement deadlines. |
| Glass-Mat Thermoplastic Capacity Expansion | Dedicated lines for battery tray housings capture Gujarat and Maharashtra PLI scheme threshold demand. |
| Captive Recycling Infrastructure | Vertically integrated compounders document EPR compliance pathways that satisfy Central Pollution Control Board mandates. |
| Chennai-Coimbatore Corridor Localization | Just-in-time delivery cells reduce logistics costs for Tamil Nadu Tier-1 suppliers feeding Hyundai and Maruti assembly. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement leads, compounder technical directors, and BIS certification auditors and refined through secondary validation across customs trade data, Automotive Industry Standard AIS-015 documentation, Central Pollution Control Board EPR filings, and SEC disclosures from listed chemical majors. Bottom-up volume modeling triangulated against top-down value estimates derived from production-linked incentive thresholds and vehicle registration databases.
Variance decomposition across resin chemistry, vehicle architecture, and manufacturing process dimensions structured the analytical framework throughout the projection horizon. CAGRs emerged from segment-level growth rate synthesis rather than single-point extrapolation. Forecast inputs incorporated battery electric vehicle penetration curves, BIS revision implementation timelines, and glass-mat thermoplastic adoption rates in battery enclosure applications.
The analysis sits within stated boundaries; outcomes outside sustained PLI scheme enforcement or feedstock price stability would require recalibration. Forecasts reflect documented assumptions regarding qualification cycle compression and regulatory implementation velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Redispersible Polymer Powder Market
Polymers & Resins
Bio-Based Thermoplastic Elastomer Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
India Polyacrylamide Copolymer Market
Polymers & Resins
Europe Engineering Plastics Market
Polymers & Resins
Middle East Polyethylene Market
Polymers & Resins
Polymer Reinforcing Filler Market
Polymers & Resins
GCC Polyethylene Terephthalate (PET) Market
Polymers & Resins
Super Absorbent Polymer Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
Sugar Polymers Market
Polymers & Resins
Wood Coating Resins Market
Polymers & Resins
Acrylic Monomers Market