
 Polyurethane Composites Market | 2026-2036
Polyurethane Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane Composites Market Analysis
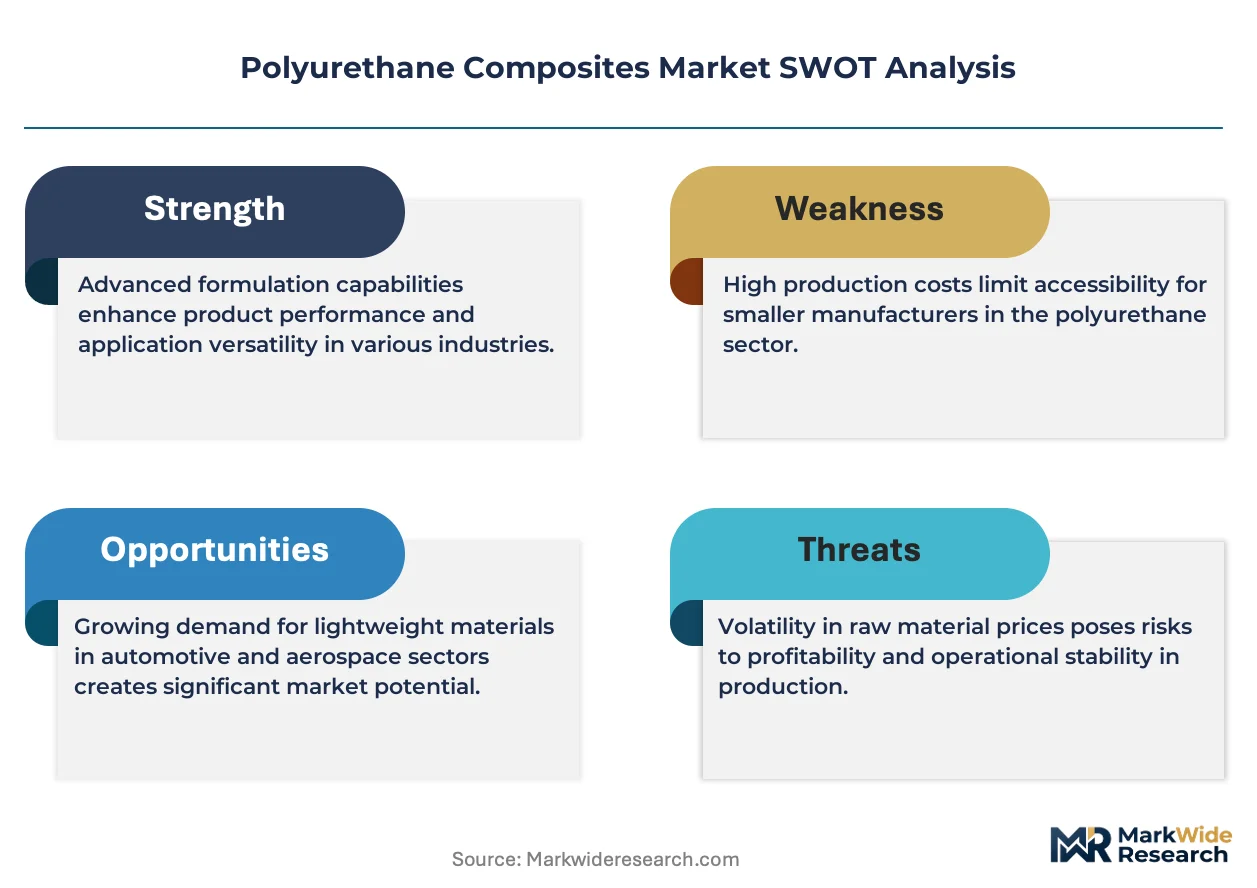
Performance-based maintenance contracts for wind turbine blade repairs is realigning how polyurethane composite suppliers monetize long-term relationships. BASF SE leverages its polymer science depth to anchor blade resin formulations across European wind farms. Covestro AG competes through differentiated low-viscosity systems that accelerate turbine manufacturing cycle times. Dow Inc. extends its position via integrated isocyanate supply chains serving North American insulation markets.
Polyurethane composites combine isocyanate and polyol reactions with reinforcing fibers to produce lightweight, high-strength materials with tunable density and thermal resistance. These materials serve primarily as structural alternatives to epoxy and polyester in applications demanding fatigue durability and design flexibility. Rigid foam formulations for construction insulation dominate volume, while coatings for corrosion protection in marine environments capture expanding margin pools. Spray application methods for on-site insulation are gaining specification share against pour-in-place alternatives due to labor efficiency and thermal bridging reduction.
EPA regulations on volatile organic compound emissions constrain solvent-based coating formulations, pushing demand toward waterborne and high-solids polyurethane systems. REACH chemical registration requirements in Europe limit certain isocyanate precursors, reshaping raw material sourcing strategies for compounders. OSHA workplace exposure standards for diisocyanates in the United States mandate engineering controls that elevate production costs for small-batch manufacturers. Stakeholders must monitor evolving chemical hazard classifications across EPA, ECHA, and state-level air quality districts to anticipate reformulation timelines and compliance-driven procurement shifts.
Market Dynamics
Wind turbine blade manufacturing is shifting from epoxy to polyurethane composites as glass-fiber alternatives, creating a structural pull that reshapes resin formulation priorities across chemical suppliers. This transition concentrates purchasing power with European renewable energy clusters and automotive OEMs demanding fatigue-resistant, lightweight materials.
Growth Catalysts
- EU Green Deal carbon neutrality mandates:Binding 2050 net-zero targets accelerate renewable energy infrastructure buildouts, directly expanding specification opportunities for polyurethane composites in wind turbine blade production across Germany, Denmark, and Spain.
- REACH chemical registration streamlining:Simplified authorization pathways for novel isocyanate formulations reduce time-to-market for next-generation polyurethane systems, encouraging R&D investment in low-toxicity curing agents.
- Automotive lightweighting specifications:German OEMs are integrating polyurethane composite structural components to meet fleet emissions standards, replacing metal stampings in underbody panels and battery enclosures.
Market Restraints
- MDI feedstock price volatility:Methylene diphenyl diisocyanate, the core polyurethane precursor, experiences cyclical supply tightness tied to benzene derivative markets, compressing compounder margins during upstream spikes.
- Epoxy incumbent lock-in:Established blade manufacturers maintain qualified supplier lists favoring epoxy resin systems, creating switching friction that slows polyurethane penetration despite performance advantages.
- OSHA diisocyanate exposure limits:Workplace ventilation and monitoring requirements elevate fixed costs for small-batch processors, consolidating production toward capital-intensive facilities with engineered containment systems.
Strategic Opportunities
- India construction insulation retrofit wave:Energy efficiency building codes in Mumbai and Delhi create first-mover openings for spray-applied polyurethane foam systems replacing mineral wool in commercial envelope upgrades.
- Marine coatings corrosion protection:Shipyards in South Korea and Japan are specifying high-solids polyurethane topcoats to extend vessel service intervals, displacing traditional alkyd systems in dry-dock maintenance cycles.
- Recyclable thermoplastic polyurethane hybridization:Conventional thermoset limitations are yielding to fiber-reinforced thermoplastic variants that enable end-of-life shredding and reprocessing, aligning with circular economy procurement criteria.
Industry Challenges
- Diisocyanate handling certification gaps:Qualified technicians for safe isocyanate processing remain scarce relative to installation demand, constraining field application capacity for spray foam contractors.
- Blade repair technician training bottlenecks:Wind farm operators require certified composite repair specialists for polyurethane blade maintenance, but vocational programs lag behind turbine deployment rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane Composites Market |
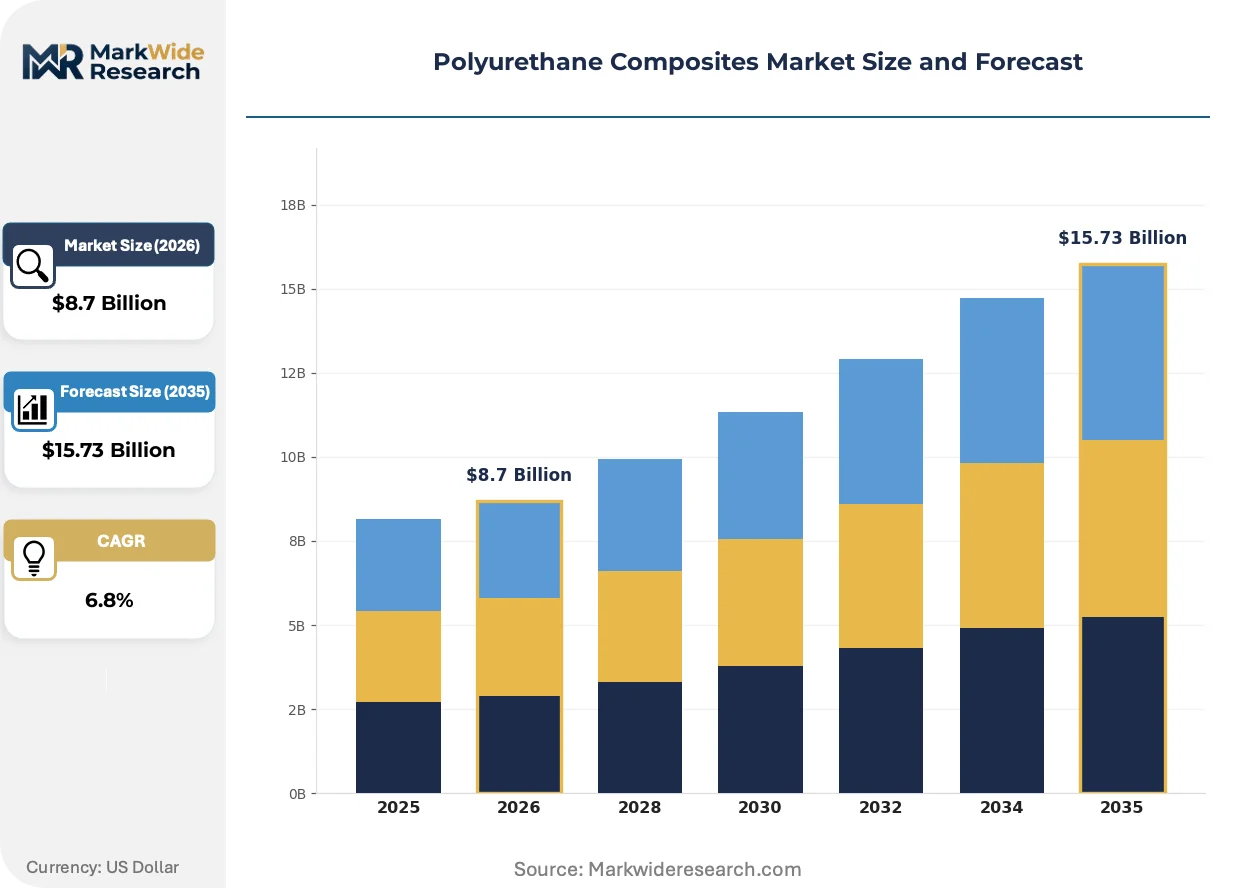
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Coatings, Adhesives End Use Industry: Automotive, Construction, Furniture, Electronics Form: Spray, Pour, Sheet, Block Application: Insulation, Sealants, Packaging, Castings |
| Companies Covered | BASF SE, Covestro AG, Dow Inc., Huntsman Corporation, Wanhua Chemical Group Co., Ltd., Toray Industries, Inc., Mitsui Chemicals, Inc., Hexcel Corporation, ELANTAS GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane Composites Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are converging to redefine how polyurethane composite systems are formulated, applied, and recovered across industrial end-uses.
Closed-cell rigid polyurethane foam is modularizing construction insulation workflows by enabling spray-applied, site-fabricated thermal envelopes that eliminate prefabricated panel logistics. German and Dutch contractors are adopting truck-mounted proportioning systems for mid-rise commercial builds. This technology is compressing project timelines from weeks to days while reducing thermal bridging at structural joints.
REACH Annex XIV authorization requirements for certain aromatic isocyanates are forcing reformulation toward aliphatic alternatives in European coatings applications. Industrial finishers face raw material qualification cycles extending 18-24 months. Marine and automotive segments in Germany and France are responding by pre-qualifying alternative curing agent portfolios before sunset dates trigger supply disruptions.
Wind farm operators are unbundling blade maintenance from original equipment supply agreements, creating standalone service markets for polyurethane composite repair specialists. Independent contractors in Denmark and Spain are capturing recurring revenue streams previously retained by turbine manufacturers. This pattern concentrates most visibly in offshore wind clusters where blade accessibility demands specialized rope-access technicians with polymer chemistry expertise.
Polyurethane Composites Market Segmentation
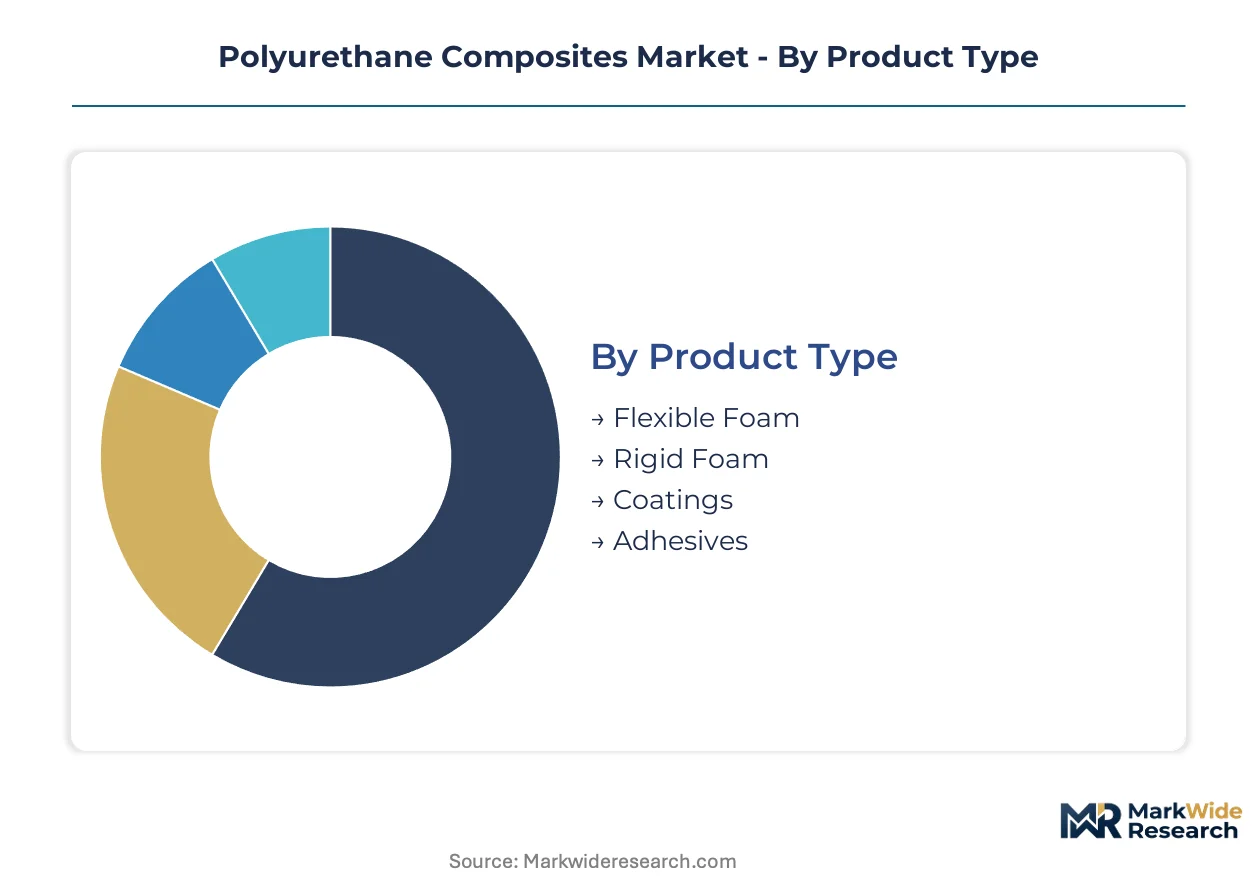
Polyurethane composites fragment across four distinct category axes, each revealing different competitive dynamics. Product type segmentation exposes where formulation complexity commands premium pricing. End-use industry segmentation shows which sectors drive specification upgrades versus commodity volume plays.
Product Type:
Integration depth varies sharply—rigid foam operates as standalone thermal systems, while coatings and adhesives embed within larger material stacks.
- Rigid Foam:Closed-cell structures with high compressive strength and dimensional stability serve as primary thermal insulation in building envelopes and refrigerated transport. Construction contractors in Germany and the Netherlands specify spray-applied rigid foam for mid-rise commercial retrofits, driven by EU Green Deal energy efficiency mandates tightening building code requirements.
- Flexible Foam:Open-cell formulations with tunable density and resilience characteristics absorb impact and vibration in seating and bedding applications. Automotive seating manufacturers in Germany integrate flexible foam composites to reduce component weight while meeting fleet emissions standards, though MDI feedstock price volatility compresses compounder margins during supply tightness.
- Coatings:High-solids and waterborne formulations provide corrosion protection and abrasion resistance for industrial substrates. Marine shipyards in South Korea specify polyurethane topcoats to extend dry-dock intervals, displacing alkyd systems.
- Adhesives:Structural bonding systems with rapid cure profiles join dissimilar materials in assembly operations. Electronics manufacturers leverage polyurethane adhesives for encapsulation and thermal management in battery pack construction.
Rigid foam leads volumes today; coatings are gaining share fastest as corrosion protection specifications tighten across marine and infrastructure sectors.
End Use Industry:
Cost tier stratification separates specification-driven sectors from price-sensitive commodity buyers, with automotive and construction commanding premium formulations.
- Construction:Thermal insulation, sealants, and structural composites dominate material consumption across residential and commercial builds. Spray foam contractors in Mumbai and Delhi capture energy efficiency retrofit demand as Indian building codes tighten, though qualified technician scarcity constrains field application capacity.
- Automotive:Lightweight structural components, seating systems, and battery enclosure materials reduce vehicle mass to meet emissions targets. German OEMs integrate polyurethane composite underbody panels and battery housings, replacing metal stampings where fatigue durability and design flexibility prove critical.
- Furniture:Cushioning, bedding, and upholstered components consume flexible foam volumes in mass-market manufacturing. Price competition from polyester alternatives limits margin expansion in this segment.
- Electronics:Encapsulation, thermal interface materials, and protective coatings serve circuit board and battery assembly operations. Miniaturization trends drive demand for low-viscosity potting compounds with precise flow characteristics.
Construction anchors volume concentration; automotive is climbing the fastest as lightweighting specifications proliferate across European OEM platforms.
Form:
Application method segmentation determines labor efficiency, equipment requirements, and thermal performance outcomes across installation contexts.
- Spray:On-site proportioning systems deliver foam or coating materials directly to substrates, eliminating prefabricated panel logistics. German contractors adopt truck-mounted spray rigs for commercial envelope upgrades, compressing project timelines from weeks to days while reducing thermal bridging at structural joints.
- Pour:Mold-filling processes create custom-molded components with complex geometries for industrial and consumer goods. Appliance manufacturers specify pour-in-place foam for refrigerator and freezer insulation where dimensional precision matters.
- Sheet:Pre-manufactured panels and membranes enable rapid assembly in standardized construction modules. Modular building producers in Scandinavia source sheet stock for factory-controlled quality and predictable thermal performance.
- Block:Bun stock for subsequent fabrication into custom shapes serves furniture and packaging converters with cutting and shaping flexibility. Block foam processors face margin pressure from Asian import competition in commodity grades.
Spray dominates new installation activity; sheet is expanding most quickly in modular and offsite construction workflows.
Application:
Maturity differentiation separates established insulation markets from emerging specification opportunities in protective and structural roles.
- Insulation:Thermal barrier systems for buildings, appliances, and industrial equipment represent the foundational polyurethane composite use case. REACH chemical registration requirements for certain isocyanate precursors force reformulation toward aliphatic alternatives, extending raw material qualification cycles.
- Sealants:Flexible joint fillers and gap closures accommodate structural movement while preventing moisture and air infiltration. Construction specification growth concentrates in high-performance commercial envelopes requiring long-term durability certification.
- Packaging:Protective cushioning and insulated shipping containers serve electronics, pharmaceuticals, and temperature-sensitive goods. E-commerce fulfillment growth drives demand for molded foam inserts with recyclability credentials.
- Castings:Tooling, prototypes, and industrial parts produced via reaction injection molding enable rapid production of complex geometries. Wind turbine blade manufacturing is shifting toward polyurethane composite castings as glass-fiber alternatives, creating structural pull that reshapes resin formulation priorities.
Insulation maintains volume leadership today; castings are gaining share fastest as renewable energy infrastructure buildouts accelerate specification opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates polyurethane composite specification authority for European wind energy, while China scales manufacturing capacity for construction-grade rigid foam systems serving domestic retrofit programs.
Germany
Automotive OEMs in Stuttgart and Munich specify polyurethane composite battery enclosures and underbody panels to meet fleet emissions standards. ECHA REACH Annex XIV authorization timelines for aromatic isocyanates force compounders toward aliphatic alternatives. The North Rhine-Westphalia chemical cluster anchors resin formulation R&D for blade manufacturers supplying North Sea wind farms.
United States
Spray foam contractors in Texas and Florida capture hurricane-resistant envelope retrofit demand from commercial property insurers. EPA volatile organic compound emission limits constrain solvent-based coating formulations, pushing specification toward waterborne systems. The Gulf Coast petrochemical corridor supplies MDI precursors to compounders serving North American insulation markets.
China
Construction-grade rigid foam consumption accelerates in Beijing and Shanghai as energy efficiency building codes tighten for commercial envelope retrofits. The country's national chemical regulator enforces stricter workplace exposure standards for diisocyanate processing facilities. The Yangtze River Delta manufacturing belt concentrates spray foam equipment production for domestic and Southeast Asian export markets.
India
Mumbai and Delhi commercial developers specify spray-applied polyurethane foam for envelope upgrades ahead of tightened energy efficiency code enforcement. The Bureau of Indian Standards certification requirements for thermal insulation materials extend raw material qualification cycles for imported resin systems. The Gujarat chemical corridor hosts compounding operations serving western Indian construction markets.
South Korea
Shipyards in Busan and Ulsan specify high-solids polyurethane marine topcoats to extend dry-dock maintenance intervals for container and LNG vessels. The Ministry of Environment enforces volatile organic compound limits in industrial coating applications. The Gyeonggi-do manufacturing cluster supplies formulated systems to domestic shipbuilders and export markets across Southeast Asia.
Polyurethane Composites Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation-intensive resin systems concentrating around integrated chemical producers while application equipment and field services fragment across regional installers. Three archetypes dominate: petrochemical majors with captive isocyanate supply, specialized composite compounders with wind energy qualifications, and spray foam contractors with certified technician networks. Competitive moves center on backward integration into MDI precursors and strategic partnerships with turbine OEMs for blade resin qualification.
Among European-integrated chemical producers, BASF SE and Covestro AG exemplify the petrochemical-major archetype with polymer science depth anchoring resin formulation supply to renewable energy clusters. Wanhua Chemical Group Co., Ltd. occupies a position within the scale-driven Asian producer tier, reflecting Chinese manufacturing concentration for construction-grade foam precursors.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Dow Inc. |
| Huntsman Corporation |
| Wanhua Chemical Group Co., Ltd. |
| Toray Industries, Inc. |
| Mitsui Chemicals, Inc. |
| Hexcel Corporation |
| ELANTAS GmbH |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon neutrality mandates gate qualified supply access for polyurethane composite suppliers, reserving premium-tier pricing power for compounders with REACH-compliant aliphatic isocyanate formulations and certified low-toxicity curing agent portfolios. Buyers without sustainability procurement criteria face restricted supplier pools, while specification-driven segments absorb cost premiums for compliant material systems.
Pricing Analysis
Capacity additions in China are reshaping price floors for construction-grade rigid foam precursors, compressing margins for commodity compounders while European wind energy resins maintain premium-mid-economy pricing differentiation based on blade manufacturer qualification status. Price differentiation separates REACH-authorized formulations from standard aromatic isocyanate systems, with German automotive OEMs least sensitive to input cost fluctuations due to lightweighting compliance deadlines. Cost compression in spray foam installation services is intensifying because qualified technician scarcity constrains field application capacity.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for formulated resin systems, feeding downstream spray foam contractors and blade manufacturing clusters. Geographic supply concentrates in Germany, China, and the United States for MDI precursors and specialized curing agents. Raw material sourcing draws from benzene derivative markets, glass fiber reinforcements, and aliphatic isocyanate alternatives. Single-source vulnerability runs through European aromatic isocyanate authorization timelines under REACH Annex XIV. Distribution runs through certified applicator networks and direct mill supply agreements to wind farm operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyurethane composites offer margin expansion through aliphatic isocyanate reformulation premiums and performance-based maintenance contract structures that capture recurring blade service revenue.
For Market Incumbents: Acquire certified technician training networks to lock in field application capacity for spray foam and blade repair services. Consolidate backward integration into MDI precursor supply to hedge benzene derivative volatility. Defend against epoxy incumbent lock-in by pre-qualifying alternative resin systems with European turbine OEMs before supplier list refresh cycles. For New Entrants and Emerging Players: Independent wind farm operators represent an underserved buyer archetype unbundling blade maintenance from original equipment supply agreements. Capture standalone service contracts in offshore wind clusters where rope-access repair specialists command scarcity premiums. Enter through recyclable thermoplastic polyurethane hybridization, aligning with circular economy procurement criteria gaining traction in German and Dutch construction markets. For Investors and Strategic Acquirers: Roll-up economics work for regional spray foam contractors with certified technician networks because diisocyanate handling certification gaps create acquisition targets with protected local market positions. Target mid-scale compounders with wind energy qualifications and REACH-compliant formulation portfolios. Watch ECHA authorization timeline announcements as inflection indicators for aliphatic isocyanate demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Precursors | Captive isocyanate supply hedges benzene derivative price volatility for European compounders. |
| Aliphatic Isocyanate Reformulation | REACH Annex XIV compliance secures authorization continuity for coatings and blade resin formulations. |
| Certified Technician Training Expansion | OSHA diisocyanate exposure compliance creates barrier to entry protecting qualified contractor margins. |
| Performance-Based Maintenance Contracts | Recurring revenue capture from wind farm operators unbundles blade service from turbine supply. |
| Thermoplastic Polyurethane Hybridization | End-of-life recyclability aligns with EU Green Deal circular economy procurement criteria. |
Methodological Framework
Multiple input streams — primary interviews with resin formulators, spray foam contractors, and wind farm procurement officers; secondary validation through ECHA REACH registration databases, customs trade flows, and SEC chemical company filings; plus technical literature on isocyanate curing kinetics — were reconciled through bottom-up and top-down triangulation. Plant managers at MDI production facilities and blade manufacturing quality directors provided capacity and specification data. Distribution channel partners in European renewable energy clusters supplied contractor network coverage metrics.
Historical volume trajectories were cross-referenced against expert panel inputs from polyurethane composite R&D directors and automotive lightweighting engineers. The analytical framework modeled product type, end-use industry, application method, and regional regulatory cluster across the projection horizon. CAGRs were derived from segment-level buildups incorporating wind turbine deployment pipelines, building code enforcement timelines, and automotive platform lightweighting specifications. Feedstock price elasticity and REACH authorization sunset schedules informed scenario weightings.
Underlying measurement precision varies by segment; rigid foam construction volumes carry tighter precision than emerging thermoplastic hybrid categories. Forecasts reflect documented assumptions on regulatory enforcement timing and OEM qualification cycle durations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Graphene Composites Market
Composite Materials
Malaysia High Pressure Laminate Market
Composite Materials
Reinforced Carbon-Carbon Composite Market
Composite Materials
FRP Grating Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Case Material Market
Composite Materials
Thermoplastic Honeycomb Market
Composite Materials
Balsa Core Materials Market
Composite Materials
Thermoplastic Prepreg Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
Laminar Composites Market
Composite Materials
Fiber Reinforced Composite Tapes Market
Composite Materials
China Marine Composites Market
Composite Materials
Asia-Pacific Molded FRP Grating Market
Composite Materials
Polyphenylene Sulfide (PPS) Composites Market