
 Graphene Composites Market | 2026-2036
Graphene Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Graphene Composites Market Intelligence
Multi-source procurement for graphene feedstock is consolidating as tier-one manufacturers seek supply security against flake quality variability. XG Sciences leverages its Michigan-based production campus to dominate North American powder supply. Haydale Graphene Industries sustains UK leadership through plasma functionalization patents. Versarien anchors European demand via its patented Nanene few-layer graphene dispersions.
Graphene composites integrate atomically thin carbon lattices into polymer, metal, or ceramic matrices to achieve tensile strengths exceeding 130 GPa with near-zero weight penalty, primarily serving industries where mechanical performance-to-mass ratios determine competitive outcomes. Structural reinforcement applications occupy the deepest margin pools due to qualification cycles and aerospace certification barriers. Energy storage segments represent the fastest-growing application category as solid-state battery developers specify graphene-enhanced electrodes for conductivity and cycle stability.
REACH compliance in Europe and EPA toxicity evaluations in the United States are shaping product registration pathways and limiting unverified supplier market access. ISO/TC 229 nanotechnology standards and IEC graphene terminology frameworks are converging to reduce technical ambiguity in procurement specifications. Stakeholders must monitor regulatory harmonization progress between ECHA and EPA test protocols to anticipate cross-border certification costs.
Market Dynamics
EU Green Deal material efficiency mandates are forcing aerospace and automotive manufacturers to substitute conventional carbon fiber with graphene composites, compressing qualification timelines and rewiring supplier relationships across Stuttgart, Munich, and Toulouse industrial corridors.
Growth Catalysts
- Solid-state battery electrode specifications:Graphene-enhanced anodes deliver conductivity and cycle stability that lithium-silicon architectures demand. Battery developers in South Korea and Japan are locking in multi-year supply agreements.
- REACH compliance acceleration:ECHA registration pathways for nanomaterials are clarifying, reducing technical ambiguity that previously delayed procurement decisions. Qualified suppliers gain preferential access to German automotive tier-ones.
- Aerospace lightweighting imperatives:FAA certification frameworks for graphene-reinforced thermoplastics are advancing, enabling wing spar and fuselage panel applications where mass reduction translates directly to fuel efficiency gains.
Market Restraints
- Flake quality variability:Graphene feedstock from Chinese suppliers exhibits inconsistent layer counts and defect densities, forcing manufacturers to maintain redundant qualification programs across multiple sources.
- Plasma functionalization capex intensity:Surface modification equipment requires specialized vacuum chambers and gas handling systems that lock up capital for mid-scale producers.
- Carbon fiber incumbent substitution resistance:Toray and Hexcel have decades of aerospace qualification data that graphene composite suppliers must replicate at comparable cost structures.
Strategic Opportunities
- India automotive supplier integration:PLI scheme incentives for advanced materials are drawing composite converters to Chennai and Pune manufacturing zones for domestic EV platform supply.
- Wind turbine blade root reinforcement:Offshore turbine OEMs are specifying graphene-epoxy hybrids for lightning strike protection and fatigue resistance in North Sea installations.
- ISO/TC 229 harmonization:Converging nanotechnology measurement standards are reducing procurement specification conflicts between ECHA and EPA test protocols, lowering cross-border certification costs.
Industry Challenges
- Interlaminar shear strength prediction:Finite element modeling of graphene-polymer interfaces requires specialized multiscale simulation expertise that resides in only a handful of academic and national laboratory programs.
- Aerospace certification timeline compression:FAA and EASA qualification cycles for primary structural applications extend 7-10 years, locking working capital in pre-revenue development phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphene Composites Market |
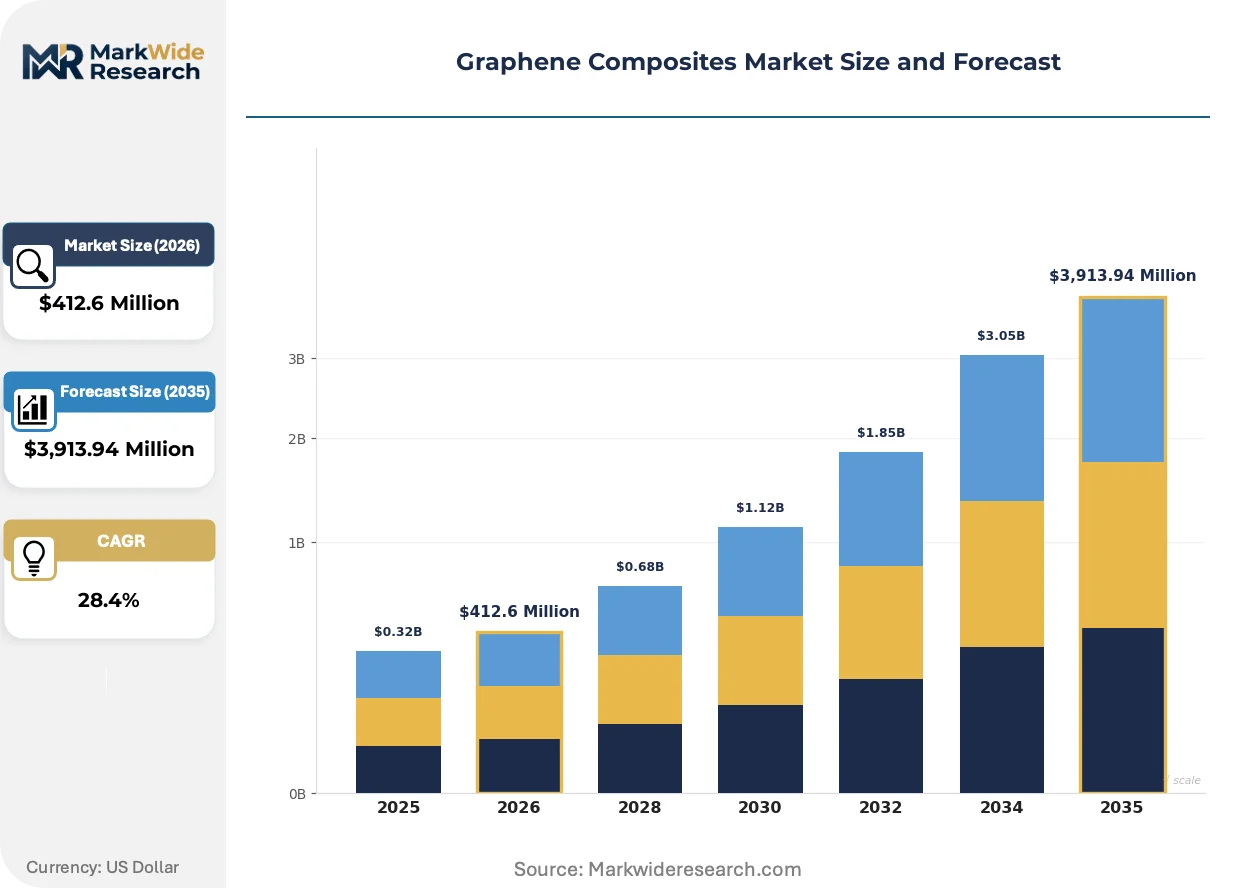
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $3,913.94 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanocomposites, Conductive Polymers, Biomedical Devices, Coatings End User: Aerospace, Automotive OEMs, Electronics, Sports Equipment Application: Energy Storage, Thermal Management, Structural Reinforcement, Sensors Distribution Channel: Direct Sales, Online Retail, Distributors, Manufacturers |
| Companies Covered | XG Sciences, Versarien, Haydale Graphene Industries, The Sixth Element, Graphenea, Directa Plus, NanoXplore, Carbon Rivers, First Graphene, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphene Composites Market Strategic Shifts & Innovations
Functionalization chemistry and dispersion processing are the twin technical battlegrounds where graphene composite performance claims get validated or invalidated, determining which suppliers survive the transition from pilot-scale to qualified production.
Few-layer graphene dispersion technology is consolidating around aqueous and solvent-based processing routes that achieve uniform exfoliation without structural damage. Aerospace laminators and battery electrode coaters are specifying these dispersions for viscosity-controlled deposition. The technology is consolidating supplier margins toward those with patented exfoliation IP and captive flake sourcing.
EPA toxicity evaluations under TSCA Section 5 are creating new product registration pathways for graphene nanoplatelets used in consumer electronics housings. Industrial consequences include mandatory 90-day inhalation studies that add six-figure costs to new material introductions. Electronics OEMs with US manufacturing footprints are prioritizing suppliers with completed EPA registrations.
Buyers are consolidating graphene composite procurement under centralized technical qualification teams rather than decentralized plant-level purchasing. Tier-one automotive suppliers are displacing spot-market transactions with framework agreements that lock in flake quality specifications and volume commitments. This pattern is most visible in Germany's automotive supplier corridor, where BMW and Mercedes-Benz platform teams enforce harmonized material approval processes.
Graphene Composites Market Segmentation
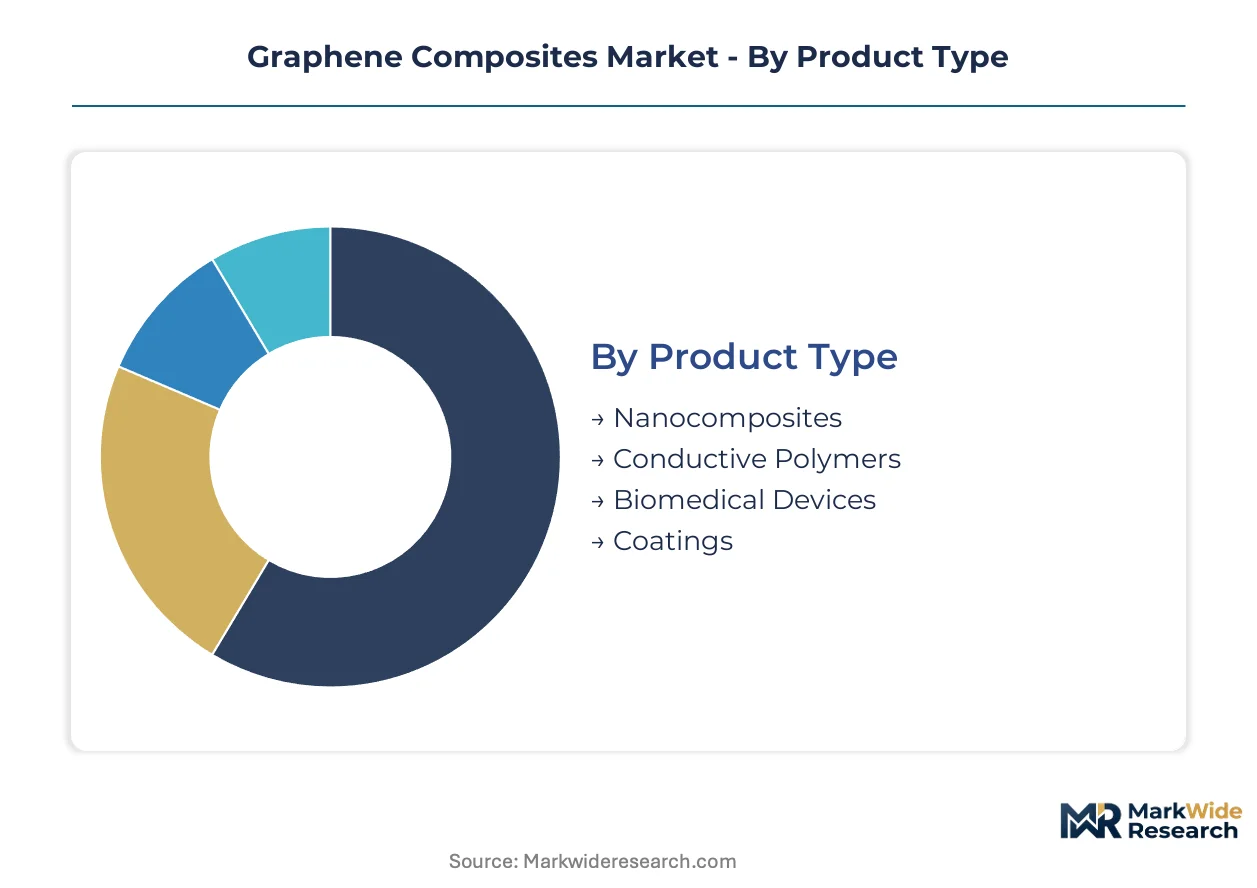
Graphene composite procurement splits sharply between commodity-scale polymer additives and qualification-intensive structural laminates. Understanding where volume concentrates versus where margins accumulate determines supplier positioning and R&D allocation across the value chain.
Product Type:
Nanocomposites dominate tonnage through polymer masterbatch supply, while biomedical devices command the steepest price premiums per gram.
- Nanocomposites:Polymer matrices loaded with graphene nanoplatelets achieve tensile modulus improvements exceeding 50% at sub-5% filler loadings. Automotive underhood components in Germany's supplier corridor specify these for heat distortion resistance.
- Conductive Polymers:Percolation thresholds below 0.1 wt% enable EMI shielding and static dissipation without compromising mechanical properties. South Korean battery manufacturers are locking in multi-year supply agreements for electrode binder applications.
- Biomedical Devices:Orthopedic implants and neural interfaces exploit graphene's biocompatibility and electrical conductivity for signal transduction.
- Coatings:Anti-corrosion marine and industrial formulations leverage barrier properties against oxygen and water ingress.
Mature deployment sits with nanocomposites. Newer deployment is concentrated in biomedical devices.
End User:
Aerospace and automotive OEMs drive qualification spending, while electronics manufacturers prioritize throughput and batch consistency.
- Aerospace:Primary structural applications require FAA and EASA certification cycles spanning 7-10 years. Wing spar and fuselage panel programs at Toulouse and Hamburg manufacturing clusters are advancing thermoplastic graphene laminates.
- Automotive OEMs:BMW and Mercedes-Benz platform teams enforce harmonized material approval processes across Stuttgart and Munich supplier networks. EV battery enclosures and lightweight body-in-white components are the focus applications.
- Electronics:Consumer device housings and flexible circuits demand EPA TSCA Section 5 registration compliance for US manufacturing footprints.
- Sports Equipment:Cycling frames and tennis rackets exploit stiffness-to-weight ratios for premium positioning.
Procurement maturity clusters with aerospace. Volume scaling is accelerating fastest through automotive OEMs.
Application:
Structural reinforcement absorbs the deepest engineering resources, while energy storage applications are expanding most quickly through solid-state battery development.
- Energy Storage:Graphene-enhanced anodes deliver conductivity and cycle stability that lithium-silicon architectures demand. Japanese and South Korean battery developers are specifying these for next-generation solid-state platforms.
- Structural Reinforcement:Interlaminar shear strength requirements for primary aerospace structures lock working capital in pre-revenue development phases. Multiscale simulation expertise resides in only a handful of academic and national laboratory programs.
- Thermal Management:Heat spreaders and interface materials exploit in-plane thermal conductivity exceeding 3000 W/mK.
- Sensors:Strain gauges and biosensors leverage piezoresistive and electrochemical response characteristics.
Established qualification pathways exist for structural reinforcement. Steepest expansion trajectory is concentrated in energy storage.
Distribution Channel:
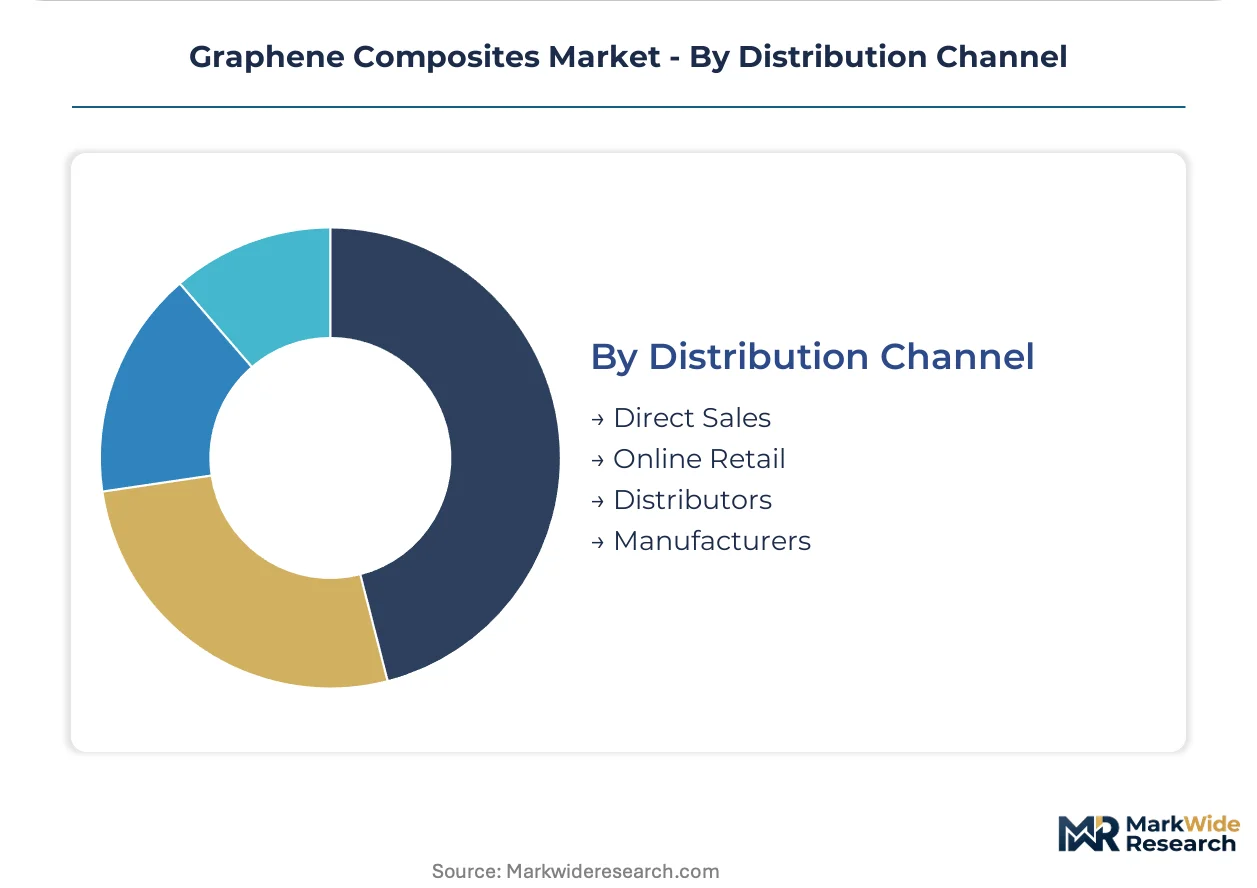
Direct sales capture framework agreements from tier-one manufacturers, while distributors serve fragmented mid-scale converters.
- Direct Sales:Centralized technical qualification teams at BMW, Mercedes-Benz, and major battery OEMs displace spot-market transactions with multi-year flake quality specifications and volume commitments.
- Distributors:Regional inventory positioning serves composite converters in India's Chennai and Pune manufacturing zones under PLI scheme incentives.
- Online Retail:Research-grade materials and small-batch dispersions reach academic and startup R&D programs.
- Manufacturers:Captive integration by graphene producers into downstream composite fabrication.
Relationship depth concentrates with direct sales. Channel experimentation is most visible through distributors in emerging manufacturing zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Graphite flake deposits in China's Heilongjiang province supply precursor material for graphene exfoliation, anchoring Asia-Pacific production capacity. German automotive OEMs and South Korean battery developers compete for qualified supply from this feedstock base.
United States
Michigan-based powder production campuses serve North American aerospace and automotive demand. EPA toxicity evaluations under TSCA Section 5 create registration barriers that favor established suppliers with completed inhalation studies. Detroit-Windsor corridor manufacturers specify graphene-enhanced thermoplastics for lightweighting programs.
Germany
BMW and Mercedes-Benz platform teams enforce harmonized material approval processes across supplier networks. REACH compliance acceleration through ECHA registration pathways reduces procurement ambiguity for nanomaterial classifications. Stuttgart and Munich industrial corridors concentrate tier-one automotive composite demand.
China
Battery developers in Shenzhen and Dongguan specify graphene-enhanced anodes for solid-state lithium-silicon architectures. MIIT industrial standards for nanomaterials shape domestic qualification protocols. Yangtze River Delta production clusters integrate flake sourcing with downstream dispersion processing.
South Korea
LG Energy Solution and Samsung SDI lock in multi-year supply agreements for electrode binder applications. MFDS biocompatibility standards guide medical device composite development. Gyeonggi-do manufacturing complexes host qualified graphene dispersion production for export markets.
United Kingdom
Plasma functionalization patents sustain supplier differentiation in European specialty markets. UK Research and Innovation funding accelerates aerospace qualification programs. Manchester-Liverpool corridor institutions anchor academic-industry partnerships for multiscale simulation expertise.
Graphene Composites Market Key Industry Players
Global majors compete with regional champions across powder supply and dispersion processing capabilities. The vendor base separates into flake producers, functionalization specialists, and downstream composite fabricators with captive integration. Three archetypes dominate: scale-driven powder suppliers, IP-anchored functionalization houses, and application-focused compounders. Capacity expansion and strategic patent licensing constitute the primary competitive moves as qualification timelines compress.
Within the scale-driven tier, XG Sciences exemplifies North American powder supply concentration. Haydale Graphene Industries occupies a position among European functionalization specialists with plasma processing capabilities. Versarien represents the dispersion-focused archetype through its patented few-layer graphene supply to battery and aerospace laminators.
| Leading Market Players |
|---|
| XG Sciences |
| Versarien |
| Haydale Graphene Industries |
| The Sixth Element |
| Graphenea |
| Directa Plus |
| NanoXplore |
| Carbon Rivers |
| First Graphene |
| Others |
Cost & Logistics Intelligence
Graphite flake spot indices from China's Heilongjiang province cascade through three distinct pricing tiers as material progresses from unprocessed feedstock to qualified aerospace-grade dispersions, with ECHA REACH registration status separating premium suppliers from commodity traders in procurement negotiations.
Pricing Analysis
Technical service bundling separates qualified suppliers from spot-market traders, with EPA TSCA Section 5 registration completion and aerospace certification support commanding 40-60% premia over unbundled powder supply. Three-tier pricing structure across premium, standard, and economy levels reflects flake quality specifications, layer count consistency, and functionalization chemistry depth. Pricing pressure stems from Chinese feedstock oversupply compressing margins at the powder tier while battery OEMs consolidate procurement leverage. Automotive tier-ones exhibit highest price sensitivity due to platform cost targets, whereas biomedical device manufacturers prioritize batch consistency over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Detroit-Windsor buffer qualified inventory against flake quality variability, enabling just-in-time delivery to aerospace laminators and battery electrode coaters. Raw material supply draws from China's Heilongjiang graphite deposits, South Korean refined flake, and North American synthetic graphite alternatives. Single-source vulnerability concentrates in plasma functionalization equipment, where specialized vacuum chamber suppliers maintain 18-month order backlogs. Distribution runs through direct sales channels for tier-one OEMs and authorized distributors for mid-scale composite converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where ECHA REACH registration pathways for nanomaterials create barrier-to-entry moats favoring suppliers with completed toxicity dossiers and aerospace qualification data packages.
For Market Incumbents: Cement supply security through captive flake sourcing agreements with Heilongjiang producers and backward integration into plasma functionalization capacity. Carbon fiber incumbents Toray and Hexcel represent substitution threats requiring accelerated FAA certification timeline compression to defend structural laminate positioning. Prioritize EASA qualification data replication for wing spar applications at Toulouse manufacturing clusters.
For New Entrants and Emerging Players: Enter via India's PLI scheme incentives for advanced materials, targeting Chennai and Pune EV platform supply where domestic qualification requirements are less encumbered than European aerospace pathways. Wind turbine blade root reinforcement for North Sea installations offers penetrable white space with shorter OEM qualification cycles. Lead with graphene-epoxy hybrid formulations for lightning strike protection applications.
For Investors and Strategic Acquirers: The window for entry favors functionalization specialists with patented plasma processing IP and completed EPA registrations, positioning ahead of solid-state battery electrode specification lock-ins. Acquisition targets should exhibit captive flake sourcing and dispersion processing capabilities under single ownership. Monitor FAA certification framework advancement for thermoplastic graphene laminates as inflection signal for aerospace demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flake Sourcing | Secures Heilongjiang feedstock supply against quality variability and tariff exposure. |
| Plasma Functionalization Capacity Expansion | Addresses 18-month equipment backlogs locking mid-scale producers out of qualified supply. |
| EASA/FAA Certification Acceleration | Compresses 7-10 year aerospace qualification timelines to displace carbon fiber incumbents. |
| Long-term Battery Supply Agreements | Locks in LG Energy Solution and Samsung SDI demand ahead of solid-state platform launches. |
| Joint Venture in India PLI Zones | Captures Chennai and Pune EV platform supply under domestic content requirements. |
Research Approach
Trade publications, ECHA registration databases, and SEC filings from graphene suppliers formed the secondary backbone, cross-referenced with primary interviews involving composite procurement directors at BMW and Mercedes-Benz platform teams, technical qualification managers at South Korean battery developers, plasma functionalization equipment specialists, and aerospace certification engineers at Toulouse manufacturing clusters. Bottom-up volume modeling from flake production capacities and top-down demand segmentation from end-use applications were triangulated against customs data for graphite nanoplatelet trade flows.
Historical capacity utilization and qualification timeline trends informed projection frameworks across the analysis window, with segmentation modeling spanning product type (nanocomposites, conductive polymers, biomedical devices, coatings), end user (aerospace, automotive OEMs, electronics, sports equipment), application (energy storage, structural reinforcement, thermal management, sensors), and distribution channel (direct sales, distributors, online retail, captive integration). CAGRs were derived from elasticity-adjusted demand curves incorporating solid-state battery development timelines and EU Green Deal material efficiency mandate compliance deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FAA certification delays or Chinese export restriction scenarios. Decision-makers should treat outputs as directional within the stated assumption set, acknowledging that flake quality variability and interlaminar shear strength prediction limitations could materially revise adoption timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Fiber Reinforced Polymer (FRP) Panels and Sheets Market
Composite Materials
Graphite Felt Market
Composite Materials
Global Geocomposites Market
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
FRP Reactor Market
Composite Materials
Composite Metal Finishing Market
Composite Materials
Long-Fiber Thermoset Composites Market
Composite Materials
Stone Plastic Composite Flooring Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Composite Coatings Market
Composite Materials
Graphite Carbon Raiser Market
Composite Materials
Pultrusion Market
Composite Materials
North America Molded FRP Grating Market
Composite Materials
Automotive Carbon Fiber Materials Market
Composite Materials
Global FRP Sheets and Panels Market
Composite Materials
Global Composites Cylinder Market