
 Balsa Core Materials Market | 2026-2036
Balsa Core Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Balsa Core Materials Market Intelligence
Modular sandwich panel kits is shifting procurement patterns across marine and wind energy OEMs, reducing on-site labor and scrap rates. Gurit Holding AG leverages its vertically integrated balsa supply chain from Ecuadorian plantations to European finishing facilities. DIAB International AB competes through specialized high-density formulations targeting aerospace tier suppliers. CoreLite Inc. anchors its position in the Americas with regional lamination capacity and marine distributor networks.
Balsa core materials are lightweight end-grain wood structures with densities ranging from 40 to 320 kg per cubic meter, engineered as the central layer in sandwich composites to absorb shear stress while minimizing mass. Natural balsa dominates volume shipments for wind blade roots and marine hulls where cost sensitivity exceeds performance premiums. Laminated balsa captures margin pools in aerospace interior panels requiring FST certification and lot-to-lot consistency. Composite balsa, blended with synthetic reinforcements, leads growth in offshore wind nacelle covers exposed to salt fatigue and UV degradation.
EMA and ECHA frameworks in Europe govern chemical content and end-of-life recyclability for balsa-containing composites entering marine and construction applications. The EU Green Deal and national carbon accounting rules in Germany and France are embedding lifecycle emissions into public procurement scoring for wind farm components. Buyers must monitor evolving FSC and PEFC chain-of-custody requirements as Ecuadorian export authorities tighten harvest quotas to combat illegal logging in the Pacific coastal zones.
Market Dynamics
Rotor diameter expansion in wind energy is compressing blade design cycles and forcing core material specification changes that favor balsa's shear-strength-to-weight ratio over synthetic alternatives.
Growth Catalysts
- EU Green Deal lifecycle mandates:German and French carbon accounting rules now embed embodied emissions into wind farm procurement scoring, directing buyers toward certified balsa with verifiable chain-of-custody documentation.
- Offshore wind nacelle scaling:Salt fatigue and UV exposure requirements in North Sea installations are accelerating specification of composite-reinforced balsa formulations for secondary structural covers.
- Ecuadorian plantation certification:FSC and PEFC harvest quota enforcement is professionalizing raw material flows and reducing illegal logging risk for European laminate finishers.
Market Restraints
- Single-origin supply concentration:Pacific coastal Ecuador supplies the majority of global raw balsa, exposing processors to weather-related harvest disruptions and export quota volatility.
- REACH chemical compliance costs:ECHA substance restrictions on resin systems used in balsa lamination are elevating formulation testing expenses for European core material finishers.
- Synthetic foam substitution:PET and PVC structural foams are capturing specification share in marine superstructure applications where lot-to-lot consistency outweighs balsa's weight advantage.
Strategic Opportunities
- Modular sandwich panel kits:Pre-cut core kits with bonded scrim layers are reducing on-site labor and scrap rates for wind blade OEMs in Denmark and Spain.
- Aerospace FST certification gap:Laminated balsa with fire-smoke-toxicity compliance remains underpenetrated in commercial aircraft interior panels relative to aramid honeycomb.
- India PLI scheme alignment:Domestic wind component manufacturing incentives are creating demand for localized balsa finishing capacity to serve nacelle assembly hubs in Gujarat and Tamil Nadu.
Industry Challenges
- Skilled laminator scarcity:End-grain balsa processing requires specialized moisture-control expertise that is concentrating among aging workforces in Ecuadorian sawmills and European finishing facilities.
- Certification timeline compression:Lot-to-lot density verification for aerospace-grade balsa is extending quality assurance cycles as FST testing protocols tighten under EASA guidance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Balsa Core Materials Market |
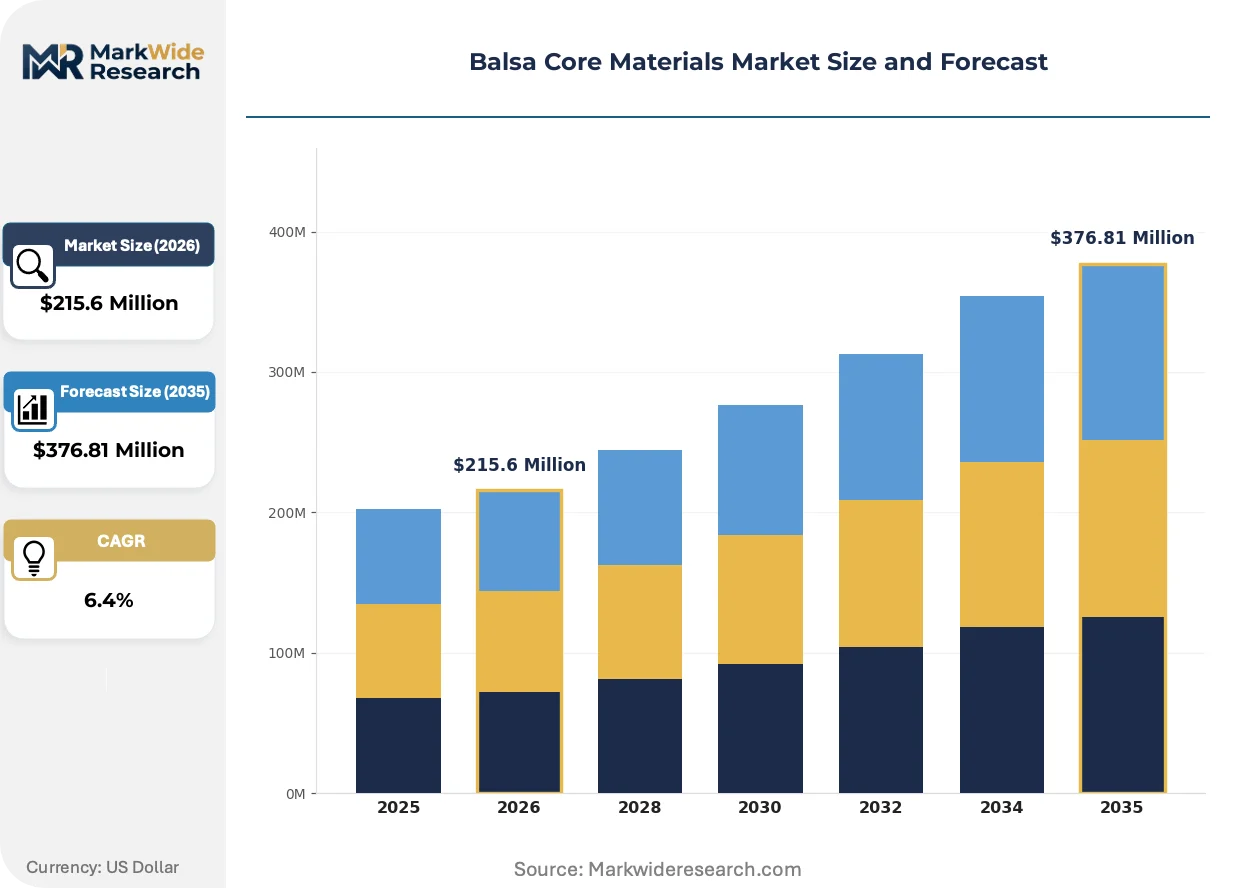
| Market Size in 2026 | $215.6 Million |
| Market Size in 2035 | $376.81 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Balsa, Laminated Balsa, Composite Balsa, Hybrid Balsa Industry Vertical: Aerospace, Marine, Wind Energy, Construction Application: Structural Components, Insulation, Sandwich Panels, Aerospace Parts Density: Low Density, Medium Density, High Density, Ultra High Density |
| Companies Covered | CoreLite Inc., Carbon-Core Corporation, Gurit Holding AG, Evonik Industries AG, Nord Compensati S.p.A., 3A Composites, Schweiter Technologies AG, Bcomp Ltd., DIAB International AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Balsa Core Materials Market Strategic Shifts & Innovations
Digital density mapping and automated scarf jointing are compressing core material variability and enabling just-in-time kit delivery to wind blade mold floors.
Automated optical scanning systems for end-grain density grading are electrifying quality assurance workflows in Ecuadorian primary processing facilities. Wind blade manufacturers in Denmark and Germany are adopting scanned-lot certification to reduce in-mold rejection rates. This precision infrastructure is compressing the specification gap between natural and synthetic core materials.
REACH authorization requirements for diisocyanate-containing adhesives are forcing laminate finishers toward water-based resin formulations. ECHA's 2023 restriction is elevating capital requirements for European balsa core processors. Marine OEMs in Italy and France are accelerating supplier audits to verify compliance ahead of enforcement deadlines.
Direct mill-to-mold procurement contracts are disintermediating traditional distributor networks for high-volume wind blade producers. Tier-one OEMs in Spain and Brazil are establishing captive balsa inventory positions at blade manufacturing campuses. This channel compression is visible most acutely in contracts exceeding five hundred cubic meters annual volume.
Balsa Core Materials Market Segmentation
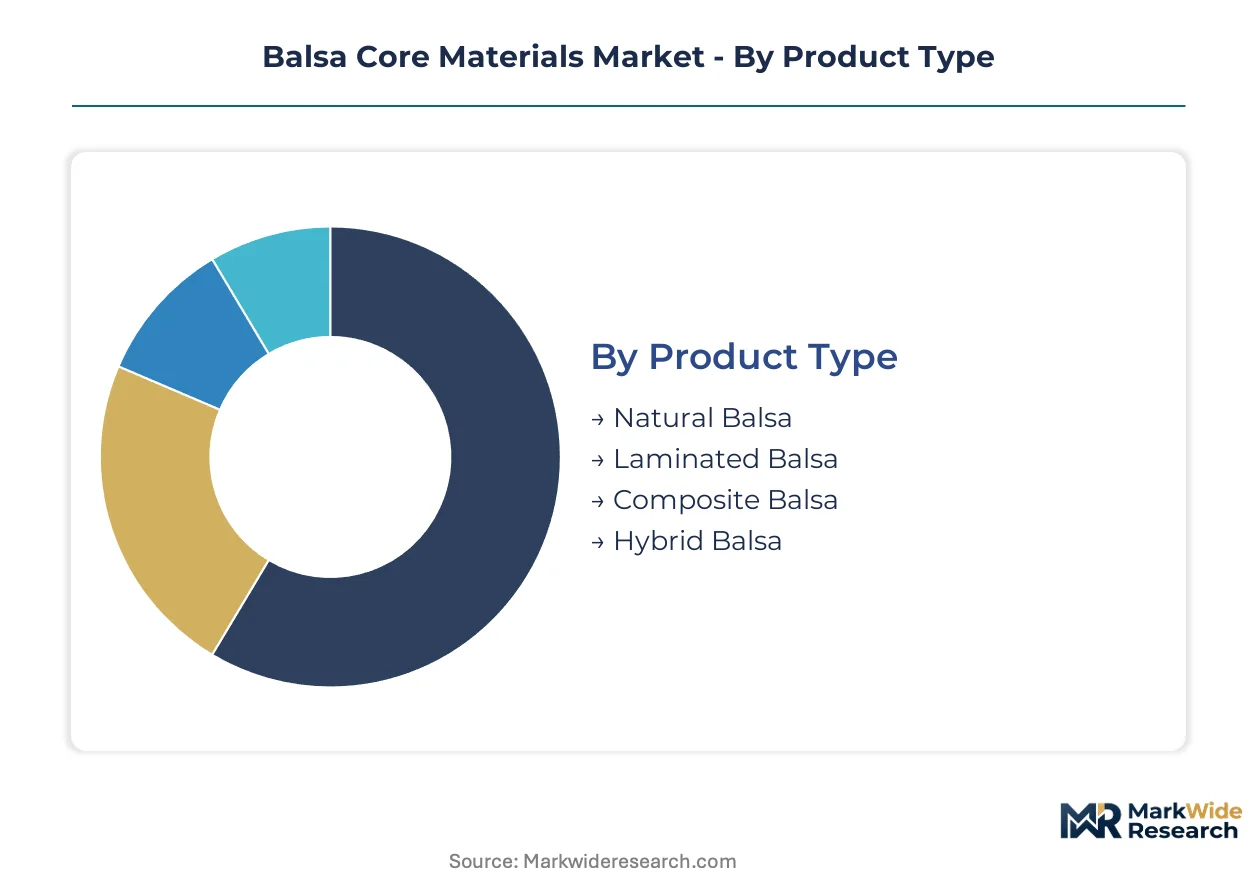
Balsa core materials exhibit distinct performance profiles across product formulations and density grades. Specification choices cascade through manufacturing economics, certification requirements, and end-use durability demands.
Product Type:
Natural balsa operates as standalone feedstock for cost-sensitive applications, while laminated and composite variants embed into engineered systems requiring certification traceability.
- Natural Balsa:Raw end-grain timber with densities from 40 to 320 kg per cubic meter, processed through kiln drying and density grading. Wind blade roots in Denmark and marine hulls in Italy concentrate procurement here, driven by shear-strength-to-weight ratios that outperform synthetic foams at equivalent mass. REACH compliance costs for resin systems are compressing margins for European finishers sourcing this grade.
- Laminated Balsa:Cross-bonded sheets with scrim reinforcement enabling lot-to-lot consistency for aerospace interior panels. EASA fire-smoke-toxicity protocols are extending quality assurance cycles for this segment as certification timelines tighten.
- Composite Balsa:Blended with synthetic reinforcements for salt fatigue resistance in offshore wind nacelle covers.
- Hybrid Balsa:Multi-material cores combining balsa with PET or PVC layers for tuned stiffness gradients.
Natural balsa leads volumes today; composite balsa is gaining share fastest.
Industry Vertical:
Cost tiers separate aerospace certification premiums from marine commodity procurement and wind energy volume contracts.
- Wind Energy:Rotor diameter expansion past 120 meters is compressing blade design cycles and forcing core specification changes. Pre-cut kit procurement from Ecuadorian plantations through Danish finishing facilities dominates this vertical.
- Marine:Hull and superstructure applications balance weight reduction against lot-to-lot consistency requirements. Italian and French OEMs are accelerating supplier audits for diisocyanate adhesive compliance under ECHA restrictions.
- Aerospace:Laminated balsa with FST certification penetrates commercial aircraft interior panels.
- Construction:Modular sandwich panels for temporary structures and facade systems.
Wind energy commands the largest volume position; aerospace delivers the steepest margin expansion trajectory.
Application:
Structural loading conditions and thermal performance requirements segment procurement specifications across end-use categories.
- Sandwich Panels:Pre-cut core kits with bonded scrim layers reduce on-site labor and scrap rates. Spain and Brazil host direct mill-to-mold contracts exceeding five hundred cubic meters annually.
- Structural Components:Blade spar caps and marine bulkheads absorb shear stress through end-grain orientation. Automated optical scanning for density grading is electrifying quality assurance workflows in Ecuadorian facilities.
- Insulation:Thermal and acoustic barrier applications in building systems.
- Aerospace Parts:Seat backs, galleys, and lavatory modules requiring FST compliance.
Sandwich panels anchor current procurement volumes; structural components in wind blades are expanding most quickly.
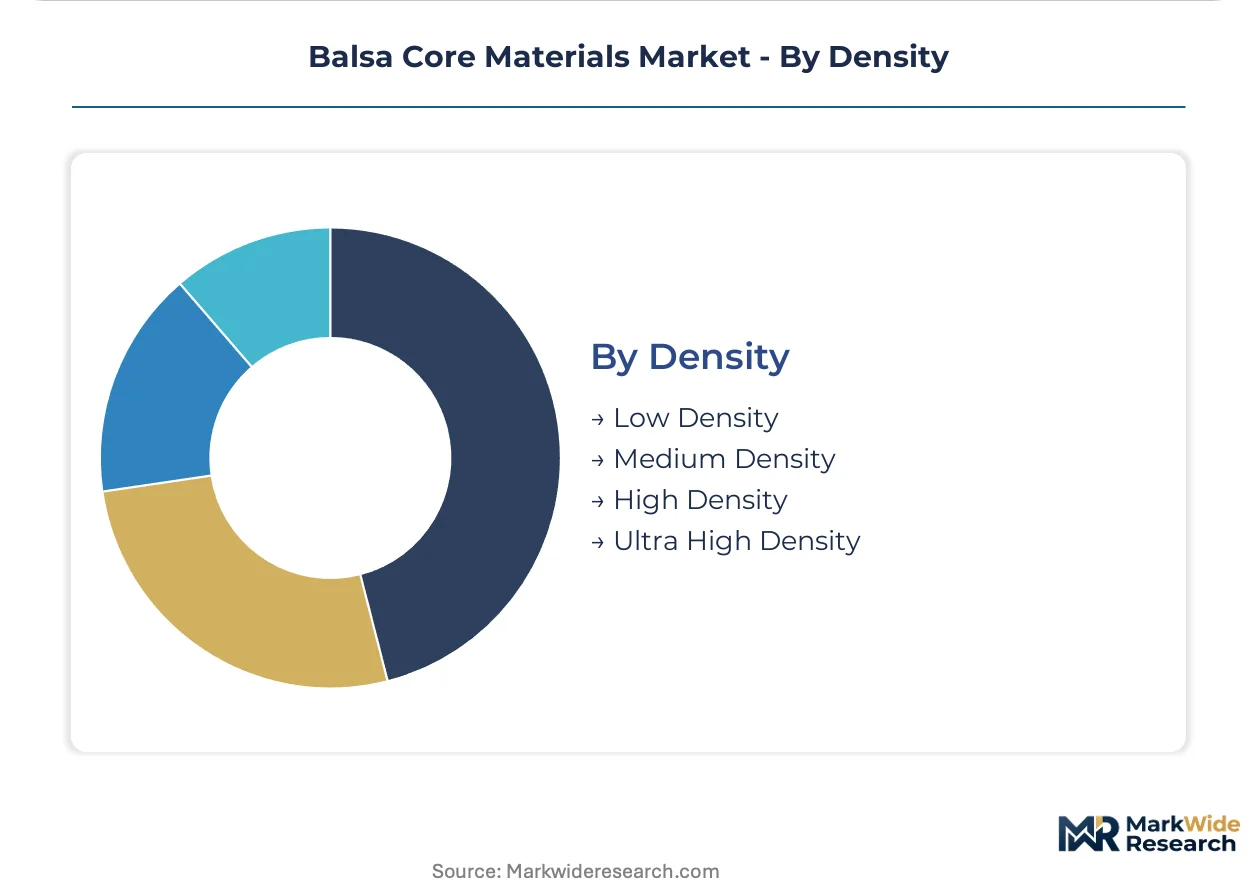
Density:
Grade stratification aligns raw material yield with performance specifications and certification premiums.
- Medium Density:100-160 kg per cubic meter grades balance structural performance with material yield. Marine hull laminators in Italy and wind blade manufacturers in Germany specify this grade for primary load-bearing cores.
- High Density:160-240 kg per cubic meter for localized reinforcement in blade root sections and marine hardware attachment points. FSC chain-of-custody documentation is tightening harvest quota enforcement for Ecuadorian exports of this grade.
- Low Density:40-100 kg per cubic meter for non-structural insulation and fill applications.
- Ultra High Density:240-320 kg per cubic meter for aerospace local reinforcement and hardware inserts.
Medium density dominates shipment volumes; high density is climbing the fastest as rotor diameters lengthen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Balsa core materials originated from Ecuador's Pacific coastal plantations, where the species thrived in tropical lowland conditions. German and Danish wind blade manufacturers pioneered industrial-scale adoption during the early offshore wind buildouts of the 2000s.
Ecuador
Coastal provinces of Guayas and Los Ríos host the majority of global balsa cultivation, supplying raw end-grain timber to international laminators. The Ministry of Environment's harvest quota enforcement under FSC and PEFC frameworks is tightening export documentation requirements. Sawmill clusters around Guayaquil are deploying automated optical scanning systems to electrify density grading workflows.
Germany
Wind turbine OEMs in Hamburg and Bremen specify medium-density balsa for blade roots exceeding 120-meter rotor diameters. National carbon accounting rules under the EU Green Deal embed embodied emissions into public procurement scoring for offshore wind farms. Finishing facilities in Lower Saxony are migrating toward water-based resin formulations to meet ECHA diisocyanate restrictions.
Denmark
Pre-cut sandwich panel kit procurement dominates blade manufacturing in Esbjerg and Ringkøbing, reducing on-site labor and scrap rates. Danish suppliers enforce REACH compliance documentation across resin systems used in balsa lamination. Direct mill-to-mold contracts exceeding five hundred cubic meters annually are compressing traditional distributor channels.
Spain
Blade producers in Navarre and Castile-La Mancha are expanding captive balsa inventory positions at manufacturing campuses. Spanish renewable energy auctions under national climate targets are accelerating nacelle assembly capacity. Local finishing operations are aligning with EU Green Deal lifecycle mandates for verifiable chain-of-custody documentation.
India
Wind component manufacturing incentives under the PLI scheme are creating demand for localized balsa finishing capacity in Gujarat and Tamil Nadu. State-level renewable purchase obligations are driving nacelle assembly hub development around Ahmedabad and Chennai. Domestic laminators are negotiating technical partnerships with Ecuadorian plantation operators to secure raw material flows.
Balsa Core Materials Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification tiers and vertical integration depth. The vendor base stratifies into three tiers: plantation-integrated finishers commanding FSC-certified supply chains, regional laminators serving marine distributors, and synthetic foam specialists capturing specification share in consistency-sensitive applications. Dominant competitive moves include backward integration into Ecuadorian raw material sourcing and geographic expansion of kit-finishing capacity near blade manufacturing clusters.
Within the plantation-integrated tier, Gurit Holding AG represents captive supply chain control from Ecuadorian harvesting through European finishing. DIAB International AB exemplifies specialized high-density formulation capabilities targeting aerospace certification requirements. CoreLite Inc. anchors regional lamination capacity and marine distributor networks across the Americas. These three entities illustrate distinct archetype positioning without exhausting the competitive field.
| Leading Market Players |
|---|
| CoreLite Inc. |
| Carbon-Core Corporation |
| Gurit Holding AG |
| Evonik Industries AG |
| Nord Compensati S.p.A. |
| 3A Composites |
| Schweiter Technologies AG |
| Bcomp Ltd. |
| DIAB International AB |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between FSC-certified plantation balsa and spot-market raw timber creates parallel pricing architectures that cascade through Ecuadorian harvest quotas, European REACH compliance testing, and wind blade OEM procurement scoring. Buyers absorbing carbon-accounting premiums under EU Green Deal mandates face structurally different landed costs than marine distributors sourcing uncertified grades through traditional channels.
Pricing Analysis
Three-tier pricing structure across aerospace-certified laminated, industrial-grade natural, and commodity spot balsa segments dominates transaction architecture. Price differentiation rests on FSC chain-of-custody documentation and EASA fire-smoke-toxicity certification tiers. Cost compression in natural balsa grades is intensifying because Ecuadorian export quota enforcement is constraining raw material yield. Marine distributors in Italy and France exhibit highest price sensitivity; aerospace tier-one suppliers in Germany accept premium positioning for lot-to-lot consistency guarantees.
Supply Chain Analysis
Single-source vulnerability sits with Ecuador's Pacific coastal provinces, where Guayas and Los Ríos plantations supply the majority of global raw end-grain timber. The supply chain draws from balsa cultivation clusters, European lamination facilities, and regional kit-finishing operations near blade manufacturing campuses. Tariff exposure through evolving EU-Andean trade preferences and harvest quota volatility under FSC enforcement constitute the dominant structural risk. Distribution runs through direct mill-to-mold contracts for high-volume wind energy OEMs and marine distributor networks for fragmented hull laminators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in balsa core materials rests on automated density grading technology compressing quality assurance cycles and shifting specification share toward certified premium grades. Pre-cut kit procurement models are capturing value previously lost to on-site scrap and labor inefficiency.
For Market Incumbents: Extend backward integration into Ecuadorian plantation operations to secure FSC-certified raw material flows before harvest quota tightening accelerates. Invest in automated optical scanning infrastructure to reduce in-mold rejection rates for Danish and German wind blade OEMs. Synthetic foam substitution in marine superstructure applications represents the most pressing substitute threat requiring certification-based differentiation response. For New Entrants and Emerging Players: Capture localized balsa finishing capacity demand created by India's PLI scheme incentives for domestic wind component manufacturing in Gujarat and Tamil Nadu. Aerospace FST certification gaps in commercial aircraft interior panels offer the most penetrable white-space target relative to established aramid honeycomb positions. Technical partnerships with Ecuadorian plantation operators provide the essential go-to-market anchor for raw material security. For Investors and Strategic Acquirers: Consolidation pressure builds where aging skilled laminator workforces concentrate in Ecuadorian sawmills and European finishing facilities, eroding operational scalability. Acquisition target archetypes include regional laminators with established marine distributor networks and dormant certification capabilities for aerospace tier supply. Watch automated kit-finishing capacity buildout near Spanish and Brazilian blade manufacturing clusters as the primary inflection signal for supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Operations | FSC-certified raw material security locks in Ecuadorian harvest quota access before enforcement tightens. |
| Automated Optical Scanning Deployment | Density grading precision reduces wind blade OEM in-mold rejection rates and compresses quality cycles. |
| Pre-cut Kit Finishing Capacity Expansion | Localized lamination near Spanish and Danish blade campuses captures value from scrap reduction. |
| Water-based Resin Formulation Migration | ECHA diisocyanate restriction compliance preserves European market access for laminate finishers. |
| Aerospace FST Certification Investment | EASA protocol alignment opens commercial aircraft interior panel specification share against aramid honeycomb. |
Research Approach
Bottom-up wind blade and marine hull demand modeling reconciled against top-down Ecuadorian plantation output and European lamination capacity tracking forms the analytical core. Primary interviews with wind turbine OEM procurement directors, marine laminator technical leads, Ecuadorian plantation operations managers, and aerospace tier supplier quality assurance heads combined with secondary validation from FSC chain-of-custody databases, ECHA substance restriction filings, EU Green Deal national implementation documents, and customs trade flow records. Top-down and bottom-up estimates were triangulated to resolve segmentation discrepancies.
Historical trendline analysis of balsa harvest volumes, laminate finishing capacity utilization, and end-use procurement patterns established baseline trajectories across the projection horizon. The analytical framework models product type, density grade, industry vertical, and application segments with regional regulatory cluster overlays. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion constraints. Forecast inputs incorporated rotor diameter expansion curves for wind energy and EASA certification timeline compression for aerospace.
Ecuadorian weather-related harvest disruptions, REACH authorization scope expansion for resin systems, and synthetic foam substitution acceleration in marine applications are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding FSC quota enforcement timelines and EU Green Deal procurement scoring implementation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
Decorative High-Pressure Laminates Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
FRP Reactor Market
Composite Materials
Composite Adhesives Market
Composite Materials
North America Molded FRP Grating Market
Composite Materials
Composite Rollers Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Composite Process Material Kits Market
Composite Materials
Core Material for Composites Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Long-Fiber Thermoset Composites Market
Composite Materials
Turbine Blade Material Market