
 MDI, TDI, and Polyurethane Market | 2026-2036
MDI, TDI, and Polyurethane Market Size, Share, and Industry Trends Forecast 2026-2036
MDI, TDI, and Polyurethane Market Intelligence
The reliance on traditional furniture and footwear manufacturing for polyurethane consumption is decoupling from growth in high-performance applications like automotive components and construction materials. BASF SE leverages its integrated production network to supply both commodity and specialty isocyanates across these diverse end-uses. Meanwhile, Covestro AG specializes in high-tech polymer materials, including advanced polyurethane systems for electric vehicles. Wanhua Chemical Group Co., Ltd. dominates the MDI supply chain with significant manufacturing scale in Asia.
Methylene diphenyl diisocyanate (MDI) and toluene diisocyanate (TDI) are key aromatic isocyanates that react with polyols to create polyurethane polymers. This reaction forms the characteristic urethane linkage, resulting in materials with exceptional versatility, from rigid foams to flexible elastomers. Within applications, foam products for insulation and cushioning remain the largest segment by volume, though elastomers offer higher margin potential. Polyether polyurethanes constitute the bulk of production, while polyester variants provide superior chemical and oil resistance for demanding industrial coatings.
The European Chemicals Agency (ECHA) imposes strict handling and registration requirements on diisocyanates under REACH. Similarly, the US Environmental Protection Agency (EPA) and China's Ministry of Ecology and Environment (MEE) regulate worker exposure and volatile organic compound (VOC) emissions. Future material selection will balance performance requirements against evolving regulations on chemical safety and circular economy principles.
Market Dynamics
The central dynamic is the bifurcation of the polyurethane value chain between high-volume, commoditized foam applications and high-performance, specialized systems. This split is driven by divergent end-market requirements and intensified by global regulatory pressures on chemical handling.
Growth Catalysts
- Bio-based Materials:Innovations in bio-based polyols and isocyanates, derived from sources like plant oils and sugars, align with corporate sustainability goals and circular economy principles, creating demand in green consumer products and construction.
- Energy Efficiency Mandates:Stringent building codes in Europe and North America requiring higher thermal insulation performance directly stimulate demand for polyurethane rigid foams in wall, roof, and pipe insulation applications.
- Infrastructure Investment:Large-scale public works and infrastructure projects, particularly within China's Belt and Road Initiative, consume significant volumes of polyurethane for coatings, sealants, and insulation materials.
Market Restraints
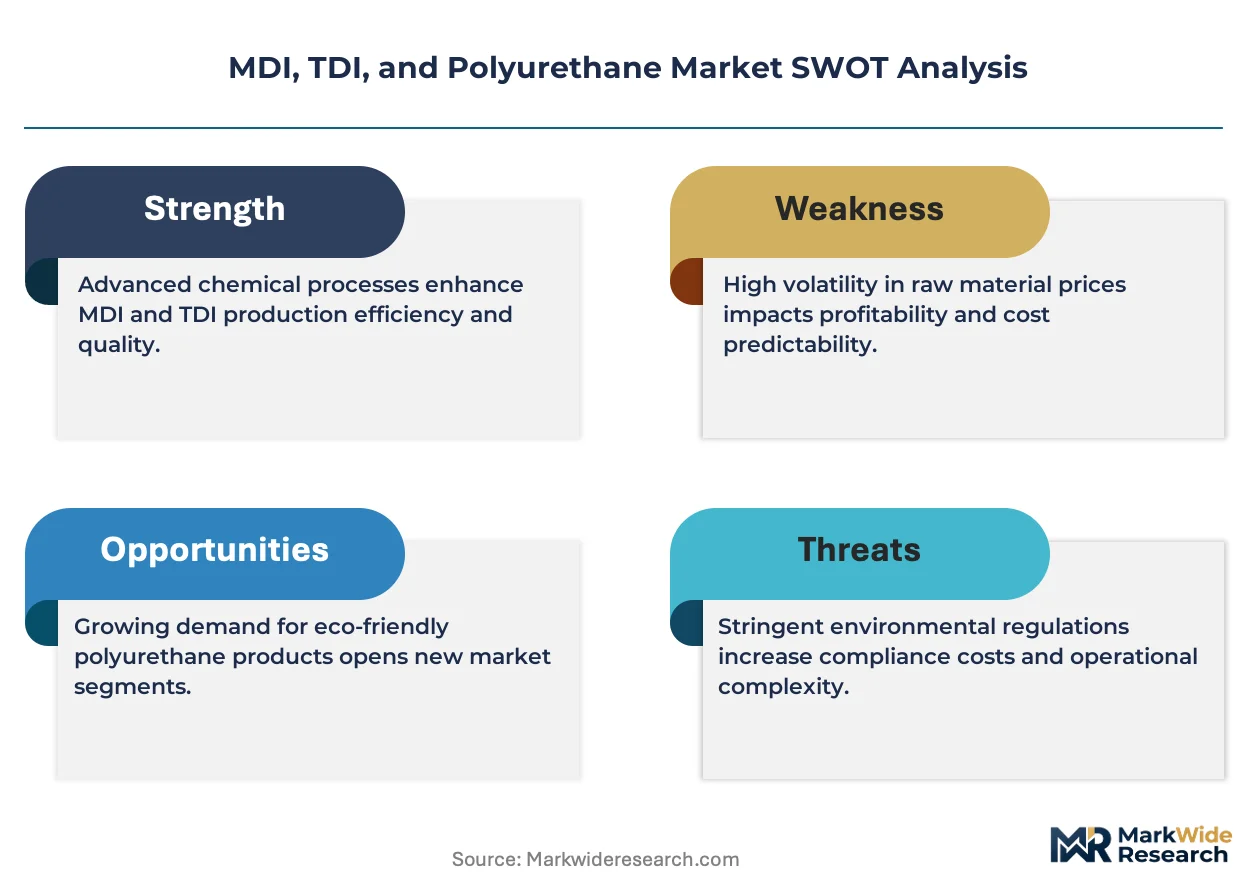
- Feedstock Volatility:The market is exposed to price and supply fluctuations of petrochemical precursors like benzene and toluene, which directly impacts MDI and TDI production costs and creates margin pressure for manufacturers.
- Regulatory Burden:Strict regulations, such as the European Chemicals Agency's (ECHA) REACH framework for diisocyanates, impose significant compliance costs related to worker training, handling protocols, and product registration.
- Supply Chain Concentration:The geographic concentration of world-scale MDI production facilities in Asia, particularly China, creates potential supply chain vulnerabilities and logistical risks for consumers in other regions.
Strategic Opportunities
- Electric Vehicle Systems:The shift to electric mobility creates new applications for specialized polyurethane elastomers and foams in battery pack encapsulation, thermal management, and lightweight structural components.
- Advanced Medical Devices:Biocompatible polyurethane elastomers offer significant potential in the development of next-generation medical devices, including catheters, wound dressings, and implantable components requiring flexibility and durability.
- Cold Chain Expansion:Growing demand for refrigerated logistics in emerging economies like India and Brazil presents an opportunity for high-performance polyurethane insulation panels used in refrigerated trucks, warehouses, and shipping containers.
Industry Challenges
- Capital Intensity:The construction of new, world-scale MDI and TDI production plants requires massive capital investment and long project timelines, creating high barriers to entry and limiting supply-side flexibility. -
- Divergent Global Regulations:Manufacturers face complexity and cost in developing products that comply with a patchwork of different regional chemical safety and environmental standards, such as those from the US EPA and China's MEE.
- Recycling Infrastructure:A lack of scaled, economically viable recycling technologies and infrastructure for post-consumer polyurethane products, especially mixed-material foams, hinders circularity and poses an end-of-life management challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MDI, TDI, and Polyurethane Market |
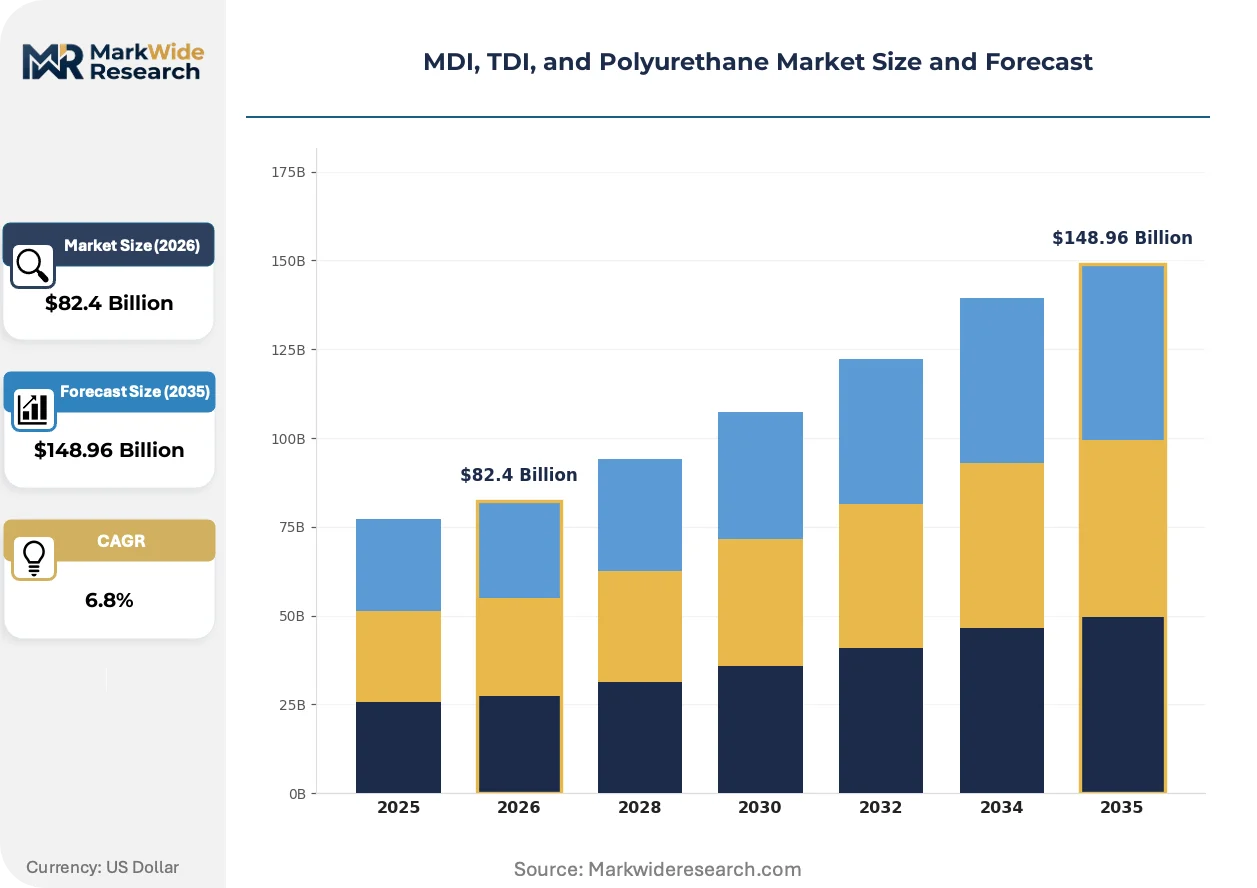
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $148.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MDI, TDI, Polyether Polyurethane, Polyester Polyurethane, Polycarbonate Polyurethane Application: Foam, Adhesives, Sealants, Elastomers, Coatings End User Industry: Furniture Manufacturing, Footwear Production, Transportation Manufacturing, Construction Materials, Consumer Goods Packaging Type: Drums, Bulk Tanks, Intermediate Bulk Containers, Flexible Bags |
| Companies Covered | Huntsman International LLC, Wanhua Chemical Group Co., Ltd., BASF SE, Mitsui Chemicals Inc., LANXESS AG, The Dow Chemical Company, DuPont de Nemours, Inc., Woodbridge Foam Corporation, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MDI, TDI, and Polyurethane Market Strategic Shifts & Innovations
Material science advancements are pushing polyurethane beyond its traditional applications in foam and furniture. The focus is on developing specialized systems that meet stringent performance and sustainability criteria for advanced industries like electric mobility and green construction.
Bio-based polyols and non-isocyanate polyurethane (NIPU) chemistries represent a significant product evolution. These materials, derived from renewable feedstocks or alternative reaction pathways, are gaining traction with manufacturers in the automotive and consumer goods sectors seeking to reduce their environmental footprint. This sustainable chemistry is expanding into rigid foams for certified green buildings and flexible foams for eco-conscious bedding, challenging the market dominance of conventional petrochemical-based polyurethane.
The European Union’s Green Deal and its associated policies are accelerating material-level changes. Frameworks like the Corporate Sustainability Reporting Directive (CSRD) compel manufacturers to provide detailed disclosures on environmental impact, forcing greater transparency in the polyurethane supply chain. The construction materials segment is most affected, as product specifiers increasingly use Environmental Product Declarations (EPDs) to select lower-carbon insulation and coating options.
A notable demand-side shift involves the unbundling of material supply from technical service. Large-volume consumers in sectors like automotive and appliances are building in-house formulation expertise, allowing them to purchase raw isocyanates and polyols directly from producers. This disintermediates traditional system houses and changes the sales model from providing blended systems to supplying pure chemical components. This pattern is most prominent in North America and Europe where large, sophisticated manufacturing operations are concentrated.
MDI, TDI, and Polyurethane Market Segmentation
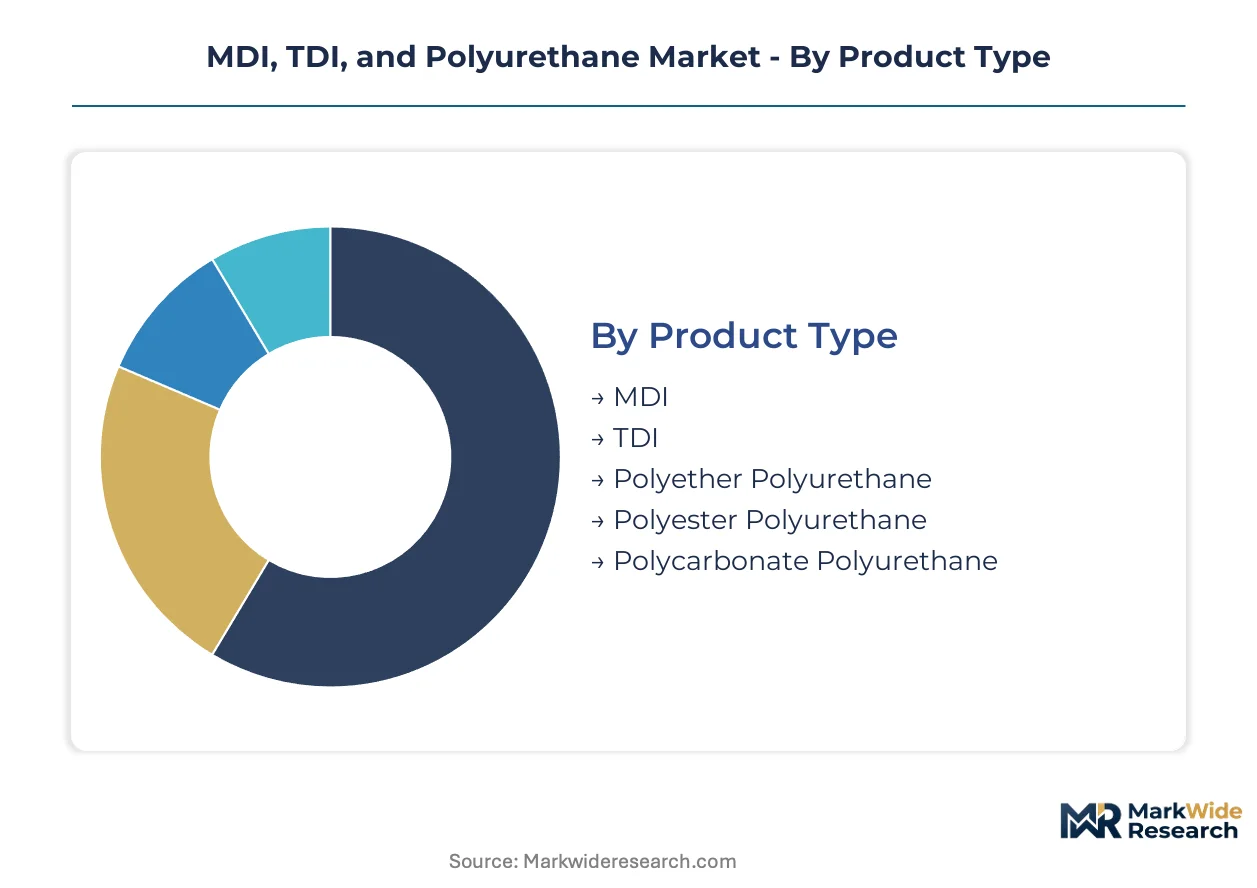
The MDI, TDI, and polyurethane market exhibits diverse product types and applications, reflecting varied performance requirements across industries. Understanding these segments is critical for manufacturers to align production capabilities with evolving regulatory landscapes and specific end-user demands. This analysis details the distinct characteristics and market dynamics of each segment.
Product Type:
Compliance with strict handling and registration requirements, such as those from the European Chemicals Agency (ECHA) and the US Environmental Protection Agency (EPA), primarily dictates material selection within the product type segments.
- MDI:Methylene diphenyl diisocyanate is a key aromatic diisocyanate, reacting with polyols to form rigid and flexible polyurethane foams. Demand concentrates within China's extensive construction and infrastructure projects, driven by the need for high-performance insulation materials.
- TDI:Toluene diisocyanate is primarily used in flexible foam applications for furniture and bedding.
- Polyether Polyurethane:These polymers are characterized by their excellent hydrolytic stability and flexibility, making them suitable for cushioning and insulation. The largest demand volume comes from the construction materials sector and traditional furniture manufacturing, seeking durable foam solutions.
- Polyester Polyurethane:Polyester variants offer superior chemical and oil resistance for demanding industrial coatings and adhesives.
- Polycarbonate Polyurethane:Polycarbonate polyurethane provides exceptional mechanical properties and biocompatibility for advanced medical devices.
Polyether Polyurethane sits at the top of the volume ranking, with Polycarbonate Polyurethane climbing the fastest due to specialized high-tech applications.
Application:
The volume distribution across applications reflects the varied material properties and processing requirements, from high-volume foam production to specialized elastomer systems.
- Foam:Polyurethane foams, both rigid and flexible, are widely used for insulation, cushioning, and sound dampening due to their lightweight and thermal properties. The largest demand concentration is in the construction materials sector, driven by energy efficiency mandates in Europe and North America.
- Adhesives:Polyurethane adhesives offer strong bonding and flexibility for construction, automotive, and footwear applications.
- Sealants:Polyurethane sealants provide excellent weather resistance and adhesion for building envelopes and automotive bodies.
- Elastomers:These highly resilient and durable materials offer exceptional abrasion and tear resistance, suitable for wheels, rollers, and automotive components. Demand is expanding rapidly in electric vehicle systems for battery encapsulation and lightweight structural parts.
- Coatings:Polyurethane coatings provide superior durability, chemical resistance, and aesthetic appeal for industrial and automotive finishes.
Foam applications continue to dominate the market by volume, while specialized Elastomers show the steepest expansion trajectory in high-performance sectors.
End User Industry:
Each end-user industry places distinct performance and regulatory demands on polyurethane materials, influencing formulation and supply chain requirements.
- Furniture Manufacturing:Furniture manufacturing primarily consumes flexible polyurethane foams for cushioning in seating and bedding.
- Footwear Production:Footwear production utilizes polyurethane for lightweight and durable soles and insoles, enhancing comfort and performance.
- Transportation Manufacturing:This sector uses polyurethane for lightweight components, thermal management, and NVH (noise, vibration, harshness) reduction in vehicles. The shift to electric mobility in Germany and the US is increasing demand for specialized elastomers and foams in battery packs.
- Construction Materials:Polyurethane provides high-performance insulation, coatings, and sealants for residential and commercial buildings. Infrastructure investment, particularly in China's Belt and Road Initiative, drives significant consumption for durable exterior applications.
- Consumer Goods:Consumer goods use polyurethane for appliance insulation, sporting goods, and protective packaging solutions.
Construction Materials represent a substantial volume segment, with Transportation Manufacturing gaining share fastest due to innovation in electric vehicle platforms.
Packaging Type:
Logistics efficiency and safe handling protocols, especially for hazardous diisocyanates, shape the preferred packaging types across the polyurethane value chain.
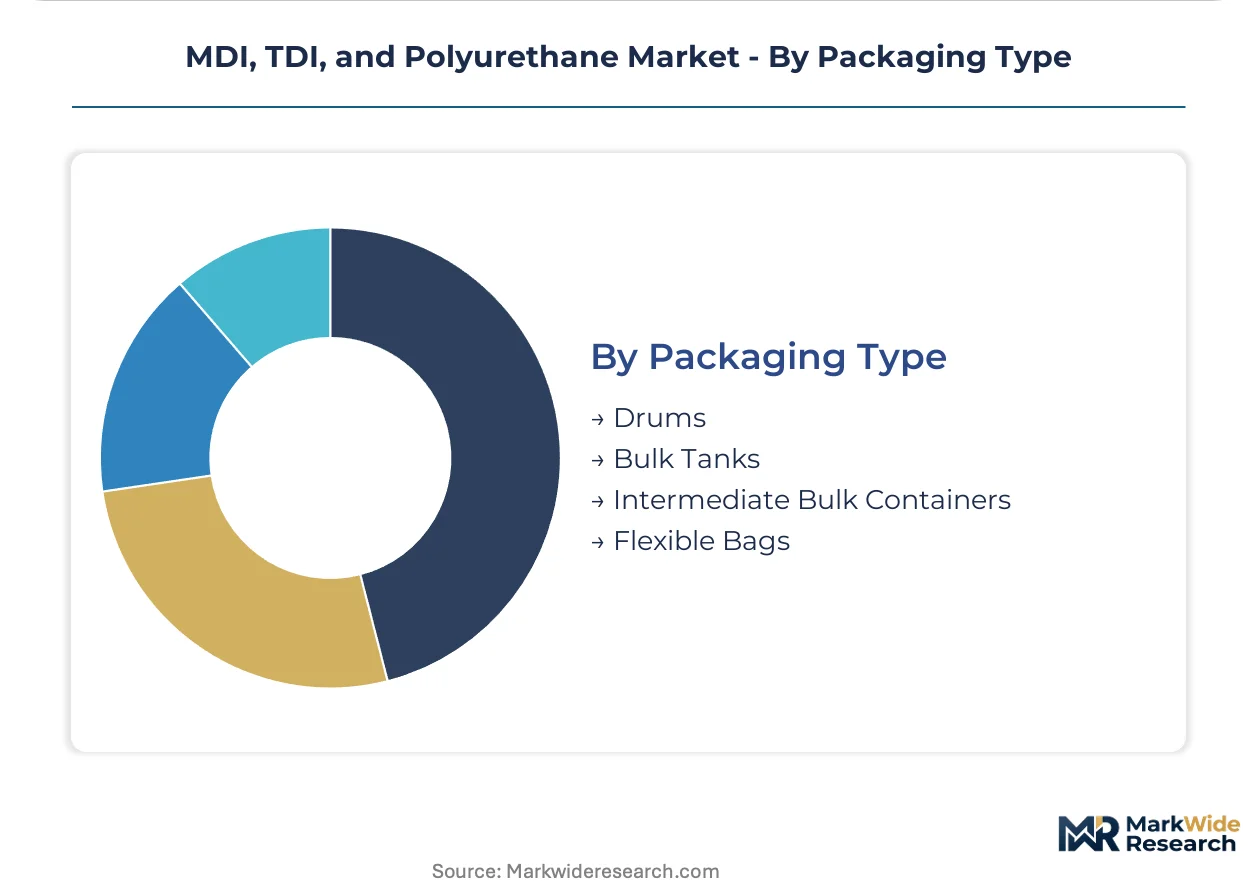
- Drums:Standard 200-liter drums are common for shipping smaller volumes of MDI, TDI, and polyols to diverse manufacturing sites. Compliance with international dangerous goods regulations is critical for drummed shipments across Europe and Asia.
- Bulk Tanks:Large bulk tanks, including ISO tanks and railcars, are utilized for high-volume transportation of liquid precursors like MDI and polyether polyols. This method optimizes cost efficiency for major producers supplying large-scale industrial consumers in North America.
- Intermediate Bulk Containers:Intermediate Bulk Containers offer a convenient solution for medium-volume shipments, balancing efficiency and handling flexibility.
- Flexible Bags:Flexible bags are used for solid polyurethane raw materials or finished products, offering cost-effective storage and transport.
Bulk Tanks account for the largest volume of material movement, while Intermediate Bulk Containers are expanding most quickly for their versatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory disparities across continents influence MDI and TDI production locations, creating cost-of-compliance gaps. Stricter environmental and chemical handling regulations in Europe and North America incentivize some manufacturing to concentrate in regions with different regulatory frameworks. This dynamic shapes investment patterns and supply chain resilience for polyurethane precursors.
China
China's extensive manufacturing base and infrastructure projects drive substantial MDI and polyurethane consumption. The Ministry of Ecology and Environment (MEE) imposes regulations on worker exposure and VOC emissions, influencing local production practices. Significant MDI production capacity in Shanghai and Ningbo supports both domestic demand and global export markets.
Germany
Germany's automotive sector, particularly electric vehicle manufacturing, fuels demand for specialized polyurethane elastomers and foams. The European Chemicals Agency (ECHA) enforces stringent REACH regulations on diisocyanates, impacting formulation and handling protocols. The Rhine-Ruhr region, home to major chemical producers, remains a hub for advanced polyurethane system development.
United States
The United States construction materials sector requires high-performance polyurethane insulation to meet energy efficiency mandates. The US Environmental Protection Agency (EPA) regulates worker exposure and volatile organic compound emissions from polyurethane applications. Industrial consumers in the Gulf Coast region benefit from large-scale bulk tank deliveries of MDI and polyols.
India
India's expanding cold chain infrastructure and construction projects generate new demand for high-performance polyurethane insulation panels. The Bureau of Indian Standards (BIS) sets quality and safety standards for construction materials, including polyurethane products. Emerging industrial zones near Mumbai and Chennai are developing new manufacturing capabilities for diverse polyurethane applications.
Brazil
Brazil's growing demand for refrigerated logistics and civil construction projects increases consumption of polyurethane foams and coatings. ANVISA, Brazil's health surveillance agency, regulates chemical safety and product registration for imported and domestically produced materials. Industrial clusters in São Paulo and Bahia are expanding production of flexible foams for furniture and automotive components.
MDI, TDI, and Polyurethane Market Key Industry Players
Capacity expansion dominates the current landscape, driven by the need to meet rising demand for both commodity and specialized polyurethane systems. The market structure exhibits consolidation among a few global chemical giants, alongside a fragmented tier of specialized system houses. Strategic archetypes include integrated producers controlling the entire value chain and niche players focusing on high-performance applications. Portfolio diversification and geographic expansion are primary competitive moves among major industry participants.
Integrated producers, exemplified by BASF SE and The Dow Chemical Company, operate extensive global networks for both commodity and specialty isocyanates and polyols. These companies leverage their scale and backward integration to serve diverse end-user industries, from construction to automotive. Wanhua Chemical Group Co., Ltd. represents a significant force in the MDI supply chain, particularly anchoring manufacturing scale in Asia. These entities collectively shape the supply dynamics and technological advancements within the global polyurethane market.
| Leading Market Players |
|---|
| Huntsman International LLC |
| Wanhua Chemical Group Co., Ltd. |
| BASF SE |
| Mitsui Chemicals Inc. |
| LANXESS AG |
| The Dow Chemical Company |
| DuPont de Nemours, Inc. |
| Woodbridge Foam Corporation |
| Covestro AG |
| Others |
Cost & Logistics Intelligence
Stringent building codes in Europe and North America requiring higher thermal insulation performance force polyurethane suppliers to invest in specialized formulations and production, which impacts pricing. This demand-side pressure necessitates supply chain adaptations and influences cost structures across the value chain.
Pricing Analysis
Distributor margins reflect regional logistics costs and technical support requirements for specialized polyurethane systems. The dominant pricing model remains contract-based long-term offtake for large industrial consumers, complemented by commodity spot pricing for smaller volumes. Price differentiation stems from volume scale and customization level for specialized applications like electric vehicle components. Pricing softness in commodity segments like furniture foam stems from feedstock volatility. Furniture manufacturing exhibits high price sensitivity, whereas advanced medical device manufacturers are less sensitive.
Supply Chain Analysis
Dual-sourcing requirements from major automotive and construction buyers aim to mitigate supply risks for critical polyurethane precursors. Geographic supply concentration for MDI centers in China, Germany, and the US Gulf Coast. The market relies heavily on petrochemical precursors like benzene and toluene, creating raw material dependencies. Single-source vulnerability for specific MDI production facilities represents a structural supply chain risk. Distribution runs through bulk tanks for high-volume industrial consumers and drums for smaller, specialized manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MDI, TDI, and polyurethane market presents a geographic-arbitrage opportunity, given the cost-of-compliance gaps between European REACH regulations and less stringent Asian environmental standards.
For Market Incumbents: Acquire bio-based polyol producers to secure sustainable feedstock sources and align with circular economy principles. Invest in advanced recycling infrastructure for post-consumer polyurethane products, addressing the end-of-life challenge and mitigating future regulatory threats. Expand production capacity in Asia to serve the region's infrastructure investment and manufacturing growth. Develop novel non-isocyanate polyurethane (NIPU) chemistries to pre-empt evolving chemical safety regulations.
For New Entrants and Emerging Players: Enter via specialized polyurethane elastomers for electric vehicle battery encapsulation and lightweight structural components. Target biocompatible polyurethanes for advanced medical devices, leveraging their unique mechanical properties and regulatory compliance. The most penetrable segment remains high-performance niche applications requiring specific material properties. A direct technical service model, offering custom formulation support, can effectively penetrate these advanced manufacturing sectors.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized system houses possessing proprietary bio-based or NIPU technologies. The long-term viability of the polyurethane market remains strong over the next decade, driven by high-performance applications and sustainability mandates. Target acquisition archetypes include mid-sized companies with strong R&D capabilities in advanced materials. Significant commercial scale-up of polyurethane chemical recycling technologies represents a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Meet rising demand for MDI in Asian construction and infrastructure projects. |
| Green Manufacturing Transition | Align production processes with EU Green Deal mandates and corporate sustainability goals. |
| Joint Venture | Develop advanced polyurethane systems for electric vehicle battery encapsulation. |
| Long-term Supply Agreement | Secure stable feedstock supply amidst petrochemical market volatility. |
| Product Launch | Introduce new bio-based polyols for sustainable consumer goods applications. |
Research Approach
Direct dialogue with plant managers, procurement leads at downstream OEMs, R&D directors, and regulatory affairs specialists provided qualitative insights into market dynamics. This primary research was validated through extensive secondary data analysis from customs/trade data, corporate financial filings, and reports from environmental agencies like ECHA, EPA, and MEE. The study employed both bottom-up and top-down triangulation to ensure data accuracy and coherence.
The quantitative model produced volume and value forecasts across the analysis window, segmented by product type, application, end-user industry, packaging format, and regional regulatory cluster. Compound annual growth rates were derived from historical data analysis and projected market drivers, including energy efficiency mandates and infrastructure investment. Key forecast inputs included petrochemical feedstock prices and global construction project pipelines.
Inputs from published industry reports and company filings were available through the study window; gaps in comprehensive bio-based material adoption rates introduce uncertainty bands into the long-term outlook. Forecasts reflect assumptions regarding macroeconomic conditions and regulatory changes. Deviation in global petrochemical supply stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Nylon 66 Market
Polymers & Resins
Global Resin Market
Polymers & Resins
Polyolefin Wax Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
Cast Polymers Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
North America Polycarbonate (PC) Market
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Global Alpha Olefins Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
Global Cyanate Ester Resins Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Polylactic Acid Market