
 Europe Polyurethane Adhesives Market | 2026-2036
Europe Polyurethane Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polyurethane Adhesives Market Foresight
Software-defined curing protocols and digital formulation services is broadening what polyurethane adhesive suppliers monetize beyond bulk resin. Henkel AG & Co. KGaA leverages its European technical centers to anchor specification control with major automotive OEMs. Sika AG competes through vertical integration into construction-grade systems, while BASF SE sustains feedstock cost advantages via its Ludwigshafen chemical complex.
Europe polyurethane adhesives are thermosetting polymers formed from isocyanate and polyol reactions, typically curing at temperatures between 20°C and 100°C to form elastomeric or rigid bonds with tensile shear strengths exceeding 10 MPa. These adhesives primarily serve industrial assembly where mechanical fastening fails or adds unacceptable weight. Flexible adhesives lead volume in automotive interior applications where vibration damping and thermal cycling resistance prove critical, while structural adhesives command premium positioning in wind turbine blade bonding and electric vehicle battery pack assembly. Reactive adhesives represent the fastest-expanding category as manufacturers seek room-temperature curing systems that eliminate energy-intensive oven processes.
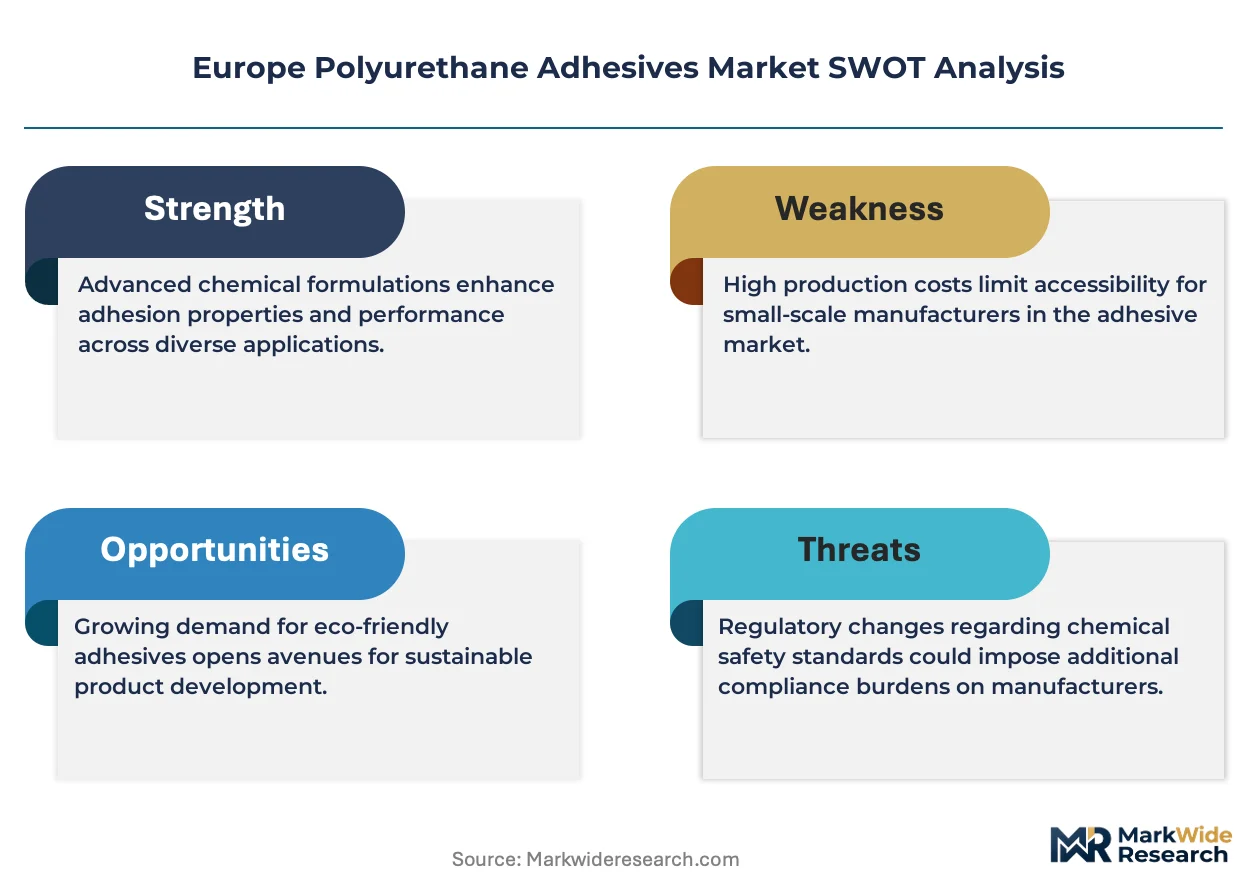
REACH and the EU Green Deal constrain isocyanate emissions and mandate substitution plans for substances of very high concern, forcing reformulation investments across German and French production sites. CE marking under the Construction Products Regulation governs structural bonding applications in building envelopes across EU member states. ECHA's ongoing restriction proposals on aromatic diisocyanates further tighten occupational exposure limits, reshaping workplace handling protocols. Stakeholders must monitor regulatory divergence between EU harmonized standards and emerging national chemical frameworks in Central European accession candidates.
Market Dynamics
REACH compliance deadlines and ECHA restriction proposals on aromatic diisocyanates are forcing simultaneous reformulation across German, French, and Italian production corridors, compressing R&D timelines while elevating capital requirements for low-VOC system transitions.
Growth Catalysts
- Electric vehicle battery pack assembly:OEMs in Germany and France are specifying structural polyurethane adhesives for thermal management and crash-resistant bonding of pouch and prismatic cells, displacing mechanical fastening in module-to-pack integration.
- EU Green Deal industrial decarbonization mandates:The framework's carbon border adjustment mechanism incentivizes adhesive systems with reduced embodied emissions, accelerating demand for bio-based polyol feedstocks in wind turbine blade manufacturing.
- Rhine-Ruhr manufacturing cluster concentration:Automotive tier suppliers co-locating near Henkel and Covestro technical centers in North Rhine-Westphalia are shortening specification cycles and reducing logistics costs for just-in-time adhesive delivery.
Market Restraints
- MDI feedstock cost volatility:Crude oil and benzene price fluctuations directly compress margin structures for formulators lacking backward integration into isocyanate production, particularly affecting mid-scale Italian and Spanish compounders.
- ECHA restriction proposals on aromatic diisocyanates:The regulatory friction is forcing workplace exposure limit reductions below 10 μg/m³, requiring capital-intensive engineering controls and respiratory protection upgrades across French and Polish assembly plants.
- Hot-melt reactive polyurethane substitution:Moisture-curing PUR hot-melts are displacing conventional two-component systems in furniture and woodworking applications, threatening volume in Southern European decorative bonding segments.
Strategic Opportunities
- Polish and Romanian industrial corridors:Underpenetrated automotive supplier parks in Silesia and Prahova County offer first-mover positioning for adhesive technical service centers ahead of OEM final assembly localization.
- Software-defined curing protocols:Convergence of IoT sensor networks with adaptive dispensing equipment enables real-time viscosity and open-time adjustment, creating service revenue streams beyond commodity resin supply.
- CE marking under Construction Products Regulation:The structural bonding certification requirement for building envelope applications in Germany and the Netherlands creates specification lock-in for approved systems, favoring incumbent European formulators with established test data.
Industry Challenges
- Formulation chemist scarcity:The specialized knowledge required for isocyanate-polyol stoichiometry optimization and REACH-compliant additive selection is concentrating among aging technical staff in German chemical clusters, constraining R&D throughput.
- Legacy equipment retrofit complexity:Automotive assembly lines originally configured for mechanical fastening require pneumatic system overhauls and operator retraining to accommodate meter-mix-dispense adhesive equipment, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polyurethane Adhesives Market |
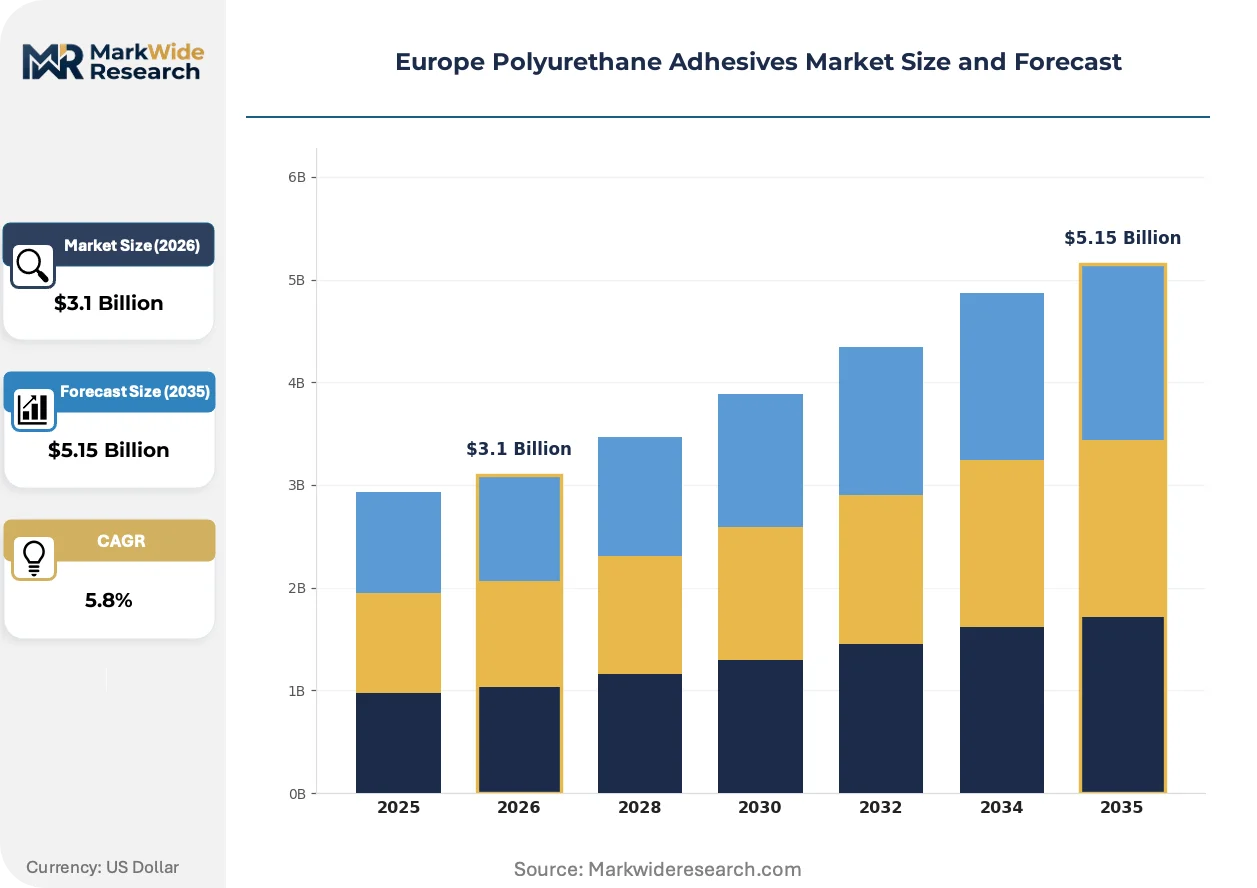
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
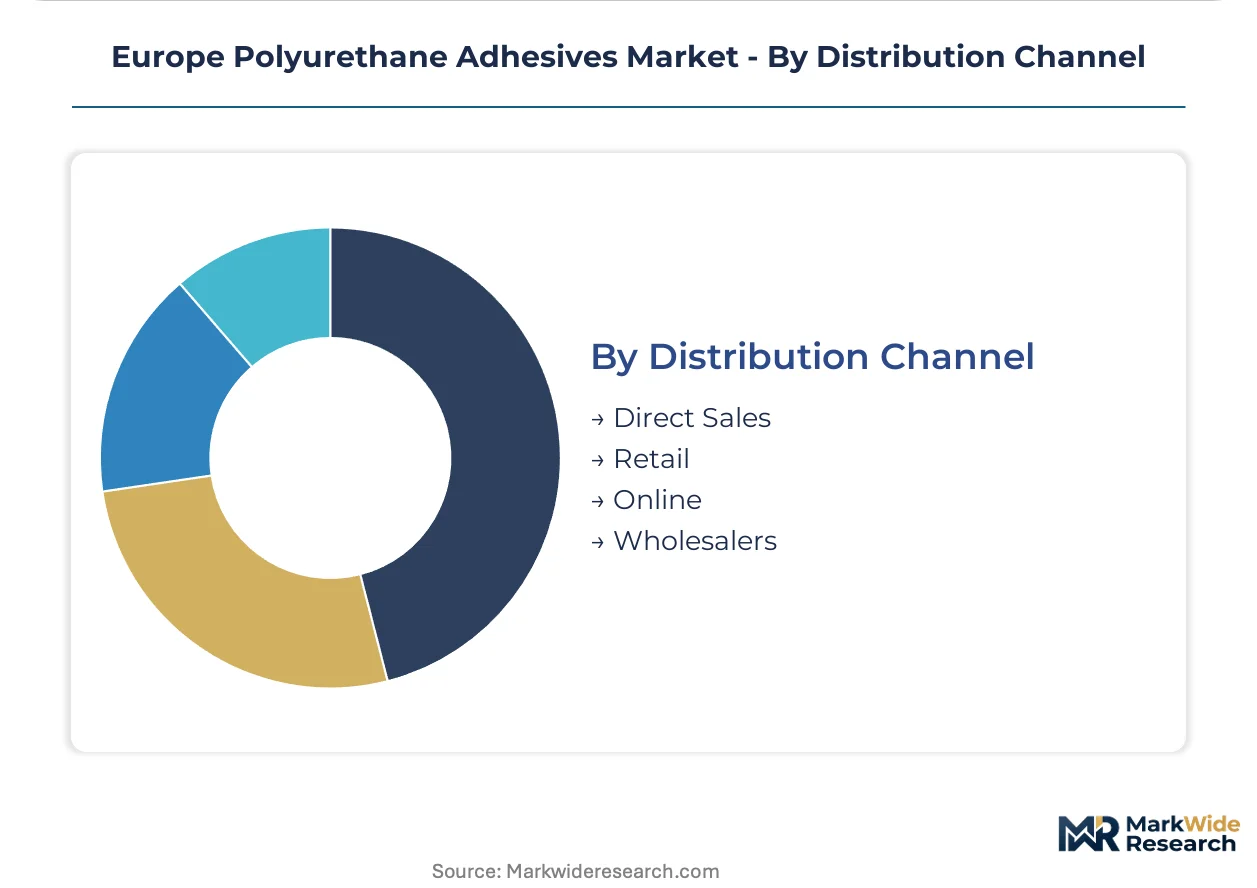
| Segmentation | Product Type: Flexible Adhesives, Rigid Adhesives, Structural Adhesives, Reactive Adhesives Application: Automotive, Construction, Furniture, Electronics End User: Manufacturers, Contractors, Distributors, Repair Shops Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Sika AG, Henkel AG & Co. KGaA, H.B. Fuller Company, Arkema Group, 3M, Huntsman International LLC, BASF SE, Covestro AG, Jowat SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polyurethane Adhesives Market Shifts & Advancements
Digital formulation platforms and adaptive curing systems are compressing the traditional specification cycle, enabling adhesive suppliers to co-develop application-specific grades directly with OEM engineering teams rather than through standardized product catalogs.
Waterborne polyurethane dispersion technology is modularizing. The chemistry enables low-VOC bonding of polar substrates without solvent recovery infrastructure. French automotive interior suppliers are adopting it for dashboard lamination at line speeds previously requiring solventborne systems. This modularization is compressing the capital barrier between compliant and non-compliant production setups, democratizing access to regulatory-grade bonding.
REACH authorization requirements for substances of very high concern are tightening substitution timelines. The industrial consequence is accelerated R&D spend on aliphatic isocyanate alternatives and bio-based polyol platforms. Wind turbine blade manufacturers in Denmark and Germany are most affected, responding with pre-qualification of next-generation structural adhesives ahead of 2027 sunset dates for legacy hardener chemistries.
Specification control is migrating upstream to adhesive suppliers. Automotive OEMs in Stuttgart and Munich are outsourcing substrate bonding engineering to Henkel and Sika technical centers, replacing in-house materials engineering headcount with outcome-based development contracts. This concentration is most visible in German premium EV platforms, where battery pack thermal interface specifications are co-owned by adhesive formulators rather than tier-one integrators.
Europe Polyurethane Adhesives Market Segmentation
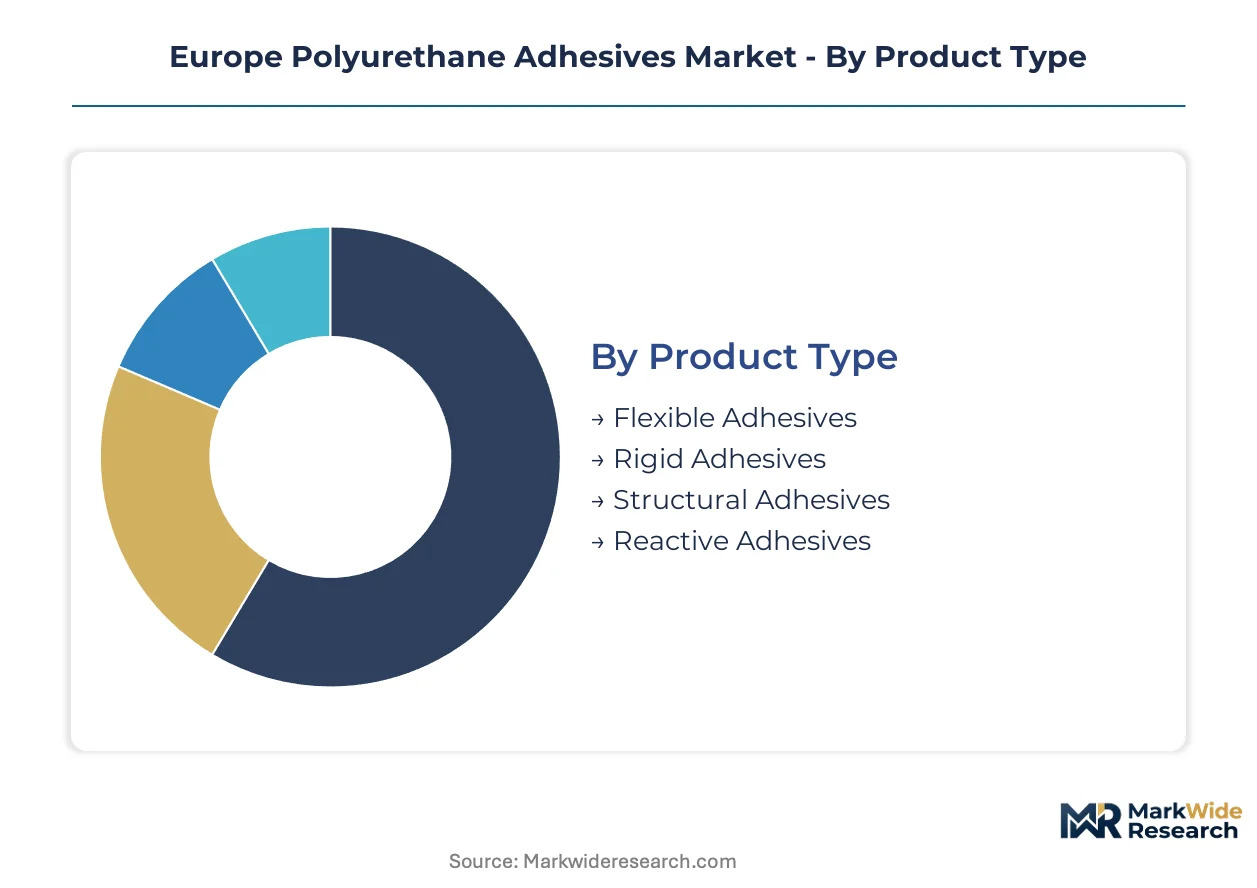
Polyurethane adhesive specifications diverge sharply across European end-uses, with automotive thermal management demands and construction structural certification requirements driving incompatible formulation priorities. Segmentation clarity enables suppliers to align R&D spend with margin concentration rather than volume dispersion.
Product Type:
Technical performance specifications define competitive positioning, with cure chemistry and modulus differentiation creating distinct value tiers.
- Flexible Adhesives:Elastomeric formulations with elongation at break exceeding 300% dominate automotive interior lamination across German OEM supply chains. Vibration damping specifications for dashboard and headliner bonding concentrate demand in Stuttgart and Munich tier networks, where thermal cycling resistance from -40°C to 120°C is mandatory.
- Structural Adhesives:High-modulus systems delivering tensile shear strengths above 15 MPa command premium positioning in wind turbine blade root bonding and electric vehicle battery pack assembly. Danish and German turbine manufacturers specify these grades for carbon fiber-to-steel hybrid joints, displacing mechanical fastening in rotor hub connections.
- Rigid Adhesives:Glass-transition temperatures above 80°C suit construction panel bonding and composite tooling fixtures in French and Italian industrial applications.
- Reactive Adhesives:Moisture-curing and two-component systems with tunable open times enable just-in-time assembly in Polish furniture manufacturing corridors.
Flexible adhesives lead on scale; reactive adhesives lead on momentum.
Application:
End-use certification requirements fragment demand, with CE marking obligations in construction and OEM thermal specifications in automotive creating non-overlapping qualification barriers.
- Automotive:Battery pack structural bonding and thermal interface materials represent the fastest-expanding demand vector. German EV platforms specify polyurethane adhesives for module-to-pack integration, crash-resistant cell containment, and thermal conductivity management above 2.0 W/mK.
- Construction:Structural glazing and insulated panel bonding dominate volume in German and Dutch building envelopes. CE marking under the Construction Products Regulation creates specification lock-in for approved systems, particularly in curtain wall applications across Rhine-Ruhr urban corridors.
- Furniture:Edgebanding and membrane pressing applications in Southern European woodworking clusters favor hot-melt reactive systems for line speed compatibility.
- Electronics:Potting and encapsulation for outdoor LED modules and sensor housings concentrates in Czech and Hungarian electronics manufacturing services.
Construction anchors volume concentration; automotive captures value expansion.
End User:
Procurement sophistication varies dramatically, with technical specification ownership migrating upstream to manufacturers while contractors prioritize logistics reliability.
- Manufacturers:Automotive OEMs and tier suppliers in Germany and France co-develop application-specific grades directly with adhesive technical centers, replacing standardized catalog purchasing with outcome-based development contracts. Specification control now resides with Henkel and Sika engineering teams rather than in-house materials departments.
- Contractors:Construction installation specialists across Benelux and Scandinavia demand just-in-time delivery of CE-certified systems with batch traceability for warranty compliance.
- Distributors:Pan-European chemical distributors stock commodity grades for mid-scale Italian and Spanish compounders lacking backward integration.
- Repair Shops:Automotive aftersales networks in Poland and Romania source small-format packaging for collision repair and windscreen replacement.
Manufacturers dominate specification value; contractors anchor logistics volume.
Distribution Channel:
Channel selection correlates with formulation complexity and technical service intensity, with direct relationships capturing structural adhesive value and wholesale networks handling commodity flexible grades.
- Direct Sales:Technical service engineers from major formulators embed within German automotive OEM development centers, co-locating specification cycles with platform engineering timelines. This channel captures structural adhesive revenue in battery pack and wind turbine applications where failure analysis support is contractual.
- Retail:Professional trade counters in French and Italian construction supply chains stock consumer-format flexible adhesives for small-scale renovation projects.
- Online:E-procurement platforms serve mid-scale electronics manufacturers in Eastern Europe with standardized potting compounds and documentation packages.
- Wholesalers:Pan-European chemical distributors aggregate demand from fragmented furniture manufacturers across Southern Europe, consolidating freight economics for commodity hot-melt systems.
Direct sales command margin concentration; wholesalers capture volume dispersion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands specification authority while France accelerates regulatory reformulation timelines, creating divergent investment rhythms across the continent's adhesive corridors.
Germany
Automotive OEMs in Stuttgart and Munich specify structural polyurethane adhesives for EV battery pack thermal management and crash-resistant cell bonding. REACH compliance deadlines from ECHA compress reformulation schedules for low-VOC systems at Ludwigshafen and Leverkusen chemical complexes. The Rhine-Ruhr manufacturing cluster concentrates Henkel and Covestro technical centers, shortening specification cycles for just-in-time adhesive delivery to tier suppliers.
France
Construction-grade systems for structural glazing and insulated panel bonding dominate demand in Paris and Lyon building envelope projects. ANSM workplace safety protocols align with ECHA restriction proposals on aromatic diisocyanates, forcing exposure limit reductions below 10 μg/m³ at assembly plants. The Auvergne-Rhône-Alpes region hosts automotive interior suppliers adopting waterborne polyurethane dispersions for dashboard lamination at solventborne line speeds.
Italy
Furniture manufacturing in Lombardy and Veneto favors hot-melt reactive polyurethane systems for edgebanding and membrane pressing applications. CE marking under the Construction Products Regulation governs structural bonding in Milan and Turin commercial building projects. Mid-scale compounders in Emilia-Romagna face margin compression from MDI feedstock volatility due to limited backward integration into isocyanate production.
Poland
Automotive supplier parks in Silesia offer first-mover positioning for adhesive technical service centers ahead of OEM final assembly localization. The country's national chemical regulator implements EU harmonized standards while monitoring divergence risks from Central European accession frameworks. Warsaw and Kraków electronics manufacturing services concentrate demand for potting compounds in outdoor LED module assembly.
Netherlands
CE marking requirements for curtain wall applications in Amsterdam and Rotterdam urban corridors create specification lock-in for approved structural bonding systems. The Randstad logistics hub enables pan-European distribution of commodity flexible adhesives to Benelux construction contractors demanding batch traceability. Rotterdam port infrastructure supports import-dependent feedstock supply chains for formulators lacking captive isocyanate production.
Europe Polyurethane Adhesives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-controlled automotive applications favoring direct technical service relationships while construction and furniture channels tolerate distributor intermediaries. The vendor base concentrates among three strategic archetypes: integrated chemical conglomerates with captive feedstock supply, formulation specialists embedding within OEM development centers, and regional compounders serving price-sensitive woodworking segments. Competitive dynamics center on backward integration into isocyanate production and co-development contracts that migrate specification ownership upstream from tier suppliers to adhesive engineers.
Among German-based chemical conglomerates, BASF SE and Covestro AG occupy positions anchored by Ludwigshafen production complexes that supply feedstock advantages to downstream formulation operations. Henkel AG & Co. KGaA exemplifies the technical service archetype through embedded engineering teams at Stuttgart and Munich OEM development centers. Sika AG represents vertical integration into construction-grade systems with specification control over CE-marked structural bonding applications. These three anchors illustrate how geographic proximity to industrial clusters and regulatory competence concentrate competitive position in European polyurethane adhesives.
| Leading Market Players |
|---|
| Sika AG |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Arkema Group |
| 3M |
| Huntsman International LLC |
| BASF SE |
| Covestro AG |
| Jowat SE |
| Others |
Supply & Pricing Matrix
Captive isocyanate production at Ludwigshafen and Leverkusen anchors both supply security and pricing power for integrated German formulators, while non-integrated compounders absorb MDI feedstock volatility without corresponding margin recovery mechanisms.
Pricing Analysis
Capacity additions in Poland and Romania are reshaping price floors for commodity flexible grades, compressing margins for Southern European compounders lacking technical differentiation. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking status, volume scale, and technical service bundling. Pricing pressure stems from hot-melt reactive polyurethane substitution in furniture applications. Mid-scale Italian compounders exhibit highest price sensitivity; German automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
EU Green Deal domestic-content mandates for bio-based feedstocks are reshaping sourcing patterns toward regional polyol production. Supply concentrates in Germany, France, and Belgium for isocyanate precursors; Poland and Italy for downstream formulation. Raw material dependencies center on benzene-derived MDI, propylene oxide for polyols, and specialty catalyst packages. Single-source vulnerability runs through Ludwigshafen chemical complex disruptions. Distribution runs through pan-European chemical distributors consolidating fragmented furniture and electronics demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in structural adhesive segments where REACH-compliant reformulation creates specification premiums, while cost compression in commodity flexible grades demands feedstock integration or geographic repositioning.
For Market Incumbents: To counter ECHA restriction proposals on aromatic diisocyanates, accelerate aliphatic isocyanate qualification programs and embed technical service teams within Stuttgart OEM development centers. Backward integration into bio-based polyol platforms secures Green Deal compliance premiums. CE marking investment for construction-grade systems locks in specification control across Rhine-Ruhr urban corridors. For New Entrants and Emerging Players: The premium-to-economy price gap in automotive battery pack adhesives offers entry positioning for qualified aliphatic systems. Polish automotive supplier parks present underpenetrated technical service opportunities ahead of final assembly localization. Co-development contracts with Silesia-based tier suppliers bypass established German specification gatekeepers. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale Italian compounders because MDI feedstock volatility is forcing distressed consolidation among non-integrated players. Five-to-ten year viability hinges on REACH substitution timeline execution. Acquisition targets should demonstrate aliphatic isocyanate formulation capability or CE-marked construction system portfolios. Watch ECHA authorization sunset dates as inflection indicators for legacy chemistry obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Polyols | EU Green Deal compliance secures carbon border adjustment advantages for Danish wind turbine manufacturers. |
| CE Marking Investment for Structural Systems | Construction Products Regulation certification creates specification lock-in across Amsterdam curtain wall projects. |
| Technical Service Center Localization | Co-location with Silesia automotive suppliers compresses qualification cycles for Polish EV platform integration. |
| Aliphatic Isocyanate Platform Development | ECHA restriction proposals on aromatic diisocyanates mandate workplace exposure limit compliance below 10 μg/m³. |
| Software-defined Curing Protocol Deployment | IoT-enabled viscosity adjustment generates service revenue streams beyond commodity resin supply to Munich OEMs. |
Research Methodology
Direct dialogue with adhesive formulator R&D directors, automotive tier supplier procurement leads, construction installation contractors, and ECHA regulatory affairs specialists grounded qualitative findings. Secondary validation drew from Cefic chemical industry reports, EU Construction Products Regulation certification databases, customs trade data for MDI and polyol flows, and SEC filings of listed chemical conglomerates. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-level value and volume trajectories across the analysis window reflect modeled interactions between automotive EV production ramps, wind turbine installation schedules, and REACH compliance transition timelines. Segmentation dimensions span product type, application end-use, and regional production cluster concentration. CAGRs derived from regression analysis of historical demand elasticities against feedstock cost indices and regulatory phase-in schedules.
Caveats apply where ECHA restriction finalization timelines, MDI feedstock price shocks, or automotive platform engineering changes could materially shift the outlook. Forecasts embody assumptions regarding aliphatic isocyanate substitution rates and bio-based polyol scale-up economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Ocular Adhesives and Sealants Market
Adhesives & Sealants
2K Epoxy Adhesives Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Europe Electronics Adhesives Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
Polyurethane Sealant Market
Adhesives & Sealants
Anti-Corrosion Tape Market
Adhesives & Sealants
Gelatin Bone Glue Market
Adhesives & Sealants
Global Methyl Acrylate Market
Adhesives & Sealants
North America Epoxy Curing Agents Market
Adhesives & Sealants
Amine Curing Agents Market