
 Malaysia High Pressure Laminate Market | 2026-2036
Malaysia High Pressure Laminate Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia High Pressure Laminate Market Foresight
Healthcare facility buyers are unwinding procurement share from traditional residential developers as hospital renovation cycles intensify across Malaysia. TOPMIX leverages its manufacturing scale to supply bulk decorative laminate orders for commercial tower projects in Kuala Lumpur. Formica sustains brand recognition among interior designers specifying premium kitchen countertop surfaces. Maica Laminates Sdn Bhd anchors its position through specialized distribution to furniture fabricators in Johor Bahru.
High pressure laminate comprises multiple layers of kraft paper impregnated with thermosetting resins, fused under pressures exceeding 7 MPa and temperatures near 150°C to form rigid, wear-resistant surfacing material. Decorative laminates lead volume consumption due to their dominance in residential and commercial interior finishes, while fire-resistant laminates command premium positioning as Malaysia's Uniform Building By-Laws tighten flame-spread requirements in high-rise structures. Industrial laminates occupy a mature niche serving electrical insulation and laboratory applications with stable but slower expansion trajectories.
Malaysia's Department of Standards Malaysia (DSM) administers MS standards for laminate surface durability, while the Construction Industry Development Board (CIDB) enforces material compliance through its contractor grading system. The Fire Services Department mandates flame-retardant certification for laminates installed in commercial buildings exceeding specified height thresholds. Stakeholders must monitor evolving green building rating tools such as Green Building Index Malaysia as sustainability criteria increasingly influence laminate specification in government-linked projects.
Market Dynamics
Malaysia's High Pressure Laminate market is restructuring around CIDB's escalating fire-rating mandates for interior materials, which are compressing specification timelines and elevating compliance costs for contractors operating across Peninsular Malaysia's dense commercial corridors.
Growth Catalysts
- CIDB Grading Requirements:The Construction Industry Development Board's tightened contractor classification system is mandating certified fire-rated laminates for high-rise fit-outs, pulling volume toward compliant suppliers in Kuala Lumpur and Selangor.
- Residential Construction Acceleration:Furniture manufacturers and kitchen cabinet producers in the Klang Valley are expanding laminate procurement as housing development permits surge across Peninsular Malaysia.
- Healthcare Renovation Cycles:Hospital refurbishment programs across Johor and Penang are diverting laminate demand from traditional residential channels toward medical-grade surfacing specifications.
Market Restraints
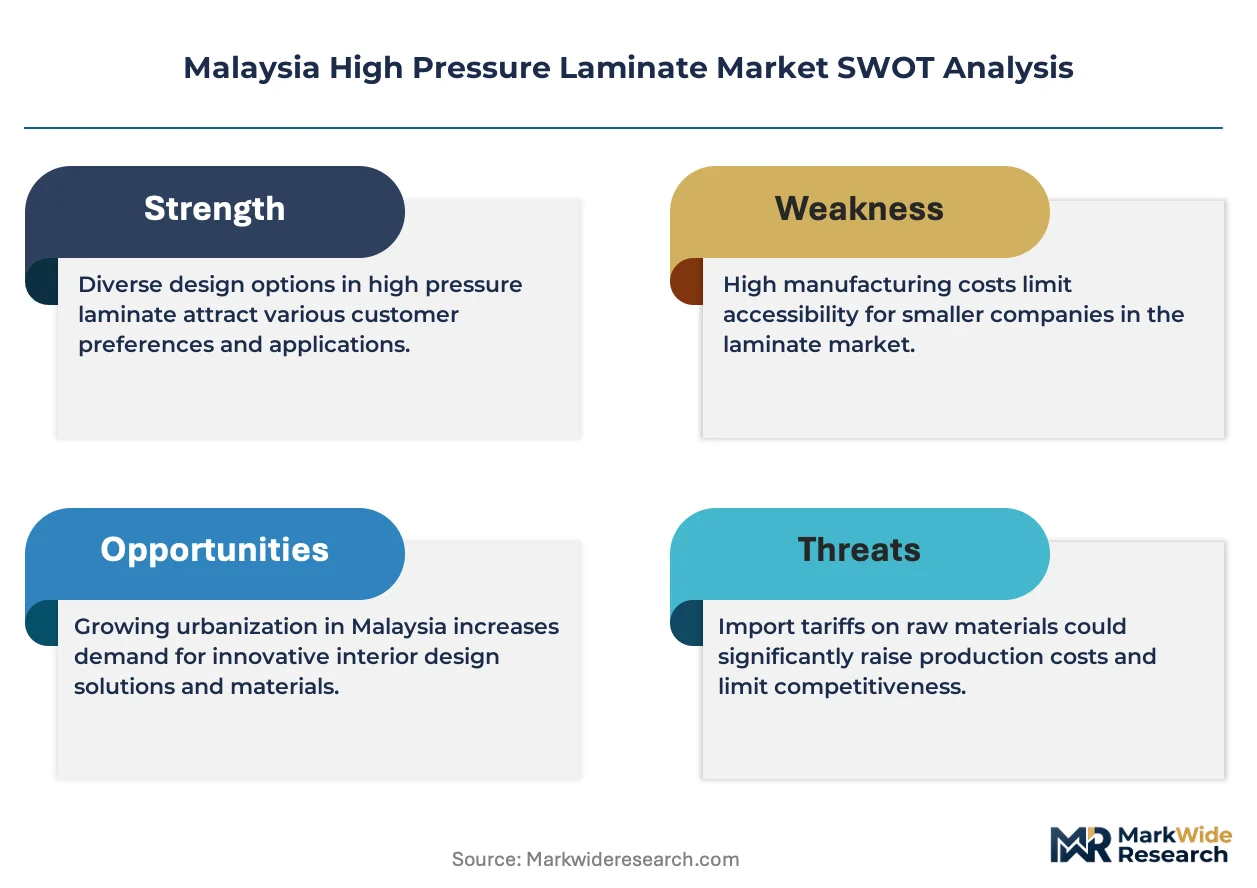
- Kraft Paper Resin Cost Volatility:Thermosetting resin prices fluctuate with petrochemical feedstock markets, squeezing margin predictability for laminate producers dependent on imported phenolic compounds.
- Import Concentration Risk:Decorative paper and specialized overlay films concentrate through Singaporean and Thai distribution hubs, exposing Malaysian fabricators to cross-border logistics friction.
- Substitute Surface Threat:Quartz composite and sintered stone materials are capturing premium countertop share in Kuala Lumpur's luxury residential segment.
Strategic Opportunities
- East Malaysia Penetration:Sarawak and Sabah construction markets remain undersupplied relative to Peninsular Malaysia, offering first-mover positioning for distributors establishing Kuching and Kota Kinabalu logistics nodes.
- Green Building Index Tailwinds:Malaysia's GBI certification incentives for government-linked projects are creating specification preference for low-emission laminate formulations meeting MS standards.
- Digital Specification Platforms:Interior designer procurement is migrating toward centralized material libraries, enabling direct manufacturer-to-specifier channel bypass of traditional timber merchant networks.
Industry Challenges
- Fire Certification Timeline Compression:Fire Services Department flame-spread testing queues are extending project delivery schedules, forcing contractors to buffer inventory or risk penalty clauses.
- Skilled Press Operator Scarcity:Shortages of technicians capable of calibrating multi-daylight hydraulic presses above 7 MPa are constraining production scale-up at Johor Bahru fabrication facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia High Pressure Laminate Market |
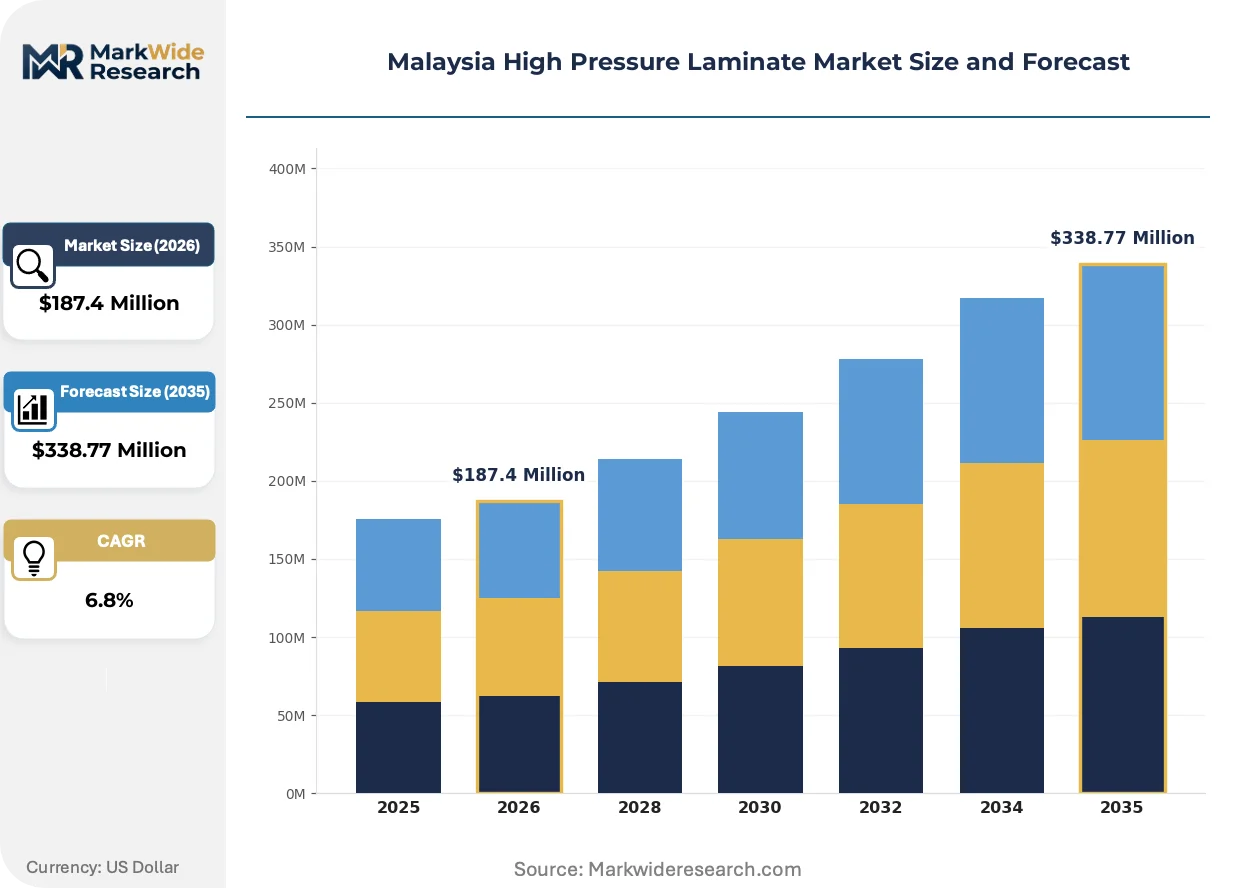
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decorative Laminates, Industrial Laminates, Fire-Resistant Laminates, Moisture-Resistant Laminates End User: Residential Sector, Commercial Sector, Hospitality Sector, Healthcare Facilities Application: Wall Panels, Kitchen Countertops, Furniture Surfaces, Flooring Solutions Distribution Channel: Direct Sales, Retail Outlets, Online Platforms, Distributors |
| Companies Covered | TOPMIX, Vitally Sdn Bhd, Formica, Board Ply Trading Sdn Bhd, Dextra Laminates Sdn Bhd, Aica Kogyo Co. Ltd, Maica Laminates Sdn Bhd, ICA Innovation Sdn Bhd, Polytec Laminates Sdn. Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia High Pressure Laminate Market Shifts & Advancements
Surface engineering and specification digitization are converging to reshape how Malaysian laminate producers compete, with compliance automation and material science advances compressing traditional procurement cycles.
Digital printing technology for decorative paper layers is displacing conventional gravure cylinder methods in Malaysian laminate manufacturing. Kitchen cabinet producers in Selangor are adopting digitally printed surfaces at accelerating rates. This shift is compressing minimum order quantities and enabling shorter design refresh cycles for residential developers.
Malaysia's Department of Standards Malaysia is revising MS 268:2014 surface durability protocols to incorporate accelerated aging test methods. The industrial consequence is forcing reformulation of resin impregnation ratios among domestic producers. Furniture fabricators in Johor Bahru are responding by pre-qualifying suppliers against anticipated 2025 compliance thresholds.
Specification behavior among interior designers is fragmenting across project scale tiers, with boutique practices consolidating material choices through curated digital libraries while large commercial firms maintain direct mill relationships. Timber merchant intermediaries in the Klang Valley are losing share to manufacturer-direct specification platforms. This pattern is most visible in Kuala Lumpur's high-rise residential tower segment where design-build contractors consolidate material decisions.
Malaysia High Pressure Laminate Market Segmentation
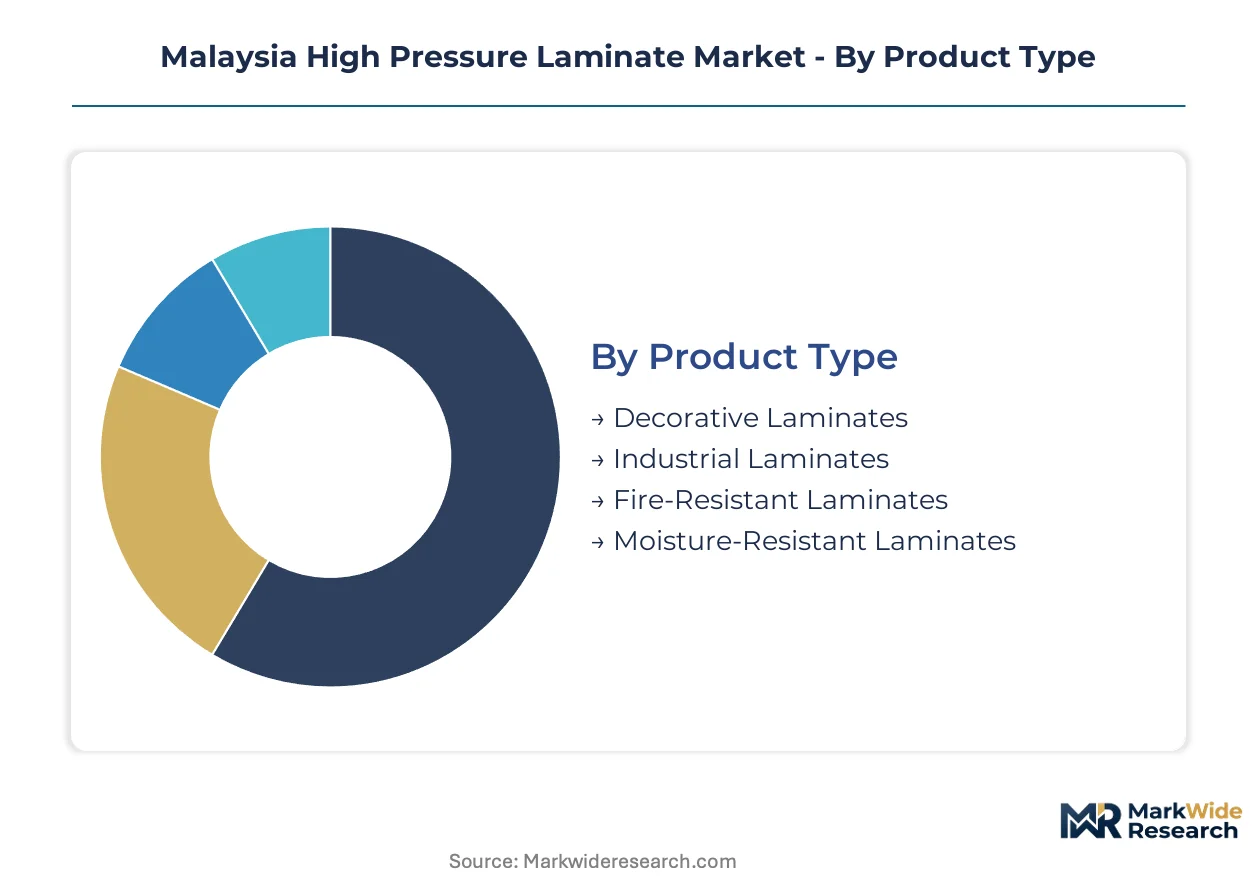
Malaysia's High Pressure Laminate market segments along four functional axes that determine procurement patterns across Peninsular Malaysia's construction corridors. Each segmentation layer reveals distinct pressure points from substitute materials, regulatory compliance burdens, and channel friction that reshape supplier positioning.
Product Type:
Fire-Resistant Laminates and Moisture-Resistant Laminates face the most acute substitution pressure from sintered stone and engineered quartz in premium residential applications, forcing these segments to defend specification share through CIDB certification leverage.
- Decorative Laminates:Multiple kraft paper layers impregnated with melamine-formaldehyde resin, finished with printed decorative overlays. Demand concentrates in Selangor furniture fabricators supplying Klang Valley residential towers, where kitchen cabinet producers specify these surfaces for cost-sensitive developer-grade interiors. Volume leadership in this segment stems from its penetration across mid-market housing projects where price elasticity dominates specification decisions.
- Fire-Resistant Laminates:Phenolic resin-impregnated kraft cores with mineral fillers achieving Class 0/Class 1 flame-spread ratings under Fire Services Department protocols. Kuala Lumpur commercial tower fit-outs drive procurement as contractors bid for CIDB G7 grading compliance, with specification timelines compressing around mandatory certification queues.
- Industrial Laminates:High-density thermoset composites serving electrical insulation and laboratory chemical resistance applications. Penang electronics manufacturers and Johor petrochemical facilities sustain steady offtake despite slower expansion trajectories compared to decorative grades.
- Moisture-Resistant Laminates:Enhanced resin formulations with reduced water absorption coefficients for humid tropical environments. Healthcare renovation programs across Johor and Penang specify these grades for sanitary surfacing in clinical settings.
Decorative Laminates retain volume leadership; Fire-Resistant Laminates hold the steepest expansion curve.
End User:
Cost tier stratification separates specification behavior across end-user categories, with government-linked healthcare and commercial projects commanding premium compliance investments that residential developers resist.
- Commercial Sector:Office towers, retail complexes, and institutional buildings across Kuala Lumpur and Selangor. CIDB fire-rating mandates and Green Building Index incentives pull specification toward certified suppliers capable of documentation-heavy procurement workflows.
- Healthcare Facilities:Hospital renovation cycles intensifying across Johor and Penang. Medical-grade surfacing requirements prioritize antimicrobial performance and chemical resistance over cost optimization, diverting procurement share from residential channels.
- Residential Sector:Housing developers and individual homeowners in Peninsular Malaysia's urban corridors. Kitchen countertop and cabinetry applications dominate, with price sensitivity highest in mass-market segments outside Kuala Lumpur's luxury tier.
- Hospitality Sector:Hotels and serviced apartments requiring durable, aesthetically consistent surfacing across high-traffic areas. Boutique properties in Georgetown and Malacca specify premium decorative grades for heritage-sensitive renovations.
Commercial Sector commands the highest compliance expenditure per project; Healthcare Facilities are expanding procurement most quickly.
Application:
Volume concentration in vertical surfacing applications creates margin pressure distinct from horizontal load-bearing uses, with flooring solutions facing the strongest displacement threat from vinyl composite and engineered wood alternatives.
- Kitchen Countertops:Horizontal work surfaces in residential and food-service environments. Klang Valley cabinet producers specify these for moisture resistance and thermal tolerance, though quartz composites capture share in premium Kuala Lumpur developments.
- Wall Panels:Vertical cladding for commercial interiors and healthcare facilities. Fire-rated grades dominate high-rise applications where Uniform Building By-Laws mandate flame-spread containment across evacuation routes.
- Furniture Surfaces:Tabletops, cabinetry facings, and built-in millwork. Johor Bahru fabricators drive demand for digitally printed decorative grades enabling shorter design refresh cycles.
- Flooring Solutions:High-wear surfacing for commercial and institutional traffic. This application faces the most intense substitution pressure from luxury vinyl tile and engineered wood, constraining laminate share to budget-sensitive segments.
Wall Panels retain specification dominance in commercial vertical surfacing; Kitchen Countertops face the most aggressive substitute encroachment.
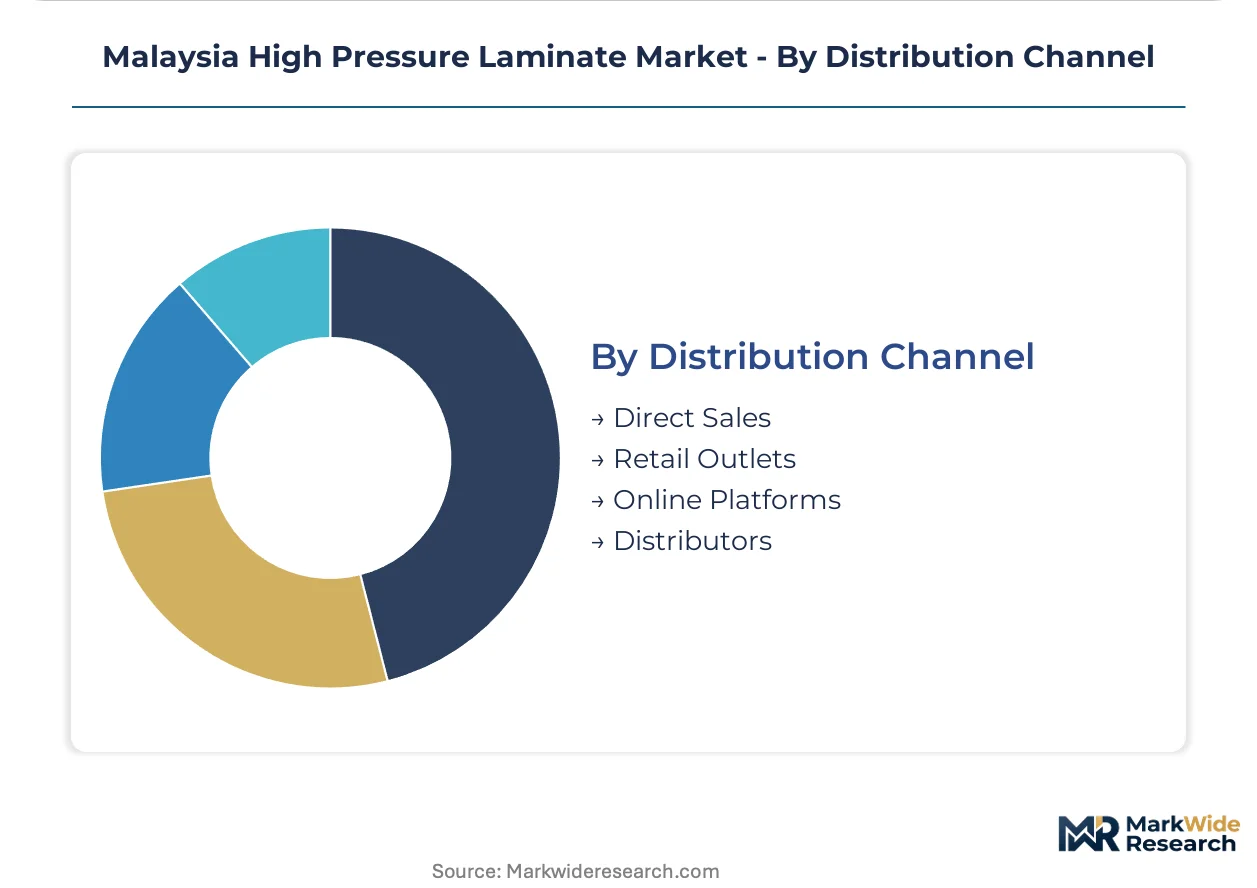
Distribution Channel:
Customer type fragmentation between large contractors and boutique designers is forcing channel restructuring, with specification digitization threatening traditional timber merchant intermediaries.
- Distributors:Regional stocking intermediaries serving furniture fabricators and smaller contractors. Johor Bahru and Penang distribution hubs concentrate inventory for Peninsular Malaysia's southern and northern construction markets.
- Direct Sales:Manufacturer-to-contractor relationships for large commercial tower projects. Kuala Lumpur design-build contractors consolidate material decisions through direct mill procurement, bypassing traditional merchant networks.
- Retail Outlets:Timber merchants and building material showrooms serving residential renovators and small contractors. Klang Valley retail density remains highest, though share erosion to digital platforms accelerates.
- Online Platforms:Centralized material libraries and specification databases. Interior designer procurement migration toward these channels enables manufacturer-direct access, compressing traditional distributor margins.
Distributors retain volume leadership in furniture fabricator supply; Online Platforms are climbing the fastest as specification behavior digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Tanjung Pelepas anchors Johor's laminate distribution throughput, connecting Malaysian fabricators to Southeast Asian resin and decorative paper supply chains. Klang Valley construction corridors absorb the majority of domestic laminate volume. East Malaysia remains structurally undersupplied relative to Peninsular demand density.
Selangor
Klang Valley furniture fabricators and kitchen cabinet producers drive laminate procurement as residential tower permits accelerate. CIDB contractor grading requirements mandate certified fire-rated materials for commercial fit-outs above specified height thresholds. Shah Alam industrial zones concentrate multi-daylight press operations serving developer-grade interior specifications.
Kuala Lumpur
Commercial tower renovation cycles and hospitality refurbishment programs sustain premium decorative laminate demand. Fire Services Department flame-spread certification queues compress project delivery timelines for high-rise contractors. Bukit Bintang and KLCC districts specify antimicrobial and fire-resistant grades for healthcare and institutional interiors.
Johor
Iskandar Malaysia development corridors and Singapore cross-border construction activity pull laminate volume through Johor Bahru distribution nodes. Maica Laminates anchors specialized supply relationships with southern furniture fabricators. Pasir Gudang logistics clusters handle bulk resin and overlay film imports from Thai and Singaporean hubs.
Penang
Hospital renovation intensification across George Town and Butterworth diverts procurement toward medical-grade surfacing specifications. Electronics manufacturing facilities sustain steady industrial laminate offtake for electrical insulation applications. Bayan Lepas industrial zones maintain stable demand trajectories distinct from volatile construction cycles.
Sarawak
Kuching construction markets remain penetration opportunities for distributors establishing East Malaysia logistics nodes. Green Building Index Malaysia certification incentives for government-linked projects create specification preference for low-emission formulations. Local fabrication capacity scarcity forces reliance on Peninsular supply chains with extended lead times.
Malaysia High Pressure Laminate Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and distribution reach, producing a tiered competitive structure where volume dominance and niche positioning coexist. The vendor base clusters around three strategic archetypes: integrated manufacturers with captive resin supply, regional distributors controlling timber merchant networks, and specification-focused specialists serving designer channels. Capacity expansion and certification pre-qualification represent the dominant competitive moves as CIDB compliance timelines compress.
Among Japanese-origin manufacturers, Aica Kogyo Co. Ltd exemplifies the integrated production archetype with upstream resin capabilities. TOPMIX occupies a position representing scale-driven supply to commercial tower projects. Formica anchors brand recognition among interior designers specifying premium residential surfaces. Maica Laminates Sdn Bhd sits within the specialized distribution tier serving Johor Bahru furniture fabricators with localized logistics.
| Leading Market Players |
|---|
| TOPMIX |
| Vitally Sdn Bhd |
| Formica |
| Board Ply Trading Sdn Bhd |
| Dextra Laminates Sdn Bhd |
| Aica Kogyo Co. Ltd |
| Maica Laminates Sdn Bhd |
| ICA Innovation Sdn Bhd |
| Polytec Laminates Sdn. Bhd |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Klang Valley furniture fabricators and Peninsular Malaysian laminate producers lock in phenolic resin supply access while insulating procurement teams from petrochemical feedstock volatility. This contract structure compresses working capital cycles for kitchen cabinet producers facing CIDB certification deadlines.
Pricing Analysis
Volume-discount tiering structures separate bulk commercial tower contractors from boutique residential developers. Three-tier pricing structure across premium, standard, and economy levels tracks fire-resistance certification grade and decorative overlay complexity. Pricing pressure stems from quartz composite encroachment in Kuala Lumpur luxury countertops. Mass-market housing developers exhibit highest price sensitivity; hospital procurement committees prioritize antimicrobial performance over unit cost.
Supply Chain Analysis
Inventory buffers at Johor Bahru distribution nodes stretch lead times for East Malaysian contractors sourcing from Peninsular production clusters. Kraft paper supply concentrates in Indonesia and Thailand; phenolic resin formulations draw from Singaporean petrochemical hubs. Single-source vulnerability persists for specialized overlay films transiting through Thai distribution corridors. Distribution runs through timber merchant networks in Selangor and direct-mill relationships for CIDB G7-graded commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's High Pressure Laminate market rewards defensive positioning through regulatory entrenchment. CIDB fire-rating mandates create switching costs that cement incumbent relationships with certified suppliers.
For Market Incumbents: Compound certification advantages by pre-qualifying resin formulations against anticipated MS 268:2014 revisions. Anchor capacity addition in Shah Alam industrial zones to defend share from sintered stone substitution. Deepen backward integration into phenolic compound production to offset petrochemical price volatility squeezing margin predictability. For New Entrants and Emerging Players: Lead with digital specification platforms targeting boutique interior designer practices in Georgetown and Malacca heritage renovation segments. Kuching and Kota Kinabalu logistics nodes offer first-mover positioning in structurally undersupplied Sarawak construction markets. Green Building Index certification provides the most penetrable specification angle for government-linked project access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among distributors controlling Johor Bahru timber merchant networks with captive furniture fabricator relationships. Over the projection horizon, vertically integrated manufacturers with upstream resin capabilities present superior acquisition profiles. Watch Fire Services Department flame-spread testing queue lengths as inflection indicators for contractor inventory build cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenolic Resin | Captive supply of thermosetting compounds insulates margins from petrochemical volatility affecting Klang Valley producers. |
| CIDB Fire-Rating Certification Investment | Pre-qualification against Uniform Building By-Laws secures specification share in Kuala Lumpur commercial tower fit-outs. |
| East Malaysia Distribution Node Establishment | Kuching and Kota Kinabalu logistics infrastructure addresses structural undersupply in Sarawak government-linked projects. |
| Digital Specification Platform Launch | Direct manufacturer-to-designer channels bypass timber merchant intermediaries losing share in Selangor residential segments. |
| Green Building Index Formulation Development | Low-emission laminate grades capture specification preference in Malaysia's government-linked construction procurement workflows. |
Research Methodology
The analysis maps decorative laminates, fire-resistant laminates, industrial laminates, and moisture-resistant grades, each validated through furniture fabricator procurement directors, CIDB-graded commercial contractors, hospital facilities managers, and interior designer specification leads. Primary interview data triangulates against Department of Standards Malaysia technical bulletins, CIDB contractor grading registers, Fire Services Department flame-spread certification records, and customs import data for phenolic resin feedstocks. Bottom-up volume builds from press capacity utilization rates reconcile with top-down construction permit flow analysis.
Consistency checks against construction sector GDP contributions and residential tower permit trajectories validate volume outputs across the projection horizon. The analytical framework segments by product type, end-user sector, application surface, and distribution channel, with geographic production cluster as an additional modeling dimension. CAGRs derive from time-series regression of laminate consumption against housing starts and commercial fit-out cycles, incorporating resin price elasticity coefficients and substitution threat parameters from sintered stone penetration rates.
Forecasts assume regulatory continuity in CIDB grading regimes and Fire Services Department certification protocols; material policy shifts would require re-modeling. Phenolic resin price volatility, cross-border logistics friction through Thai hubs, and quartz composite substitution acceleration in premium residential segments represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Graphite Felt Market
Composite Materials
Fiber Reinforced Polymer (FRP) Panels and Sheets Market
Composite Materials
Composite Cans Market
Composite Materials
Laminar Composites Market
Composite Materials
Composites Testing Market
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
Acrylic Laminates Market
Composite Materials
Wind Turbine Composites Market
Composite Materials
Phenolic Panel Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Europe Composites Market
Composite Materials
Composite Material for Passenger Car Market
Composite Materials
High Performance Composites Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Global Carbon Fiber Composite Heating Elements Market
Composite Materials
Composite Coatings Market