
 Sodium Polyacrylate Market | 2026-2036
Sodium Polyacrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Polyacrylate Market Analytics
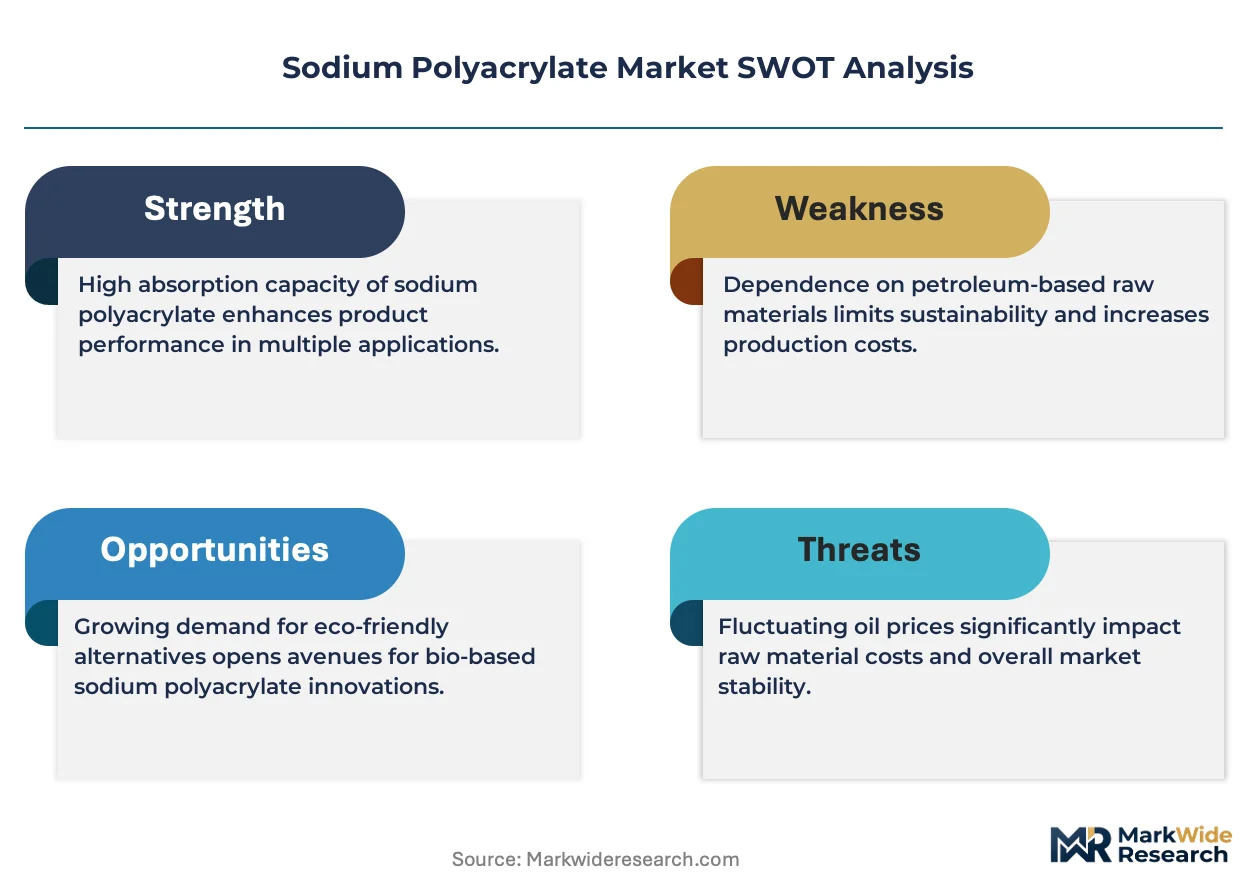
Petroleum-based polyacrylate is rebalancing toward bio-based acrylic acid feedstocks as cracker economics tighten and brand owners enforce Scope 3 targets. Evonik Industries AG leverages its backward integration into acrylic acid to sustain margin stability across European operations. Sumitomo Seika Chemicals anchors high-purity grades for pharmaceutical hydrogel applications, while Nippon Shokubai competes through manufacturing scale at its Himeji complex.
Sodium polyacrylate is a cross-linked sodium salt of polyacrylic acid with absorption capacities exceeding 300 times its mass in deionized water, synthesized primarily through aqueous solution or inverse suspension polymerization of acrylic acid neutralized with sodium hydroxide. Super absorbent polymers command the dominant value share in personal care end uses, while hydrogel forms are expanding fastest in pharmaceutical wound dressings and drug delivery matrices. Solid formulations occupy the volume lead across agriculture and waste management segments where granular spreading dominates application methods.
REACH in Europe and EPA TSCA in the United States constrain residual monomer thresholds and environmental release profiles, forcing reformulation investments and third-party certification. China's GB standards and MEE discharge permits add compliance layers for export-oriented producers operating from Shandong and Jiangsu provinces. Stakeholders must monitor feedstock pivot timelines and regulatory divergence between jurisdictions to align capacity decisions with evolving product specifications.
Market Dynamics
EU REACH compliance on residual monomer content is forcing baby diaper manufacturers to requalify super absorbent polymer suppliers, tightening procurement specifications across Southeast Asian supply chains and compressing margins for non-integrated producers.
Growth Catalysts
- Pharmaceutical hydrogel demand:Wound dressing manufacturers in Germany and Japan are expanding orders for high-purity sodium polyacrylate grades, driving capacity upgrades at specialized polymerization facilities.
- REACH residual monomer thresholds:Tightening EU compliance requirements are accelerating supplier consolidation, favoring backward-integrated producers with captive acrylic acid supply.
- Shandong province cluster effects:Integrated acrylic acid-to-SAP complexes in China's chemical corridor are capturing procurement from Southeast Asian diaper manufacturers seeking volume reliability.
Market Restraints
- Propylene feedstock volatility:Cracker economics and naphtha pricing swings directly compress margins for petroleum-based acrylic acid routes, exposing non-integrated producers to cost pressure.
- Supply concentration in East Asia:Overreliance on Shandong and Jiangsu province production creates geographic risk for global buyers, with limited alternative sourcing during regional disruptions.
- Technical ceiling on bio-based substitution:Fermentation-derived acrylic acid remains cost-prohibitive at scale, constraining Scope 3 target achievement for brand owners with 2030 commitments.
Strategic Opportunities
- Indian agricultural hydrogel penetration:Drought-prone states are piloting super absorbent polymers for moisture retention, with state agricultural departments exploring subsidy frameworks.
- Drug delivery matrix convergence:Transdermal patch manufacturers are testing sodium polyacrylate hydrogels as controlled-release substrates, opening pharmaceutical-grade demand.
- EU Green Deal bio-feedstock mandates:Renewable content thresholds for chemical intermediates are creating preferential procurement status for producers with certified bio-acrylic acid pathways.
Industry Challenges
- Polymerization process engineering talent:Inverse suspension expertise remains concentrated among veteran technologists at legacy Japanese and German producers, constraining new entrant scale-up.
- Residual monomer certification timelines:Third-party REACH compliance testing extends supplier qualification cycles to 18-24 months, delaying contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Polyacrylate Market |
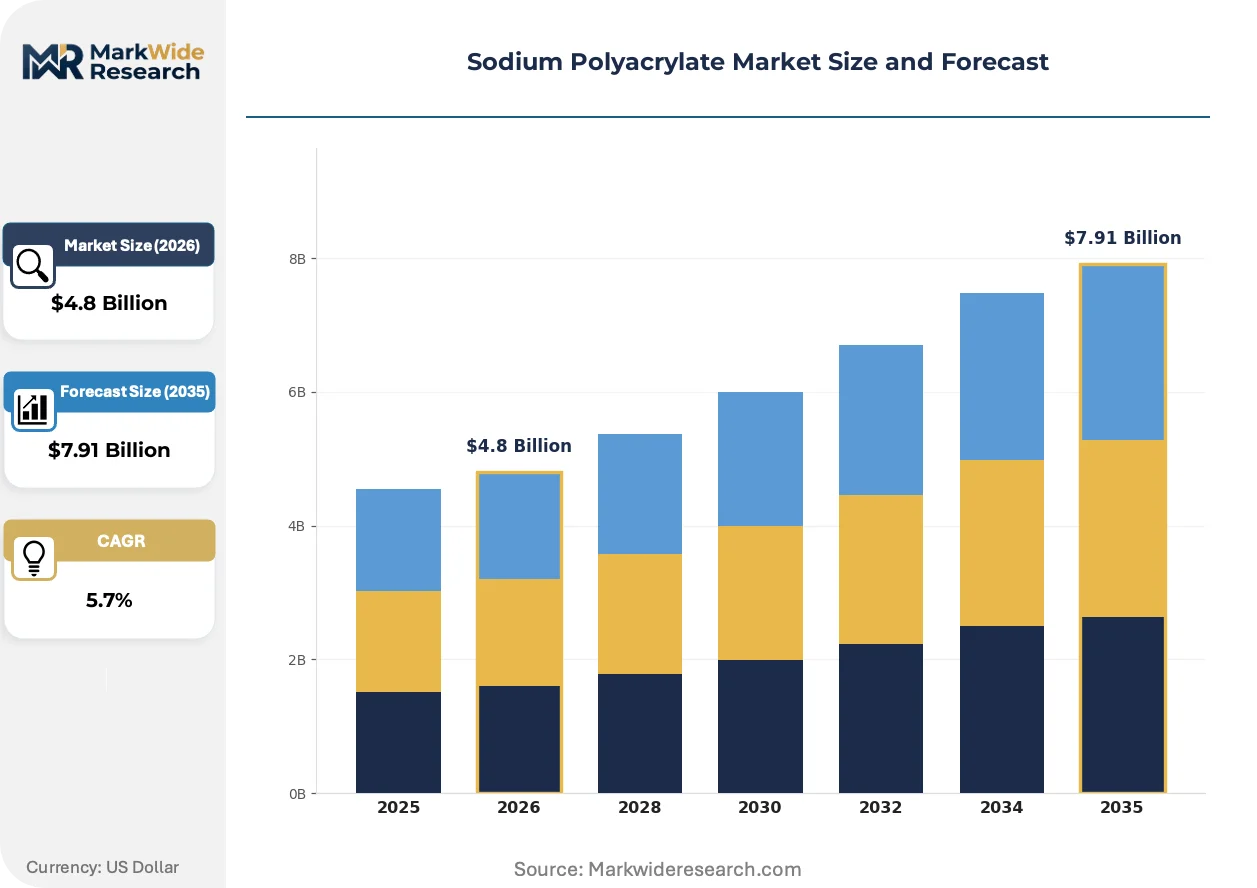
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Super Absorbent Polymers, Hydrogel Forms, Granules, Powder End Use Industry: Agriculture, Personal Care, Pharmaceuticals, Waste Management Formulation: Liquid, Solid, Semi-Solid, Gel Packaging Type: Bags, Drums, Totes, Pails |
| Companies Covered | Evonik Industries AG, Sumitomo Seika Chemicals, Nippon Shokubai, Showa Denko, Formosa Plastics Corporation, BASF SE, Sanyo Chemical Industries, SNF Holding Company, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Polyacrylate Market Evolving Landscape
Bio-based feedstock integration, regulatory-driven purity escalation, and pharmaceutical application expansion are restructuring competitive advantage around certification depth and backward integration rather than commodity scale alone.
Surface-crosslinked sodium polyacrylate with optimized particle size distribution is converging with high-speed diaper manufacturing lines, enabling thinner core designs without absorbency sacrifice. Japanese hygiene product manufacturers are adopting these grades fastest, compressing demand for conventional standard-density polymers in premium segments.
EU REACH restrictions on acrylic acid residual monomers are forcing reformulation investments across personal care supply chains. Manufacturers serving European baby diaper brands now require third-party certification below 300 ppm thresholds, shifting procurement preference toward producers with advanced neutralization and washing protocols.
Brand-owner Scope 3 carbon accounting is redirecting procurement toward suppliers with verified bio-based content. Consumer goods companies with 2030 net-zero commitments are embedding renewable feedstock requirements into super absorbent polymer tenders, with preference weighting for producers offering mass-balance certification from European chemical complexes.
Sodium Polyacrylate Market Segmentation
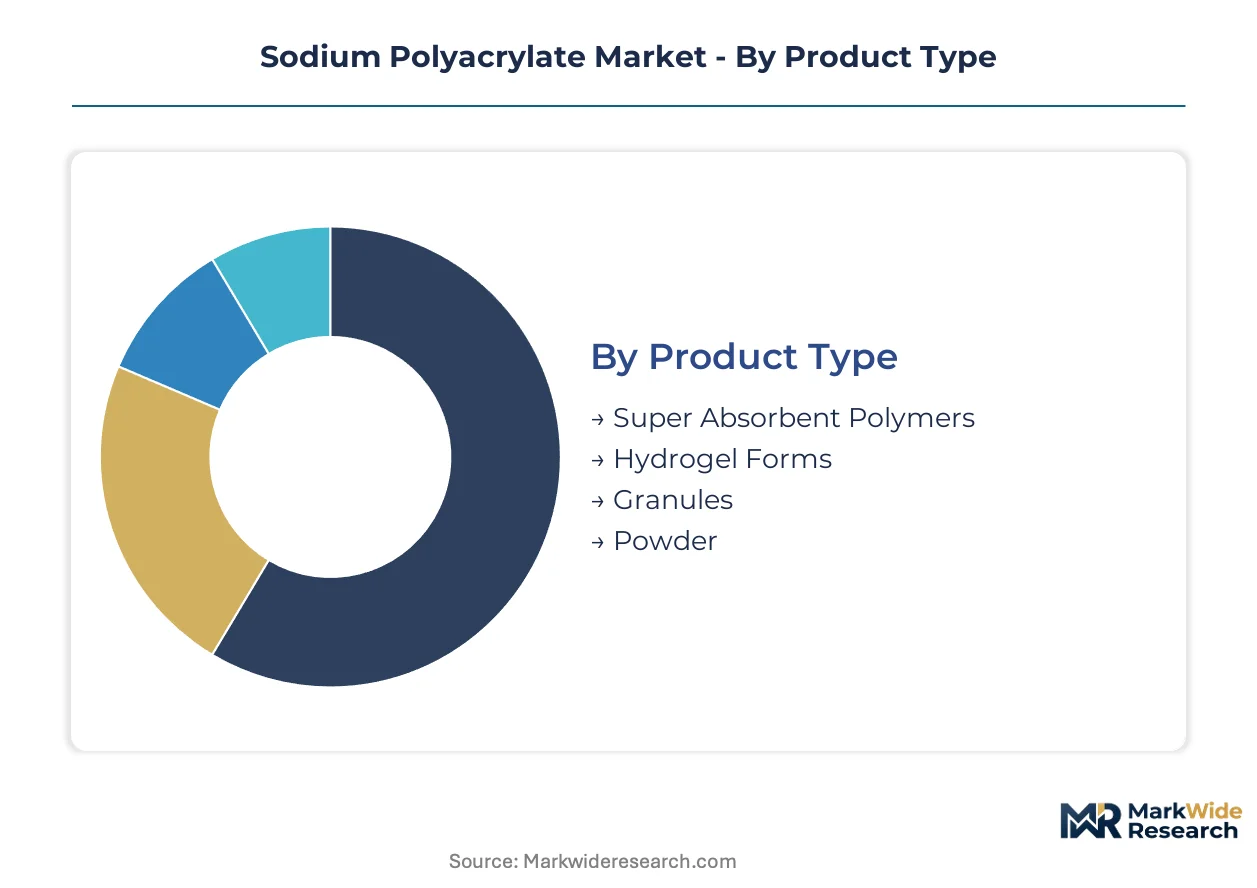
Sodium polyacrylate's absorption kinetics and cross-link density vary sharply across product architectures, creating distinct procurement specifications for each end-use channel. Formulation and packaging choices directly determine logistics economics and shelf stability, particularly for moisture-sensitive pharmaceutical grades.
Product Type:
Cross-link density and particle architecture separate performance tiers, with surface-modified variants commanding specification premiums in high-speed manufacturing environments.
- Super Absorbent Polymers:Cross-linked sodium polyacrylate with absorption capacities exceeding 300 times mass in deionized water dominates baby diaper cores and adult incontinence products. Procurement from Southeast Asian hygiene manufacturers is tightening around EU REACH residual monomer thresholds below 300 ppm.
- Hydrogel Forms:Three-dimensional hydrophilic polymer networks with tunable pore structures serve wound dressing substrates and drug delivery matrices. German and Japanese pharmaceutical manufacturers are expanding orders for high-purity grades, driving capacity upgrades at specialized polymerization facilities.
- Granules:Solid particulate formulations with controlled particle size distribution anchor agricultural moisture retention and industrial spill containment applications.
- Powder:Fine-milled sodium polyacrylate with rapid hydration kinetics targets cement admixtures and specialty coatings where dispersion speed matters.
Mature deployment sits with super absorbent polymers in personal care. Newer deployment is concentrated in hydrogel forms for pharmaceutical applications.
End Use Industry:
Volume concentration and margin structure diverge across end-use channels, with regulatory intensity escalating fastest in consumer-facing segments.
- Agriculture:Granular super absorbent polymers for soil moisture retention are gaining traction in drought-prone Indian states, with state agricultural departments exploring subsidy frameworks for smallholder adoption.
- Personal Care:Baby diaper and adult incontinence manufacturers in Southeast Asia are requalifying suppliers amid tightening EU REACH compliance on residual monomer content, compressing margins for non-integrated producers.
- Pharmaceuticals:High-purity hydrogel grades for wound dressings and transdermal drug delivery matrices are climbing the fastest, with Japanese and German manufacturers leading formulation innovation.
- Waste Management:Solid sodium polyacrylate formulations for liquid waste solidification and landfill leachate control operate on specification-grade procurement with lower purity thresholds than personal care.
Volume leadership resides in personal care procurement. Steepest expansion trajectory is emerging in pharmaceutical-grade hydrogel applications.
Formulation:
Rheological behavior and handling characteristics determine logistics infrastructure requirements, with semi-solid and gel forms demanding specialized temperature-controlled distribution.
- Liquid:Low-viscosity aqueous solutions or dispersions of sodium polyacrylate serve industrial coating and adhesive applications where pre-dissolved formats reduce processing steps.
- Solid:Dried granular or powder forms occupy volume leadership across agriculture and waste management segments where spreading equipment compatibility and shelf stability dominate procurement criteria.
- Semi-Solid:Intermediate viscosity preparations bridge processing gaps in specialty manufacturing where controlled hydration rates matter.
- Gel:Fully hydrated hydrogel forms with defined cross-link density target pharmaceutical wound care and drug delivery applications requiring biocompatibility certification.
Standard procurement gravitates toward solid formulations for handling simplicity. Emerging demand is concentrating in gel formats for pharmaceutical specification compliance.
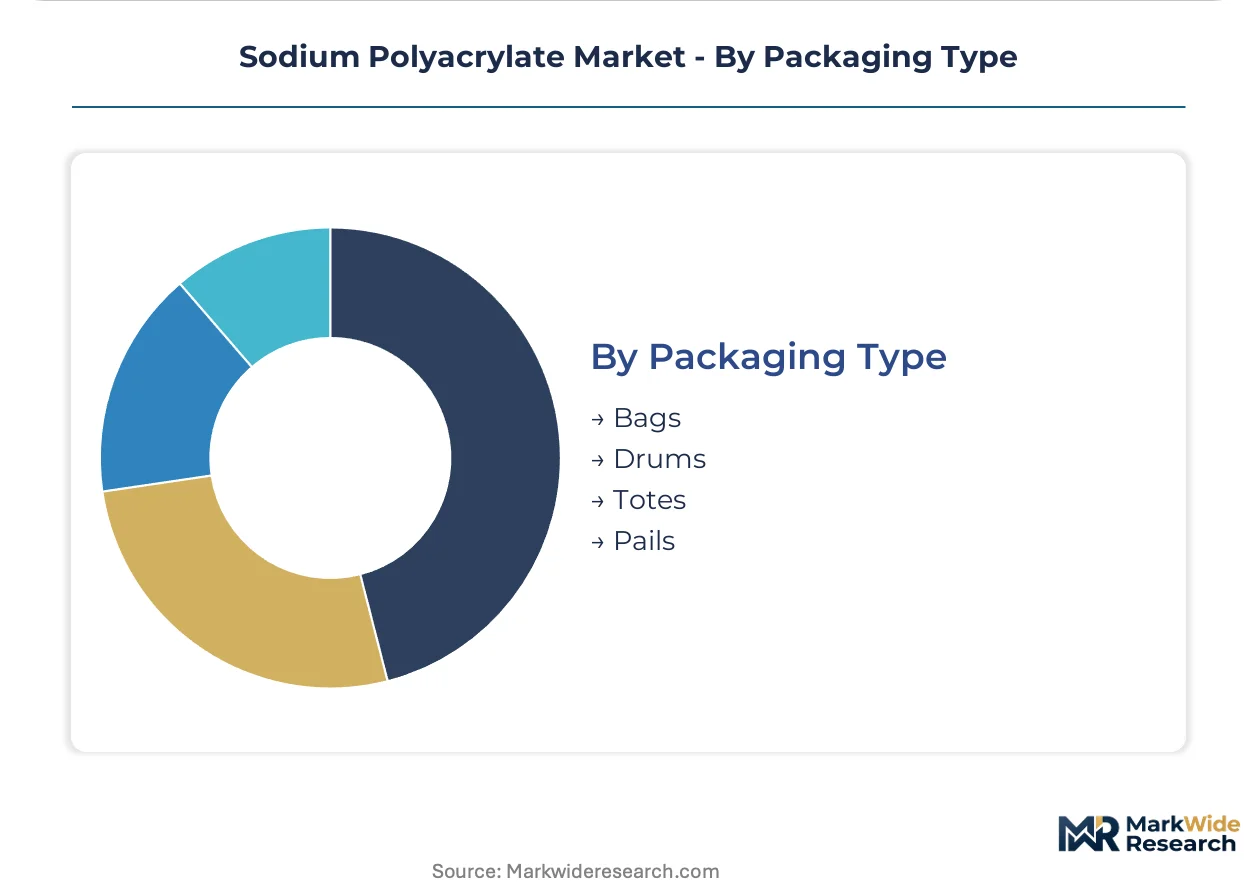
Packaging Type:
Unit economics and contamination risk shape packaging selection, with bulk formats favored in high-volume agriculture and sealed pharmaceutical-grade containers commanding premiums.
- Bags:Multi-layer polymer bags with moisture barriers serve agricultural and industrial applications where palletized handling and weather resistance balance cost against protection.
- Drums:Steel or fiber drums with sealed closures target pharmaceutical and food-contact applications requiring contamination prevention and lot traceability.
- Totes:Intermediate bulk containers with liner systems capture mid-volume procurement from diaper manufacturers seeking reduced handling labor versus drums.
- Pails:Smaller-format plastic pails with tamper-evident seals serve laboratory, pharmaceutical compounding, and specialty industrial applications where batch sizes remain limited.
Scale deployment favors bags and totes for volume efficiency. Precision deployment is migrating toward drums and pails for regulated pharmaceutical channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Shandong Free Trade Zone anchors the densest concentration of acrylic acid-to-SAP integrated complexes, drawing procurement from Southeast Asian hygiene manufacturers seeking volume reliability and regulatory compliance pathways.
China
Shandong province hosts vertically integrated production corridors linking acrylic acid crackers to super absorbent polymer finishing lines. MEE discharge permits and GB standards compliance create export certification layers for producers serving EU-bound supply chains. Qingdao and Zibo chemical clusters are expanding hydrogel-grade capacity to capture pharmaceutical demand from Japanese and German wound-care manufacturers.
Germany
Evonik Industries AG leverages backward integration into acrylic acid to sustain margin stability across European operations amid tightening REACH residual monomer thresholds. ECHA compliance requirements below 300 ppm are accelerating supplier consolidation, favoring producers with advanced neutralization and washing protocols. The Marl chemical complex anchors high-purity grade production for pharmaceutical hydrogel applications.
Japan
Sumitomo Seika Chemicals and Nippon Shokubai compete through differentiated positioning in the Himeji and Kawasaki industrial belts. METI industrial standards and PMDA pharmaceutical-grade certifications constrain new entrant qualification timelines to 18-24 months. Osaka-based hygiene product manufacturers are adopting surface-crosslinked grades fastest, compressing demand for conventional standard-density polymers in premium diaper segments.
United States
EPA TSCA residual monomer constraints and state-level discharge permits shape operational parameters for petroleum-based acrylic acid routes. The Gulf Coast petrochemical corridor faces margin pressure from naphtha pricing volatility and cracker economics tightening. Brand-owner Scope 3 carbon accounting is redirecting procurement interest toward mass-balance certified bio-feedstock pathways, though fermentation-derived acrylic acid remains cost-prohibitive at commercial scale.
India
Drought-prone states in Maharashtra and Karnataka are piloting super absorbent polymers for agricultural moisture retention, with state agricultural departments exploring subsidy frameworks for smallholder adoption. BIS certification requirements and CDSCO pharmaceutical-grade standards create dual compliance tracks for suppliers targeting personal care versus wound-care applications. Gujarat chemical clusters are emerging as import substitution hubs for diaper-grade SAP procurement.
Sodium Polyacrylate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with backward-integrated petrochemical conglomerates commanding procurement preference in high-volume personal care while specialized polymerization houses capture pharmaceutical-grade premiums. Three archetypes dominate: integrated petrochemical majors with captive acrylic acid supply, specialized hydrogel manufacturers with pharmaceutical certification depth, and regional scale players serving agricultural and industrial spill-containment segments. Competitive moves concentrate on capacity expansion in Shandong province and strategic partnerships for bio-based feedstock qualification.
Among German-based chemical conglomerates, Evonik Industries AG and BASF SE occupy positions defined by upstream control over acrylic acid intermediates and REACH compliance infrastructure. Japanese specialists including Sumitomo Seika Chemicals and Nippon Shokubai exemplify the high-purity hydrogel tier, with Showa Denko representing diversified chemical portfolio approaches to the segment. LG Chem anchors Korean-scale manufacturing, while SNF Holding Company and Sanyo Chemical Industries sit within regional supply architectures serving distinct procurement geographies.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Sumitomo Seika Chemicals |
| Nippon Shokubai |
| Showa Denko |
| Formosa Plastics Corporation |
| BASF SE |
| Sanyo Chemical Industries |
| SNF Holding Company |
| LG Chem |
| Others |
Value Network & Pricing Analysis
Southeast Asian baby diaper manufacturers anchor procurement volume and negotiate contract structures indexed to acrylic acid feedstock costs, with pricing power concentrating among backward-integrated producers in China's Shandong province.
Pricing Analysis
Short lead-time premiums apply to pharmaceutical-grade hydrogel orders from German and Japanese wound-care manufacturers, while spot inventory discounts emerge in agricultural-grade granules during harvest-season demand troughs. Three-tier pricing structure across pharmaceutical certification, personal care standard, and agricultural economy levels reflects residual monomer thresholds and purity grades. Cost compression in personal care tiers is intensifying because REACH compliance investments are squeezing non-integrated suppliers. Agricultural buyers exhibit highest price sensitivity due to subsidy-dependent procurement, while pharmaceutical manufacturers accept premiums for PMDA and ECHA-certified grades.
Supply Chain Analysis
Single-source vulnerability sits with acrylic acid supply from petroleum-based crackers in China's Shandong and Jiangsu provinces, where integrated complexes control upstream feedstock. Production draws from propylene derivatives, sodium hydroxide neutralization agents, and cross-linking monomers. Tariff exposure on acrylic acid intermediates threatens margin stability for export-oriented diaper manufacturers. Distribution runs through bulk rail and containerized ocean freight to Southeast Asian hygiene plants, with pharmaceutical grades requiring temperature-controlled air freight to German and Japanese facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based acrylic acid feedstocks are displacing petroleum-derived routes as brand-owner Scope 3 mandates harden, creating a technology-transition phase where fermentation pathways and mass-balance certification determine competitive viability.
For Market Incumbents: Acquire fermentation-based acrylic acid technology licenses to secure bio-feedstock pathways ahead of EU Green Deal renewable content thresholds. Defensive consolidation should prioritize REACH-certified capacity in Germany and captive cracker economics in China, as residual monomer compliance investments are raising barriers for non-integrated competitors.
For New Entrants and Emerging Players: Indian state agricultural departments represent an underserved buyer archetype with pilot subsidy programs for moisture-retention hydrogels. White-space targets include drought-prone Maharashtra and Karnataka smallholder segments, plus transdermal patch manufacturers testing sodium polyacrylate drug delivery matrices. Go-to-market positioning should emphasize BIS certification and state-level subsidy navigation.
For Investors and Strategic Acquirers: The window for entry favors specialized hydrogel manufacturers with pharmaceutical-grade certification depth and backward-integrated acrylic acid supply. Long-term viability rests on bio-feedstock transition timelines and regulatory divergence between EU REACH and Chinese GB standards. The inflection signal to watch is mass-balance certification adoption rates among European chemical complexes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Evonik and Shandong producers sustain margin stability amid feedstock volatility. |
| Pharmaceutical-Grade Certification Investment | Sumitomo Seika captures wound-dressing premiums through PMDA compliance. |
| Bio-Based Feedstock Transition | Fermentation-derived routes align with brand-owner Scope 3 procurement mandates. |
| Capacity Expansion in Shandong Province | Integrated complexes anchor supply reliability for Southeast Asian diaper manufacturers. |
| Long-Term Supply Agreement with Hygiene OEMs | Contract structures indexed to acrylic acid costs reduce procurement volatility. |
Research Methodology
Independent corroboration across plant managers at acrylic acid-to-SAP complexes, procurement leads at Southeast Asian diaper manufacturers, and distribution channel partners underwrites the qualitative findings. Primary interviews with technical R&D directors at Japanese and German hydrogel specialists combined with secondary validation from customs/trade data, ACC/Cefic chemical industry reports, and SEC 10-K filings of listed petrochemical conglomerates established demand-side and supply-side baselines. Bottom-up capacity assessments and top-down end-use consumption estimates were triangulated to resolve segmentation splits.
Rate-of-change decomposition across the analysis window separated volume growth into feedstock cost pass-through, grade-mix shifts toward pharmaceutical purity, and geographic demand rebalancing. Segmentation dimensions modeled include product architecture (super absorbent polymer, hydrogel, granule, powder), end-use industry (personal care, pharmaceutical, agriculture, waste management), formulation state, and regional production hub. CAGRs were derived from regression against acrylic acid price indices and diaper shipment data. Industry-specific forecast inputs incorporated REACH residual monomer threshold enforcement timelines and Indian agricultural subsidy program expansion.
Revisions become necessary when bio-based acrylic acid cost curves flatten, EU REACH thresholds tighten beyond 300 ppm, or Shandong province environmental discharge permits restrict capacity utilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Brazil Engineering Plastics Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
Global Acrylic Emulsions Market
Polymers & Resins
Polyamide Resins Market
Polymers & Resins
Bio Based Resin Market
Polymers & Resins
Rigid Spray Polyurethane Foam Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Polycide Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Global Acrylic Polymer Market
Polymers & Resins
Europe Fluoropolymer Market