
 Polyester Polyol Market | 2026-2036
Polyester Polyol Market Size, Share, and Industry Trends Forecast 2026-2036
Polyester Polyol Market Outlook
Buyer concentration among automotive seating and insulation contractors is hardening as tier-one suppliers consolidate polyurethane procurement. BASF SE leverages integrated adipic acid-to-polyol streams across European manufacturing corridors. Covestro AG anchors its position through high-performance aliphatic grades serving coatings formulators. Huntsman Corporation differentiates via specialized aromatic formulations for rigid foam insulation systems.
Polyester polyols are hydroxyl-terminated polyesters synthesized from dicarboxylic acids and diols, with molecular weights typically ranging from 1,000 to 3,000 g/mol, engineered primarily as polyurethane building blocks for foams, elastomers, and coatings. Standard polyester polyol retains volume leadership across construction insulation applications where cost-performance ratios dominate specification decisions. Bio-based polyester polyol captures accelerated interest from automotive OEMs pursuing scope-three emissions reductions in seating and interior components. Aromatic polyester polyol commands premium positioning within industrial coatings requiring enhanced thermal and chemical resistance profiles.
EPA regulations under TSCA constrain phthalate-based formulations in US consumer goods applications, while REACH authorization procedures in Europe restrict certain aromatic amine precursors used in conventional synthesis pathways. China's MEE enforces dual carbon compliance thresholds on petrochemical operations, elevating capital requirements for conventional adipic acid routes. Stakeholders must evaluate feedstock pivot timelines against certification lag periods to secure formulation approvals in tightening regulatory environments.
Market Dynamics
Automotive OEMs are consolidating polyurethane seating specifications around bio-based feedstock content, compressing formulation approval cycles and forcing adipic acid suppliers to certify renewable carbon pathways ahead of traditional petrochemical routes.
Growth Catalysts
- EU Green Deal compliance mandates:REACH authorization timelines for conventional aromatic amines are accelerating formulator migration toward aliphatic polyester polyol grades in European coatings applications.
- China's dual carbon enforcement:MEE thresholds on adipic acid production are redirecting capital toward bio-based diol feedstocks in Shandong and Jiangsu manufacturing clusters.
- Automotive seating lightweighting:Foam density reduction targets in electric vehicle platforms are pulling high-functionality aromatic grades into structural interior components previously served by metal.
Market Restraints
- Adipic acid price volatility:Cyclohexane feedstock exposure and benzene derivative swings compress margin predictability for integrated polyol producers.
- Chinese supply concentration:Over half of global adipic acid capacity sits in Shandong province, creating single-point vulnerability to environmental compliance shutdowns.
- Technical ceiling on bio-content:Current bio-based polyester polyols face hydrolytic stability trade-offs that limit replacement rates in high-humidity automotive applications.
Strategic Opportunities
- Indian construction insulation:Bureau of Indian Standards energy code enforcement is opening specification windows for rigid foam systems in commercial building envelopes.
- Coatings-applicator direct channels:Industrial maintenance contractors are bypassing distributor tiers to secure volume pricing on aliphatic grades for chemical-resistant topcoats.
- ISO 14001 certification acceleration:Scope-three accounting requirements are creating first-mover advantage for suppliers with cradle-to-gate lifecycle data.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise in hydrolysis-resistant bio-polyol design concentrates among retiring specialists in European and Japanese R&D centers.
- REACH authorization timelines:New substance notification procedures extend market entry by 18-24 months for novel diacid feedstocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyester Polyol Market |
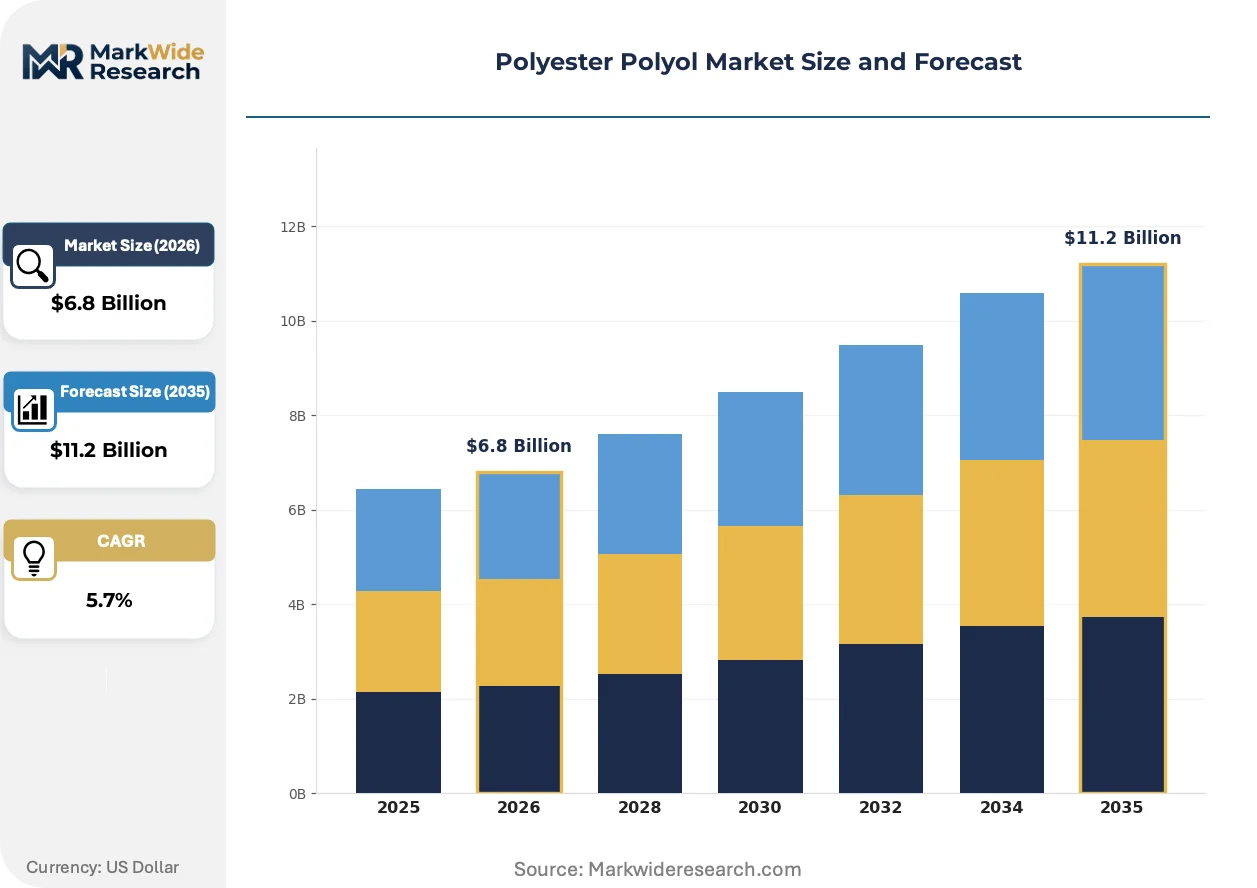
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Polyester Polyol, Bio-Based Polyester Polyol, Aromatic Polyester Polyol, Aliphatic Polyester Polyol Application: Automotive, Construction, Coatings, Adhesives End User: Consumer Goods, Industrial, Furniture, Electronics Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Stepan Company, BASF SE, Covestro AG, Huntsman Corporation, COIM Group, Arkema, Dow Inc., Wanhua Chemical Group, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyester Polyol Market Strategic Shifts
Polyester polyol production is fragmenting into smaller, distributed units capable of switching feedstock streams between petrochemical and renewable diols within campaign cycles.
Continuous adipic acid-to-polyol reactor systems are modularizing plant scale, enabling 10-50 kilotonne units to match regional foam demand without pipeline infrastructure. Tier-two Chinese producers are deploying these systems in inland provinces to serve construction insulation contractors directly. The technology is modularizing capital deployment away from coastal mega-sites toward demand-adjacent production nodes.
REACH authorization procedures for aromatic amine precursors are tightening substitution timelines, forcing coatings formulators to validate aliphatic polyester polyol performance in high-temperature industrial applications. German automotive OEMs are requiring supplier documentation on precursor origin. The regulation is compressing specification windows for conventional aromatic grades across European industrial coatings.
Automotive seating contractors are consolidating polyurethane procurement under single-source agreements with formulation houses, displacing spot purchasing through distributor networks. Tier-one suppliers now specify bio-content thresholds and lifecycle data as contractual terms. The behavior is concentrating in German and US Midwest automotive corridors where OEM sustainability scorecards drive supplier selection.
Polyester Polyol Market Segmentation
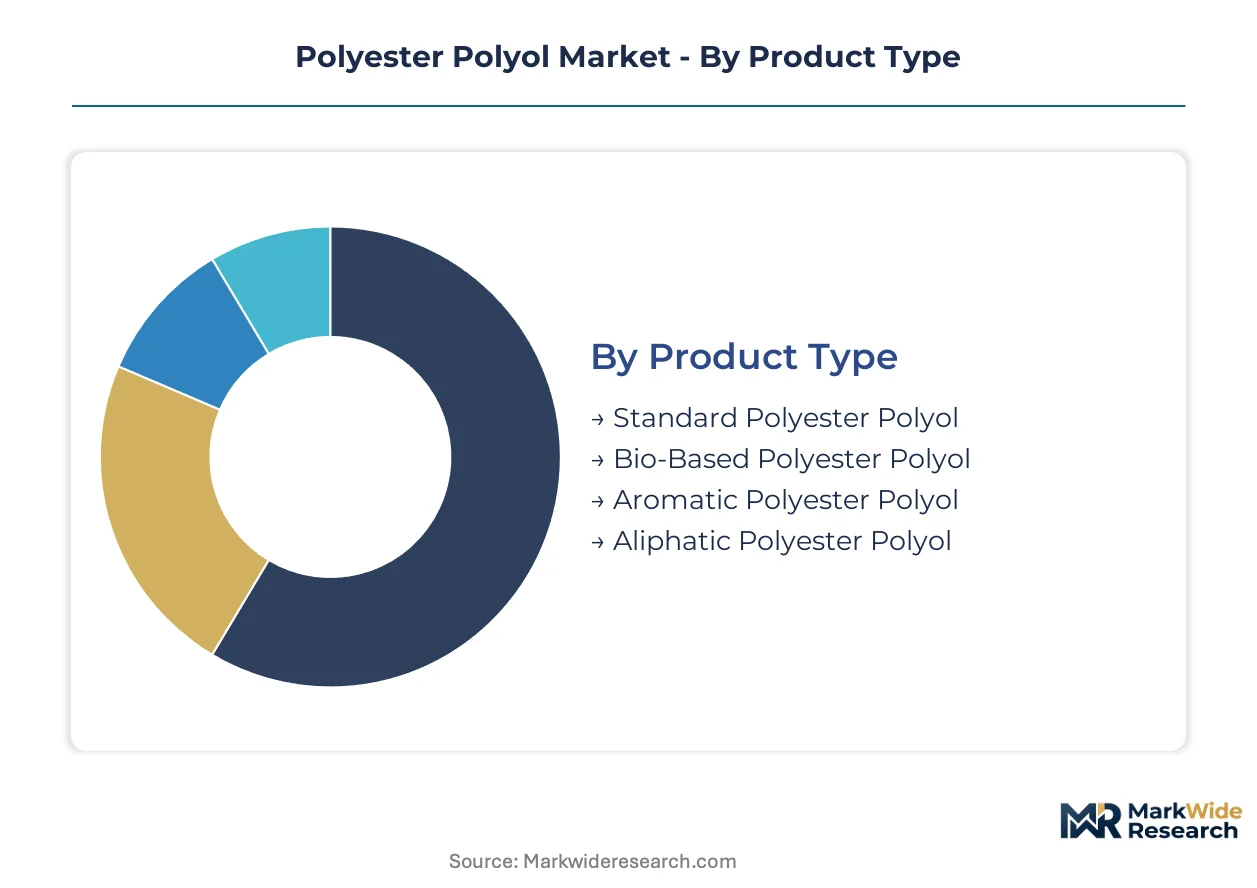
Segmentation in polyester polyols determines which certification pathways formulators must navigate. Product chemistry dictates REACH authorization requirements, while end-use specifications drive ISO 14001 documentation intensity.
Product Type:
REACH authorization timelines vary sharply across chemistries, with aromatic grades facing the tightest substitution deadlines under ECHA procedures.
- Standard Polyester Polyol:Conventional adipic acid-based formulations dominate construction insulation specifications where cost-performance ratios govern procurement. Demand concentrates in German and Chinese rigid foam systems serving commercial building envelopes, though margin pressure from cyclohexane feedstock volatility constrains producer flexibility.
- Bio-Based Polyester Polyol:Renewable diol feedstocks from castor oil or succinic acid routes command automotive OEM interest for scope-three emissions accounting. German seating contractors now require cradle-to-gate lifecycle data as contractual terms, compressing certification timelines for suppliers lacking ISO 14001 documentation.
- Aromatic Polyester Polyol:High-functionality grades deliver thermal and chemical resistance for industrial coatings. REACH restrictions on aromatic amine precursors are forcing formulators toward aliphatic alternatives in European applications.
- Aliphatic Polyester Polyol:Light-stable formulations serve premium coatings where weathering resistance commands specification priority. UV durability drives adoption in automotive exterior clearcoats.
Leading the category by volume: Standard Polyester Polyol. Growing fastest: Bio-Based Polyester Polyol.
Application:
Application segmentation tracks diverging margin structures, with coatings commanding premium pricing against commodity foam volumes.
- Automotive:Seating foam specifications consolidate under tier-one supplier agreements with bio-content thresholds. Electric vehicle lightweighting targets pull high-functionality grades into structural interior components.
- Construction:Rigid foam insulation for commercial building envelopes represents the volume anchor. Bureau of Indian Standards energy code enforcement in India is opening specification windows for polyurethane systems.
- Coatings:Industrial maintenance applications drive aliphatic grade demand where chemical resistance and thermal stability justify premium positioning. Direct procurement channels are displacing distributor tiers.
- Adhesives:Structural bonding applications in furniture and electronics assembly favor hydrolysis-resistant formulations. Moisture sensitivity limits bio-based substitution rates.
Construction holds the volume lead. Automotive exhibits the steepest expansion trajectory on electrification-driven lightweighting.
End User:
End-user segmentation reveals diverging sustainability pressure intensity, with consumer-facing industries subject to stricter disclosure mandates.
- Consumer Goods:EPA TSCA phthalate restrictions constrain formulation options in US markets. Mattress and bedding applications face heightened chemical transparency requirements.
- Industrial:Maintenance coatings and specialty adhesives prioritize performance over bio-content. Procurement centers on technical specification compliance.
- Furniture:Flexible foam cushioning for residential and commercial seating follows automotive sustainability scorecard adoption. Major retailers now require supplier environmental documentation.
- Electronics:Encapsulation and potting compounds demand ultra-low moisture uptake. Hydrolytic stability requirements exclude most current bio-based offerings.
Industrial end users dominate current offtake. Consumer Goods is climbing the fastest on retailer-driven chemical transparency mandates.
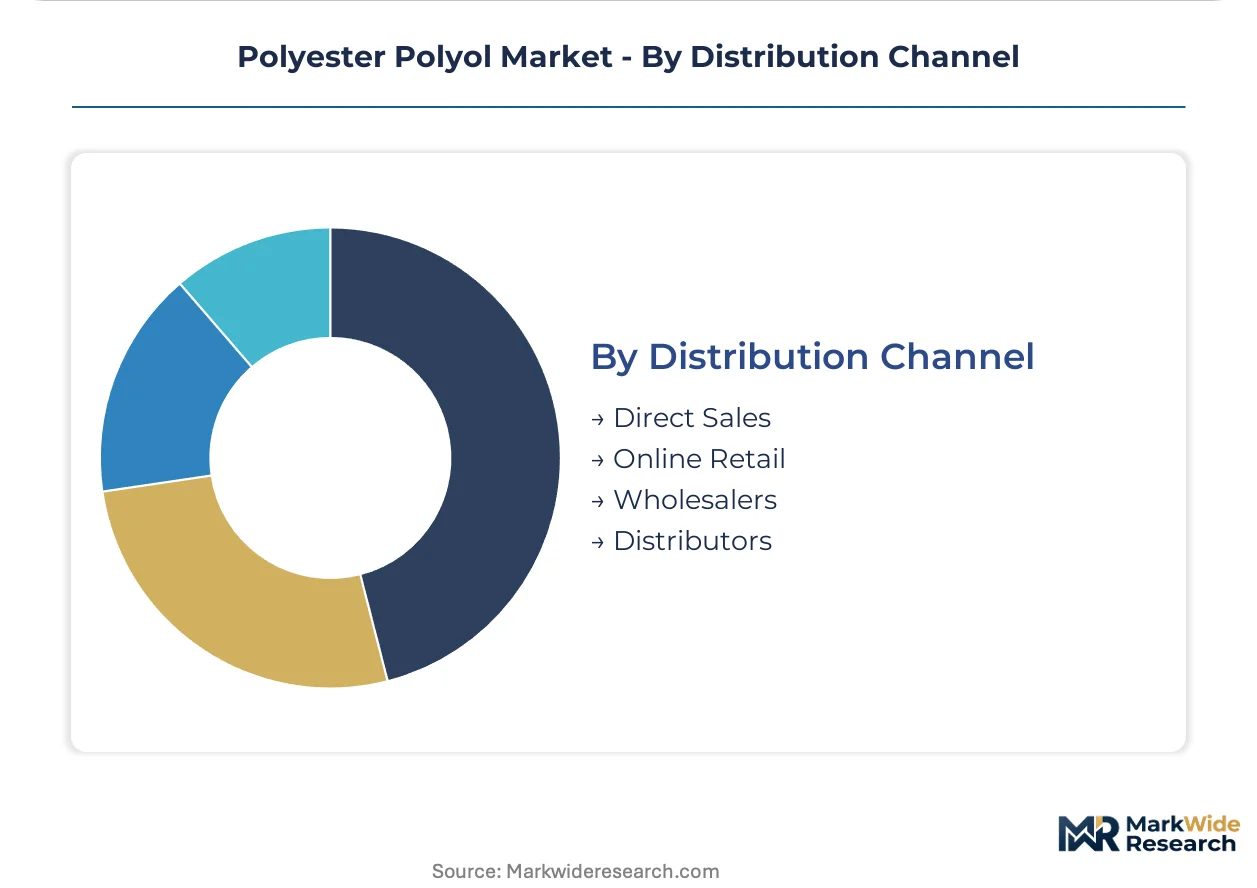
Distribution Channel:
Channel segmentation reflects procurement consolidation trends, with volume concentration favoring direct relationships over fragmented intermediation.
- Direct Sales:Tier-one automotive seating contractors and industrial coatings applicators negotiate single-source agreements with formulation houses. Lifecycle data and bio-content thresholds now appear as contractual terms.
- Online Retail:Specialty grades for small-batch adhesives and prototype coatings move through digital platforms. Technical documentation accessibility drives platform selection.
- Wholesalers:Construction insulation contractors in inland Chinese provinces source standard grades through regional bulk distributors. Inventory proximity outweighs price optimization.
- Distributors:Spot purchasing for maintenance coatings and aftermarket automotive applications persists where formulation flexibility matters. Margin compression from direct channel expansion is forcing portfolio specialization.
Direct Sales leads by value contribution. Online Retail is gaining share fastest on small-batch specialty demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Adipic acid production corridors in Shandong province anchor polyester polyol supply geography. German automotive corridors and US Midwest manufacturing belts concentrate downstream formulation demand. Regulatory fragmentation across REACH, EPA TSCA, and China's MEE thresholds is redirecting investment toward bio-based feedstock certification.
China
Shandong and Jiangsu manufacturing clusters host over half of global adipic acid capacity. MEE dual carbon enforcement is elevating capital requirements for conventional petrochemical routes. Zibo and Yantai chemical parks are redirecting investment toward bio-based diol feedstocks to maintain operating licenses under tightening emissions thresholds.
Germany
Automotive seating contractors in Bavaria and Baden-Württemberg are consolidating polyurethane procurement under single-source agreements with bio-content thresholds. REACH authorization timelines for aromatic amine precursors are compressing specification windows for conventional grades. Ludwigshafen and Leverkusen chemical corridors anchor integrated adipic acid-to-polyol production streams.
United States
EPA TSCA regulations constrain phthalate-based formulations in consumer goods applications across automotive and bedding sectors. Michigan and Ohio automotive corridors are pulling high-functionality aromatic grades into electric vehicle interior components. Gulf Coast petrochemical infrastructure supports cyclohexane feedstock access for standard polyester polyol production.
India
Bureau of Indian Standards energy code enforcement is opening specification windows for rigid foam insulation in commercial building envelopes across Maharashtra and Gujarat. Construction activity in Mumbai and Ahmedabad is driving demand for cost-optimized standard grades. Domestic adipic acid capacity constraints are forcing insulation contractors to rely on regional bulk distributors for inventory proximity.
Japan
Polymer chemist expertise in hydrolysis-resistant bio-polyol design concentrates among retiring specialists in Kanto and Kansai R&D centers. METI industrial policy is supporting succinic acid route development for renewable diol feedstocks. Osaka and Nagoya chemical clusters maintain formulation capabilities for electronics encapsulation applications demanding ultra-low moisture uptake.
Polyester Polyol Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bio-based certification pathways and modular production scale. The vendor base stratifies across integrated petrochemical majors, regional formulation houses, and specialty aliphatic grade suppliers. Three archetypes dominate: backward-integrated adipic acid producers, coatings-focused aliphatic specialists, and automotive-seating formulation partners. Competitive intensity centers on M&A consolidation among tier-two Chinese producers and strategic partnerships for renewable feedstock certification.
Within the integrated petrochemical tier, BASF SE and Covestro AG occupy positions exemplifying European manufacturing corridor dominance. Huntsman Corporation anchors the specialty formulation archetype serving rigid foam insulation systems. Among Asia-Pacific producers, Wanhua Chemical Group represents scale-driven capacity expansion in Shandong province. Stepan Company and Dow Inc. sit within the North American supplier set confronting EPA TSCA compliance thresholds. These named entities illustrate competitive positioning without exhaustively cataloging market presence.
| Leading Market Players |
|---|
| Stepan Company |
| BASF SE |
| Covestro AG |
| Huntsman Corporation |
| COIM Group |
| Arkema |
| Dow Inc. |
| Wanhua Chemical Group |
| Evonik Industries AG |
| Others |
Value Chain & Pricing Dynamics
Cyclohexane feedstock costs cascade through adipic acid conversion into three distinct pricing tiers downstream, with benzene derivative volatility compressing margin predictability for integrated producers serving automotive seating contractors and construction insulation formulators.
Pricing Analysis
Lifecycle documentation and technical service bundling separate premium aliphatic grades from unbundled standard polyester polyol transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with ISO 14001 cradle-to-gate data commanding measurable premiums from German automotive OEMs. Cost compression in standard grades is intensifying because Shandong adipic acid oversupply is eroding spot contract leverage. Tier-one automotive seating contractors exhibit lowest price sensitivity, while inland Chinese construction insulation contractors prioritize inventory proximity over grade optimization.
Supply Chain Analysis
Adipic acid supply rests on Shandong province petrochemical corridors, German Ludwigshafen chemical parks, and US Gulf Coast cyclohexane infrastructure. Raw material flows draw from benzene derivatives, renewable diol feedstocks from castor oil and succinic acid routes, and specialized aliphatic diacid precursors. Single-source vulnerability concentrates in Shandong environmental compliance shutdowns under MEE dual carbon enforcement. Distribution runs through direct sales channels for tier-one automotive contractors and regional bulk wholesalers serving inland construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyester polyol competitive dynamics have become a vertical-integration race, with backward control over adipic acid conversion and renewable diol certification emerging as the decisive margin levers.
For Market Incumbents: Anticipate REACH authorization deadlines for aromatic amine precursors by accelerating aliphatic grade capacity in German chemical corridors. Secure captive adipic acid supply through upstream partnership structures in Shandong to mitigate environmental shutdown exposure. Bio-based certification investment represents the priority defensive move against emerging succinic acid route entrants.
For New Entrants and Emerging Players: Indian construction insulation contractors present the most penetrable buyer archetype, with Bureau of Indian Standards energy code enforcement creating specification windows for rigid foam systems. Modular 10-50 kilotonne production units in Maharashtra and Gujarat bypass coastal mega-site capital requirements. Direct procurement relationships with regional building envelope contractors offer the strongest go-to-market angle against established distributor networks.
For Investors and Strategic Acquirers: Tier-two Chinese producers securing MEE operating licenses under dual carbon thresholds is the leading indicator that consolidation value will concentrate in compliant adipic acid-to-polyol assets. Long-term viability over the next decade favors backward-integrated specialists with renewable feedstock certification pathways. Watch for REACH authorization rejections on aromatic amine precursors as the signal that aliphatic grade premiums will structurally expand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adipic Acid | Captive supply from Shandong or Ludwigshafen corridors insulates margin from benzene volatility. |
| Bio-Based Feedstock Certification | ISO 14001 cradle-to-gate documentation satisfies German automotive OEM contractual terms. |
| Modular Production Scale Deployment | 10-50 kilotonne units in inland provinces match regional construction demand without pipeline infrastructure. |
| REACH-Compliant Aliphatic Grade Expansion | Aliphatic polyester polyol capacity captures substitution demand from restricted aromatic amine routes. |
| Direct Sales Channel Concentration | Single-source agreements with tier-one seating contractors displace fragmented distributor purchasing. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving polyurethane plant managers, automotive tier-one procurement leads, coatings formulators, distribution channel partners, and technical R&D directors at adipic acid producers. Secondary sources incorporated ECHA REACH authorization databases, MEE emissions compliance disclosures, SEC 10-K chemical segment filings, and Bureau of Indian Standards energy code documentation. Bottom-up capacity modeling and top-down demand triangulation validated volume estimates across the analysis window.
Segmentation granularity operated at product chemistry tier, end-use industry, regional production hub, and certification status levels throughout the forecast period. CAGRs derived from weighted average growth contributions across automotive lightweighting, construction insulation code enforcement, and coatings substitution dynamics. Key inputs included electric vehicle platform foam density specifications, Shandong environmental compliance thresholds, and REACH authorization timeline assumptions for aromatic amine precursors.
Revisions become necessary when MEE enforcement intensity shifts, REACH authorization outcomes diverge from baseline assumptions, or bio-based hydrolytic stability breakthroughs alter automotive substitution rates. Forecasts reflect documented assumptions on feedstock pivot timelines and certification lag periods. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Polyamide Precursors Market
Polymers & Resins
Thermoplastic Polyester Engineering Resin (TPER) Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Smart Polymers Market
Polymers & Resins
South America Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Global Thermoset Resin Market
Polymers & Resins
Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Polymer Resin Market
Polymers & Resins
Global Thermosetting Polymer Market