
 Vinyl Acetate Homopolymer Emulsion Market | 2026-2036
Vinyl Acetate Homopolymer Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Acetate Homopolymer Emulsion Market Outlook
Acrylic resin is pivoting away from high-cost architectural coatings in several European projects, creating margin pressure that vinyl acetate homopolymer emulsion suppliers exploit through cost-performance positioning. Celanese Corporation leverages backward integration into vinyl acetate monomer to sustain feedstock cost advantages across North American adhesive markets. Wacker Chemie AG anchors its competitiveness through specialized emulsion polymerization technology for textile finishing applications in Central European manufacturing clusters.
Vinyl acetate homopolymer emulsion comprises a colloidal dispersion of polyvinyl acetate particles stabilized in water by surfactant systems, typically manufactured through batch or semi-continuous emulsion polymerization at solids contents of 50-55% by weight. The chemistry serves primarily as a film-forming binder in water-based adhesives, architectural paints, and paper coatings where solvent elimination reduces workplace exposure and simplifies cleanup protocols. Adhesives applications dominate volume consumption due to established bonding performance on porous cellulosic substrates, while textile finishing represents the fastest-growing application dimension as apparel manufacturers eliminate solvent-based softeners from finishing lines. Paints and coatings segments retain mature growth profiles in developed markets though margin pools remain attractive in premium low-VOC architectural grades.
EPA regulations on architectural coating VOC content and REACH registration requirements for polymer imports into Europe shape product development priorities and market access conditions for emulsion suppliers. BIS certification mandates for construction chemicals in India and China's GB standards on indoor air quality create additional compliance layers that favor larger producers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving state-level restrictions on formaldehyde emissions from bonded wood products, as these cascade directly into adhesive specification changes that can either accelerate or constrain vinyl acetate homopolymer emulsion substitution patterns.
Market Dynamics
Water-based adhesive specifications are displacing solvent systems across construction and packaging end-uses, compressing reformulation cycles for emulsion suppliers while amplifying volume pull from VOC-compliant product lines.
Growth Catalysts
- REACH registration tiers:European polymer import requirements are filtering out smaller non-compliant suppliers, concentrating procurement among certified emulsion producers with dedicated regulatory affairs infrastructure.
- China's packaging export engine:Domestic carton sealing and paperboard lamination operations are absorbing expanded vinyl acetate homopolymer capacity as e-commerce fulfillment scales.
- Textile finishing chemistry:Apparel manufacturers are eliminating solvent-based softeners from dyeing lines, redirecting specification authority toward water-based polyvinyl acetate binders for fabric hand modification.
Market Restraints
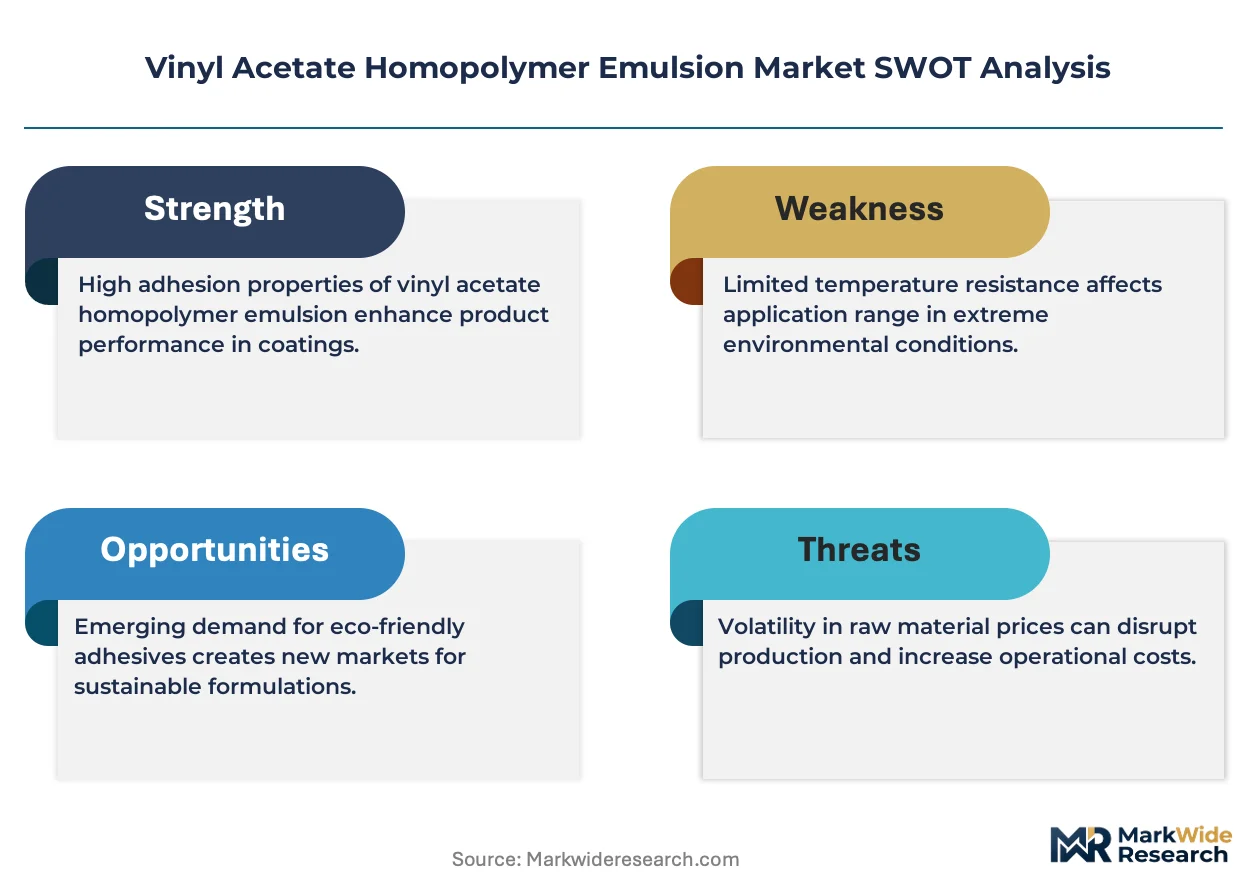
- Vinyl acetate monomer volatility:Feedstock price swings tied to ethylene and acetic acid supply imbalances compress margin predictability for non-integrated emulsion producers.
- Acrylic substitution in premium coatings:Performance-grade architectural applications are specification-shifting toward all-acrylic systems despite higher cost, constraining vinyl acetate homopolymer expansion in margin-rich segments.
- Formaldehyde emission limits:State-level bonded wood product restrictions in the US are cascading into adhesive requalification requirements that delay vinyl acetate homopolymer approval cycles.
Strategic Opportunities
- India's BIS certification gap:Construction chemical standardization is creating first-mover advantage windows for emulsion suppliers willing to absorb compliance timeline costs ahead of domestic competitors.
- Biomass-derived monomer pathways:Bio-based vinyl acetate pilot production is converging with brand owner carbon reduction commitments, opening premium positioning for verified low-carbon emulsion grades.
- Direct-to-miller distribution:Paper coating operations are consolidating procurement authority, enabling bypass of traditional chemical distributor markups for high-volume vinyl acetate homopolymer contracts.
Industry Challenges
- Emulsion polymerization expertise scarcity:Specialized process engineering talent for semi-continuous reactor operation is concentrating at established producers, constraining new entrant scale-up velocity.
- Multi-jurisdiction registration synchronization:REACH dossier maintenance, EPA pre-manufacture notifications, and China's MEE chemical inventory listings require parallel compliance investments that strain mid-cap regulatory budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Acetate Homopolymer Emulsion Market |
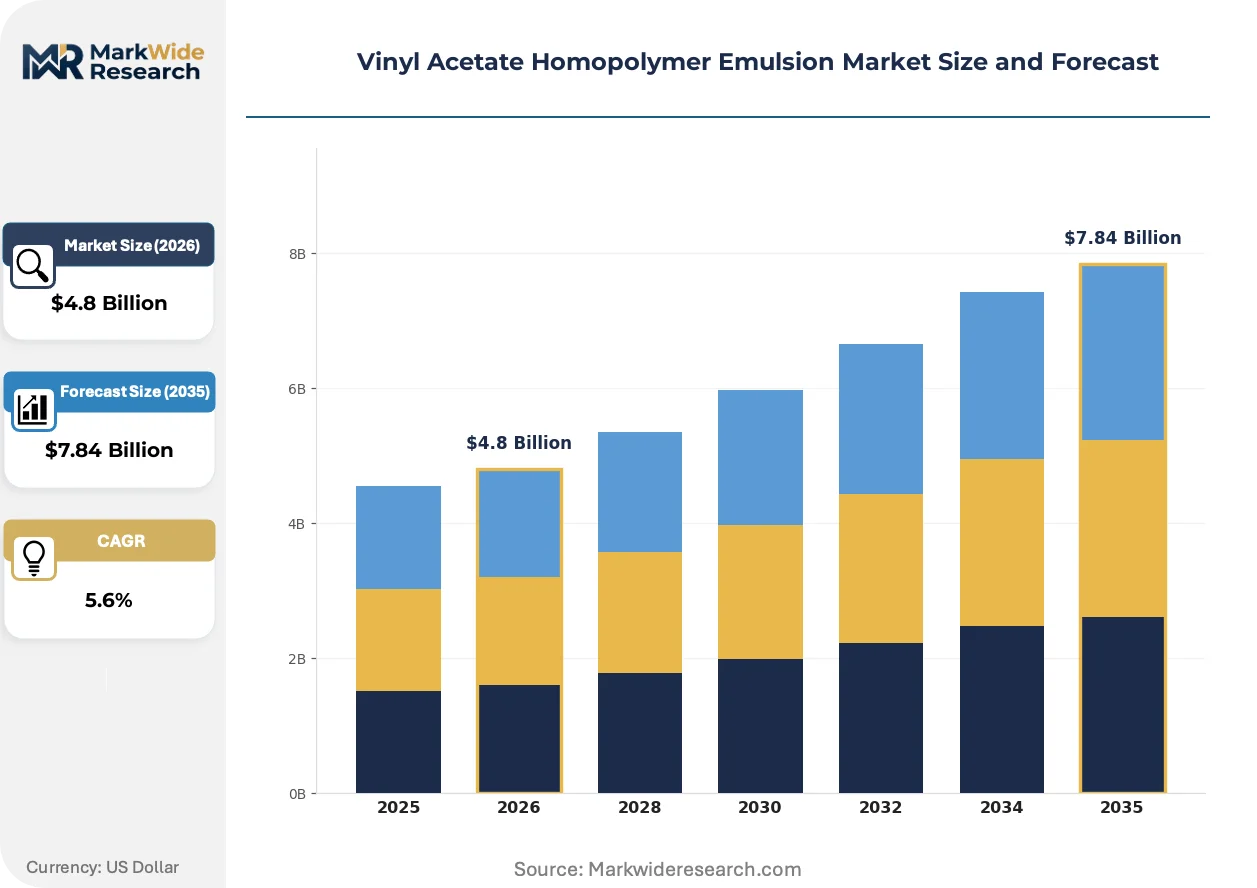
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Paints, Coatings, Inks End User: Construction, Automotive, Packaging, Textile Application: Surface Coating, Textile Finishing, Adhesive Bonding, Paper Coating Technology: Emulsion Polymerization, Suspension Polymerization, Solution Polymerization, Polymer Blending |
| Companies Covered | Arkema, Vinavil, Celanese Corporation, Kuraray, H.B. Fuller, Wacker Chemie AG, Henkel, Chang Chun Group, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Acetate Homopolymer Emulsion Market Strategic Shifts
Reformulation chemistry and polymerization process control are compressing product development cycles while regulatory compliance automation is reshaping supplier capability requirements across the value chain.
Core-shell emulsion architecture is consolidating performance positioning in high-shear adhesive applications. Flooring installers and furniture manufacturers are specifying these hybrid particles for improved creep resistance under sustained load. The technology is consolidating mid-tier producers into specialty positioning as standard homopolymer grades face specification pressure.
EPA architectural coating VOC limits are tightening enforcement granularity across state implementation plans. Industrial maintenance coating operations face reformulation mandates that accelerate water-based system qualification. California's South Coast Air Quality Management District is driving the most aggressive compliance timelines, forcing supplier technical service expansion.
Buyers are consolidating adhesive procurement through specified-performance contracts rather than resin-grade purchasing. Large construction contractors and packaging converters are shifting volume commitment structures toward bonded-assembly performance guarantees. This pattern is most visible in Germany's woodworking clusters where mill-direct relationships are displacing distributor intermediation.
Vinyl Acetate Homopolymer Emulsion Market Segmentation
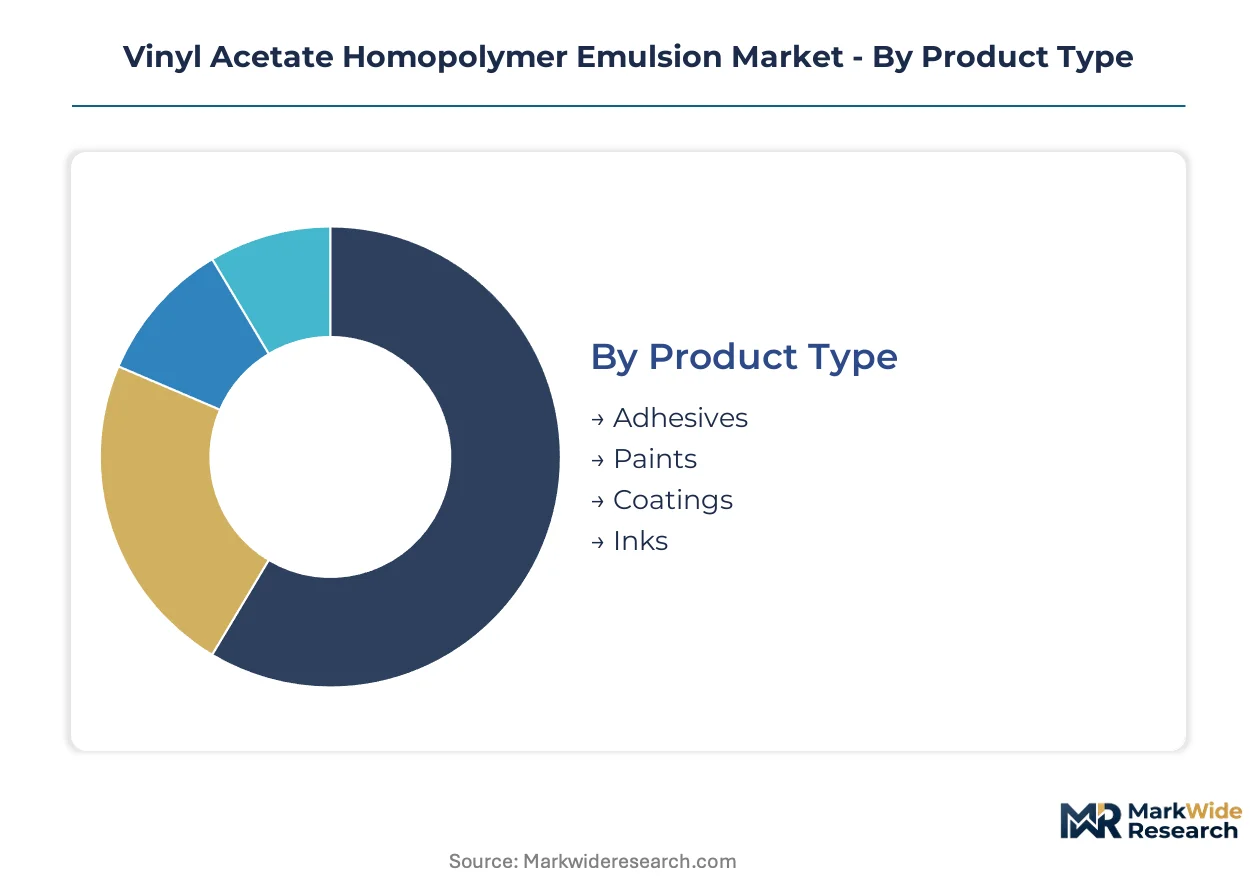
Segmentation in vinyl acetate homopolymer emulsion reveals how formulation chemistry and end-use performance requirements fragment procurement patterns across adhesive, coating, and textile applications. Understanding these divides exposes where specification authority concentrates and where margin pools shift between commodity and specialty grades.
Product Type:
Standardization dominates at the commodity end with limited formulation flexibility, while premium tiers demand customized solids content and viscosity profiles for specialized bonding or film-forming performance.
- Adhesives:Water-based bonding systems for porous cellulosic substrates, construction woodworking, and packaging carton sealing. Demand concentrates in China's infrastructure buildouts and Germany's furniture manufacturing clusters as builders eliminate solvent-based alternatives under tightening VOC limits.
- Paints:Architectural coating binders with established film-forming properties on interior and exterior substrates. Specification authority is shifting toward premium low-VOC grades in California's South Coast Air Quality Management District and across EU member states enforcing REACH-compliant import tiers.
- Coatings:Industrial maintenance and protective film applications requiring moisture resistance and substrate adhesion.
- Inks:Water-based printing formulations for paper and flexible packaging with controlled rheology and drying speed.
Most installed capacity flows through Adhesives. Expansion is steepest in Paints as regulatory pressure accelerates water-based system qualification.
End User:
Volume scale concentrates in mature construction applications, while margin pools favor automotive and textile segments where performance certification requirements filter out commodity suppliers.
- Construction:Woodworking adhesives, flooring installation, and structural bonding for residential and commercial buildouts. Celanese Corporation leverages backward integration into vinyl acetate monomer to sustain feedstock cost advantages across North American adhesive markets serving this segment.
- Textile:Fabric finishing, hand modification, and softener replacement in apparel manufacturing. Wacker Chemie AG anchors competitiveness through specialized emulsion polymerization technology for textile finishing applications in Central European manufacturing clusters.
- Packaging:Carton sealing, paperboard lamination, and flexible packaging adhesives driven by e-commerce fulfillment scaling.
- Automotive:Interior trim bonding, headliner assembly, and acoustic damping applications with stringent fogging and emission specifications.
Construction commands the largest volume commitment structures. Textile is climbing the fastest as apparel manufacturers eliminate solvent-based softeners from dyeing lines.
Application:
Process integration depth varies sharply—surface coating and paper coating favor high-volume mill-direct procurement, while adhesive bonding and textile finishing retain distributor intermediation for technical service support.
- Adhesive Bonding:Wood product assembly, furniture construction, and packaging closure systems. Core-shell emulsion architecture is consolidating performance positioning in high-shear applications where flooring installers specify hybrid particles for improved creep resistance under sustained load.
- Textile Finishing:Fabric hand modification, softening, and functional coating of woven and nonwoven materials. This application dimension is expanding most quickly as water-based polyvinyl acetate binders replace solvent-based softeners in dyeing lines across Bangladesh and Vietnam apparel manufacturing.
- Surface Coating:Protective and decorative films on wood, metal, and mineral substrates with defined gloss and durability specifications.
- Paper Coating:Printability enhancement, barrier properties, and structural reinforcement for packaging and label stock.
Adhesive Bonding carries the heaviest historical volume. Textile Finishing shows the steepest expansion trajectory as sustainability commitments redirect specification authority.
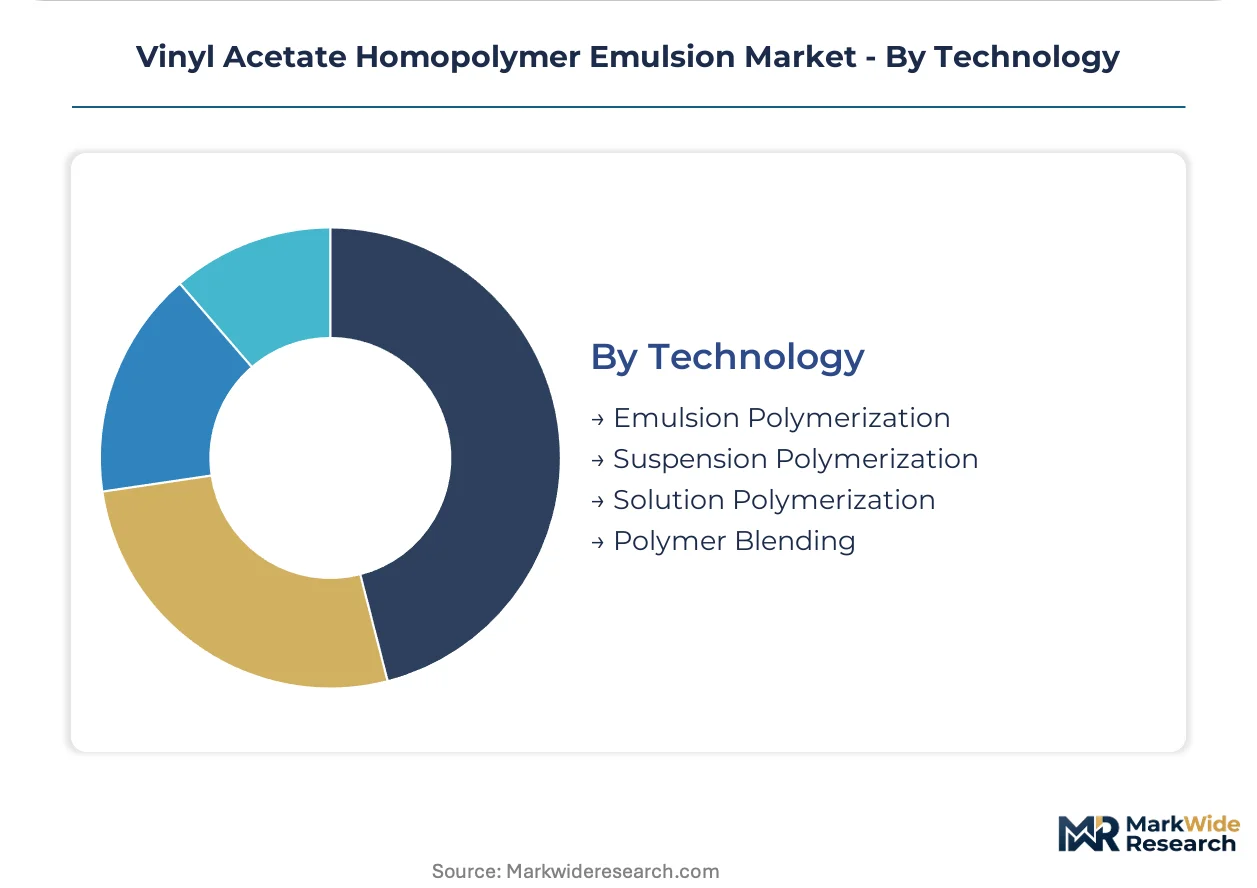
Technology:
Process control sophistication creates a capability moat—emulsion polymerization expertise concentrates at established producers while alternative technologies serve niche performance requirements.
- Emulsion Polymerization:Batch or semi-continuous aqueous dispersion at 50-55% solids content, stabilized by surfactant systems. Specialized process engineering talent for semi-continuous reactor operation is concentrating at established producers, constraining new entrant scale-up velocity in this dominant technology pathway.
- Suspension Polymerization:Bead-form polymerization in aqueous medium yielding discrete particle morphologies for specific adhesive rheology requirements.
- Solution Polymerization:Organic solvent-based synthesis for specialty grades where molecular weight control exceeds aqueous system capabilities.
- Polymer Blending:Physical combination of vinyl acetate homopolymer with acrylic, ethylene-vinyl acetate, or other resin systems to bridge performance gaps.
Emulsion Polymerization hosts the bulk of installed reactor capacity. Polymer Blending is gaining share fastest as formulators seek cost-performance positioning between standard homopolymer and all-acrylic systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta manufacturing corridor absorbs the largest volume of vinyl acetate homopolymer emulsion as packaging exporters and construction chemical formulators scale water-based system adoption.
China
E-commerce fulfillment infrastructure and carton sealing operations drive emulsion consumption in Jiangsu and Zhejiang provinces. GB standards on indoor air quality tighten adhesive specifications for bonded wood products. Ningbo's chemical industrial park hosts expanded domestic emulsion capacity serving export-oriented packaging manufacturers.
United States
Construction woodworking and flooring installation applications dominate volume demand across the Southeast and Midwest. EPA regulations on architectural coating VOC content accelerate reformulation toward compliant water-based systems. Texas Gulf Coast petrochemical corridors supply vinyl acetate monomer feedstock to integrated adhesive producers.
Germany
Furniture manufacturing clusters in North Rhine-Westphalia specify water-based adhesives under REACH-registered import tiers. ECHA dossier maintenance requirements filter procurement toward certified emulsion suppliers with dedicated regulatory infrastructure. Bavaria's woodworking machinery sector drives technical service intensity for high-shear adhesive applications.
India
Residential construction buildouts and packaging sector expansion absorb emulsion volumes in Maharashtra and Gujarat. BIS certification mandates for construction chemicals create compliance barriers favoring early-entrant suppliers with dedicated regulatory affairs capabilities. Mumbai-Pune industrial corridor concentrates adhesive formulator procurement authority.
Japan
Automotive interior trim and acoustic damping applications specify low-emission vinyl acetate homopolymer grades. METI chemical inventory listings and JIS standards govern emulsion import and domestic production qualification. Osaka-Kobe manufacturing belt concentrates textile finishing operations transitioning from solvent-based softeners.
Vinyl Acetate Homopolymer Emulsion Market Competitive Environment
Global majors compete with regional champions across feedstock integration and specialized emulsion polymerization capabilities. The supplier base organizes into three tiers: integrated petrochemical producers with captive vinyl acetate monomer supply, specialized emulsion polymerization technology holders, and regional formulators serving construction adhesive markets. Consolidation pressure concentrates among mid-cap producers facing multi-jurisdiction registration synchronization costs. Dominant competitive moves include backward integration into monomer production and geographic expansion through distributor acquisition in high-growth packaging markets.
Within the integrated petrochemical tier, Celanese Corporation and Dow occupy positions anchored by North American ethylene-based feedstock access. Wacker Chemie AG exemplifies specialized emulsion polymerization technology holders competing through proprietary reactor control systems. Arkema and Kuraray represent diversified chemical producers with regional formulation networks spanning European and Asian adhesive markets.
| Leading Market Players |
|---|
| Arkema |
| Vinavil |
| Celanese Corporation |
| Kuraray |
| H.B. Fuller |
| Wacker Chemie AG |
| Henkel |
| Chang Chun Group |
| Dow |
| Others |
Value Chain & Pricing Dynamics
Core-shell emulsion polymerization technology adoption is compressing cost economics for mid-tier producers while simultaneously concentrating supply among established players with proprietary reactor control systems. This production-method transition rewards backward integration into vinyl acetate monomer and penalizes non-integrated formulators exposed to ethylene and acetic acid feedstock volatility.
Pricing Analysis
Input-cost pass-through from vinyl acetate monomer fluctuations dominates pricing dynamics, with integrated producers capturing margin stability that non-integrated competitors forfeit during ethylene supply crunches. Three-tier pricing structure across premium low-VOC certified grades, standard construction adhesives, and economy packaging tiers reflects certification burden and volume scale differentiation. Cost compression in standard grades is intensifying because Chinese capacity expansion absorbs regional demand growth. Small packaging converters exhibit highest price sensitivity, while automotive interior trim buyers prioritize emission certification over unit economics.
Supply Chain Analysis
Freight cost escalation on bulk liquid emulsion shipments from China's Yangtze River Delta to Southeast Asian packaging hubs is redirecting procurement toward regional blending operations. Manufacturing concentrates in China, Germany, and the United States, with each node serving distinct regulatory compliance zones. Feedstock supply draws from Texas Gulf Coast petrochemical corridors, European naphtha crackers, and Chinese coal-to-chemical complexes. Single-source vulnerability concentrates in vinyl acetate monomer supply from integrated petrochemical majors. Distribution runs through mill-direct contracts for high-volume paper coating buyers and distributor networks for construction adhesive formulators requiring technical service support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH registration tiers and EPA VOC enforcement accelerate demand concentration among certified suppliers. The EU Green Deal's chemical sustainability requirements represent the pivotal regulatory milestone reshaping procurement authority.
For Market Incumbents: To counter acrylic substitution in premium architectural coatings, Celanese Corporation and Wacker Chemie AG should deepen backward integration into bio-based vinyl acetate pilot production and expand technical service presence in California's South Coast Air Quality Management District. Certification investment in India's BIS construction chemical standards creates defensive moats against domestic formulator competition. For New Entrants and Emerging Players: Regional packaging converters in Vietnam and Bangladesh present underserved buyer archetypes seeking water-based adhesive alternatives to solvent systems. Textile finishing operations eliminating solvent-based softeners offer the most penetrable application dimension. A go-to-market angle anchored by direct-to-miller distribution partnerships bypasses entrenched chemical distributor markups. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap European emulsion specialists burdened by REACH dossier maintenance costs and lacking Asian production footprints. Long-term viability across the analysis window hinges on regulatory compliance automation capabilities and biomass-derived monomer pathway development. The signal to watch is state-level formaldehyde emission restriction cascades into bonded wood product adhesive requalification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VAM | Celanese Corporation's captive ethylene feedstock access insulates margin stability against acetic acid price swings. |
| Green Manufacturing Transition | Bio-based vinyl acetate pilot production aligns with brand owner carbon reduction commitments in European packaging. |
| Long-term Supply Agreement | Mill-direct contracts with Ningbo packaging exporters compress distributor markups and lock volume commitments. |
| Joint Venture | Technology licensing partnerships in India's Mumbai-Pune corridor accelerate BIS certification timeline absorption. |
| Capacity Expansion | Semi-continuous reactor additions in Jiangsu province serve e-commerce fulfillment infrastructure scaling. |
Study Parameters
Coverage spans China, the United States, Germany, India, and Japan, with primary inputs from each market informing demand segmentation and competitive positioning assessments. Primary interviews with emulsion plant managers, procurement leads at downstream packaging converters, distribution channel partners, and technical R&D directors combined with secondary validation from customs trade data, Cefic chemical industry reports, SEC 10-K filings, and EPA regulatory filings. Bottom-up and top-down triangulation reconciles production capacity estimates with end-use consumption patterns across adhesive, coating, and textile applications.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry concentration, regional production hub, and regulatory compliance cluster. CAGRs were derived from historical trajectory analysis adjusted for policy inflection points and technology substitution elasticities. Forecast inputs incorporate vinyl acetate monomer feedstock cost assumptions and REACH registration tier compliance cost burdens.
Underlying measurement precision varies by segment; adhesives and construction end-use carry tighter precision than emerging textile finishing applications. Forecasts reflect assumptions on regulatory enforcement granularity and biomass monomer commercialization timelines. A model refresh is warranted upon material change in EPA state implementation plan VOC limit stringency or EU ECHA polymer import requirement enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Melamine Formaldehyde Resin Powder Market
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
Water-Borne Resins Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
India Polyacrylamide Copolymer Market
Polymers & Resins
Indonesia Flooring Resins Market
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Styrenics Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
Silane-Modified Polymers Market
Polymers & Resins
Asia-Pacific Fluoropolymer Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Global Ultra-High Molecular Weight Polyethylene Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market