
 Polymer Gel Market | 2026-2036
Polymer Gel Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Gel Market Analysis
Software-defined formulation services is consolidating around polymer gel platforms as vendors bundle predictive modeling with raw material supply. BASF SE leverages its specialty chemicals portfolio to anchor hydrogel innovation for medical-grade applications. Evonik Industries AG differentiates through high-purity silicone gel technologies targeting implantable device makers. Dow Inc competes on manufacturing scale across aqueous gel segments for industrial absorbents.
Polymer gel denotes a cross-linked polymer network swollen with a liquid phase, typically exhibiting elastic solid behavior with water or organic solvent contents exceeding 90 percent by weight, and serves primarily as a functional matrix for controlled release, moisture management, or mechanical cushioning in industrial and biomedical systems. Hydrogel formulations occupy the largest value pool due to established use in wound dressings and drug delivery matrices, while organogel variants represent the fastest-expanding category as cosmetic manufacturers seek lipophilic active carriers. Tissue engineering applications sustain premium pricing through stringent biocompatibility requirements and small-batch customization protocols.
FDA biocompatibility standards under ISO 10993 govern material qualification for implantable polymer gels in the United States, while REACH and the EU Medical Device Regulation shape chemical disclosure and clinical evidence requirements across European markets. Japan's PMDA enforces comparable premarket approval pathways for gel-based medical devices, creating parallel compliance burdens for multinational suppliers. Stakeholders must monitor evolving biocompatibility testing protocols and regional registration timelines to secure market access without qualification delays.
Market Dynamics
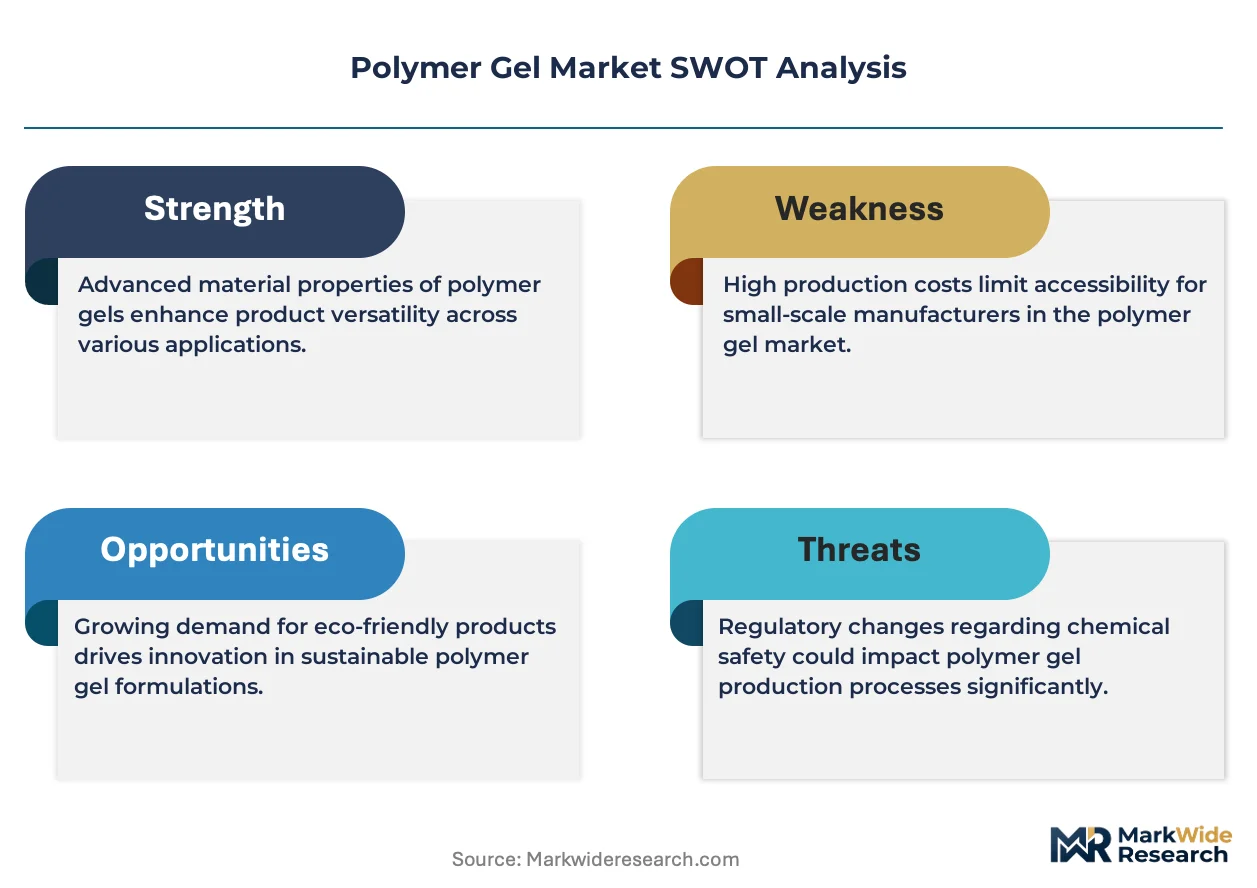
REACH compliance and FDA biocompatibility standards are tightening material qualification timelines, forcing manufacturers to consolidate formulation capabilities and accelerate predictive modeling investments to maintain access to premium medical device contracts.
Growth Catalysts
- ISO 10993 Testing Protocols:FDA biocompatibility requirements for implantable gels are driving demand for high-purity silicone formulations in wound care and drug delivery matrices.
- Chronic Wound Prevalence:Aging demographics in Germany and Japan are expanding hydrogel consumption for advanced dressing applications in hospital and homecare settings.
- Organogel Lipophilic Carriers:Cosmetic manufacturers are adopting solvent-swollen polymer networks for active ingredient encapsulation in premium skincare formulations.
Market Restraints
- Specialty Monomer Volatility:Acrylamide and silicone precursor costs fluctuate with petrochemical feedstock pricing, compressing margins for aqueous gel producers.
- Regional Supply Concentration:High-purity medical-grade gel production clusters in the United States and Germany, creating qualification bottlenecks for Asian device makers.
- Biodegradability Trade-offs:Synthetic cross-linking agents in durable hydrogels face scrutiny under EU Green Deal circular economy targets.
Strategic Opportunities
- India CDSCO Pathways:Streamlined medical device registration is opening access to domestic manufacturing for export-oriented gel suppliers.
- 3D Bioprinting Convergence:Bio-ink formulations combining cell-laden hydrogels with structural polymers are creating tissue engineering white space.
- PLI Scheme Incentives:India's production-linked incentive framework supports local specialty chemical capacity for medical gel precursors.
Industry Challenges
- Cross-Functional Talent Scarcity:Formulation chemists with dual expertise in polymer science and regulatory affairs command premium compensation and extended search timelines.
- ISO 13485 Certification Burden:Medical device quality management system audits require 12-18 month implementation cycles for new gel manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Gel Market |
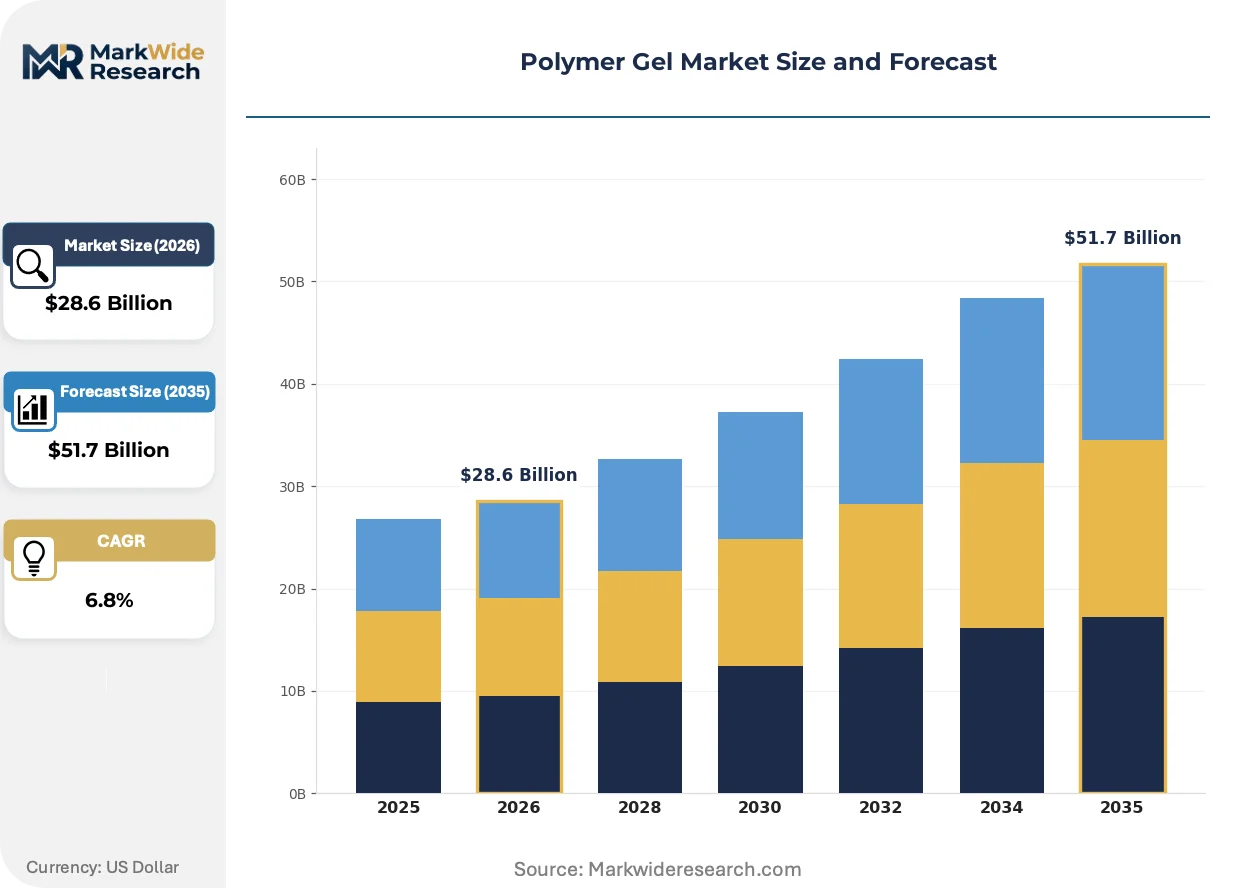
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Gel, Hydrogel, Organogel, Xerogel Application: Medical Devices, Cosmetic Products, Drug Delivery, Tissue Engineering End User: Pharmaceuticals, Healthcare Providers, Research Laboratories, Cosmetics Manufacturers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Ashland LLC, Sanyo Chemical Industries Ltd., BASF SE, Evonik Industries AG, Nippon Shokubai Co. Ltd, LG Chem Ltd., 3M Company, Synthomer PLC, Dow Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Gel Market Emerging Trajectories
Software-defined formulation platforms are collapsing traditional R&D timelines, enabling real-time property prediction that reshapes how polymer gel developers prototype and qualify new compositions for regulated applications.
Stimuli-responsive hydrogels with tunable swelling kinetics are overtaking passive moisture-management formulations in advanced wound care. Hospital procurement teams in the United States are prioritizing gels with pH-sensitive release profiles for chronic ulcer treatment. This capability compression is eliminating commodity dressing suppliers from tier-one contract bidding.
EU Medical Device Regulation clinical evidence requirements are extending premarket approval timelines for implantable gel products. European notified bodies now demand lifetime biocompatibility data that exceeds previous MEDDEV guidelines. Manufacturers are responding by front-loading toxicology studies and establishing dedicated MDR transition teams.
Device makers are consolidating supplier relationships around full-service formulation partners who bundle raw material supply with regulatory documentation. This preference compression disadvantages pure-play chemical distributors in Japan and Germany. Procurement teams now evaluate total qualification cost rather than unit chemistry pricing.
Polymer Gel Market Segmentation
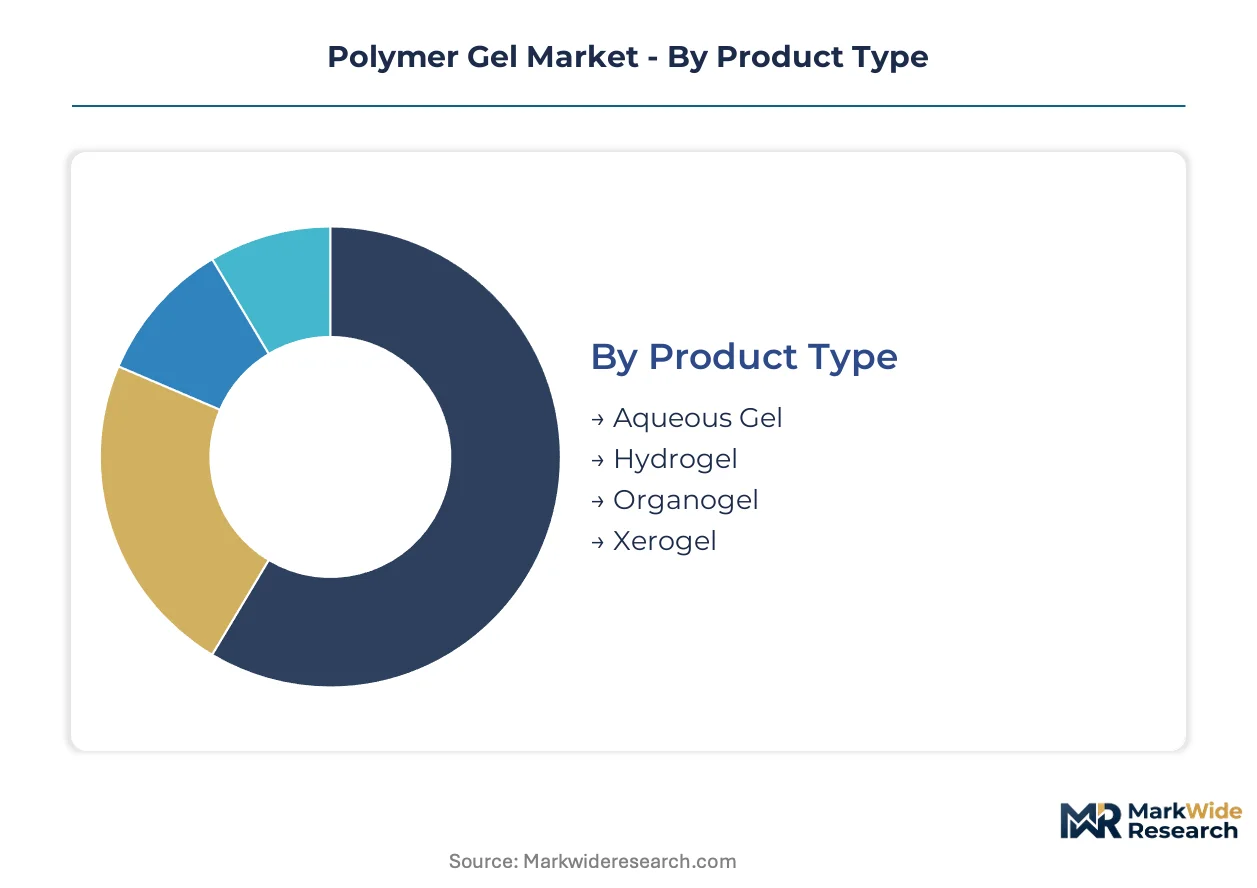
Polymer gel suppliers face divergent capital requirements across formulation categories. Product complexity drives facility investment, while application mix determines regulatory compliance spend and customer qualification timelines.
Product Type:
Hydrogel manufacturing demands the heaviest upfront capital for medical-grade purification systems and cleanroom infrastructure. Organogel production requires specialized solvent handling and recovery equipment.
- Hydrogel:Water-swollen polymer networks with cross-linked hydrophilic chains dominate wound care and drug delivery matrices. FDA biocompatibility protocols under ISO 10993 concentrate demand in United States hospital procurement channels for chronic ulcer management.
- Organogel:Lipophilic solvent-swollen networks serve as active ingredient carriers in premium cosmetic formulations. Japanese and German cosmetics manufacturers drive specification tightening for thermal stability and controlled release kinetics.
- Aqueous Gel:Industrial absorbents and moisture-management applications utilize lower-purity formulations with reduced cross-linking density.
- Xerogel:Dried gel matrices with high porosity function as insulation materials and controlled-release substrates requiring specialized drying equipment.
Most installed capacity flows through Hydrogel. Expansion is steepest in Organogel.
Application:
Medical device integration commands premium pricing through extended qualification cycles. Tissue engineering applications sustain the highest margin profiles due to small-batch customization protocols.
- Medical Devices:Implantable gels for cushioning, sealing, and drug elution require ISO 13485-certified manufacturing and lifetime biocompatibility documentation. REACH compliance and EU MDR clinical evidence rules extend European approval timelines beyond comparable United States pathways.
- Tissue Engineering:Cell-laden hydrogel scaffolds and bio-ink formulations command pricing premiums through stringent sterility requirements and batch-to-batch consistency protocols. Research laboratories in Germany and Japan anchor early-stage demand for 3D bioprinting convergence.
- Drug Delivery:Controlled-release matrices for transdermal and implantable administration.
- Cosmetic Products:Moisture retention and active encapsulation for skincare formulations.
Revenue concentration sits with Medical Devices. Tissue Engineering climbs the fastest.
End User:
Pharmaceutical companies impose the most demanding supplier qualification standards. Cosmetics manufacturers prioritize formulation flexibility and rapid scale-up capabilities.
- Healthcare Providers:Hospital systems and wound care clinics procure hydrogel dressings through group purchasing organizations. United States acute care facilities are consolidating supplier relationships around full-service partners who bundle predictive modeling with raw material supply.
- Pharmaceuticals:Drug manufacturers require extensive toxicology dossiers and stability data for excipient and active carrier applications. Japan's PMDA enforces premarket approval pathways comparable to FDA standards, creating parallel compliance burdens.
- Cosmetics Manufacturers:Premium skincare brands specifying organogel carriers for lipophilic actives.
- Research Laboratories:Academic and commercial R&D facilities prototyping tissue engineering scaffolds.
Contract volume concentrates with Healthcare Providers. Procurement growth is strongest in Pharmaceuticals.
Distribution Channel:
Direct sales relationships capture the highest-value medical device contracts. Distributor networks dominate industrial and cosmetic segments where technical support requirements are lower.
- Direct Sales:Dedicated account teams manage multi-year supply agreements with implantable device makers and pharmaceutical manufacturers. BASF SE and Evonik Industries AG anchor this channel through bundled formulation services and regulatory documentation packages.
- Distributors:Regional chemical distributors serve cosmetics manufacturers and research laboratories with standardized aqueous gel grades. German and Japanese distribution networks concentrate medical-grade inventory near device manufacturing clusters.
- Online Retail:E-commerce platforms for standardized industrial gel formulations and small-volume research quantities.
- Wholesalers:Bulk procurement intermediaries for commodity absorbent applications.
Value capture concentrates in Direct Sales. Channel expansion runs fastest through Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates medical-grade gel production capacity while the United States dominates hospital procurement volume for advanced wound care applications. Japan maintains stringent premarket approval pathways that filter supplier entry. India is emerging as a manufacturing alternative through streamlined regulatory frameworks.
United States
Hospital systems in the United States procure hydrogel dressings through consolidated group purchasing organizations that favor full-service formulation partners. FDA biocompatibility standards under ISO 10993 govern implantable gel qualification, extending material validation timelines. Medical device clusters in Minneapolis and Boston anchor demand for high-purity silicone formulations.
Germany
German wound care manufacturers specify organogel carriers with thermal stability requirements for premium cosmetic and medical applications. REACH compliance and EU Medical Device Regulation clinical evidence rules extend premarket approval timelines beyond comparable pathways. Industrial concentration in North Rhine-Westphalia supports specialty chemical precursor production for export-oriented gel suppliers.
Japan
Japanese cosmetics manufacturers drive specification tightening for controlled-release kinetics in lipophilic active carrier applications. PMDA enforces premarket approval pathways comparable to FDA standards for gel-based medical devices. Research laboratories in the Kanto region anchor early-stage demand for 3D bioprinting convergence with cell-laden hydrogel scaffolds.
India
Domestic pharmaceutical manufacturers are expanding excipient sourcing from local gel suppliers to reduce import dependency. CDSCO streamlined medical device registration pathways and PLI scheme incentives support specialty chemical capacity buildout. Manufacturing clusters in Gujarat and Maharashtra are capturing export-oriented production for aqueous gel segments.
United Kingdom
United Kingdom research institutions prototype tissue engineering scaffolds with stringent batch-to-batch consistency protocols. MHRA alignment with EU MDR requirements maintains parallel compliance burdens for multinational suppliers. London-based procurement teams evaluate total qualification cost rather than unit chemistry pricing for implantable device contracts.
Polymer Gel Market Vendor Landscape
Top-tier vendors anchor medical-grade formulation services, while mid-scale specialists occupy industrial absorbent and cosmetic carrier segments. The vendor base stratifies across three capability tiers: integrated chemical conglomerates with regulatory documentation bundles, regional purification specialists with ISO 13485 certification, and commodity distributors serving standardized aqueous grades. Dominant competitive moves include backward integration into specialty monomer supply and predictive modeling partnerships with device makers.
Within the integrated chemical tier, BASF SE and Evonik Industries AG occupy positions exemplifying bundled formulation services with raw material supply. Sanyo Chemical Industries Ltd. represents the Asia-Pacific specialist archetype. These three companies illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic actions or market shares.
| Leading Market Players |
|---|
| Ashland LLC |
| Sanyo Chemical Industries Ltd. |
| BASF SE |
| Evonik Industries AG |
| Nippon Shokubai Co. Ltd |
| LG Chem Ltd. |
| 3M Company |
| Synthomer PLC |
| Dow Inc |
| Others |
Supply Flow & Price Mechanics
Formulation chemists with dual expertise in polymer science and regulatory affairs cluster in Germany and the United States, where their scarcity widens spreads between premium medical-grade gels and commodity aqueous formulations. Labor-cost differentials between these specialized talent pools and emerging manufacturing hubs in India compress margins at the standard tier while reinforcing pricing power at the certification-intensive premium level.
Pricing Analysis
Capacity additions in India are reshaping price floors for industrial-grade hydrogel absorbents while medical-grade silicone formulations in Germany and the United States maintain structural premiums. Contract-based long-term offtake dominates hospital procurement, with price differentiation anchored in ISO 13485 certification tier and FDA biocompatibility documentation depth. Cost compression in aqueous gel segments intensifies because petrochemical feedstock volatility transmits directly to acrylamide precursor costs. Cosmetics manufacturers exhibit highest price sensitivity, implantable device makers least.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical and medical device demand, while distributor networks serve research laboratories and cosmetics manufacturers with standardized grades. Production concentrates in the United States, Germany, and Japan for high-purity medical formulations, with India expanding capacity for export-oriented aqueous segments. Supply chains draw from silicone precursors, acrylamide monomers, and cross-linking agents, with single-source vulnerability concentrated in specialty monomer purification. Distribution runs through regional chemical distributors with medical-grade inventory positioned near device manufacturing clusters in Minneapolis, Boston, and North Rhine-Westphalia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where chronic wound prevalence and implantable device demand shift procurement toward premium specifications with stringent biocompatibility documentation.
For Market Incumbents: Acquire predictive modeling capabilities and regulatory affairs talent pools to consolidate full-service formulation positioning. BASF SE and Evonik Industries AG anchor this strategy through bundled raw material supply with ISO 10993 documentation packages. Backward integration into specialty monomer supply defends margin position against petrochemical feedstock volatility. Capacity expansion in India captures PLI scheme incentives while serving export-oriented device makers.
For New Entrants and Emerging Players: Launch via India's CDSCO streamlined registration pathways targeting domestic pharmaceutical excipient demand. Tissue engineering applications in German and Japanese research laboratories represent the most penetrable white space, with small-batch customization protocols favoring agile entrants over scaled incumbents. Position around 3D bioprinting convergence with cell-laden hydrogel bio-inks, leveraging software-defined formulation partnerships to collapse R&D timelines.
For Investors and Strategic Acquirers: Medical device manufacturers are the most active acquirer in this space, seeking captive gel formulation capabilities to secure supply continuity and accelerate MDR transition timelines. Over a five-to-ten year horizon, the market rewards vertically integrated specialists with ISO 13485 certification and established FDA master files. Monitor EU Medical Device Regulation notified body capacity as the critical inflection signal—approval timeline extensions will compress valuations for qualification-lagged suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Monomers | Captive acrylamide and silicone precursor supply insulates margins from petrochemical volatility. |
| Software-Defined Formulation Platform Launch | Predictive modeling partnerships with device makers collapse prototype-to-qualification timelines. |
| ISO 13485 Certification Investment | Hospital procurement committees filter supplier pools through quality management system audits. |
| India Manufacturing Footprint Expansion | PLI scheme incentives and CDSCO pathways support export-oriented capacity for aqueous gel segments. |
| EU MDR Transition Team Establishment | Dedicated clinical evidence capabilities secure premarket approval for implantable gel products. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each market's stakeholder ecosystem. The research combines structured interviews with formulation chemists, regulatory affairs directors, hospital procurement managers, and biomedical engineers with secondary validation from FDA 510(k) filings, EMA MDR submission databases, CDSCO registration records, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up demand modeling triangulates against top-down production capacity assessments across the analysis window.
Segmentation granularity operates at product type, application, end user, and distribution channel levels, with additional modeling of certification tier and geographic regulatory cluster. CAGRs derive from trend extrapolation of historical volume and value data, cross-referenced with capacity expansion announcements and raw material cost trajectories. Forecast inputs incorporate REACH compliance timeline evolution, FDA biocompatibility testing protocol updates, and PMDA premarket approval pathway modifications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated EU Green Deal circular economy enforcement or sustained petrochemical feedstock price volatility. Projections reflect assumptions regarding regulatory timeline stability, specialty monomer supply continuity, and hospital procurement consolidation patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
Renewable Polyethylene Market
Polymers & Resins
Hydrocarbon Resins Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Styrenic Block Copolymer (SBC) Market
Polymers & Resins
Polymer Ingredients Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
Europe Polyurethane Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Africa Polyamide Market
Polymers & Resins
Global Polycarbonate Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
India Flooring Resins Market
Polymers & Resins
EVA Foam Market