
 Polymeric Sand Market | 2026-2036
Polymeric Sand Market Size, Share, and Industry Trends Forecast 2026-2036
Polymeric Sand Market Intelligence
The EU Green Deal is expanding the addressable market for low-emission jointing materials across European hardscape projects. Techniseal leverages its specialized R&D pipeline to sustain certification leadership in volatile organic compound compliance. SRW Products anchors North American distribution through extensive contractor channel control. Alliance Designer Products Inc. differentiates via product specialization in color-matched formulations for premium residential segments.
Polymeric sand consists of fine silica aggregate combined with water-activated polymer binders, typically polyurethane or epoxy resins, that cure to form flexible, weed-resistant joints between paving units. The material functions primarily to stabilize interlocking pavers, prevent erosion, and maintain permeability in exterior hardscape surfaces. Silica-based formulations dominate volume due to established supply chains and cost efficiency, while polyurethane grades capture premium margin pools through superior freeze-thaw performance. Residential developers represent the fastest-growing end use industry as new construction integrates outdoor living spaces with permeable drainage requirements.
EPA regulations on construction site runoff and REACH restrictions on hazardous resin additives jointly shape product formulation standards and market access conditions for imported binders. The EU F-Gas Regulation indirectly influences polymer curing agent availability, while ISO 9001 quality certification serves as a baseline procurement filter for municipal hardscape tenders. Stakeholders must monitor evolving state-level permeable surface mandates and resin feedstock price volatility to time capacity investments and formulation shifts effectively.
Market Dynamics
The EU Green Deal's material sustainability mandates are compressing formulation timelines across European hardscape supply chains, forcing resin suppliers to certify lower-VOC alternatives before tender deadlines.
Growth Catalysts
- REACH restrictions on hazardous resin additives:German municipal tenders now specify certified jointing compounds, creating procurement pull for compliant formulations.
- Permeable hardscape mandates:Landscaping contractors in residential construction integrate polymeric sand to meet drainage requirements for outdoor living installations.
- Freeze-thaw performance standards:Polyurethane grades capture specification in cold-climate infrastructure where silica formulations fail durability testing.
Market Restraints
- Resin feedstock volatility:Polyurethane binder costs fluctuate with petrochemical supply chain disruptions, compressing margin stability for formulators.
- Silica supply concentration:Fine aggregate mining clusters in specific regional deposits create geographic vulnerability to logistics bottlenecks.
- Cement-based jointing substitution:Traditional mortar compounds retain cost advantage in price-sensitive municipal maintenance contracts.
Strategic Opportunities
- EU F-Gas Regulation compliance:Curing agent reformulation for reduced fluorinated gas content opens specification access to green infrastructure tenders.
- Color-matched residential segments:Premium paver aesthetics drive demand for specialized pigment integration in jointing compounds.
- Permeable surface mandates:State-level stormwater management regulations in the US expand addressable market for drainage-compliant installations.
Industry Challenges
- ISO 9001 certification timelines:Municipal procurement filters require quality system documentation that extends supplier onboarding cycles.
- Polymer-chemistry technical expertise:Formulation shifts toward bio-based binders strain R&D staffing pools at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymeric Sand Market |
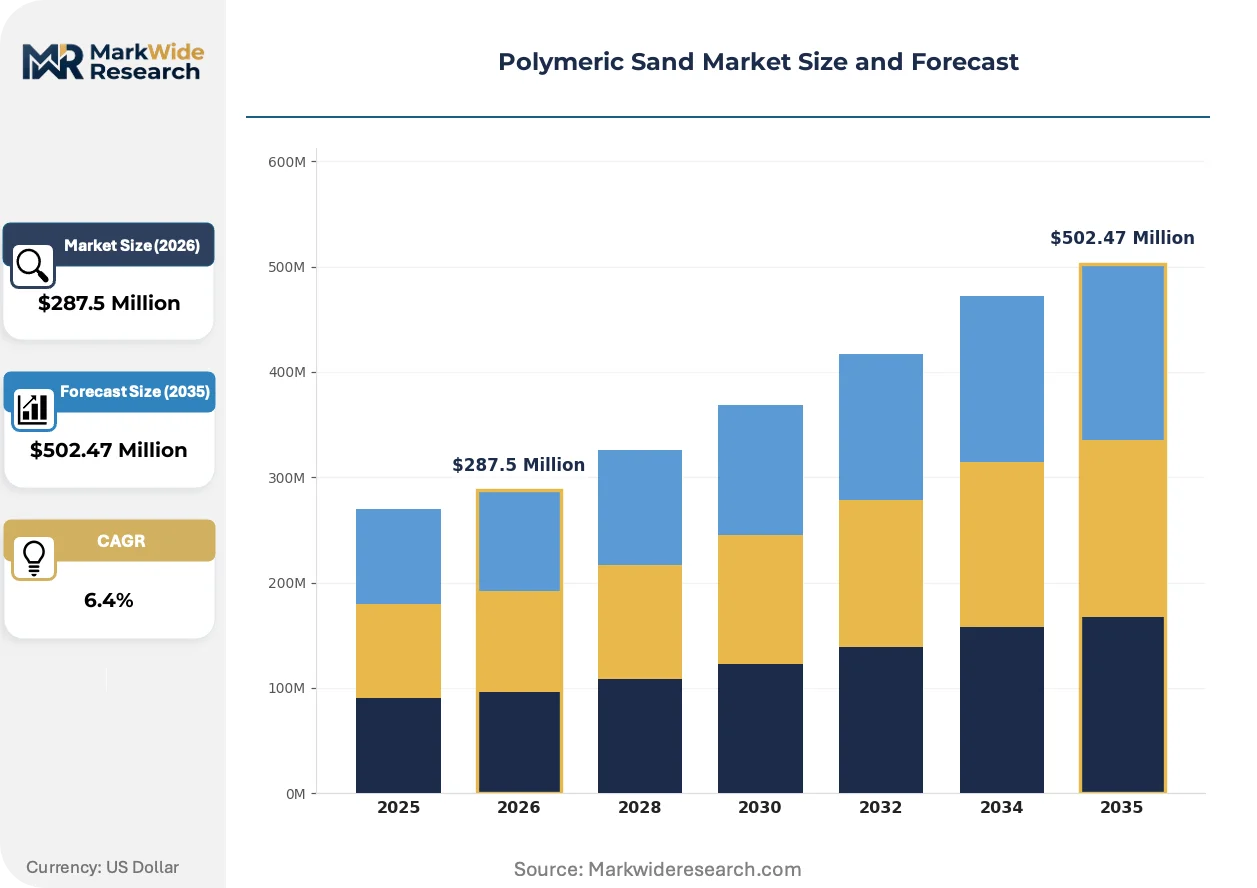
| Market Size in 2026 | $287.5 Million |
| Market Size in 2035 | $502.47 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica-Based, Resin-Coated, Cement-Based, Polyurethane, Epoxy, Acrylic Application: Driveways, Patios, Walkways, Pool Decks, Commercial Flooring, Garden Paths End Use Industry: Landscaping Contractors, Residential Developers, Commercial Builders, Municipal Authorities, Property Managers, Hardscape Specialists Packaging Type: 25 lb Bags, 50 lb Bags, Bulk Sacks, Sealed Containers, Buckets, Eco-Friendly Packaging |
| Companies Covered | SRW Products, Sable Marco, Techniseal, Unilock, Vimark Srl, Alliance Designer Products Inc., SEK Surebond, Quikrete, Sakrete, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymeric Sand Market Strategic Shifts & Innovations
Formulation chemistry and procurement specifications are diverging sharply as regulatory compliance becomes the primary selection filter over historical cost-performance tradeoffs.
Water-activated epoxy resin systems are rewriting durability benchmarks for high-traffic commercial hardscapes. Municipal infrastructure departments specify these grades for plaza and roadway installations requiring ten-year joint integrity guarantees. The technology is compressing replacement cycles and shifting maintenance budgets toward premium material procurement.
EPA construction site runoff regulations now mandate permeable surface coverage percentages for developments exceeding specific disturbance thresholds. Industrial consequence: developers must specify jointing materials that maintain drainage porosity under load. Residential subdivision builders in the mid-Atlantic states face the steepest compliance curves, accelerating adoption of certified permeable jointing systems.
Certification-driven preference shifts now dominate contractor material selection. Landscaping professionals prioritize pre-approved product lists over independent performance testing, streamlining specification around municipal compliance documentation. This behavior concentrates procurement volume through distributor channels holding inventory of pre-certified SKUs, particularly visible in German-speaking European markets where tender documentation requirements are most stringent.
Polymeric Sand Market Segmentation
Polymeric sand purchasing decisions pivot on performance specifications, installation scale, and regulatory compliance requirements. Contractors and developers evaluate formulations against freeze-thaw durability, permeability standards, and VOC certification thresholds. Understanding segment dynamics reveals where margin pools concentrate and which specifications drive tender wins.
Product Type:
Cost tier determines specification access for contractors bidding municipal versus residential projects.
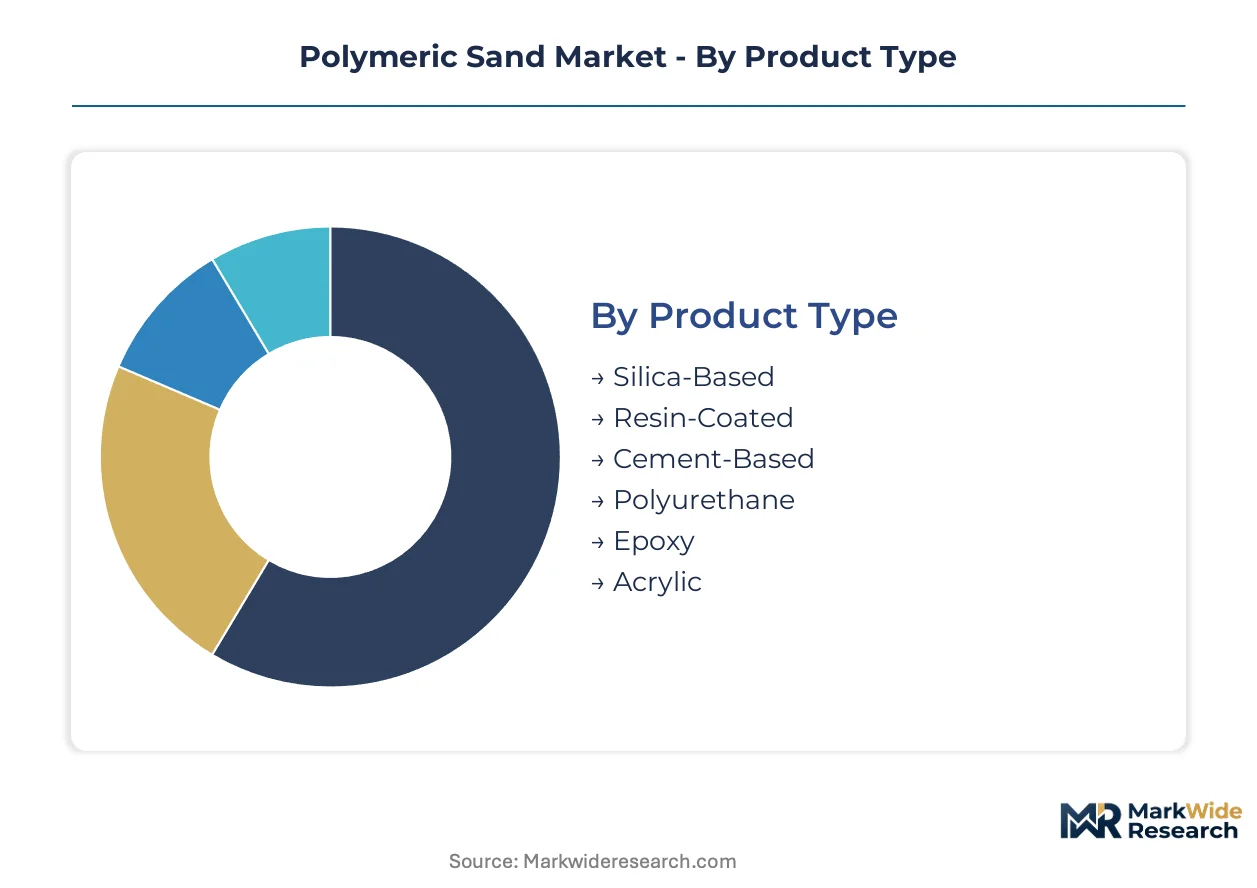
- Silica-Based:Fine quartz aggregate dominates volume through established mining operations and supply chain efficiency. German municipal green infrastructure standards specify certified silica grades for permeable paver installations requiring drainage compliance.
- Polyurethane:Superior elasticity under thermal cycling commands premium positioning in cold-climate infrastructure. Minnesota and Wisconsin departments of transportation specify polyurethane jointing for plaza installations facing freeze-thaw stress.
- Resin-Coated:Intermediate performance tier bridges cost-sensitive commercial segments.
- Cement-Based:Traditional mortar alternative retains specification in maintenance contracts prioritizing material cost over longevity.
- Epoxy:Water-activated systems capture high-traffic commercial specifications demanding decade-long joint integrity guarantees.
- Acrylic:Emerging bio-based binder chemistry targets EU Green Deal compliance pathways.
Silica-based formulations lead on scale; polyurethane leads on momentum.
Application:
Drainage mandates and load-bearing requirements split demand across residential and commercial hardscape typologies.
- Driveways:Vehicle load specifications demand high-compressive-strength jointing compounds. Virginia and Maryland residential developers integrate polymeric sand to meet EPA construction site runoff thresholds for permeable surface coverage.
- Patios:Aesthetic integration with outdoor living spaces drives color-matched formulation demand. Premium residential segments in Texas and Florida specify pigment-customized jointing for paver visual continuity.
- Walkways:Pedestrian traffic applications prioritize weed resistance and erosion control.
- Pool Decks:Chlorine exposure and drainage requirements favor specialized chemical-resistant binders.
- Commercial Flooring:High-traffic retail and hospitality installations specify epoxy systems for durability guarantees.
- Garden Paths:Low-load residential landscaping accepts economy-grade silica formulations.
Driveway installations lead on scale; patio applications lead on margin expansion.
End Use Industry:
Procurement authority and specification control determine channel access for formulators.
- Landscaping Contractors:Primary installation decision-makers influence material selection through distributor relationships. EPA construction site runoff regulations in the mid-Atlantic states accelerate contractor adoption of certified permeable jointing systems.
- Residential Developers:Outdoor living space integration drives fastest-expanding demand segment. New subdivision builders specify polymeric sand to meet state-level stormwater management mandates.
- Commercial Builders:Large-scale hardscape projects prioritize pre-approved product lists for compliance efficiency.
- Municipal Authorities:Tender documentation requirements in Germany and Austria concentrate procurement through ISO 9001-certified suppliers.
- Property Managers:Maintenance-driven replacement cycles favor cost-optimized formulations.
- Hardscape Specialists:Technical expertise enables specification of premium performance grades.
Landscaping contractors lead on volume concentration; residential developers lead on trajectory steepness.
Packaging Type:
Project scale and logistics infrastructure shape procurement format preferences.
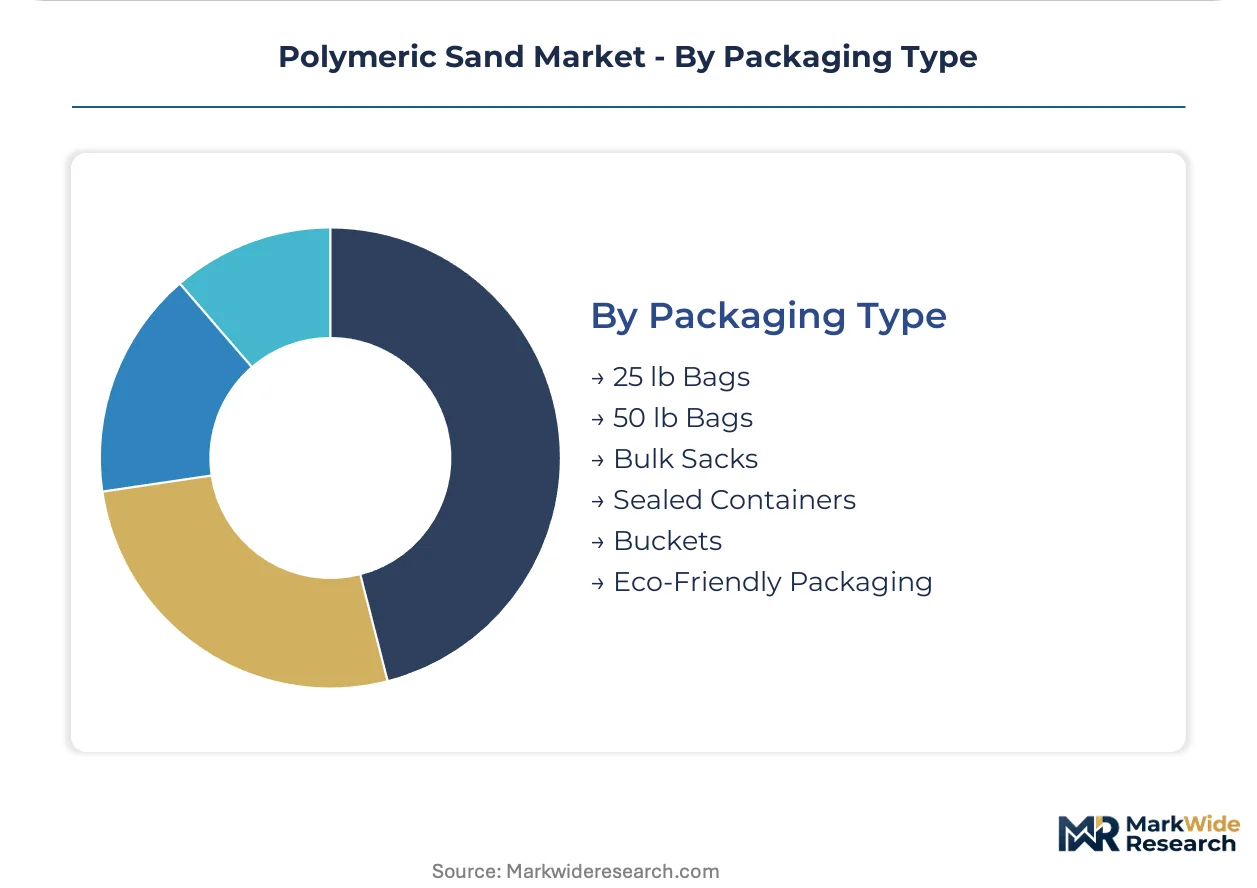
- 50 lb Bags:Standard contractor format balances handling efficiency with inventory flexibility. North American distribution channels stock 50 lb SKUs as baseline contractor procurement unit.
- Bulk Sacks:Large commercial and municipal projects reduce per-unit logistics costs through bulk delivery. German infrastructure tenders specify bulk packaging for plaza and roadway installations exceeding material volume thresholds.
- 25 lb Bags:Retail-accessible format targets DIY residential segments.
- Sealed Containers:Moisture-sensitive epoxy systems require hermetic storage.
- Buckets:Pre-mixed formulations serve repair and touch-up applications.
- Eco-Friendly Packaging:Recyclable and reduced-plastic formats respond to EU Green Deal procurement preferences.
50 lb bags lead on shipment frequency; bulk sacks lead on tonnage velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Landscaping contractors and municipal hardscape specialists cluster in regions with stringent permeable surface mandates and established paver installation networks. Workforce density in outdoor construction trades determines specification velocity for certified jointing compounds.
United States
Mid-Atlantic residential developers drive specification volume through EPA construction site runoff compliance thresholds. Virginia and Maryland state regulations mandate permeable surface coverage percentages for subdivisions exceeding disturbance thresholds. The Washington DC-Baltimore corridor concentrates contractor adoption of certified drainage-compliant jointing systems.
Germany
Municipal green infrastructure tenders in Bavaria and North Rhine-Westphalia specify ISO 9001-certified jointing compounds with verified VOC documentation. The EU Green Deal's material sustainability requirements compress formulation certification timelines for resin suppliers. Stuttgart and Munich anchor specification control through stringent tender documentation standards.
Canada
Ontario and Quebec landscaping contractors integrate polymeric sand for freeze-thaw resilient hardscape installations. Provincial stormwater management guidelines in the Greater Toronto Area accelerate permeable paver adoption for residential driveways. Toronto's contractor networks concentrate procurement through distributors holding pre-certified inventory.
Italy
Lombardy and Veneto hardscape specialists specify color-matched formulations for premium residential outdoor living projects. Regional building codes in Milan's metropolitan area emphasize aesthetic continuity in paver jointing for high-value developments. The Po Valley industrial cluster supports specialized pigment integration capabilities.
Australia
New South Wales and Victoria municipal authorities specify permeable jointing for urban heat island mitigation in plaza and roadway installations. State-level stormwater harvesting regulations in Sydney accelerate specification of drainage-maintaining compounds. The Sydney-Melbourne corridor concentrates contractor training and certification programs.
Polymeric Sand Market Key Industry Players
Capital-heavy producers compete with asset-light designers as integrated resin formulators face pressure from specialized compound blenders outsourcing polymer supply. The market structure consolidates around three tiers: multinational construction chemical conglomerates with captive resin production, regional hardscape specialists controlling distributor relationships, and niche pigment-customization shops serving premium residential segments. Dominant competitive moves include backward integration into silica aggregate mining and strategic partnerships with paver manufacturers for co-specification programs.
Within the specialist compound tier, Techniseal anchors Canadian positioning through regulatory certification depth, while SRW Products exemplifies North American distributor channel control. Alliance Designer Products Inc. occupies the premium-customization vector for color-matched residential specifications. SEK Surebond and Sable Marco sit within the mid-tier regional fabrication cluster serving contractor-direct procurement networks.
| Leading Market Players |
|---|
| SRW Products |
| Sable Marco |
| Techniseal |
| Unilock |
| Vimark Srl |
| Alliance Designer Products Inc. |
| SEK Surebond |
| Quikrete |
| Sakrete |
| Others |
Cost & Logistics Intelligence
Polymer-chemistry technical specialists in the Greater Toronto Area command wage premiums that widen spreads between economy-grade silica formulations and certified polyurethane systems. Labor-cost differentials between certified formulators and commodity blenders translate directly into pricing-tier stratification across contractor procurement channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates epoxy-based commercial grades from silica residential formulations from cement-based maintenance compounds. Price differentiation hinges on REACH certification status and freeze-thaw performance tier. Cost compression in economy silica grades is intensifying because of cement-based jointing substitution in municipal maintenance contracts. Residential developers exhibit highest price sensitivity; municipal infrastructure departments show lowest sensitivity due to decade-long durability guarantees.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Canada anchor hub-and-spoke patterns for contractor-direct fulfillment. Silica aggregate mining clusters in Wisconsin, Bavaria, and Ontario create geographic concentration for fine quartz feedstock. Polymer binder supply draws from petrochemical corridors in the US Gulf Coast and Rotterdam-Antwerp hub. Single-source vulnerability in specialized polyurethane resin grades threatens margin stability for mid-tier formulators. Distribution runs through hardscape-specialist distributors holding pre-certified inventory for municipal tender compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polymeric sand market represents a late-cycle quality story as municipal procurement shifts decisively toward certified low-VOC formulations with documented ISO 9001 compliance.
For Market Incumbents: Cement certification leadership through accelerated REACH-compliant resin binder R&D before German tender deadlines compress. Deepen backward integration into silica aggregate mining in Wisconsin and Bavaria to secure feedstock against logistics bottlenecks. Defend against cement-based jointing substitution by embedding ten-year durability guarantees into municipal maintenance contract structures. For New Entrants and Emerging Players: DIY residential segments in Texas and Florida present accessible entry points through 25 lb bag retail formats and color-matched pigment customization. Target stormwater management compliance gaps in mid-Atlantic residential construction where EPA runoff mandates outpace certified supplier capacity. Launch through big-box retail partnerships with pre-mixed bucket formats for repair and touch-up applications. For Investors and Strategic Acquirers: Construction chemical conglomerates with captive resin production are the most active acquirers in this space, seeking regional hardscape specialists with distributor channel control. The five-to-ten year viability window favors targets with EU Green Deal compliance pathways and established ISO 9001 documentation systems. Monitor state-level permeable surface mandate adoption velocity as the inflection signal for capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Mining | Captive aggregate supply from Wisconsin deposits insulates formulators against logistics bottlenecks. |
| REACH-Compliant Resin Reformulation | Lower-VOC binder certification unlocks German municipal tender access under EU Green Deal mandates. |
| Distributor Channel Expansion | Pre-certified inventory positioning in Toronto and Baltimore corridors captures EPA compliance-driven demand. |
| Color-Matched Pigment Specialization | Premium residential specifications in Texas and Florida reward aesthetic continuity capabilities. |
| Bulk Packaging Infrastructure | Bulk sack logistics for German plaza installations reduce per-ton delivery costs below 50 lb bag alternatives. |
Research Approach
Direct dialogue with landscaping contractors, municipal procurement officers, resin supplier technical directors, and hardscape distributor inventory managers grounded qualitative findings. Secondary validation drew from EPA construction site runoff filings, ECHA REACH substance registrations, German municipal tender documentation, and ISO 9001 certification databases. Bottom-up project pipeline analysis and top-down construction spending trajectories were triangulated to anchor volume estimates.
Segment-level outputs across product type, application, end use industry, packaging format, and regional regulatory cluster were generated through the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating resin feedstock price volatility and state-level permeable surface mandate adoption schedules. Forecast inputs included municipal green infrastructure spending commitments and contractor certification penetration rates by region.
Inputs from EPA and ECHA regulatory filings were available through the study window; gaps in real-time resin binder inventory data introduce uncertainty bands around near-term pricing assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Phenolic Resin Market
Polymers & Resins
Redispersible Polymer Powder Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Hydrogenated Styrene Block Copolymers Market
Polymers & Resins
Global Medium Molecular Weight Polyisobutylene Market
Polymers & Resins
South-East Asia Low-Density Polyethylene (LDPE) Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
US Polycarbonate Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Filled Fluoropolymer Market
Polymers & Resins
Styrenic Block Copolymer (SBC) Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
EVA Resins and Films Market