
 Embossed Film Market | 2026-2036
Embossed Film Market Size, Share, and Industry Trends Forecast 2026-2036
Embossed Film Market Analysis
Buyer concentration in European food packaging is shifting as mid-sized converters consolidate procurement volumes to secure supply stability and technical service. RKW Group anchors large-volume polyethylene film supply across German retail chains. Tee Group Films differentiates through specialty embossing patterns for premium confectionery wrappers. Aintree Plastics Ltd competes in custom short-run labeling films with rapid die-change capability.
Embossed film is a thermoplastic substrate with raised surface patterns created by mechanical calendering or vacuum-forming against engraved rolls, typically ranging from twelve to two hundred microns in thickness, engineered to enhance tactile grip, optical diffusion, or air-channel ventilation in laminated structures. Polypropylene films dominate volume in breathable hygiene and medical packaging applications where thermal embossing creates controlled porosity. Polyester films command margin pools in electronics and automotive interiors due to dimensional stability and heat resistance. Thin film grades represent the fastest-growing thickness category as downgauging pressures intersect with flexible packaging sustainability targets.
REACH restrictions on phthalate plasticizers and FDA food-contact notification requirements for new polymer compositions shape raw material selection and reformulation cycles across the value chain. The EU Packaging and Packaging Waste Regulation, alongside California's extended producer responsibility frameworks, is forcing substrate recyclability redesigns that favor mono-material embossed structures over multi-layer laminates. Stakeholders must monitor how mechanical recycling infrastructure investments in France and Italy alter specifications for embossed film surface contamination tolerance and ink adhesion properties.
Market Dynamics
Mono-material embossing specifications are compressing multi-layer laminate demand as recyclability mandates force substrate redesign across European and North American packaging converters. This structural pivot favors polypropylene and polyethylene homopolymer structures over complex coextrusions.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are accelerating mono-material embossed film adoption in French and Italian food packaging supply chains.
- Electric vehicle cabin acoustics:German automotive interior suppliers are procuring embossed polyester laminates for sound-dampening applications in EV architectures.
- Downgauging technology:Advanced calendering equipment enables sub-twenty-micron embossed films without pattern distortion, opening medical and hygiene segments.
Market Restraints
- Phthalate plasticizer restrictions:REACH Annex XVII limits on phthalates are forcing reformulation cycles that extend qualification timelines for European converters.
- Polymer supply concentration:Polypropylene resin supply clusters in the US Gulf Coast and Rotterdam create input cost volatility during petrochemical turnaround seasons.
- Mechanical recycling contamination tolerance:Current French and Italian sorting infrastructure rejects embossed films with surface ink adhesion above specified thresholds, limiting circular economy participation.
Strategic Opportunities
- California extended producer responsibility:State-level packaging fee structures incentivize embossed film designs that score favorably on recyclability assessment protocols.
- Breathable medical packaging:Thermal embossing of polypropylene films for sterile barrier applications represents underpenetrated demand in German hospital supply chains.
- Digital printing convergence:Combination of inline embossing and inkjet decoration enables short-run premium confectionery packaging with rapid pattern changeover.
Industry Challenges
- Skilled calendering technician scarcity:Engraved roll maintenance and pattern registration expertise concentrates among aging workforces in German and Italian film extrusion clusters.
- FDA food-contact notification timelines:New polymer compositions for embossed substrates face eighteen-to-twenty-four-month regulatory review cycles that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embossed Film Market |
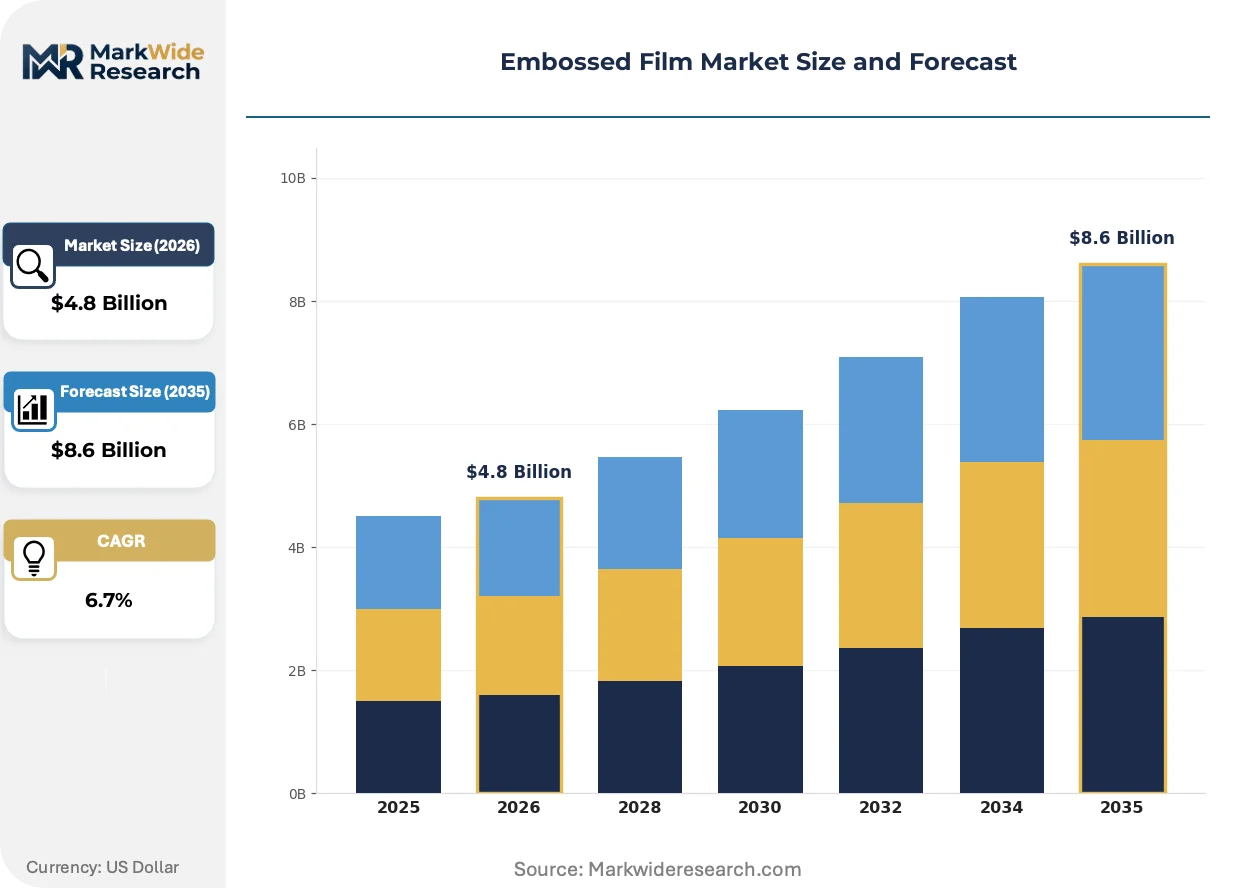
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polypropylene, PVC, Others Application: Packaging, Labeling, Decorative, Textiles End User: Packaging Industry, Automotive, Electronics, Consumer Goods Thickness: Thin Film, Medium Film, Thick Film, Ultra-Thin Film |
| Companies Covered | Tee Group Films, Aintree Plastics Ltd, RKW Group, Hi-Tech Packaging (India) Private Limited, C. E. Shepherd Company, Plastotecnica, Ampa Plastics Group, Skymark Packaging International Limited, ISOSPORT Verbundbauteile GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embossed Film Market Emerging Trajectories
Laser-engraved roll technology and inline vision systems are compressing pattern development cycles while enabling real-time quality verification. These capabilities are shifting competitive advantage toward converters with integrated design-to-production workflows.
Micro-embossing technology is expanding into pharmaceutical blister packaging as drug manufacturers adopt child-resistant lidding with tactile verification features. German packaging converters are installing multi-zone calendering lines capable of pattern depth variation across single web widths. This capability is expanding into compliance-driven markets where authentication features command specification premiums.
REACH restrictions on per- and polyfluoroalkyl substances are forcing substrate redesigns in grease-resistant food packaging applications. ECHA's proposed PFAS ban timeline is compressing fluoropolymer coating alternatives development across European converter R&D programs. French and Italian food brands are accelerating embossed polyethylene specifications that substitute mechanical barrier performance for chemical treatments.
Consolidation among mid-sized European converters is compressing supplier bases and extending technical service expectations. German retail chains are consolidating embossed film procurement through nominated supplier programs that mandate volume commitments and co-development investment. This concentration is visible in polyethylene hygiene film segments where three converters now supply majority German private-label demand.
Embossed Film Market Segmentation
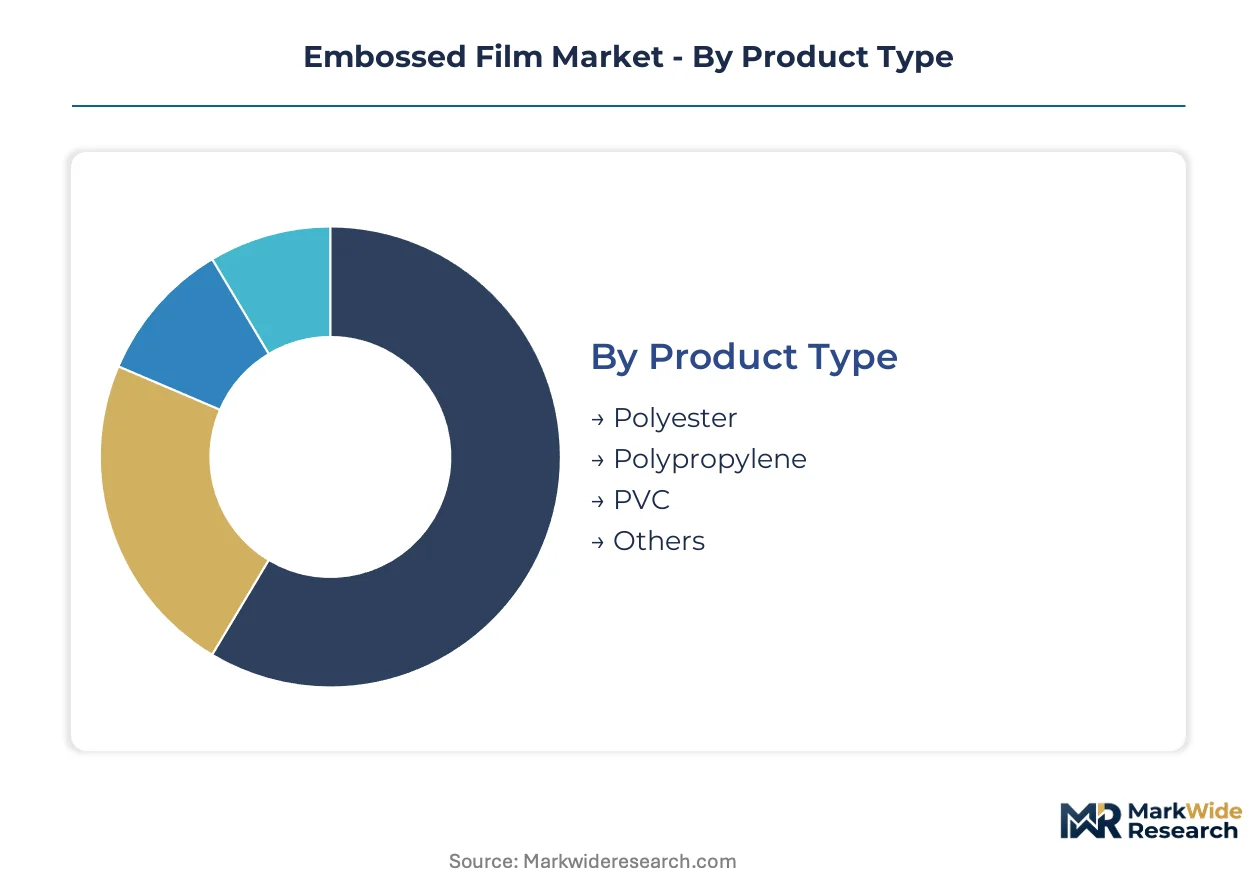
Embossed film specifications diverge sharply across polymer chemistry and thickness grades, with converters selecting substrates based on thermal tolerance, barrier requirements, and recyclability mandates. Segmentation clarity enables procurement teams to match calendering capabilities against end-use performance thresholds without over-engineering cost structures.
Product Type:
Polymer selection determines embossing depth fidelity, heat resistance, and compatibility with downstream lamination processes.
- Polyester:Biaxially oriented polyethylene terephthalate substrates retain dimensional stability above 150°C, enabling deep-pattern embossing for automotive interior laminates. German EV cabin suppliers specify embossed polyester for acoustic damping layers where thermal cycling resistance is non-negotiable.
- Polypropylene:Isotactic polypropylene homopolymers dominate breathable hygiene applications through controlled thermal embossing that creates microporous channels. French and Italian converters favor this substrate for mono-material packaging redesigns driven by EU recyclability targets.
- PVC:Plasticized vinyl films offer low-temperature embossing flexibility for decorative wallcoverings and synthetic leather applications.
- Others:Polycarbonate and bio-based PLA variants serve niche medical and premium cosmetic segments requiring optical clarity or compostability certification.
Polypropylene leads on scale; polyester leads on momentum as automotive electrification accelerates specification upgrades.
Application:
End-use functionality dictates pattern geometry, from micro-embossed air channels to macro-scale tactile grips.
- Packaging:Food and pharmaceutical converters deploy embossed films for controlled ventilation, anti-slip stacking, and tamper-evident features. Thermal embossing of polypropylene creates sterile barrier properties for German hospital supply chains.
- Labeling:Pressure-sensitive label facestocks leverage micro-embossing for premium haptics and optical diffusion without ink coverage.
- Decorative:Furniture and automotive interior laminates specify deep-pattern embossed films for wood-grain simulation and soft-touch surfaces.
- Textiles:Synthetic leather and technical textile backings utilize embossed films as carrier substrates with controlled elongation properties.
Packaging commands volume concentration; labeling gains share fastest as premium brand owners invest in tactile differentiation.
End User:
Customer technical requirements span from commodity hygiene specifications to precision-tolerance electronics applications.
- Packaging Industry:Food, pharmaceutical, and personal care converters represent the dominant procurement base, with consolidation among mid-sized European players extending supplier qualification demands.
- Automotive:Interior tier suppliers source embossed laminates for EV cabin acoustics and decorative soft-touch surfaces, with German OEMs driving pattern complexity requirements.
- Electronics:Display diffusers and membrane switch substrates require sub-twenty-micron embossing with optical-grade pattern registration.
- Consumer Goods:Appliance and cosmetic brands specify embossed films for premium unboxing experiences and anti-counterfeiting features.
Packaging industry anchors procurement volumes; automotive climbs the fastest as electrification reshapes interior material specifications.
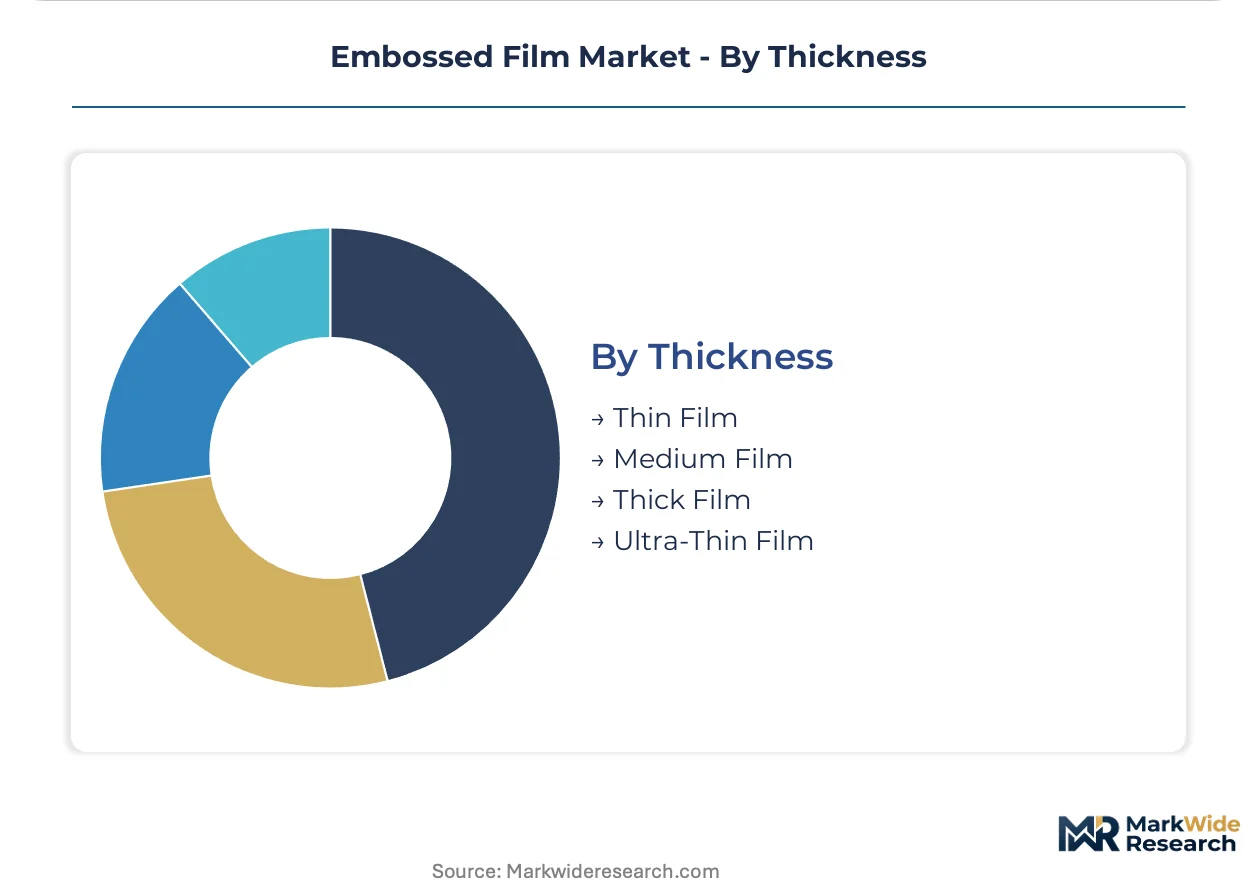
Thickness:
Downgauging pressure intersects with functional requirements across medical, hygiene, and flexible packaging segments.
- Thin Film:Sub-forty-micron grades enable material reduction in flexible pouches and sterile barrier systems without sacrificing mechanical integrity. Advanced calendering equipment maintains pattern fidelity at these gauges.
- Medium Film:Forty-to-eighty-micron specifications balance processability with stiffness for standard food packaging and labeling applications.
- Thick Film:Above-eighty-micron substrates serve heavy-duty industrial packaging and decorative laminates requiring structural rigidity.
- Ultra-Thin Film:Sub-twenty-micron embossed films target medical and electronics segments where weight reduction and conformability are critical.
Medium film retains installed base dominance; thin film expands most quickly as sustainability targets force material intensity reductions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium automotive embossed film specifications while India scales commodity-grade supply for hygiene and food packaging converters. China concentrates calendering equipment manufacturing and raw material resin production. The United States shapes regulatory frameworks that cascade through North American supply chains.
Germany
Electric vehicle cabin acoustics and decorative interior laminates drive specification upgrades among Baden-Württemberg and Bavaria automotive tier suppliers. REACH Annex XVII phthalate restrictions and ECHA PFAS proposals force reformulation cycles across converter R&D programs. The Stuttgart automotive cluster sources embossed polyester laminates for sound-dampening applications in EV architectures.
United States
California extended producer responsibility frameworks and FDA food-contact notification requirements reshape packaging substrate specifications. Flexible packaging converters in the Midwest and Southeast adapt to state-level packaging fee structures that favor mono-material designs. The US Gulf Coast polypropylene resin concentration creates input cost volatility during petrochemical turnaround seasons.
China
Calendering equipment manufacturing and polypropylene resin production concentrate in Yangtze River Delta and Pearl River Delta industrial corridors. Domestic converters serve hygiene and food packaging demand across Asia-Pacific markets. Shanghai and Zhejiang film extrusion clusters export embossed substrates to Southeast Asian packaging converters.
India
Food packaging and hygiene film demand accelerates among Maharashtra and Gujarat converter operations. BIS standards and FSSAI food-contact material regulations tighten substrate specifications for domestic and export markets. The Mumbai-Pune industrial corridor hosts expanding polyethylene and polypropylene film extrusion capacity.
France
EU Packaging and Packaging Waste Regulation implementation accelerates mono-material redesigns among Île-de-France and Auvergne-Rhône-Alpes food brands. ANSM pharmaceutical packaging standards elevate barrier performance requirements for medical embossed films. Lyon and Paris packaging clusters invest in mechanical recycling-compatible substrate development.
Embossed Film Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct specification tiers. The vendor base organizes around volume-scale commodity suppliers, pattern-specialty converters, and custom short-run fabricators. Three archetypes dominate: integrated resin-to-film operators controlling upstream polymer supply, independent converters leveraging engraved roll expertise, and regional specialists serving niche medical or automotive segments. Competitive moves concentrate on capacity expansion in mono-material lines and strategic partnerships with brand owners for co-development programs.
Among European-based converters, RKW Group anchors large-volume polyethylene supply across retail chain procurement programs. Tee Group Films exemplifies pattern-specialty positioning through engraved roll capabilities for premium packaging applications. Aintree Plastics Ltd occupies the custom short-run tier with rapid die-change infrastructure for labeling film specifications.
| Leading Market Players |
|---|
| Tee Group Films |
| Aintree Plastics Ltd |
| RKW Group |
| Hi-Tech Packaging (India) Private Limited |
| C. E. Shepherd Company |
| Plastotecnica |
| Ampa Plastics Group |
| Skymark Packaging International Limited |
| ISOSPORT Verbundbauteile GmbH |
| Others |
Supply Flow & Price Mechanics
Performance-grade divergence between automotive acoustic laminates and commodity hygiene films manifests in divergent pricing architectures and supply chain configurations. Premium polyester specifications for German EV cabin applications command contract-based long-term offtake structures with engraved roll exclusivity clauses, while polyethylene hygiene grades trade on spot-indexed resin pass-through mechanisms with minimal value-added capture.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard polypropylene embossed films. Three-tier pricing structure across premium, standard, and economy levels reflects pattern complexity and thermal tolerance certifications. Cost compression in commodity hygiene grades intensifies because of resin supply volatility at US Gulf Coast and Rotterdam hubs. Small-scale Italian converters exhibit highest price sensitivity due to limited volume leverage, whereas German automotive tier suppliers prioritize technical service over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with engraved roll manufacturing concentrated in Germany and Italy. Polypropylene resin production clusters in the US Gulf Coast, Rotterdam, and China's Pearl River Delta. Raw material dependencies encompass petroleum-derived olefins, specialty steel for calendering equipment, and laser engraving consumables. Tariff exposure on Chinese calendering machinery imports threatens European converter capex cycles. Distribution runs through nominated supplier programs at major German retail chains and direct mill relationships for automotive specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The embossed film market functions as a geographic-arbitrage play where REACH compliance costs in Europe exceed California EPR administrative burdens, creating margin capture opportunities for North American converters serving premium packaging segments.
For Market Incumbents: Deepen backward integration into polypropylene resin supply through offtake agreements with Rotterdam and US Gulf Coast producers to offset feedstock volatility. Secure engraved roll maintenance expertise through apprenticeship partnerships with German and Italian technical institutes to address aging workforce attrition. Defend position against Asian equipment manufacturers by embedding inline vision systems and digital pattern libraries that compress qualification timelines for FDA food-contact notifications. For New Entrants and Emerging Players: Launch via digital printing convergence partnerships with premium confectionery brands seeking rapid pattern changeover capabilities. Target breathable medical packaging specifications for German hospital supply chains where thermal embossing of polypropylene remains underpenetrated. Exploit white-space in California EPR-compliant mono-material structures by co-developing recyclable substrates with mid-sized French and Italian food brands. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-sized European converters lack capital for multi-zone calendering line upgrades required by German automotive specifications. Long-term viability favors integrated resin-to-film operators with captive polymer supply and pattern-specialty converters holding engraved roll IP. Target acquisition archetype: Italian or French converters with mechanical recycling-compatible substrate development capabilities and established brand owner co-development relationships. Signal to watch: FDA food-contact notification approval velocity for novel polymer compositions as indicator of regulatory friction costs.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-material Line Capacity Expansion | EU Packaging and Packaging Waste Regulation mandates accelerate specification shifts in French and Italian supply chains. |
| Laser Engraving Technology Licensing | German automotive tier suppliers demand pattern depth variation across single web widths for EV cabin acoustics. |
| Backward Integration into Polypropylene Resin | Rotterdam and US Gulf Coast supply concentration creates margin vulnerability during petrochemical turnaround seasons. |
| Digital Printing Convergence Partnership | Premium confectionery brands in Germany seek inline embossing with inkjet decoration for short-run flexibility. |
| Mechanical Recycling Compatibility Certification | French and Italian sorting infrastructure thresholds for surface ink adhesion limit circular economy participation. |
Methodological Framework
Multiple input streams — primary interviews with film extrusion plant managers, procurement leads at German automotive tier suppliers, and distribution channel partners; secondary validation through customs/trade data, SEC 10-K filings of resin producers, and Cefic industry reports — were reconciled using bottom-up and top-down triangulation. Conversations with engraved roll maintenance technicians and technical R&D directors at European converters provided qualitative calibration on pattern development cycle compression.
Data-stream reconciliation across polymer chemistry, thickness grades, application segments, and regional production clusters informed the analytical framework over the projection horizon. Segmentation dimensions encompassed polyester versus polypropylene substrate selection, thin-to-thick film specifications, and automotive versus packaging end-use concentration. CAGRs were derived from elasticity modeling against resin price trajectories and regulatory implementation timelines. Industry-specific forecast inputs included EU Packaging and Packaging Waste Regulation enforcement velocity and German EV production ramp schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA PFAS ban acceleration or mechanical recycling contamination threshold tightening in France and Italy. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Twist Wrap Film Market
Poly film
Bundling Film Market
Poly film
Global BOPET Packaging Films Market
Poly film
Silicone-Coated PET Films Market
Poly film
India Plastic Packaging Film Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
Colombia Plastic Packaging Films Market
Poly film
Australia and New Zealand Plastic Packaging Film Market
Poly film
Global Specialty Films Polymer Market
Poly film
Foamed Polypropylene Films Market
Poly film
LDPE Films Market
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
Polyurethane (PU) Film Market
Poly film
Peelable and Resealable Films Market
Poly film
High Density Polyethylene Film Market
Poly film
Stretch Films Packs Market