
 Middle East and Africa Amino Acids Market | 2026-2036
Middle East and Africa Amino Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Amino Acids Market Foresight
Pharmaceutical buyers are unwinding share from traditional food-industry offtake as biologic drug manufacturing expands across the Gulf. Ajinomoto Co., Inc. leverages its fermentation technology leadership to supply high-purity grades for injectable formulations. Evonik Industries AG anchors regional animal feed supply through its methionine production network. Merck KGaA differentiates via pharmaceutical-grade amino acids for cell culture media.
Middle East and Africa amino acids comprise organic compounds containing amine and carboxyl functional groups, typically produced via microbial fermentation or enzymatic synthesis, serving as protein building blocks and metabolic intermediates across industrial applications. The animal feed application dominates volume consumption as regional poultry and aquaculture operations expand, while pharmaceutical-grade L-Glutamine and L-Arginine command premium margins due to stringent purity requirements. Powder form leads logistics efficiency for bulk feed blending, though soluble grades gain traction in clinical nutrition and sports nutrition end uses.
Saudi Arabia's SFDA and South Africa's Department of Agriculture enforce feed additive safety protocols that elevate compliance costs for imported amino acids. Egypt's national pharmaceutical regulator applies WHO-aligned GMP standards for amino acids used in parenteral nutrition, restricting market access to certified manufacturers. Stakeholders must monitor evolving halal certification requirements for fermentation-derived products and assess local production partnerships before committing capital to regional expansion.
Market Dynamics
Saudi Arabia's SFDA feed additive purity mandates are compressing supplier margins while redirecting procurement toward certified fermentation facilities, fundamentally restructuring Middle East and Africa amino acid sourcing patterns.
Growth Catalysts
- Livestock operation scaling:Poultry and aquaculture integrators across South Africa and Egypt are expanding lysine and methionine offtake to support protein production targets.
- WHO-aligned GMP enforcement:Egypt's national pharmaceutical regulator applies stringent manufacturing standards for parenteral nutrition amino acids, filtering out uncertified suppliers.
- Fermentation technology maturation:Microbial production platforms are achieving pharmaceutical-grade purity thresholds that unlock injectable formulation demand across Gulf biologic manufacturing.
Market Restraints
- Import dependency concentration:Regional supply concentrates through a narrow corridor of certified Asian and European fermentation facilities, exposing buyers to shipping disruptions.
- Halal certification complexity:Fermentation-derived amino acids face variable religious compliance standards across Gulf Cooperation Council jurisdictions, fragmenting product registration requirements.
- Feed-grade pricing compression:Bulk lysine and methionine face margin pressure from standardized commodity specifications that limit premium extraction.
Strategic Opportunities
- Cell culture media expansion:Biologic drug manufacturing growth across the UAE and Saudi Arabia creates demand for pharmaceutical-grade L-Glutamine and L-Arginine with stringent purity specifications.
- Local production partnerships:Joint ventures with established fermentation technology holders can bypass import bottlenecks while satisfying SFDA traceability requirements.
- Soluble grade nutrition penetration:Clinical and sports nutrition applications in South Africa's private healthcare sector favor water-soluble amino acid formats over traditional powders.
Industry Challenges
- Fermentation specialist scarcity:The region lacks sufficient industrial microbiologists and downstream processing engineers to staff expanded amino acid manufacturing capacity.
- Multi-jurisdiction registration timelines:Separate SFDA, Department of Agriculture, and national pharmaceutical regulator approvals extend product commercialization cycles.
- Legacy feed blending infrastructure:Existing animal feed facilities require capital retrofitting to handle pharmaceutical-grade segregation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Amino Acids Market |
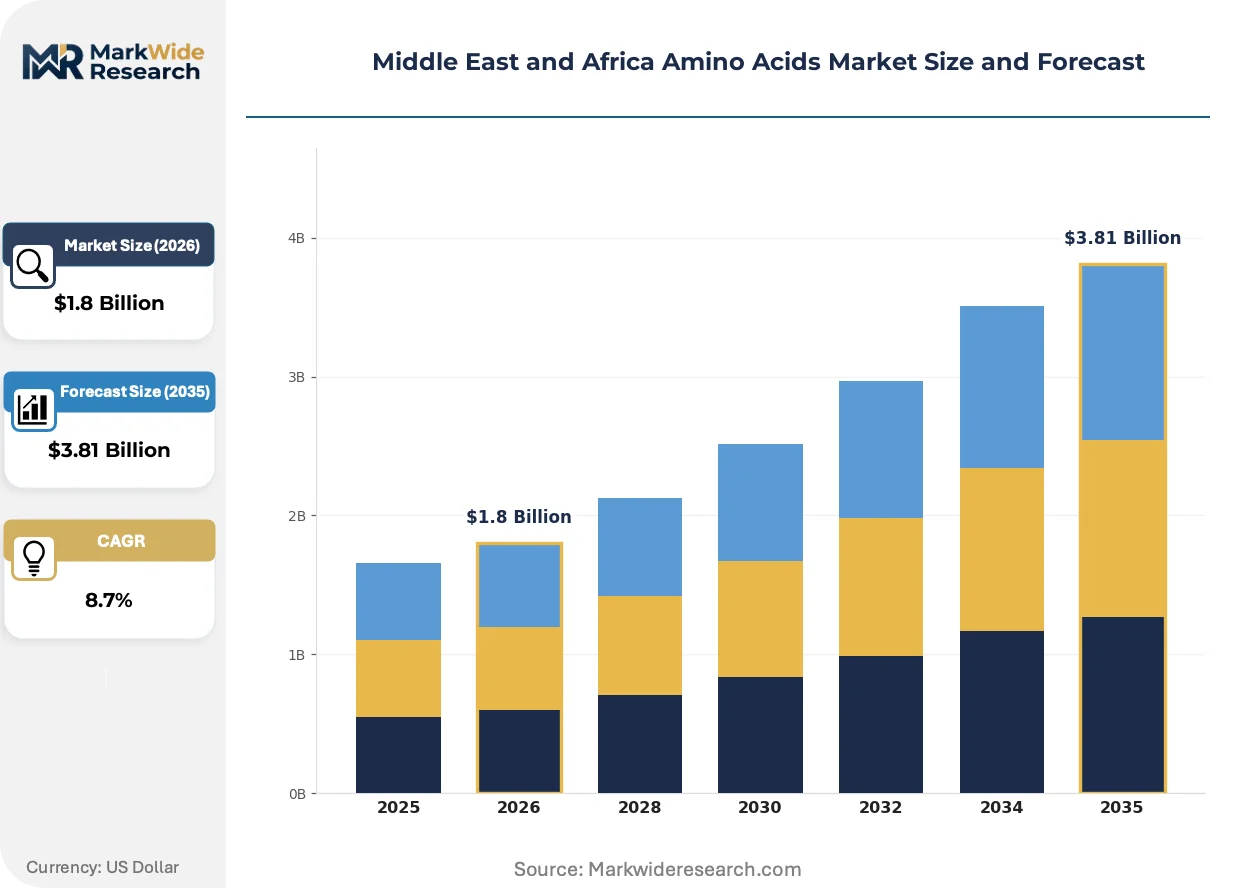
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Glutamine, L-Arginine, L-Leucine, L-Tryptophan Application: Food & Beverage, Animal Feed, Pharmaceuticals, Nutritional Supplements Form: Soluble, Powder, Granular, Liquid End User: Healthcare, Sports Nutrition, Food Industry, Animal Husbandry |
| Companies Covered | Ajinomoto Co., Inc., Evonik Industries AG, Merck KGaA, Kyowa Hakko Bio Co., Ltd., Archer Daniels Midland Co., Adisseo, CJ CheilJedang Corp, Prinova Group LLC, Daesang, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Amino Acids Market Shifts & Advancements
Continuous fermentation monitoring systems are displacing batch quality control in regional amino acid plants, while halal blockchain traceability and direct-to-integrator supply contracts are compressing traditional distribution layers across the Middle East and Africa.
Single-use bioreactor technology is miniaturizing upstream amino acid production footprints for pharmaceutical-grade applications. Gulf biologic manufacturers are adopting these modular systems to reduce cross-contamination risks during multi-product campaigns. This shift is miniaturizing capital requirements for entry-grade fermentation capacity while accelerating product changeover timelines.
South Africa's Department of Agriculture is tightening mycotoxin co-contamination limits in imported feed additives, forcing amino acid suppliers to enhance pre-shipment testing protocols. The regulation elevates compliance costs for bulk lysine and methionine shipments. Poultry integrators are responding by consolidating procurement through distributors with in-house analytical laboratories.
Integrated livestock producers are compressing supplier relationships from multi-vendor spot purchasing to sole-source annual contracts with quality guarantees. This consolidation displaces traditional feed additive traders across Egypt and Nigeria's poultry belts. The pattern is most visible among South Africa's vertically integrated aquaculture operations seeking batch-to-batch amino acid consistency.
Middle East and Africa Amino Acids Market Segmentation
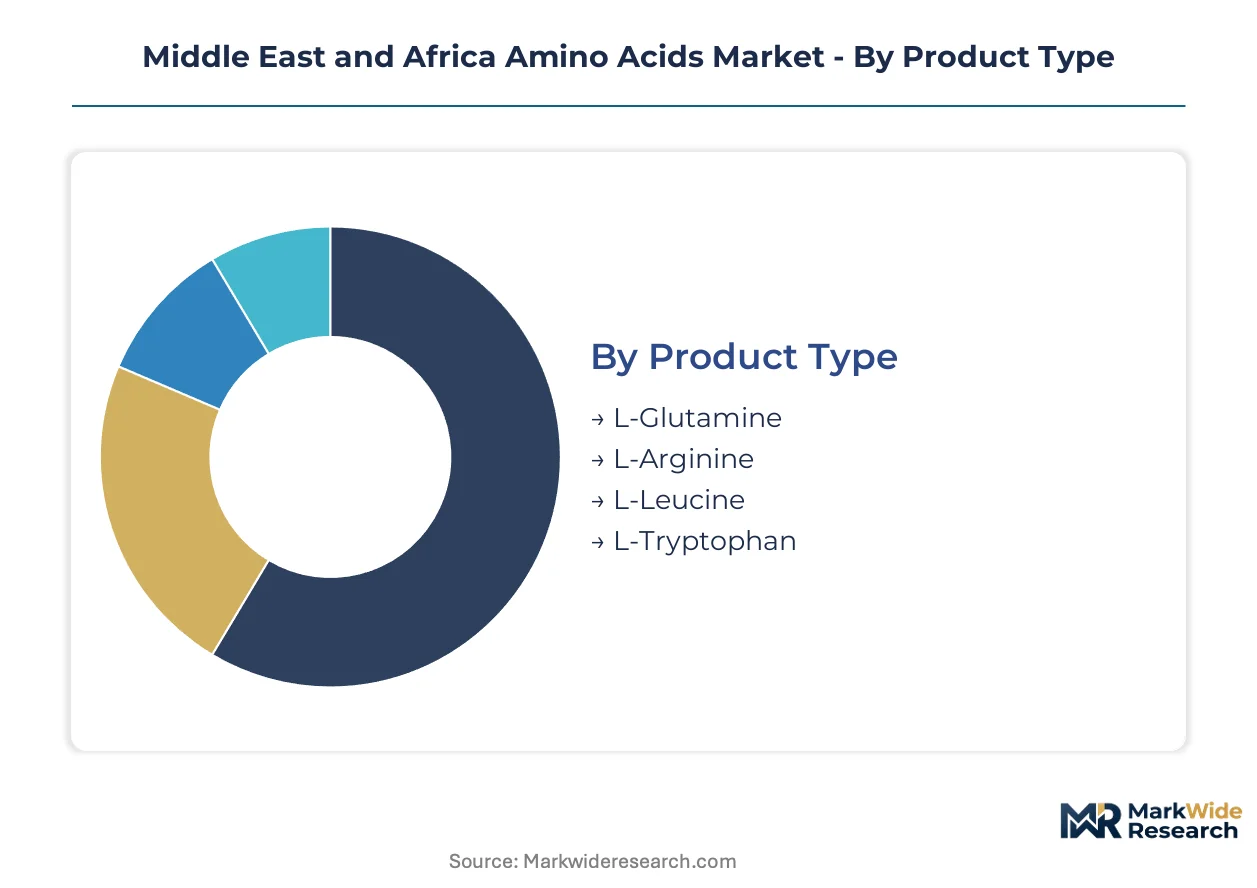
Amino acid suppliers across the Middle East and Africa navigate divergent purity requirements and channel economics. Product form and certification grade determine whether shipments flow through pharmaceutical distributors, feed compounders, or direct-to-manufacturer contracts.
Product Type:
Channel economics split sharply between pharmaceutical-grade amino acids moving through licensed distributors and feed-grade products flowing direct to integrators.
- L-Glutamine:Pharmaceutical-grade specifications command premium positioning in Gulf biologic manufacturing. UAE and Saudi Arabia cell culture facilities source this amino acid for monoclonal antibody production under SFDA traceability mandates.
- L-Arginine:Parenteral nutrition applications in Egypt's hospital networks drive demand for injectable-grade material. The country's national pharmaceutical regulator enforces WHO-aligned GMP standards that filter out uncertified suppliers.
- L-Leucine:Sports nutrition formulators in South Africa's private healthcare sector favor this branched-chain amino acid for recovery formulations.
- L-Tryptophan:Poultry feed applications dominate offtake as Egyptian and Nigerian integrators seek to optimize broiler growth rates.
L-Glutamine dominates installed base. L-Arginine is where expansion concentrates.
Application:
Cost tier stratification separates commodity feed additives from premium pharmaceutical and clinical nutrition grades.
- Animal Feed:Bulk lysine and methionine shipments constitute the volume anchor. South Africa's vertically integrated poultry and aquaculture operations purchase through sole-source annual contracts with quality guarantees.
- Pharmaceuticals:Injectable-grade amino acids for parenteral nutrition and cell culture media attract the steepest expansion trajectory. Gulf biologic manufacturers require fermentation-derived material with documented halal compliance.
- Food & Beverage:Fortification applications in processed foods face margin pressure from standardized commodity specifications.
- Nutritional Supplements:Clinical and sports nutrition segments in South Africa favor water-soluble formats over traditional powders.
Animal Feed dominates installed base. Pharmaceuticals is where expansion concentrates.
Form:
Supply concentration in powder grades contrasts with emerging demand for soluble and liquid formats in specialized applications.
- Powder:Logistics efficiency favors bulk feed blending operations across Egypt and Nigeria's poultry belts. Existing animal feed facilities handle this format without capital retrofitting.
- Soluble:Clinical nutrition and sports nutrition end uses in South Africa's private healthcare sector drive adoption. Water-soluble grades eliminate dissolution steps in parenteral formulation.
- Liquid:Automated dosing systems in large-scale aquaculture operations prefer this format for precision amino acid delivery.
- Granular:Dust-reduction properties appeal to feed mill operators handling high-volume methionine supplementation.
Powder dominates installed base. Soluble is where expansion concentrates.
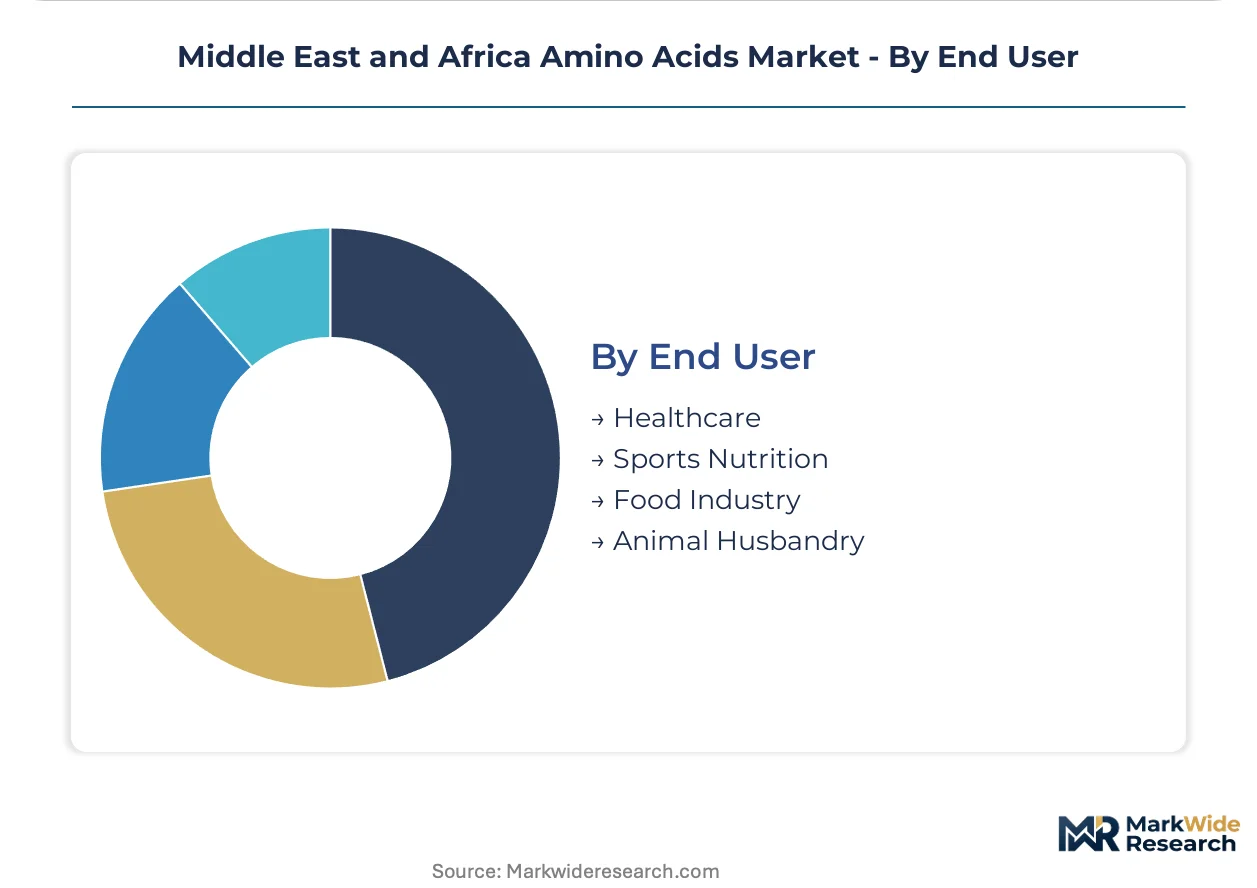
End User:
Customer type determines certification burden and contract structure, from spot purchasing to multi-year supply agreements with audit rights.
- Healthcare:Hospital networks and parenteral nutrition compounders in Egypt enforce WHO-aligned GMP standards. Procurement concentrates through distributors with in-house analytical laboratories.
- Animal Husbandry:Integrated livestock producers compress supplier relationships from multi-vendor spot purchasing to sole-source contracts. South Africa's Department of Agriculture mycotoxin limits elevate pre-shipment testing costs.
- Sports Nutrition:Private healthcare sector formulators in South Africa seek batch-to-batch consistency for premium recovery products.
- Food Industry:Processed food fortification applications face standardized specifications that limit premium extraction.
Animal Husbandry dominates installed base. Healthcare is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese and European fermentation facilities export bulk lysine and methionine through Gulf ports to serve Saudi Arabia's integrators and South Africa's poultry belts. Regional buyers face shipping disruption exposure from this import dependency concentration.
Saudi Arabia
Integrated poultry operations in the Riyadh corridor are expanding methionine offtake for broiler protein optimization. The SFDA enforces feed additive purity mandates that redirect procurement toward certified fermentation facilities. Jeddah's port infrastructure handles the majority of amino acid import volume for domestic feed compounders.
South Africa
Vertically integrated aquaculture and poultry producers in the Western Cape are consolidating lysine purchases through sole-source annual contracts. The Department of Agriculture applies tightening mycotoxin co-contamination limits that elevate pre-shipment testing costs for bulk shipments. Durban's chemical import terminals serve as the primary entry point for feed-grade amino acids destined for KwaZulu-Natal feed mills.
Egypt
Poultry integrators across the Nile Delta are scaling L-tryptophan supplementation to optimize broiler growth rates. The national pharmaceutical regulator enforces WHO-aligned GMP standards for parenteral nutrition amino acids that filter uncertified suppliers. Alexandria's port complex processes pharmaceutical-grade shipments for Cairo's hospital network compounders.
United Arab Emirates
Biologic drug manufacturers in Dubai's biotechnology cluster are sourcing pharmaceutical-grade L-glutamine for monoclonal antibody production. MOHAP traceability mandates require documented halal compliance for fermentation-derived cell culture media inputs. Jebel Ali's free zone infrastructure supports re-export of certified amino acids to Gulf Cooperation Council markets.
Nigeria
Poultry belt operations in Lagos and Ogun states are expanding feed additive procurement as commercial broiler production scales. The national food and drug regulator applies variable import standards that fragment product registration timelines across West African markets. Kano's emerging feed milling corridor is attracting amino acid distributor investment for northern livestock operations.
Middle East and Africa Amino Acids Market Competitive Landscape
Listed leaders compete with private specialists across certification-grade tiers in the Middle East and Africa amino acids market. Japanese and German publicly traded entities anchor pharmaceutical-grade supply while privately held Asian fermentation specialists dominate feed-grade volume. Three archetypes define positioning: integrated fermentation technology holders, pharmaceutical-grade purity specialists, and regional distribution consolidators. Capacity expansion through joint ventures and technology licensing agreements represent the dominant competitive moves as stakeholders seek SFDA traceability compliance.
Among Japanese fermentation technology holders, Ajinomoto Co., Inc. and Kyowa Hakko Bio Co., Ltd. exemplify the pharmaceutical-grade purity specialist archetype with documented halal compliance capabilities. German chemical conglomerate Evonik Industries AG occupies a position within the integrated technology holder tier, while Merck KGaA represents the life-sciences-focused segment serving cell culture media applications. These three entities anchor the premium-grade supply vector for Gulf biologic manufacturing and Egyptian parenteral nutrition markets.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Evonik Industries AG |
| Merck KGaA |
| Kyowa Hakko Bio Co., Ltd. |
| Archer Daniels Midland Co. |
| Adisseo |
| CJ CheilJedang Corp |
| Prinova Group LLC |
| Daesang |
| Others |
Supply & Pricing Matrix
Fermentation facility scale economies in Chinese and European production hubs concentrate cost advantages among established technology holders, compressing price floors for bulk lysine and methionine while elevating premiums for pharmaceutical-grade certification tiers across Middle East and Africa markets.
Pricing Analysis
Batch-process versus continuous-fermentation technology generations command divergent price premiums, with legacy batch systems anchoring feed-grade commodity floors and continuous monitoring platforms extracting pharmaceutical-grade margins. Three-tier pricing structure across pharmaceutical, feed-grade, and technical specifications segments buyer willingness-to-pay by purity threshold and regulatory documentation burden. Cost compression in feed-grade lysine intensifies as South African poultry integrators consolidate procurement through sole-source contracts with quality guarantees. Animal feed compounders exhibit highest price sensitivity, while Gulf biologic manufacturers accept steep premiums for SFDA-traceable injectable-grade material.
Supply Chain Analysis
Strait of Hormuz transit underwrites the majority of amino acid import volume reaching Saudi Arabia's Jeddah corridor and UAE's Jebel Ali free zone, exposing regional buyers to shipping disruption risk from this logistics chokepoint. Supply concentrates through certified fermentation facilities in China, Germany, and Japan, with corn-derived glucose and nitrogen sources feeding upstream microbial production platforms. Single-source vulnerability concentrates in pharmaceutical-grade L-glutamine and L-arginine, where halal-certified fermentation capacity remains tethered to a narrow supplier base. Distribution runs through Gulf port free zones for re-export coordination, with direct-to-integrator contracts displacing traditional feed additive traders across Egypt and Nigeria's poultry belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where SFDA traceability mandates and WHO-aligned GMP certification create switching costs that protect incumbent positions while raising barriers for uncertified challengers.
For Market Incumbents: Secure sole-source annual contract structures with South Africa's vertically integrated poultry and aquaculture operations to lock in volume commitments before emerging Asian fermentation specialists achieve halal certification. Deepen backward integration into corn-derived glucose supply through joint ventures with Egyptian agricultural processors, reducing exposure to commodity input volatility while satisfying SFDA origin-documentation requirements.
For New Entrants and Emerging Players: Lead with soluble-grade amino acid formats targeting South Africa's private healthcare sector clinical nutrition applications, where water-soluble specifications remain underpenetrated relative to powder-dominant feed channels. Pursue technology licensing partnerships with established Japanese fermentation holders to bypass multi-year certification timelines, leveraging their documented halal compliance for rapid Gulf market access.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade purity specialists serving Gulf biologic manufacturing and Egyptian parenteral nutrition compounders, where multi-year supply agreements with audit rights generate predictable offtake across the analysis window. Prioritize acquisition targets with existing SFDA registration dossiers and in-house analytical laboratory capabilities. Monitor Egyptian national pharmaceutical regulator enforcement patterns as the inflection signal for certification-tier margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Investment | SFDA and MOHAP traceability mandates require documented fermentation compliance for Gulf market access. |
| Joint Venture with Technology Holder | Local production partnerships bypass import bottlenecks while satisfying Egyptian WHO-aligned GMP standards. |
| Continuous Fermentation Upgrade | Real-time quality monitoring systems displace batch control, unlocking pharmaceutical-grade purity thresholds. |
| Soluble Grade Product Line Expansion | Water-soluble formats capture South African clinical nutrition demand without feed-mill infrastructure retrofit. |
| Direct-to-Integrator Contract Structure | Sole-source agreements with South African poultry belts displace traditional distribution margin layers. |
Research Methodology
Desk research of trade customs data, SFDA regulatory filings, and WHO GMP certification databases preceded structured interviews with fermentation plant managers, pharmaceutical procurement leads at Gulf biologic manufacturers, feed compounder technical directors, and Egyptian hospital network formulary managers. Secondary validation drew from SEC filings of listed amino acid producers, South African Department of Agriculture mycotoxin enforcement records, and port authority import manifests. Bottom-up volume estimates by product grade and application triangulated against top-down market sizing from production capacity utilization rates.
Variance decomposition across the projection horizon isolates volume growth drivers from price-mix effects, with segmentation modeling across pharmaceutical-grade, feed-grade, and technical specifications intersecting with powder, soluble, and liquid form factors. CAGRs were derived from installed base expansion rates and replacement demand patterns, incorporating poultry and aquaculture operation scaling trajectories alongside biologic manufacturing capacity buildouts in the UAE and Saudi Arabia.
Forecasts assume regulatory continuity in Saudi SFDA feed additive mandates and Egyptian pharmaceutical GMP enforcement; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as halal certification standard harmonization across Gulf Cooperation Council jurisdictions evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Arginine Market
Specialty Chemicals
Zinc Ricinoleate Market
Specialty Chemicals
Phytosphingosine Market
Specialty Chemicals
Esterquats Market
Specialty Chemicals
Mequinol Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Structure Directing Agents Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Sophorolipids Market
Specialty Chemicals
1,2 Hexanediol Market
Specialty Chemicals
Sandarac Market
Specialty Chemicals
Organosilicon Electrolyte Market
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Fatliquoring Agents Market