
 Allantoin Market | 2026-2036
Allantoin Market Size, Share, and Industry Trends Forecast 2026-2036
Allantoin Market Intelligence
A shift from single-source to multi-source procurement for cosmetic and pharmaceutical grade allantoin is recalibrating supply chain dependencies for personal care manufacturers. This change pressures established suppliers while creating openings for regional specialists. Lonza Group leverages its pharmaceutical background to offer high-purity grades for wound healing applications. Meanwhile, Symrise competes on its integrated portfolio for cosmetic active ingredients, and BASF utilizes its vast chemical manufacturing scale.
Allantoin is a diureide of glyoxylic acid, a chemical compound used primarily for its keratolytic, moisturizing, and soothing properties. It functions by promoting cell proliferation and aiding in the healing process of skin. Cosmetic Grade material commands the largest share due to its extensive use in skin care and hair care formulations. The pharmaceutical grade segment, while smaller, offers higher margins and is essential for wound healing and specific oral care products.
Regulatory frameworks from the US FDA, the European Union's EMA, and China's NMPA govern purity and safety standards, directly impacting market access for suppliers. These regulations mandate specific testing and documentation for allantoin used in pharmaceutical and cosmetic applications. Future competitive advantage will hinge on a supplier's ability to navigate these diverse international compliance requirements while managing production costs.
Market Dynamics
The market's structure is defined by tightening purity standards from regulators like the EU and FDA. This pressure forces manufacturers to diversify suppliers, balancing compliance risk against procurement costs for cosmetic and pharmaceutical applications.
Growth Catalysts
- EU Regulations:The EU's Cosmetic Products Regulation, mandating high purity and safety documentation, elevates the baseline for market entry, creating demand for certified, premium-grade allantoin in skin care.
- 'Soothing' Formulations:Rising consumer preference for cosmetic products with soothing and healing properties, particularly in the dermo-cosmetic segment, directly boosts volume demand for allantoin in creams and lotions.
- Asian Cosmetic Hubs:Advanced cosmetic manufacturing in South Korea and Japan creates concentrated, high-volume offtake for allantoin, as local brands incorporate it into sophisticated, multi-step skincare routines.
Market Restraints
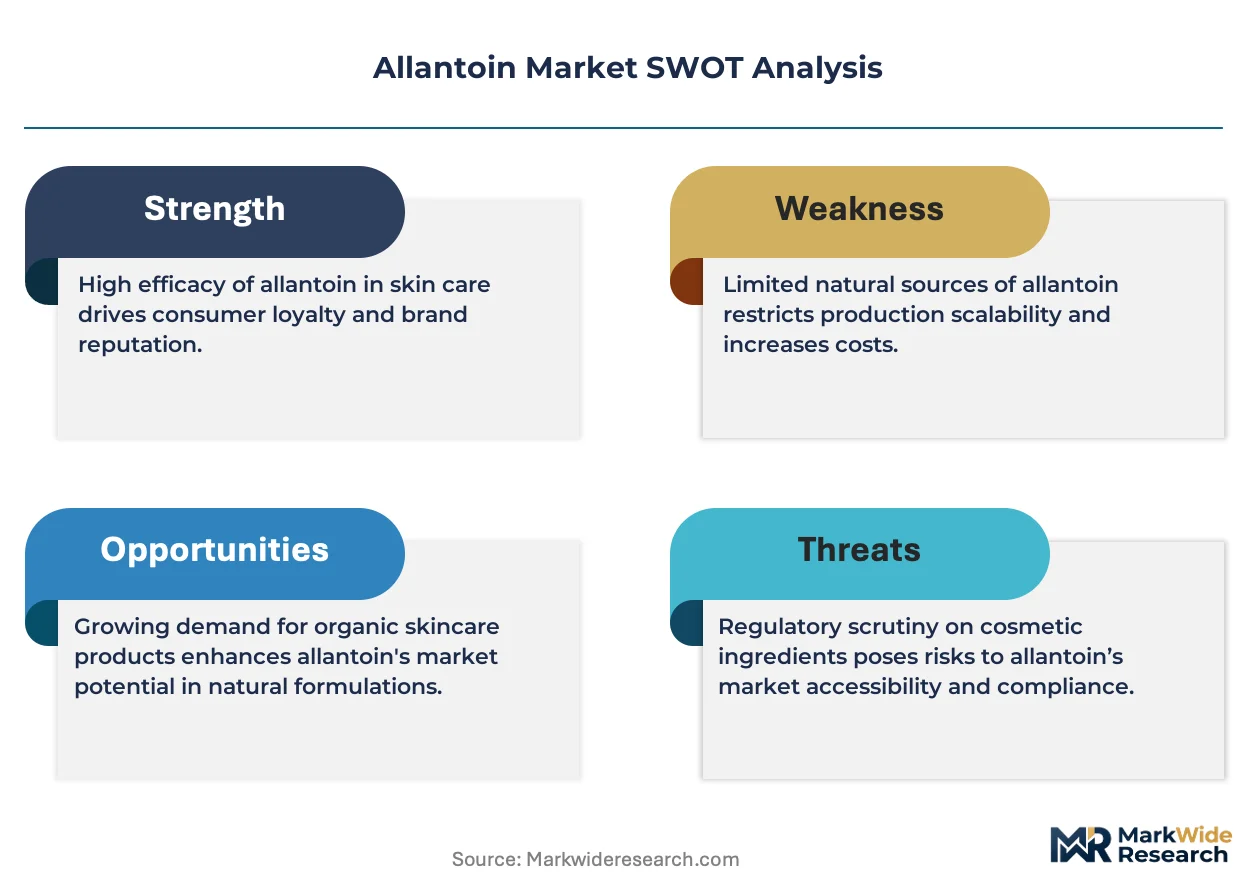
- Raw Material Volatility:The price and availability of glyoxylic acid, a key precursor for allantoin synthesis, are subject to fluctuations in the broader chemical market, impacting production cost stability for suppliers.
- Substitution Risk:The availability of alternative soothing and keratolytic agents like bisabolol and panthenol presents a substitution threat, particularly in price-sensitive, mass-market cosmetic formulations.
- Divergent Purity Standards:Navigating disparate purity and documentation requirements between the US FDA, EU's EMA, and China's NMPA creates compliance friction and increases market-entry costs for suppliers.
Strategic Opportunities
- Advanced Wound Care:Development of high-purity allantoin for specialized hydrogels and dressings in chronic wound management offers a high-margin opportunity beyond traditional cosmetics and basic first aid.
- Latin American Cosmetics:Expanding cosmetic manufacturing in countries like Brazil and Mexico presents an underpenetrated market for allantoin suppliers, as local consumer demand for sophisticated skin care grows.
- Microencapsulation Technology:Integrating allantoin into microencapsulated delivery systems for time-release effects in cosmetic products can create new product categories with enhanced efficacy claims and differentiation.
Industry Challenges
- Multi-Region Certification Burden:The operational challenge of simultaneously managing and maintaining compliance dossiers for the FDA, EMA, and NMPA extends product registration timelines and consumes significant internal resources.
- Multi-Source Qualification:Qualifying and integrating new regional suppliers into existing supply chains without compromising formulation consistency or regulatory standing is a significant logistical hurdle for personal care brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allantoin Market |
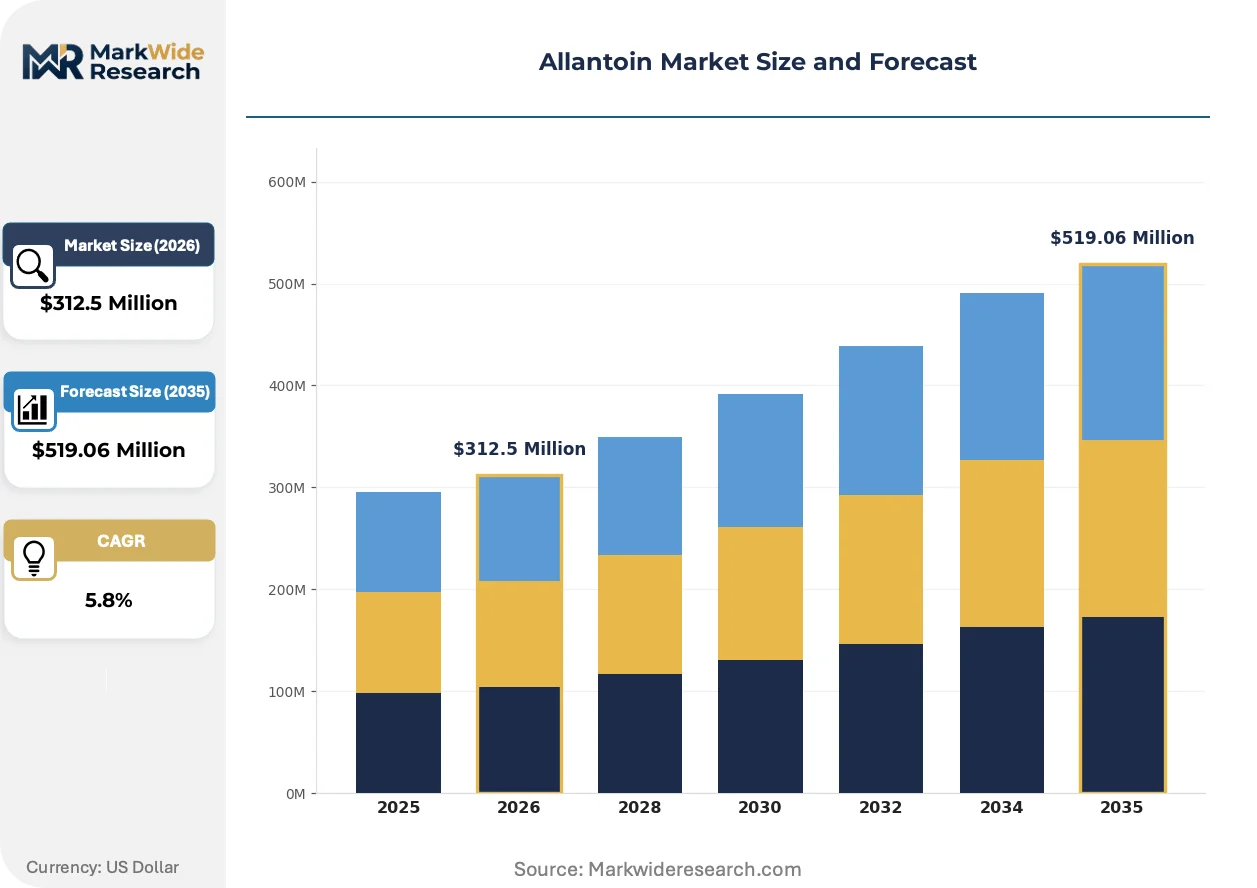
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Cosmetic Grade, Industrial Grade, Agricultural Grade Application: Skin Care, Hair Care, Oral Care, Wound Healing, Veterinary Care End User Industry: Personal Care Manufacturers, Pharmaceutical Companies, Agrochemical Companies, Veterinary Clinics Form: Powder, Liquid, Granules, Tablets |
| Companies Covered | Symrise, Lonza Group, BASF, Allantoin Chemical, Wuhan Biochemicals, Evonik Industries, Ashland Inc., Croda International, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allantoin Market Strategic Shifts & Innovations
Innovations in material science are meeting new regulatory benchmarks and evolving consumer behaviors. These forces are compelling a re-evaluation of allantoin's role, from a simple additive to a performance-critical ingredient in specialized formulations.
Bio-fermentation is emerging as a sustainable method for producing allantoin, offering an alternative to traditional chemical synthesis. Cosmetic brands with a strong "green" or "natural" marketing focus are the primary adopters of this technology. The availability of a bio-derived grade is electrifying the raw material sourcing debate, creating a new axis of competition based on origin and sustainability claims.
China's updated Cosmetic Supervision and Administration Regulation (CSAR) imposes stricter requirements for ingredient safety information and efficacy claim substantiation. This regulation compels suppliers to generate more extensive toxicological and clinical data for allantoin to gain market access. The skin care segment targeting the Chinese market is most affected, pushing brands to partner with suppliers who can provide comprehensive NMPA-compliant dossiers.
A move away from exclusive, long-term contracts toward a diversified, multi-sourcing procurement strategy is becoming standard for personal care manufacturers. This model reduces dependency on single large-scale producers and creates openings for agile, regional suppliers with specialized certifications. This pattern is most prominent among mid-sized cosmetic brands in Europe and North America seeking greater supply chain resilience.
Allantoin Market Segmentation
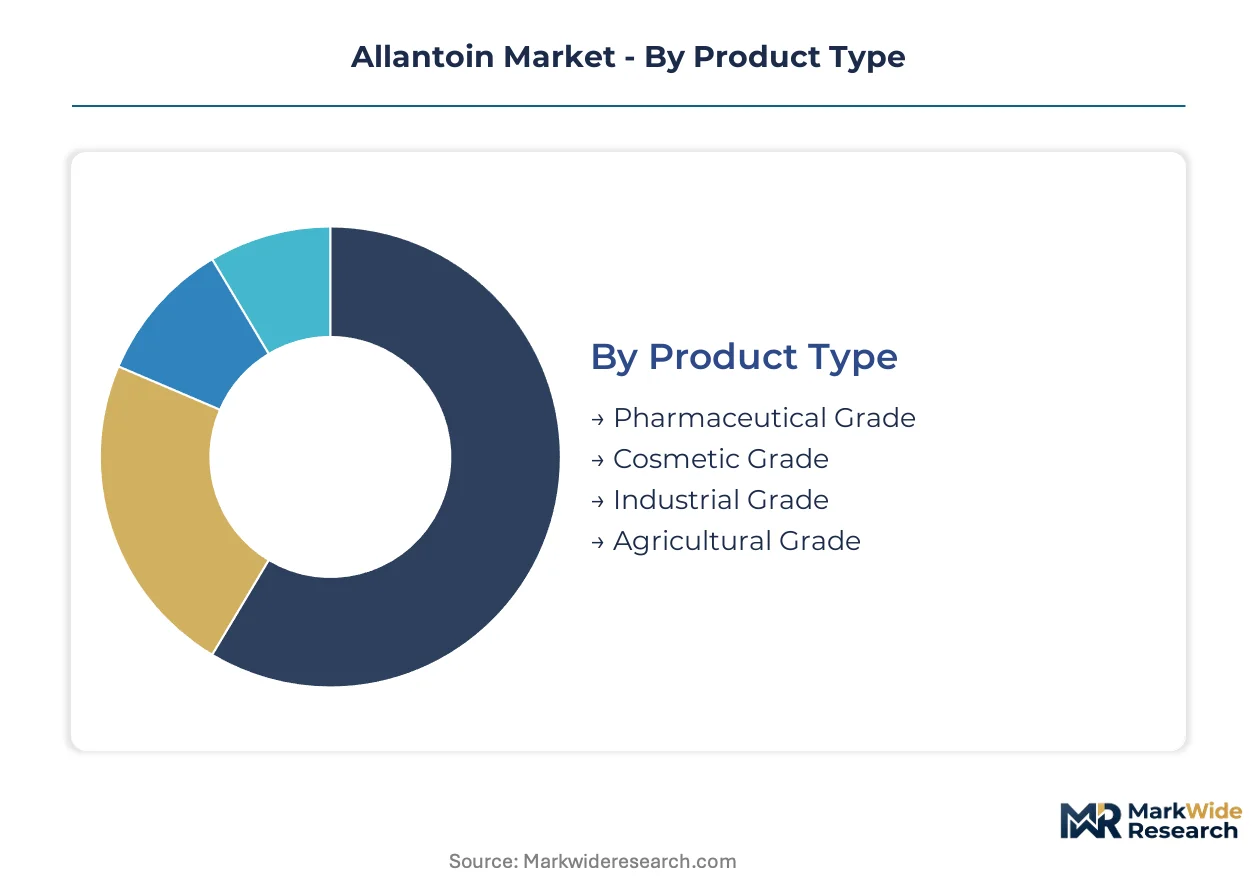
The Allantoin market's segmentation reflects diverse purity requirements and application-specific demands across various end-use sectors. Understanding these distinct market segments provides clarity on where value creation and competitive differentiation are most pronounced for suppliers and manufacturers.
Product Type:
The transition from commodity-grade materials to specialized purities drives procurement decisions within the allantoin product type segment.
- Cosmetic Grade:This grade of allantoin meets stringent purity standards for topical skin and hair care formulations. Its extensive use in soothing and healing creams, lotions, and shampoos contributes to its dominant market share, particularly in Asian cosmetic hubs like South Korea.
- Pharmaceutical Grade:Characterized by exceptional purity and rigorous testing, this allantoin is crucial for wound healing applications, specialized dermatological treatments, and oral care products. Lonza Group leverages its pharmaceutical background to offer high-purity grades for these essential medical uses.
- Industrial Grade:This allantoin variant is typically used in non-personal care applications where purity requirements are less stringent. It finds utility in various chemical processes and formulations outside of human contact products.
- Agricultural Grade:Tailored for agricultural applications, this grade supports plant growth and protection formulations. Its usage helps improve crop resilience and yield in specific farming contexts.
Volume placements concentrate in Cosmetic Grade; the faster expansion belongs to Pharmaceutical Grade.
Application:
The diverse functional properties of allantoin define its application landscape, with specific end-uses driving distinct demand profiles.
- Skin Care:Allantoin's keratolytic, moisturizing, and soothing properties make it a foundational ingredient in a vast array of skin care products. Consumer preference for dermo-cosmetic formulations, especially in Europe, directly boosts demand for allantoin in creams and lotions.
- Wound Healing:Specialized allantoin formulations are critical for advanced wound care products, including hydrogels and dressings. This segment offers higher margins due to the stringent purity and efficacy requirements for medical applications.
- Hair Care:In hair care products, allantoin contributes to scalp health and conditioning. It is incorporated into shampoos, conditioners, and treatments to soothe irritated scalps and improve hair texture.
- Oral Care:Allantoin is used in certain toothpastes and mouthwashes for its soothing and healing effects on oral tissues. Its inclusion supports gum health and reduces irritation in sensitive mouths.
- Veterinary Care:This application segment utilizes allantoin in topical treatments for animal skin conditions and wound management. Veterinary clinics incorporate it into specialized balms and creams for pet health.
The dominant share belongs to Skin Care, while Wound Healing exhibits the steepest expansion trajectory.
End User Industry:
The structure of allantoin demand is primarily shaped by the specific operational needs and regulatory environments of its key end-user industries.
- Personal Care Manufacturers:These companies, ranging from large multinationals to mid-sized cosmetic brands, represent the largest consumers of allantoin. Their demand is driven by innovation in skin care and hair care, particularly in South Korea and Japan.
- Pharmaceutical Companies:Requiring high-purity allantoin for therapeutic applications, these firms focus on wound healing, dermatological preparations, and specific oral care products. Regulatory compliance with bodies like the US FDA and EU's EMA is paramount for this segment.
- Agrochemical Companies:These businesses incorporate allantoin into various agricultural formulations to enhance plant health and stress resistance. Their procurement patterns are tied to seasonal farming cycles and crop protection needs.
- Veterinary Clinics:Utilizing allantoin in medicinal and dermatological products for animals, these clinics represent a niche but consistent demand segment. Their purchasing decisions are often based on product efficacy and supplier reliability.
Personal Care Manufacturers drive the majority of revenue, with Pharmaceutical Companies showing significant growth potential.
Form:
The physical presentation of allantoin dictates its ease of integration into different manufacturing processes and final product formats.
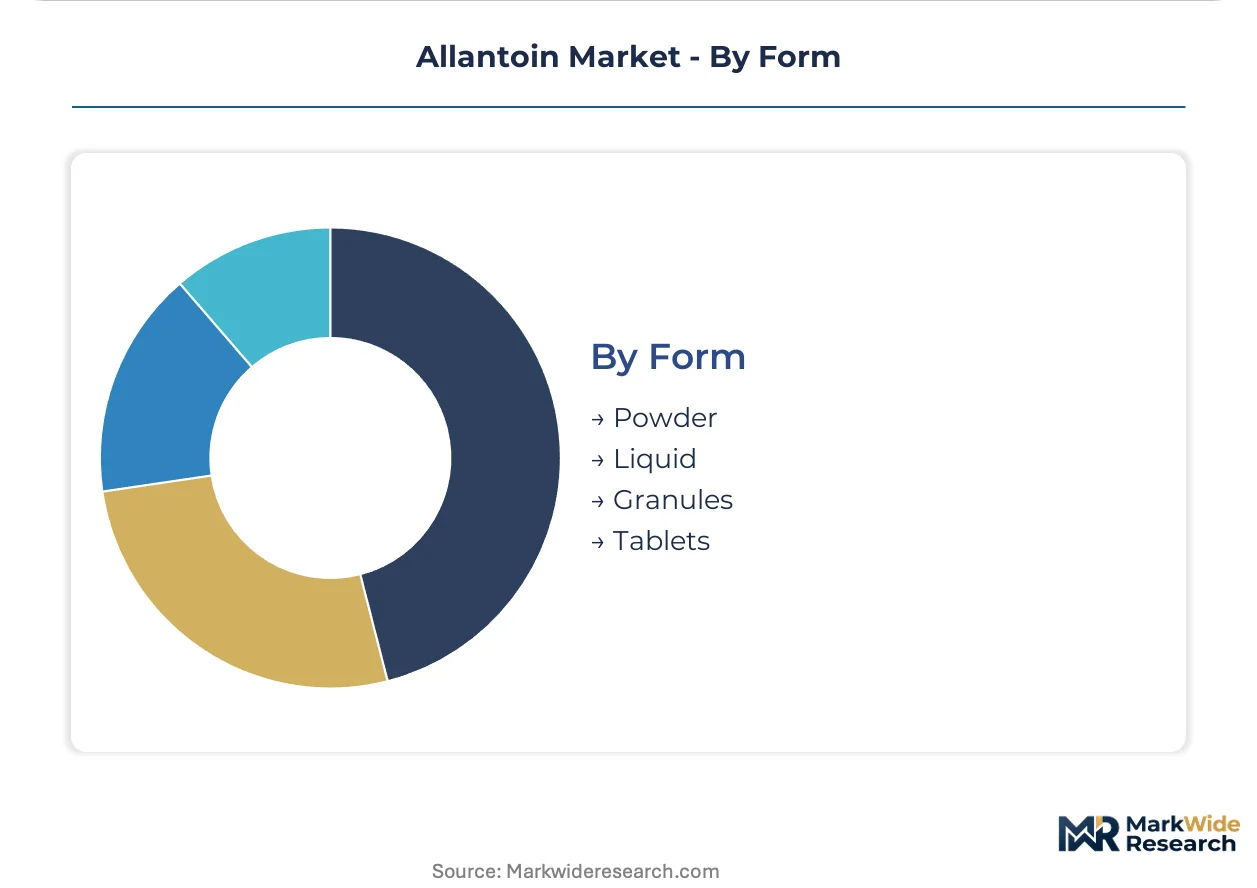
- Powder:The most common and versatile form, allantoin powder is widely used due to its ease of storage, transport, and precise dosing in formulations. It integrates well into both cosmetic and pharmaceutical manufacturing processes.
- Liquid:Liquid allantoin solutions offer convenience for manufacturers seeking to streamline mixing and dispersion in certain liquid-based formulations. This form is particularly useful in large-scale cosmetic production for quick incorporation.
- Granules:Granular allantoin provides a dust-free alternative to powder, improving handling safety and reducing airborne particles during manufacturing. This form is preferred in facilities with strict environmental controls.
- Tablets:Allantoin in tablet form is typically found in specific oral care or pharmaceutical applications where precise, pre-measured dosages are required. This format ensures consistency for consumers or medical practitioners.
Powder remains the foundational format, while Liquid is gaining traction for specific delivery needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive chemical manufacturing underpins global allantoin supply. Its domestic market for personal care and pharmaceuticals is expanding significantly. This creates a dual role for the country in the allantoin ecosystem, serving both as a major producer and consumer.
China
China's skin care formulations and pharmaceutical applications drive substantial allantoin consumption. The NMPA and CSAR impose rigorous safety and efficacy requirements for cosmetic ingredients. Cities like Guangzhou and Shanghai lead in cosmetic ingredient production and domestic market consumption.
South Korea
South Korea's advanced cosmetic manufacturing and innovative skincare routines fuel high-volume allantoin offtake. The MFDS ensures product safety and quality standards for cosmetic ingredients. Seoul and Gyeonggi Province house major cosmetic brands and ingredient formulators.
Germany
European dermo-cosmetic brands and pharmaceutical companies seek high-purity allantoin from suppliers in Germany. The EU's Cosmetic Products Regulation and EMA guidelines dictate strict ingredient compliance. Chemical parks in Ludwigshafen and Leverkusen support specialized allantoin production and research.
United States
United States personal care manufacturers and wound healing product developers require diverse allantoin grades. The US FDA oversees purity and safety standards for both cosmetic and pharmaceutical uses. New Jersey and California host significant cosmetic and pharmaceutical research and manufacturing hubs.
Brazil
Expanding domestic cosmetic manufacturing and growing personal care markets drive allantoin procurement in Brazil. ANVISA establishes health surveillance and ingredient registration protocols for cosmetic products. São Paulo's industrial regions are centers for cosmetic production and ingredient distribution.
Allantoin Market Key Industry Players
Global majors compete with regional champions across product purity and regulatory compliance. The market structure exhibits a tiered consolidation, with large chemical conglomerates dominating the high-volume, standard-grade segments. Specialized ingredient suppliers focus on premium pharmaceutical and cosmetic grades, often leveraging proprietary synthesis methods for differentiation. Strategic competitive moves include portfolio diversification into adjacent active ingredients, geographic expansion into emerging markets, and technology licensing to enhance product efficacy.
Within the integrated chemical and life science companies tier, Lonza Group and Symrise exemplify providers offering high-purity allantoin. Lonza Group leverages its pharmaceutical background, anchoring its position in wound healing applications with specialized grades. Symrise occupies a strong position with its comprehensive portfolio of cosmetic active ingredients, catering to diverse personal care needs, particularly in advanced formulations. BASF, a large chemical conglomerate, represents another major player, utilizing its vast manufacturing scale for broader market reach across various industrial and cosmetic applications globally.
| Leading Market Players |
|---|
| Symrise |
| Lonza Group |
| BASF |
| Allantoin Chemical |
| Wuhan Biochemicals |
| Evonik Industries |
| Ashland Inc. |
| Croda International |
| Merck KGaA |
| Others |
Cost & Logistics Intelligence
Glyoxylic acid volatility, a key precursor, directly impacts allantoin production costs, which then influence pricing across cosmetic and pharmaceutical grades. Tightening regulatory standards further segment the market by purity, creating distinct price points.
Pricing Analysis
Service bundling, including comprehensive documentation and certification support, defines premium allantoin pricing for specialized pharmaceutical applications. The dominant pricing model remains contract-based long-term offtake for large-volume customers, with transactional pricing for smaller, spot purchases. Price differentiation stems primarily from purity grade, such as cosmetic versus pharmaceutical, and specific regulatory certifications like NMPA or EMA compliance. Pricing pressure increases on commodity grades due to multi-source procurement strategies, while high-purity pharmaceutical grades command significantly higher margins. Mass-market cosmetic formulators exhibit high price sensitivity, unlike specialized wound care product developers who prioritize efficacy.
Supply Chain Analysis
Regional distribution centers, particularly in Europe and Asia, facilitate efficient delivery of allantoin to key manufacturing hubs. Geographic supply concentrates heavily in China for bulk production and in Germany for specialized high-purity grades. The supply chain significantly relies on the availability of glyoxylic acid, its primary precursor. Single-source vulnerability for specialized precursors represents a structural risk. Distribution primarily occurs through direct sales to large personal care and pharmaceutical manufacturers, complemented by regional distributors serving smaller brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The allantoin market is entering a technology-transition phase, with bio-fermentation emerging as a sustainable alternative to traditional chemical synthesis processes. This shift is redefining sourcing preferences and competitive dynamics across the personal care industry.
For Market Incumbents: Anticipate increased competition from agile regional specialists leveraging bio-fermentation technologies. Incumbents should invest in advanced purification processes and NMPA-compliant dossier generation to maintain market access in China. Securing long-term supply agreements for high-purity grades and exploring vertical integration into glyoxylic acid synthesis can mitigate raw material volatility risks. Lonza Group, for instance, could deepen its pharmaceutical-grade offerings.
For New Entrants and Emerging Players: Launch via direct sales channels targeting mid-sized cosmetic brands in Latin America, particularly Brazil and Mexico. New entrants should focus on bio-fermented allantoin, emphasizing sustainability and natural origin claims to differentiate. Developing specialized, high-purity grades for advanced wound care offers a high-margin entry point. Offering comprehensive NMPA-compliant documentation provides a strong go-to-market angle in Asia.
For Investors and Strategic Acquirers: Increased M&A activity among mid-sized cosmetic ingredient suppliers is the leading indicator that market consolidation and specialization are accelerating. The allantoin market exhibits long-term viability, driven by sustained demand for skin soothing and healing formulations, coupled with regulatory-driven premiumization. Acquisition targets include regional specialists possessing proprietary bio-fermentation technologies or robust multi-region regulatory compliance dossiers. Monitor the adoption rate of microencapsulation technologies for enhanced delivery systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Bio-Fermented Allantoin | This move supports sustainability claims and meets rising consumer demand for natural cosmetic ingredients. |
| Invest in Multi-Region Regulatory Compliance | Ensuring NMPA and EMA certifications unlocks market access and premium pricing for specialized grades. |
| Secure Long-term Glyoxylic Acid Supply Contracts | This action mitigates raw material price volatility and ensures production stability for allantoin manufacturers. |
| Launch Microencapsulated Allantoin Formulations | This innovation creates new product categories with enhanced efficacy and controlled release for skin care. |
| Geographic Expansion into Latin American Markets | Targeting Brazil and Mexico capitalizes on growing domestic cosmetic manufacturing and consumer demand. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing foundational market insights. Primary research involved interviews with R&D directors, procurement leads at personal care manufacturers, and regulatory affairs specialists. This approach combined bottom-up volume sizing with top-down market validation, ensuring data integrity. Secondary sources included NMPA filings, EMA submissions, and company annual reports.
Data-stream reconciliation involved cross-referencing historical market performance with future growth catalysts across the analysis window. Volume and value outputs were triangulated across product type, application, end-user industry, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected impacts of consumer preference shifts. Regulatory stringency and raw material availability served as key forecast inputs.
Raw material price volatility, new regulatory mandates, and unexpected substitution by alternative ingredients are the dominant revision risks for allantoin market forecasts. These forecasts reflect assumptions regarding market dynamics and technological advancements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Natural Ingredient Insect Repellent Market
Specialty Chemicals
Global Specialty Fuel Additives Market
Specialty Chemicals
Monoaluminum Phosphate Market
Specialty Chemicals
Crystal Hard Wax Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Cellulose Esters and Ethers Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Global Non-Phthalate Plasticizers Market
Specialty Chemicals
Dimethyl Silicone Market
Specialty Chemicals
1,2 Hexanediol Market
Specialty Chemicals
Bemotrizinol Market
Specialty Chemicals
Cholesteryl Isostearate Market
Specialty Chemicals
Cellulose Ether and Derivatives Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Global Flame Retardants Market
Specialty Chemicals
Europe Non-Phthalate Plasticizers Market