
 Global Anti-Static Agents Market | 2026-2036
Global Anti-Static Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Static Agents Market Analysis
REACH is rebalancing the cost-of-entry calculus for anti-static agent suppliers entering European plastics and electronics value chains. Croda International plc leverages its bio-based surfactant portfolio to navigate tightening substance restrictions. BASF sustains formulation leadership through integrated alkoxylate production in Ludwigshafen. Evonik Industries AG anchors specialty amine supply for high-performance polymer applications.
Anti-static agents are surface-active compounds—typically quaternary ammonium salts, ethoxylated amines, or glycerol esters—applied at 0.1% to 3.0% loading to dissipate electrostatic charge from insulating polymer matrices. Liquid formulations dominate packaging and film extrusion for their ease of metering and dispersion, while powder grades occupy textile fiber finishing where aqueous systems disrupt downstream drying economics. The plastics application segment leads volume as automotive interior specifications tighten static decay thresholds, and hybrid technology approaches are gaining traction where single-mechanism chemistries fail multi-substrate lines.
The EPA regulates volatile organic compound emissions from coating applications containing solvent-borne anti-static additives, while ECHA's SVHC candidate list pressures substitution of long-chain alkyl dimethyl benzyl ammonium chlorides. China's MEE enforces discharge limits on surfactant manufacturing that reshape regional cost structures. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation cycles.
Market Dynamics
REACH substance restrictions and EPA volatile organic compound rules are forcing simultaneous reformulation across multiple polymer application lines, compressing supplier R&D cycles and redrawing competitive boundaries between bio-based and conventional chemistry portfolios.
Growth Catalysts
- Semiconductor fabrication expansion:Electronics manufacturers in Taiwan, South Korea, and China are scaling cleanroom polymer consumption, pulling high-purity anti-static grades into wafer handling and packaging substrates.
- Automotive interior electrification:Cabin air quality standards and touch-sensitive surface proliferation in electric vehicles are tightening static decay specifications for dashboard and seating materials.
- MEE discharge enforcement:China's Ministry of Ecology and Environment surfactant manufacturing limits are accelerating consolidation toward compliant producers with captive wastewater treatment.
Market Restraints
- Fatty acid feedstock volatility:Palm oil and coconut oil price swings directly compress margins on glycerol ester formulations, forcing hedging costs onto mid-tier suppliers.
- Quaternary ammonium substitution pressure:ECHA's SVHC candidate list inclusion of long-chain alkyl dimethyl benzyl ammonium chlorides is triggering forced reformulation cycles ahead of sunset dates.
- Specialty amine supply concentration:High-performance polymer applications depend on concentrated European and Japanese amine producers, creating single-source vulnerability.
Strategic Opportunities
- India precision manufacturing emergence:PLI scheme incentives for electronics and automotive component production are building virgin demand for anti-static packaging and processing aids.
- Textile fiber bio-based transition:Sustainable apparel mandates in Germany and France are opening specification windows for plant-derived ethoxylated amines in synthetic fiber finishing.
- Hybrid mechanism formulations:Converging ionic and non-ionic chemistries are addressing multi-substrate processing lines where single-mechanism agents fail.
Industry Challenges
- Cross-jurisdiction compliance staffing:Simultaneous REACH, EPA, and GB standard tracking requires dedicated regulatory affairs capacity that strains mid-size formulation houses.
- Legacy extrusion line integration:Powder-to-liquid system conversions for textile applications demand capital outlays that conflict with depreciation schedules.
- Static decay test standard divergence:Incompatible measurement protocols between IEC, ASTM, and JIS methods complicate universal product certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Static Agents Market |
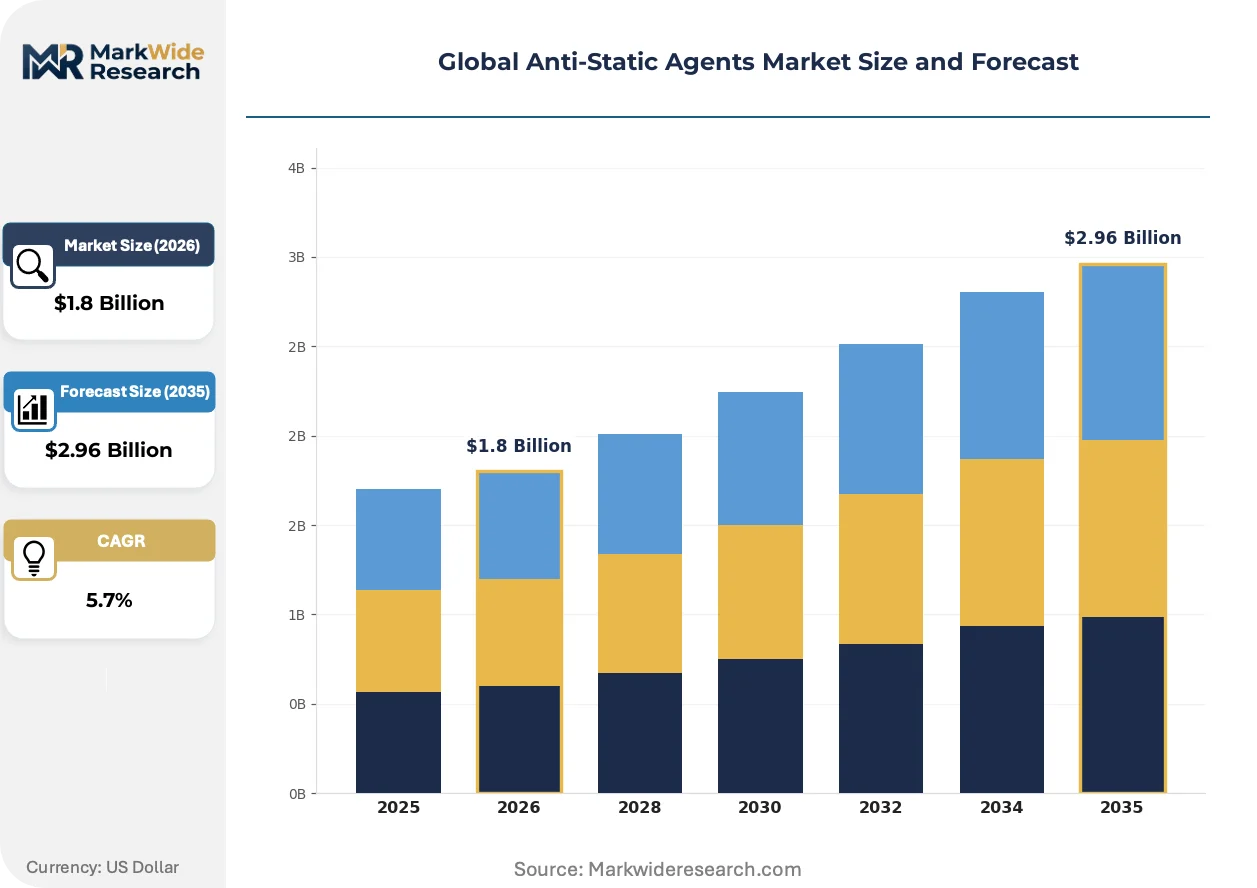
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Paste Application: Plastics, Coatings, Textiles, Electronics End User: Automotive, Healthcare, Packaging, Consumer Goods Technology: Chemical, Biological, Physical, Hybrid |
| Companies Covered | Croda International plc, BASF, Clariant, Adeka Corporation, Ampacet Corporation, 3M, Evonik Industries AG, Arkema, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Static Agents Market Emerging Trajectories
Formulation chemistry is bifurcating between high-performance synthetic routes for semiconductor applications and bio-derived pathways for consumer-facing plastics, with regulatory compliance serving as the primary sorting mechanism between the two tracks.
Polymer-compatible glycerol ester formulations are decentralizing supply chain risk for packaging film producers. Food-contact approved grades from Malaysian and Indonesian oleochemical feedstocks are capturing share in European flexible packaging. This chemistry is decentralizing procurement patterns away from petrochemical-dependent quaternary ammonium suppliers toward integrated oleochemical producers with backward control over plantation supply.
EPA volatile organic compound emission rules for coating applications are compressing solvent-borne additive viability. Manufacturers are pivoting toward aqueous and 100% solid concentrate formats to maintain compliance. Electronics packaging lines in the United States are most affected, with California and Texas fabrication clusters driving early adoption of water-based metering systems.
Specification consolidation among automotive tier-one suppliers is compressing supplier qualification cycles. Buyers are unbundling anti-static performance from broader additive packages, creating direct procurement relationships with specialty chemical houses. This pattern is most visible in Germany's automotive interior supply chain, where Volkswagen and BMW sustainability scorecards now weight bio-based content above historical cost-per-kilogram metrics.
Global Anti-Static Agents Market Segmentation
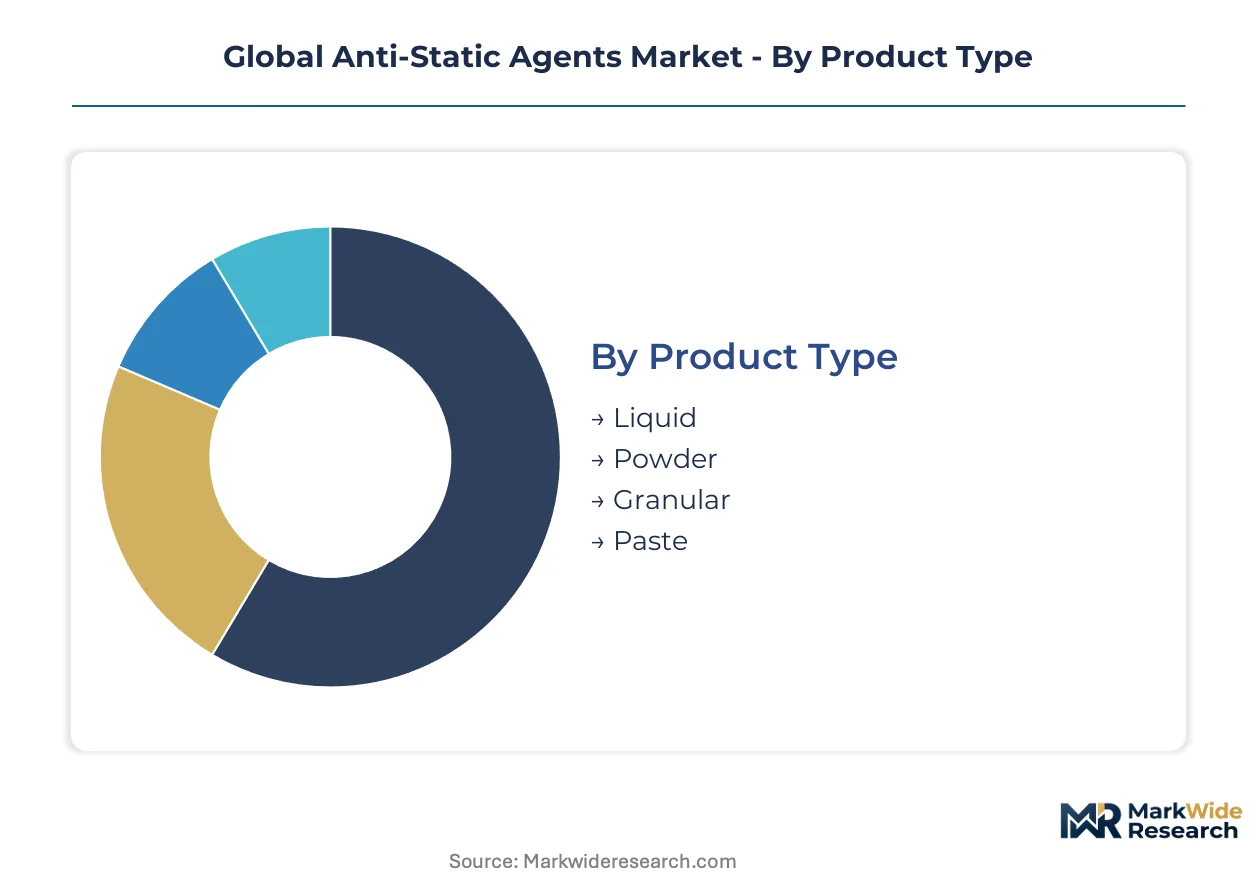
Anti-static agent procurement decisions pivot on formulation compatibility with substrate processing conditions and regulatory clearance requirements. Specification divergence across semiconductor, automotive, and medical end-uses fragments supplier portfolios into distinct certification tracks.
Product Type:
REACH SVHC restrictions and FDA food-contact approvals segment the certification burden: liquid grades face EPA volatile organic compound scrutiny, while powder formulations trigger OSHA respirable dust exposure protocols.
- Liquid:Ethoxylated amine and quaternary ammonium solutions dominate film extrusion and injection molding for their metering precision. Demand concentrates in German automotive interior supply chains where Volkswagen and BMW sustainability scorecards weight bio-based content above historical cost metrics. ECHA substance restrictions are accelerating substitution toward glycerol ester alternatives.
- Powder:Quaternary ammonium salt concentrates serve textile fiber finishing where aqueous systems disrupt downstream drying economics. Procurement clusters in China's Yangtze River Delta synthetic fiber production zones, with MEE discharge enforcement consolidating supply toward compliant producers with captive wastewater treatment.
- Granular:Dust-free masterbatch pellets integrate into high-throughput compounding lines serving packaging film producers.
- Paste:High-viscosity formulations target specialty coating applications requiring precise film thickness control.
Leading the category by volume: Liquid. Growing fastest: Powder.
Application:
Cost tier stratification separates premium semiconductor-grade chemistries from commodity packaging formulations, with price multiples exceeding 4x between the two bands.
- Plastics:Automotive interior electrification tightens static decay specifications for dashboard and seating materials. Cabin air quality standards in German electric vehicle production anchor procurement volumes for low-emission glycerol ester grades.
- Electronics:Wafer handling and packaging substrates demand parts-per-billion purity levels. Taiwan Semiconductor Manufacturing and Samsung Electronics fabrication expansion in Hsinchu and Pyeongtaek pulls high-purity anti-static grades into cleanroom polymer consumption.
- Coatings:Solvent-borne additive viability compresses under EPA emission rules, pivoting procurement toward aqueous concentrate formats.
- Textiles:Sustainable apparel mandates in Germany and France open specification windows for plant-derived ethoxylated amines in synthetic fiber finishing.
Highest margin capture: Electronics. Steepest expansion trajectory: Plastics.
End User:
Customer type determines volume contracting structures, with automotive tier-one suppliers unbundling anti-static performance from broader additive packages to create direct procurement relationships.
- Automotive:Touch-sensitive surface proliferation in electric vehicles tightens static decay thresholds. Tier-one interior suppliers in Stuttgart and Wolfsburg now weight bio-based content above historical cost-per-kilogram metrics.
- Packaging:Food-contact approved grades from Malaysian and Indonesian oleochemical feedstocks capture share in European flexible packaging, decentralizing procurement away from petrochemical-dependent suppliers.
- Healthcare:Sterile barrier applications demand FDA 21 CFR compliance for medical device packaging substrates.
- Consumer Goods:Personal electronics and appliance housings drive specification consolidation among Asian contract manufacturers.
Dominant procurement volume: Automotive. Gaining share fastest: Packaging.
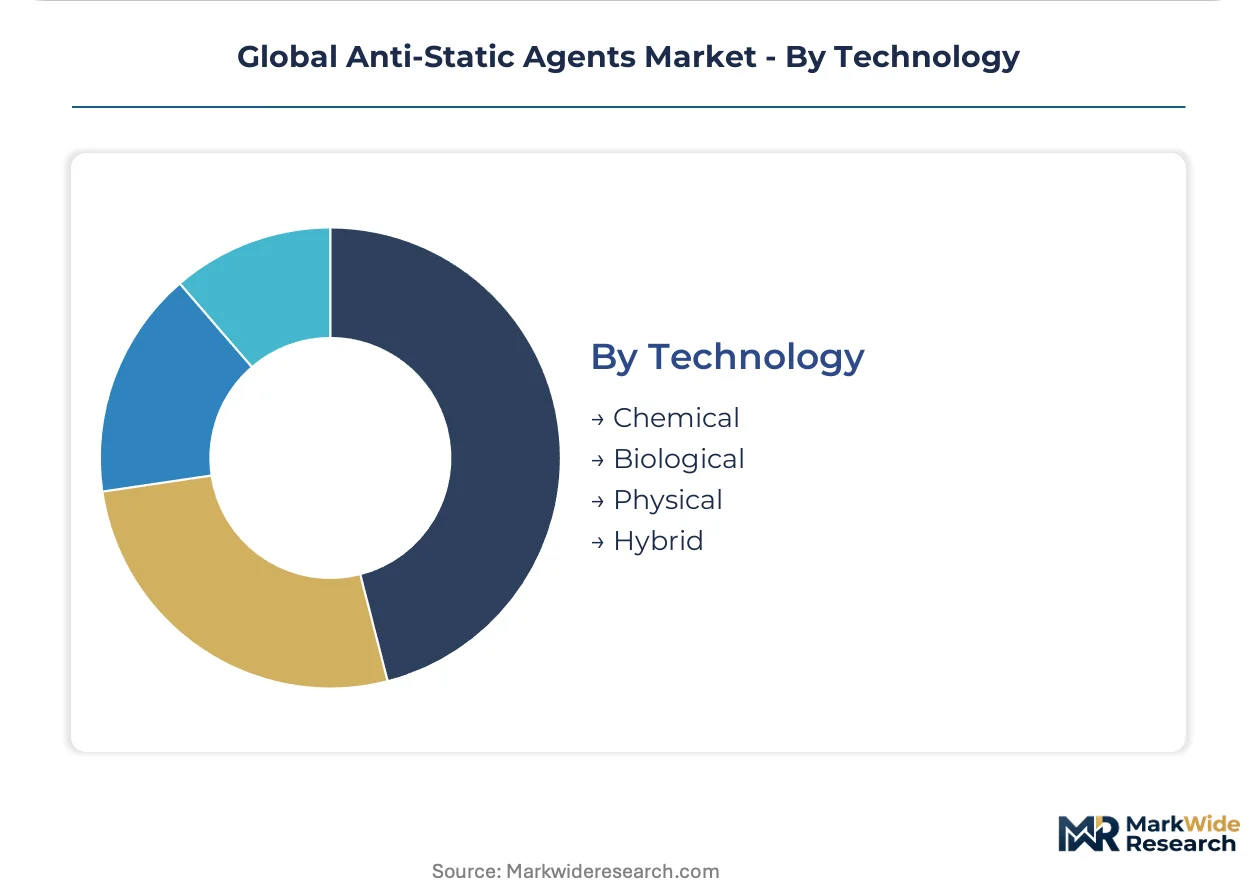
Technology:
Supply concentration in European and Japanese amine producers creates single-source vulnerability for high-performance polymer applications, while bio-based pathways decentralize toward integrated oleochemical producers.
- Chemical:Quaternary ammonium salts and ethoxylated amines sustain formulation leadership through integrated alkoxylate production. BASF's Ludwigshafen complex anchors European supply.
- Hybrid:Converging ionic and non-ionic chemistries address multi-substrate processing lines where single-mechanism agents fail. Electronics packaging lines in California and Texas fabrication clusters drive early adoption.
- Biological:Plant-derived glycerol esters from Malaysian and Indonesian oleochemical feedstocks navigate tightening REACH substance restrictions.
- Physical:Conductive filler dispersions serve applications where surface-active chemistries interfere with optical or electrical properties.
Technology maturity leader: Chemical. Steepest capability investment: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate semiconductor packaging demand, pulling high-purity anti-static grades into wafer handling substrates. German automotive clusters anchor European procurement for low-emission glycerol ester formulations. Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek fabrication corridors drive cleanroom polymer consumption across Asia-Pacific.
China
Semiconductor fabrication expansion in Shanghai and Wuxi pulls high-purity anti-static grades into wafer handling applications. The Ministry of Ecology and Environment enforces surfactant manufacturing discharge limits that reshape regional cost structures. Yangtze River Delta synthetic fiber production zones concentrate powder-grade procurement toward MEE-compliant producers with captive wastewater treatment.
Germany
Automotive interior electrification tightens static decay specifications for dashboard and seating materials in Stuttgart and Wolfsburg production corridors. REACH substance restrictions accelerate substitution away from long-chain alkyl dimethyl benzyl ammonium chlorides. BASF's Ludwigshafen complex anchors European alkoxylate supply for high-performance polymer applications.
United States
Electronics packaging lines in California and Texas fabrication clusters drive early adoption of water-based metering systems. EPA volatile organic compound emission rules compress solvent-borne additive viability in coating applications. Volkswagen and BMW sustainability scorecards now weight bio-based content above historical cost-per-kilogram metrics in German-owned US facilities.
Taiwan
Taiwan Semiconductor Manufacturing expansion in Hsinchu pulls high-purity anti-static grades into cleanroom polymer consumption. Local environmental regulators enforce discharge limits on surfactant manufacturing that reshape procurement patterns. Precision electronics clusters anchor demand for parts-per-billion purity specifications in wafer handling substrates.
South Korea
Samsung Electronics fabrication expansion in Pyeongtaek drives cleanroom polymer consumption for anti-static packaging substrates. National chemical management frameworks pressure substitution toward compliant formulation chemistries. Gyeonggi Province semiconductor corridors concentrate demand for specialty amine supply in high-performance polymer applications.
Global Anti-Static Agents Market Vendor Landscape
German producers anchor one tier; Japanese specialists hold concentrated positions in high-purity semiconductor grades. The vendor base separates into integrated petrochemical houses, bio-based oleochemical processors, and regional compounding specialists. Three strategic archetypes dominate: backward-integrated alkoxylate producers, plantation-controlled glycerol ester suppliers, and cleanroom-certified purity specialists. Competitive moves concentrate on M&A for regulatory-compliant formulation portfolios and capacity expansion in MEE-compliant Asian manufacturing zones.
Among European integrated chemical houses, BASF and Evonik Industries AG exemplify the alkoxylate production archetype with Ludwigshafen-based manufacturing complexes. Croda International plc represents the bio-based transition path through oleochemical surfactant portfolios. These three anchors illustrate how REACH compliance and EPA standards are redrawing competitive boundaries between synthetic and plant-derived chemistry tracks.
| Leading Market Players |
|---|
| Croda International plc |
| BASF |
| Clariant |
| Adeka Corporation |
| Ampacet Corporation |
| 3M |
| Evonik Industries AG |
| Arkema |
| Solvay |
| Others |
Supply Flow & Price Mechanics
German automotive tier-one suppliers concentrate procurement volumes for low-emission glycerol ester grades, anchoring contract-based long-term offtake structures that compress spot-market liquidity for mid-tier formulation houses. This buyer concentration feeds pricing power upstream toward REACH-compliant producers with captive alkoxylate capacity, while spot buyers absorb volatility from fatty acid feedstock swings.
Pricing Analysis
Short lead-time premiums dominate semiconductor-grade procurement, with Taiwan Semiconductor Manufacturing and Samsung Electronics fabrication clusters paying substantial markups for parts-per-billion purity specifications delivered on compressed schedules. Three-tier pricing structure across premium, standard, and economy levels separates electronics-grade ethoxylated amines from automotive interior formulations and commodity packaging glycerol esters. Cost compression in standard-tier glycerol ester formulations is intensifying because Malaysian and Indonesian oleochemical feedstock volatility transfers directly to margin structures. Packaging film producers exhibit highest price sensitivity due to unbundled procurement and volume contracting, while wafer handling substrate buyers prioritize specification compliance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German automotive interior supply chains, bypassing traditional distribution layers for glycerol ester formulations. Manufacturing concentrates in Germany, China, and Malaysia, with Ludwigshafen-based alkoxylate complexes, Yangtze River Delta surfactant producers, and Malaysian oleochemical processors anchoring regional supply. Raw material flows draw from palm oil and coconut oil plantations, ethylene oxide feedstocks, and specialty amine precursors. Single-source vulnerability in European and Japanese amine supply creates structural risk for high-performance polymer applications. Distribution runs through integrated chemical houses for large-volume accounts, with regional compounding specialists serving fragmented textile and coating end-uses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance restrictions function as a cost-of-compliance moat, elevating capital requirements for formulation portfolios and consolidating competitive advantage among pre-certified European producers. ECHA's SVHC candidate list pressures substitution timelines that compliant players have already absorbed.
For Market Incumbents: Anchor formulation leadership through backward integration into captive alkoxylate production and MEE-compliant manufacturing capacity in China's Yangtze River Delta. Bio-based oleochemical entrants threaten glycerol ester margins; defend through sustainability certification investments that preempt Volkswagen and BMW scorecard requirements. Prioritize hybrid mechanism R&D to capture multi-substrate processing lines where single-chemistry suppliers fail. For New Entrants and Emerging Players: India's precision manufacturing ecosystem offers virgin demand from PLI scheme incentives for electronics and automotive component production, with limited incumbent certification presence. Target textile fiber finishing in Germany and France where sustainable apparel mandates open specification windows for plant-derived ethoxylated amines. Pursue direct technical service partnerships with tier-two automotive suppliers seeking scorecard compliance without incumbent pricing premiums. For Investors and Strategic Acquirers: The window for entry favors plantation-controlled glycerol ester suppliers with REACH pre-certification and Malaysian or Indonesian feedstock security. Long-term viability rests on regulatory compliance durability rather than commodity cost cycles. Watch ECHA sunset date announcements for long-chain alkyl dimethyl benzyl ammonium chlorides as inflection indicators for forced substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkoxylate Production | BASF's Ludwigshafen complex demonstrates margin defense through captive ethylene oxide conversion. |
| MEE-Compliant Capacity Expansion | China's Ministry of Ecology and Environment enforcement consolidates supply toward wastewater-treatment-equipped producers. |
| Hybrid Mechanism Formulation Development | Converging ionic and non-ionic chemistries address California and Texas electronics packaging line complexity. |
| Plantation-Controlled Oleochemical Security | Malaysian and Indonesian feedstock backward integration navigates REACH substance restrictions. |
| Direct Technical Service Partnerships | Unbundled procurement from German automotive tier-one suppliers creates channel access for specialty houses. |
Methodological Framework
Multi-period observation of semiconductor fabrication expansion, REACH regulatory amendment timelines, and fatty acid feedstock price movements anchored the trend analysis, supplemented by interviews with specialty chemical plant managers, automotive tier-one procurement leads, electronics packaging engineers, and distribution channel partners. Secondary validation drew from ECHA SVHC candidate list updates, EPA volatile organic compound rulemakings, China MEE discharge enforcement records, and customs trade data for surfactant precursor flows. Bottom-up volume modeling across formulation grades triangulated against top-down value projections from integrated chemical house disclosures.
Input-output matrices structured demand as a function of plastics processing volumes, electronics cleanroom polymer consumption, and textile fiber production across the analysis window. Segmentation dimensions modeled included formulation type, application substrate, end-use industry vertical, purity grade tier, and regional regulatory cluster. CAGRs derived from slope-intercept fitting of historical volume trajectories adjusted for substitution elasticity parameters. Forecast inputs incorporated semiconductor capital expenditure cycles and automotive electrification content-per-vehicle assumptions.
Revisions become necessary when ECHA accelerates SVHC sunset timelines, EPA expands volatile organic compound rules to additional coating categories, or MEE enforcement intensity shifts surfactant manufacturing cost structures in China. Forecasts reflect assumptions about regulatory compliance durability and feedstock price mean-reversion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Distarch Phosphate Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Global Foam Blowing Agents Market
Specialty Chemicals
Methyl Salicylate Market
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
Dimethicone Market
Specialty Chemicals
Zinc Ricinoleate Market
Specialty Chemicals
Silver Sulfate Market
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
Fatty Acid Methyl Ester Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
UV Light Stabilizers Market
Specialty Chemicals
Cellulose Esters and Ethers Market
Specialty Chemicals
4-ADPA Market
Specialty Chemicals
Barium Sulfate Market
Specialty Chemicals
Magnesium Gluconate Market