
 4-Benzoylbutyric Acid Market | 2026-2036
4-Benzoylbutyric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
4-Benzoylbutyric Acid Market Outlook
Pharmaceutical-grade specification tiers is collapsing the gap between commodity chemical suppliers and qualified drug-intermediate producers. Dayang chem (Hangzhou) Co. Ltd. leverages its Hangzhou manufacturing base to serve domestic and export pharmaceutical clients. Jinan Haohua Industry Co. Ltd. anchors northern China's specialty chemical corridor with dedicated intermediate production lines. Tokyo Chemical Industry Co. Ltd. differentiates through its Japan-certified reagent catalog that extends into high-purity custom synthesis.
4-Benzoylbutyric acid is a gamma-keto carboxylic acid with the molecular formula C11H12O3, synthesized primarily via Friedel-Crafts acylation of butyric acid derivatives followed by oxidation, serving as a critical building block in peptide coupling reactions and polymer modification. The pharmaceutical manufacturing application leads value generation due to stringent qualification requirements that lock in supplier relationships, while polymer production represents the fastest-growing application as biodegradable material developers seek novel functional monomers. Pharmaceutical companies dominate end-user demand through direct procurement contracts, though academic institutions increasingly compete for limited high-purity lots in early-stage research.
REACH registration obligations in Europe and FDA intermediate guidance in the United States shape supplier qualification burdens, forcing smaller producers toward distributor channels or toll manufacturing arrangements. China's NMPA alignment with ICH Q7 guidelines tightens documentation standards for export-oriented facilities. Stakeholders must monitor regulatory divergence between major import jurisdictions to avoid stranded inventory or costly re-qualification cycles.
Market Dynamics
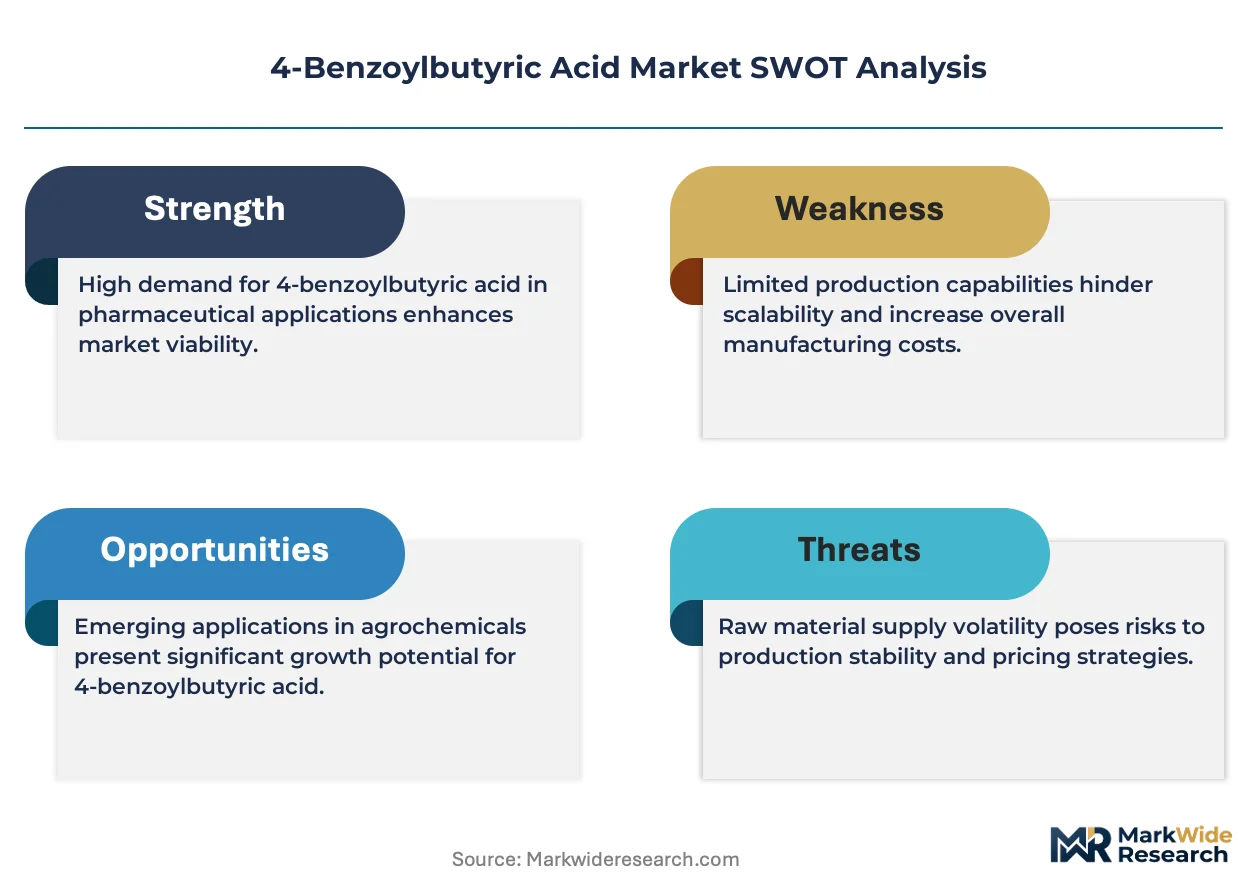
Pharmaceutical-grade qualification barriers are consolidating supplier tiers, as peptide synthesis pipelines multiply and REACH purity benchmarks force commodity producers toward toll manufacturing or exit.
Growth Catalysts
- Peptide synthesis expansion:Drug developers scaling GLP-1 and oligonucleotide programs require gamma-keto acid building blocks in multi-kilogram batches, locking in qualified intermediate suppliers.
- Biodegradable polymer mandates:EU Green Deal targets for packaging recyclability accelerate functional monomer demand from polyhydroxyalkanoate and polylactic acid developers seeking novel comonomers.
- REACH registration completion:ECHA dossier acceptance for 4-benzoylbutyric acid removes import friction for European pharmaceutical formulators, opening validated supply channels.
Market Restraints
- Friedel-Crafts feedstock volatility:Aluminum chloride and butyric acid derivatives face petrochemical price swings that compress toll manufacturer margins during contract renegotiations.
- China supply concentration:Custom synthesis capacity clusters in Zhejiang and Shandong provinces, exposing buyers to single-country logistics disruptions and NMPA inspection backlogs.
- Fluorinated solvent substitution:Dichloromethane restrictions under REACH Annex XVII push developers toward less efficient acylation media, lengthening batch cycles.
Strategic Opportunities
- India CDMO penetration:PLI scheme incentives for active pharmaceutical ingredient manufacturing attract investment in gamma-keto acid synthesis capabilities at Hyderabad and Ahmedabad clusters.
- Continuous flow acylation:Microreactor technology convergence with inline spectroscopic monitoring enables real-time impurity control for high-purity peptide-grade material.
- Academic direct sourcing:Research institutions bypass distributors through e-procurement platforms, creating captive channels for gram-scale high-purity lots.
Industry Challenges
- Analytical method transfer:FDA intermediate guidance requires validated impurity profiling protocols that small-scale producers lack resources to develop independently.
- Multipurpose reactor qualification:Shared equipment for custom synthesis demands extensive cleaning validation between campaigns, extending campaign changeover timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 4-Benzoylbutyric Acid Market |
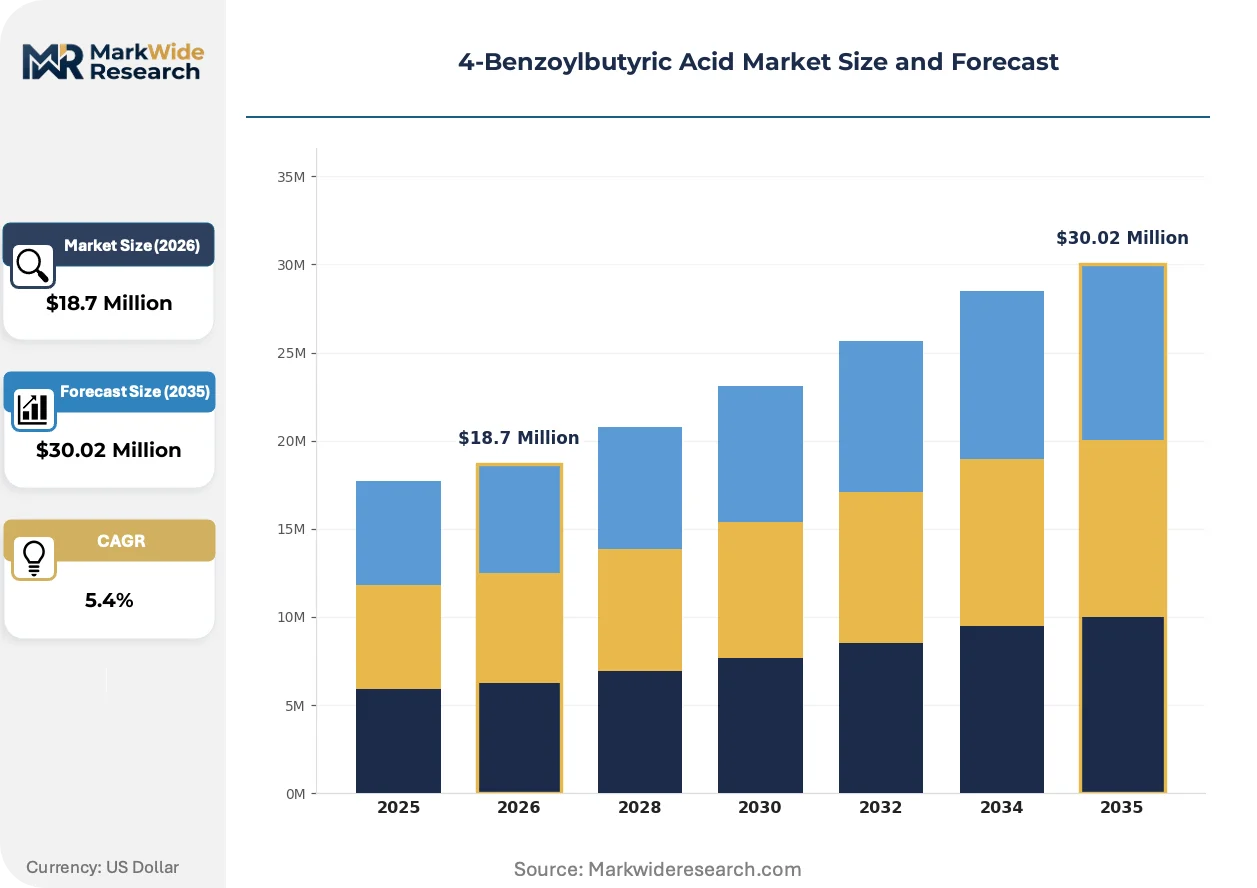
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $30.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Chemicals, Additives, Intermediates Application: Pharmaceutical Manufacturing, Chemical Synthesis, Polymer Production, Food Preservation End User: Pharmaceutical Companies, Chemical Industries, Food Manufacturers, Academic Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Dayang chem (Hangzhou) Co. Ltd., Jinan Haohua Industry Co. Ltd., Tokyo Chemical Industry Co. Ltd., Pfaltz & Bauer Inc., Shanghai Meicheng Chemical Co. Ltd., Sarex, Finetech Industry Limited, Energy Chemical, Acros Organics B.V.B.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4-Benzoylbutyric Acid Market Strategic Shifts
Process intensification and regulatory data harmonization are compressing development timelines while fragmenting procurement channels across pharmaceutical and materials science end-uses.
Continuous flow Friedel-Crafts acylation is supplanting batch-wise aluminum chloride protocols in pilot-scale peptide intermediate manufacturing. European CDMOs adopting this technology report thirty percent reduction in solvent waste generation. The shift enables just-in-time production for clinical trial material campaigns that batch processes cannot accommodate.
ICH Q7 guideline alignment by China's NMPA is forcing documentation upgrades at export-oriented Hangzhou and Jinan facilities. European importers now demand identical impurity specification sheets across Chinese and Indian suppliers. Small producers without dedicated quality units are consolidating through toll manufacturing arrangements with larger certified competitors.
Research procurement officers now specify pharmacopeial-grade material for early discovery chemistry, displacing reagent-grade purchases previously routed through distributor catalogs. Academic institutions in Germany and Switzerland negotiate frame contracts directly with manufacturers for gram-to-kilogram scale supply. This behavior concentrates volume with qualified producers while marginalizing catalog distributors in high-purity segments.
4-Benzoylbutyric Acid Market Segmentation
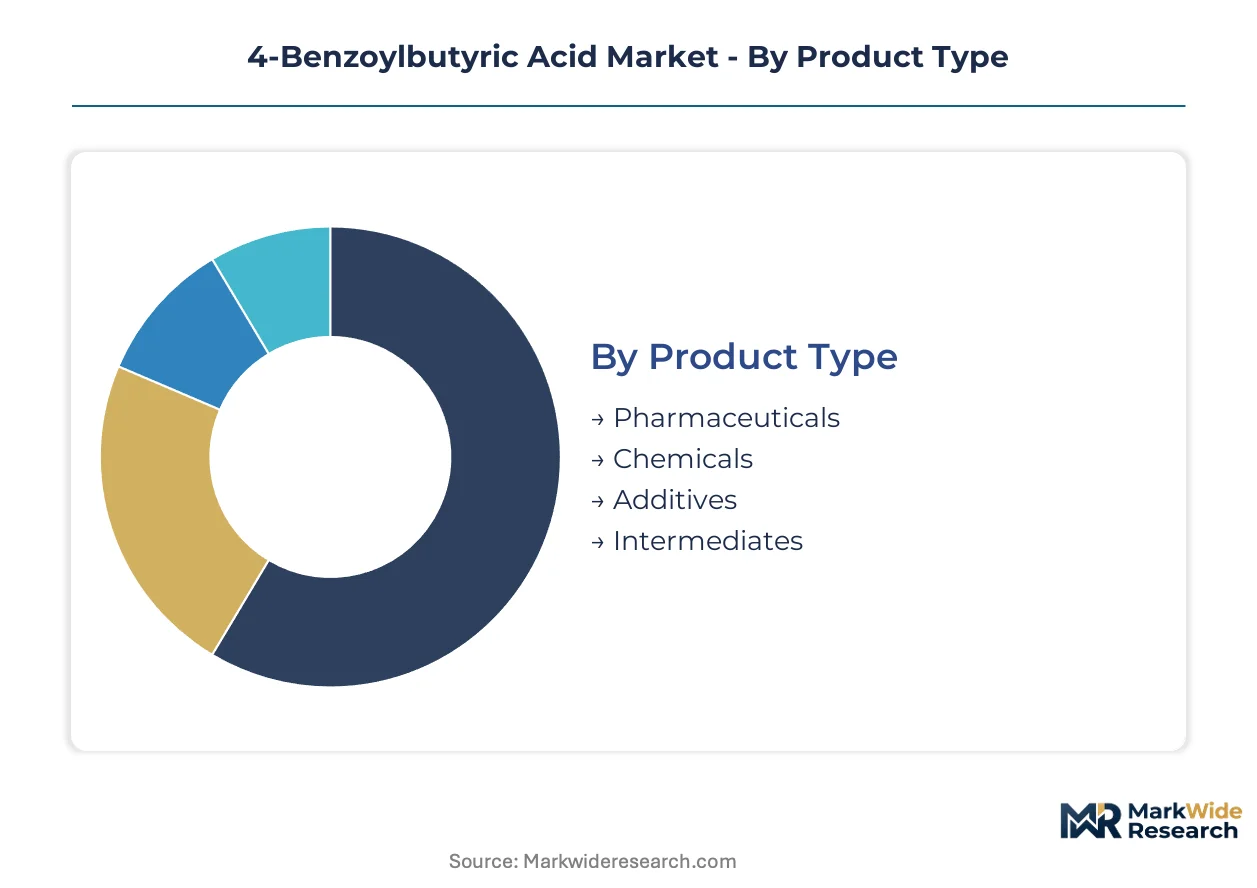
Segmentation in the 4-benzoylbutyric acid market reveals how qualification tiers and regulatory pathways fragment procurement channels. Each dimension exposes distinct margin structures and supplier qualification burdens that reshape competitive positioning.
Product Type:
Substitution pressure from alternative gamma-keto acids and synthetic routes intensifies most acutely for undifferentiated commodity grades, while qualified pharmaceutical intermediates maintain defensive moats through documentation barriers.
- Pharmaceuticals:USP-grade material meeting ICH Q3D elemental impurity limits commands dedicated production campaigns at Hangzhou and Jinan facilities. Peptide synthesis pipelines at Merck KGaA and Bachem lock in multi-year supply agreements with validated suppliers.
- Intermediates:Custom synthesis lots for late-stage clinical candidates require batch-specific COAs with residual solvent profiles. CDMOs in Hyderabad and Ahmedabad compete for these campaigns through PLI scheme cost advantages.
- Chemicals:Technical-grade material serves industrial acylation applications with lower purity thresholds.
- Additives:Polymer modification grades functionalize biodegradable packaging resins under EU Green Deal mandates.
Pharmaceuticals anchors the volume base while Intermediates gains share at the steepest rate.
Application:
Cost tier stratification separates qualified drug-substance precursors from commodity chemical synthesis feedstocks, with polymer applications occupying an emerging mid-tier demanding novel functional specifications.
- Pharmaceutical Manufacturing:Gamma-keto acid building blocks enable GLP-1 receptor agonist and oligonucleotide conjugation chemistry. FDA intermediate guidance forces validated impurity profiling that excludes toll manufacturers lacking dedicated analytical capabilities.
- Polymer Production:Functional monomer demand from polyhydroxyalkanoate developers accelerates as EU packaging recyclability targets tighten. Novel comonomer specifications require custom synthesis relationships rather than catalog procurement.
- Chemical Synthesis:Friedel-Crafts acylation feedstock serves general organic synthesis with price-sensitive spot purchasing.
- Food Preservation:Regulatory barriers limit gamma-keto acid deployment in direct food contact applications.
Pharmaceutical Manufacturing anchors the volume base while Polymer Production climbs the fastest on biodegradable material mandates.
End User:
Customer type fragmentation concentrates procurement leverage with large pharmaceutical formulators while fragmenting academic demand across e-procurement platforms.
- Pharmaceutical Companies:Direct procurement contracts with qualified intermediate producers bypass distributor markups for multi-kilogram campaigns. EMA and FDA dual-inspection requirements favor suppliers with dedicated quality units.
- Academic Institutions:Frame contracts with German and Swiss research universities specify pharmacopeial-grade material for discovery chemistry, displacing reagent-grade catalog purchases.
- Chemical Industries:Spot market purchasing for technical-grade material responds to aluminum chloride feedstock volatility.
- Food Manufacturers:Limited adoption pending toxicological clearance from EFSA and FDA.
Pharmaceutical Companies anchor the volume base while Academic Institutions expand most quickly through direct manufacturer relationships.
Distribution Channel:
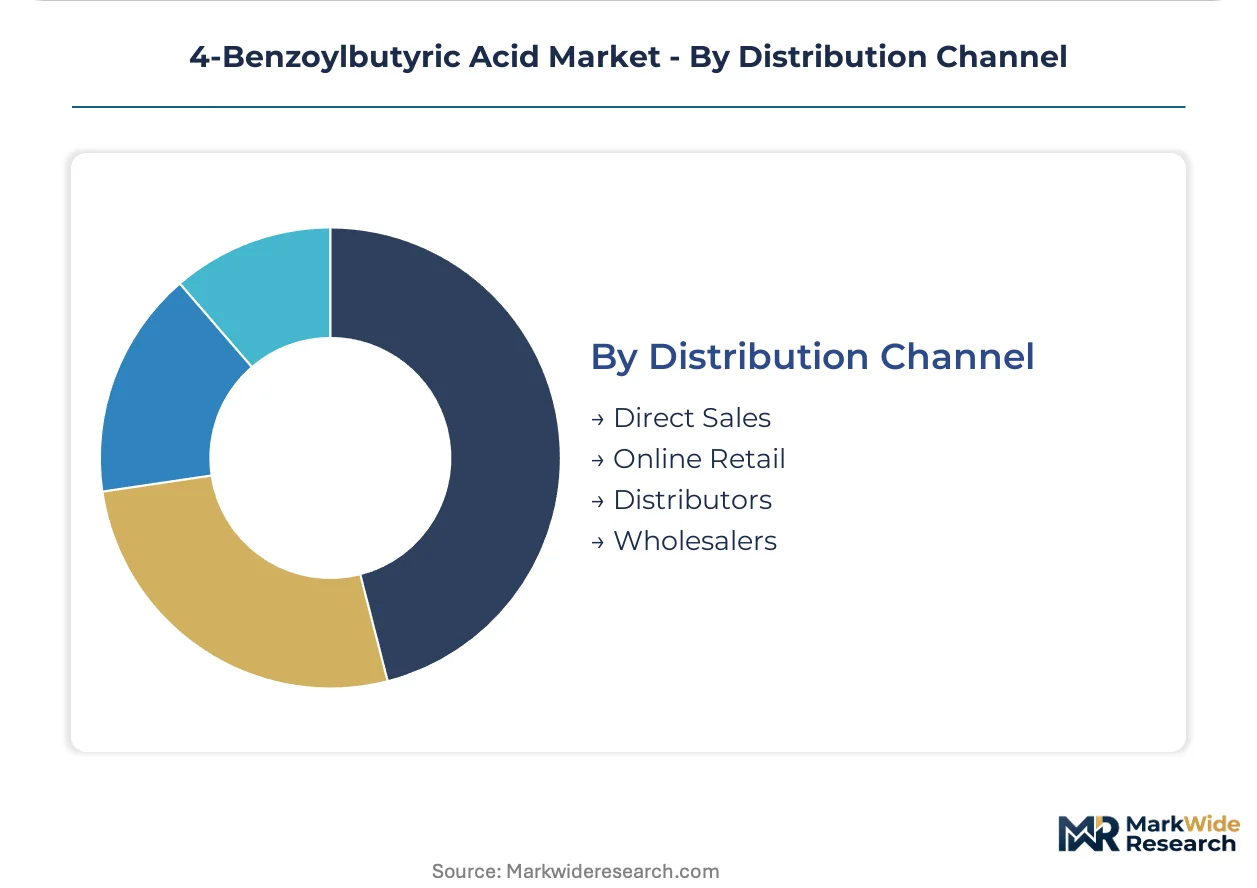
Supply concentration in Zhejiang and Shandong provinces shapes channel economics, with direct sales capturing qualified pharmaceutical volumes while distributors serve fragmented technical-grade demand.
- Direct Sales:Frame contracts with peptide API manufacturers specify batch release protocols and regulatory documentation packages. REACH registration completion enables validated European supply chains.
- Distributors:Catalog channels retain relevance for gram-scale research quantities and spot technical-grade purchases.
- Online Retail:E-procurement platforms aggregate academic demand for high-purity lots.
- Wholesalers:Inventory holding for commodity chemical grades buffers petrochemical price volatility.
Direct Sales anchors the volume base while Online Retail shows the steepest expansion trajectory on academic procurement platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland exhibit minimal price elasticity for USP-grade peptide intermediates, while chemical synthesis purchasers in India and technical-grade consumers in China drive aggressive spot-market negotiations. This divergence fragments procurement strategies across geographies.
China
Peptide API contract manufacturing and custom synthesis outsourcing dominate demand from Hangzhou and Jinan industrial clusters. NMPA alignment with ICH Q7 guidelines forces documentation upgrades at export-oriented Zhejiang and Shandong facilities. The Yangtze River Delta concentration of gamma-keto acid producers faces intensifying EMA and FDA dual-inspection requirements.
Germany
GLP-1 receptor agonist developers at Merck KGaA and Bachem lock in multi-year supply agreements with validated intermediate suppliers. REACH registration completion for 4-benzoylbutyric acid removes import friction under ECHA dossier acceptance. The Rhine-Main chemical corridor hosts peptide synthesis CDMOs demanding batch-specific COAs with residual solvent profiles.
United States
FDA intermediate guidance shapes supplier qualification burdens for oligonucleotide conjugation chemistry programs. Academic institutions in Greater Boston and the San Francisco Bay Area negotiate frame contracts directly with manufacturers for pharmacopeial-grade discovery material. The Southeast pharmaceutical manufacturing belt increasingly sources through validated toll manufacturing arrangements.
India
PLI scheme incentives for active pharmaceutical ingredient manufacturing attract investment in gamma-keto acid synthesis capabilities. CDMOs in Hyderabad and Ahmedabad compete for late-stage clinical candidate campaigns through cost-advantaged custom synthesis. The country's national pharmaceutical regulator tightens impurity profiling protocol requirements for export-oriented facilities.
Japan
PMDA-certified reagent catalogs extend into high-purity custom synthesis for domestic peptide developers. METI industrial standards shape specification tiers separating pharmaceutical-grade from technical-grade procurement channels. The Kanto region concentration of fine chemical producers maintains defensive moats through analytical method transfer capabilities.
4-Benzoylbutyric Acid Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with European and Japanese specialists commanding premium positioning through certification depth while Chinese manufacturers capture volume through integrated custom synthesis platforms. The supplier base fragments across three tiers: validated pharmaceutical-grade producers, toll manufacturing intermediaries, and undifferentiated commodity chemical suppliers. Strategic consolidation concentrates among CDMOs acquiring analytical capabilities and Chinese producers upgrading quality units for ICH Q7 compliance. Capacity expansion and regulatory documentation investments represent the dominant competitive moves.
Within the China-based manufacturing tier, Dayang chem (Hangzhou) Co. Ltd. and Jinan Haohua Industry Co. Ltd. occupy positions exemplifying the Zhejiang-Shandong corridor concentration of gamma-keto acid synthesis capacity. Tokyo Chemical Industry Co. Ltd. represents the Japan-certified regrade catalog archetype that extends into high-purity custom synthesis relationships. These three anchors illustrate how geographic clustering and certification tier differentiation fragment competitive positioning across procurement channels.
| Leading Market Players |
|---|
| Dayang chem (Hangzhou) Co. Ltd. |
| Jinan Haohua Industry Co. Ltd. |
| Tokyo Chemical Industry Co. Ltd. |
| Pfaltz & Bauer Inc. |
| Shanghai Meicheng Chemical Co. Ltd. |
| Sarex |
| Finetech Industry Limited |
| Energy Chemical |
| Acros Organics B.V.B.A. |
| Others |
Value Chain & Pricing Dynamics
Multi-kilogram batch scale economies at Hangzhou and Jinan facilities compress unit costs for peptide-grade material while simultaneously erecting price floors that exclude smaller toll manufacturers from qualified pharmaceutical supply chains. This scale-driven concentration reinforces margin bifurcation between certified producers serving Merck KGaA and Bachem versus commodity suppliers trapped in spot-market aluminum chloride volatility.
Pricing Analysis
ICH Q7 guideline alignment dictates the pricing tier structure across the 4-benzoylbutyric acid market, separating validated pharmaceutical-grade campaigns from technical-grade spot purchases. Three-tier pricing structure across premium, standard, and economy levels reflects documentation burden, batch-specific COA requirements, and residual solvent profiling depth. Cost compression in the technical-grade tier is intensifying because Friedel-Crafts feedstock volatility transfers directly from aluminum chloride and butyric acid derivative markets. Academic institutions exhibit highest price sensitivity through e-procurement platform aggregation, while GLP-1 developers at Merck KGaA demonstrate minimal elasticity for USP-grade peptide intermediates.
Supply Chain Analysis
Inventory holding patterns reveal twelve-to-sixteen-week lead times for validated pharmaceutical campaigns versus spot-market availability for technical-grade material. Gamma-keto acid synthesis capacity concentrates in China, India, and Japan, with Zhejiang-Shandong corridor facilities serving export-oriented peptide API manufacturers. Raw material dependencies center on aluminum chloride catalysts, butyric acid derivatives, and dichloromethane acylation media facing REACH Annex XVII substitution pressures. Single-country logistics vulnerability in China's custom synthesis clusters exposes buyers to NMPA inspection backlogs and Yangtze River Delta port congestion. Distribution runs through direct frame contracts for qualified pharmaceutical volumes, with catalog distributors retaining relevance only for gram-scale research quantities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical method transfer capabilities and dedicated quality unit infrastructure constitute the binding constraint separating viable suppliers from stranded commodity producers in this peptide intermediate market. The scarcity of FDA-intermediate-guidance-compliant impurity profiling protocols locks in defensive positioning for certified incumbents while raising capital barriers for aspirants.
For Market Incumbents: Consolidate analytical capabilities through acquisition of regional CDMOs possessing validated impurity profiling infrastructure, defending against continuous flow microreactor technology disruption from European pilot-scale competitors. Prioritize backward integration into aluminum chloride and butyric acid derivative supply to buffer Friedel-Crafts feedstock volatility. Lock in multi-year frame contracts with Bachem and Merck KGaA peptide synthesis pipelines before PLI scheme incentives mature Indian CDMO cost advantages. For New Entrants and Emerging Players: Gram-to-kilogram scale pharmacopeial-grade supply for German and Swiss academic institutions represents the most penetrable white-space segment, as incumbents prioritize multi-kilogram pharmaceutical campaigns. Target Hyderabad and Ahmedabad CDMO clusters seeking gamma-keto acid synthesis capabilities through toll manufacturing partnerships leveraging PLI scheme cost structures. Establish e-procurement platform presence to capture research procurement officer demand displacing catalog distributors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among validated pharmaceutical-grade producers with dedicated quality units and EMA-FDA dual-inspection histories, offering multi-year supply agreement visibility. Across the five-to-ten year viability window, acquisition targets should display ICH Q7 documentation alignment and continuous flow technology pilot data. Monitor ECHA REACH registration completion rates for 4-benzoylbutyric acid as inflection indicator for European import friction removal and validated supply channel opening.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Acylation Scale-Up | Microreactor technology reduces solvent waste generation thirty percent at European CDMO pilot facilities. |
| ICH Q7 Documentation Upgrade | NMPA alignment forces Hangzhou and Jinan export-oriented facilities toward dedicated quality unit investment. |
| Backward Integration into Feedstocks | Captive aluminum chloride and butyric acid derivative supply buffers petrochemical price swing exposure. |
| Academic Direct Sourcing Platform | E-procurement aggregation displaces catalog distributors in gram-scale high-purity research material segments. |
| PLI Scheme CDMO Partnership | Hyderabad and Ahmedabad gamma-keto acid synthesis capabilities compete for late-stage clinical candidate campaigns. |
Study Parameters
Initial hypotheses were tested against primary input from peptide synthesis directors, regulatory affairs leads at CDMOs, procurement officers at academic institutions, and custom synthesis plant managers, then refined against secondary validation from ECHA REACH registration databases, FDA intermediate guidance filings, NMPA ICH Q7 alignment notices, and SEC 10-K disclosures from listed specialty chemical producers. Bottom-up demand modeling across pharmaceutical manufacturing, polymer production, and chemical synthesis applications triangulated with top-down capacity assessments at Zhejiang and Shandong facilities.
Variance decomposition across product type, application, end user, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by qualification tier pricing differentials incorporated peptide pipeline expansion rates from GLP-1 and oligonucleotide developers, EU Green Deal biodegradable polymer mandate implementation timelines, and continuous flow technology adoption curves at European pilot facilities.
Forecasts assume regulatory continuity in REACH, FDA intermediate guidance, and NMPA ICH Q7 alignment regimes; material policy shifts including dichloromethane Annex XVII expansion or dual-carbon goal acceleration in China would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
Silicone Derivative Market
Specialty Chemicals
North America Chromatography Resins Market
Specialty Chemicals
Colloidal Silver Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market
Specialty Chemicals
GLDA Market
Specialty Chemicals
Organo-Modified Siloxanes Market
Specialty Chemicals
Phospholipid Market
Specialty Chemicals
Cloud Emulsions Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
Plastic Stabilizer Market
Specialty Chemicals
Zinc Ricinoleate Market