
 Global Bonding Varnish Market | 2026-2036
Global Bonding Varnish Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bonding Varnish Market Analysis
Aftermarket service revenue for motor rewind and transformer refurbishment is reconfiguring margin pools away from initial varnish sales toward recurring technical service contracts. Axalta leverages its global coil coatings infrastructure to cross-sell bonding varnish solutions into electrical OEM channels. Sherwin-Williams anchors North American distribution through dedicated industrial coatings branches serving motor repair shops. KANSAI HELIOS Austria competes on specialty formulations for traction motors in European rail systems.
Bonding varnish is an insulating resin system applied to electrical conductors and laminations, typically formulated from epoxy, polyurethane, or alkyd chemistries with thermal class ratings from 130°C to 220°C, that cures to form a dielectric bond resisting thermal cycling and moisture ingress. Its primary purpose is to secure winding wires and core laminations against vibration and electrical stress in rotating machinery and static transformers. Epoxy formulations dominate volume due to their superior thermal endurance in automotive traction motors, while water-based technology captures expanding share as VOC regulations tighten across manufacturing jurisdictions. Solvent-based systems retain position in aerospace applications where film integrity under extreme thermal shock outweighs environmental compliance costs.
REACH in Europe, EPA regulations in the United States, and China's MEE emission standards collectively restrict solvent content and mandate hazard communication across the supply chain, elevating compliance costs for smaller compounders while creating certification barriers for import-dependent buyers. ECHA's SVHC candidate list pressures reformulation timelines for legacy bisphenol-based epoxy systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and secure dual-technology production flexibility.
Market Dynamics
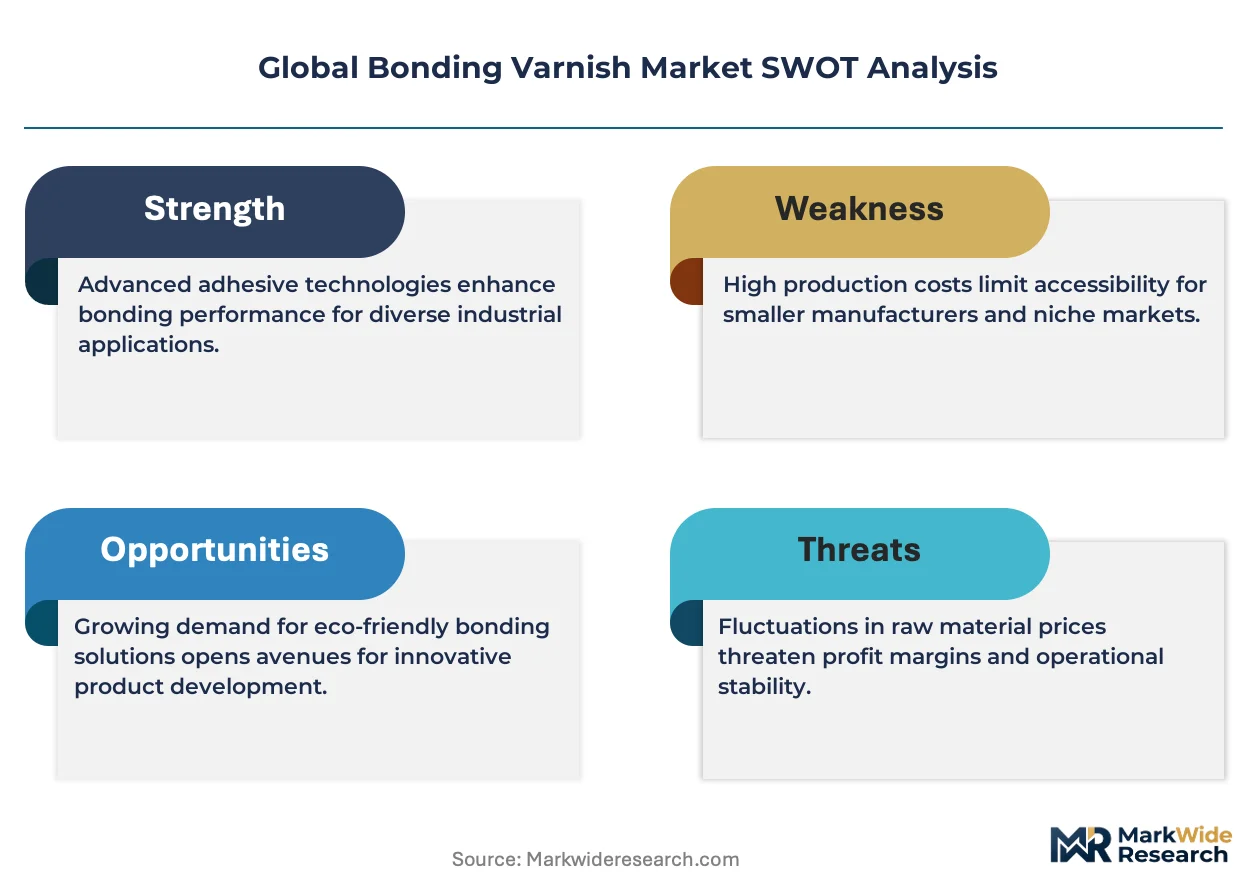
EV drivetrain production scaling in Germany and China is compressing thermal class requirements upward, forcing varnish formulators to prioritize 180°C-220°C epoxy systems while simultaneously retooling for water-based compliance under tightening VOC regimes.
Growth Catalysts
- EV traction motor thermal stress:Automotive OEMs specify Class H (180°C) and Class N (200°C) bonding varnishes for permanent magnet motor windings, pulling high-performance epoxy formulations into volume production.
- REACH SVHC pressure:ECHA's candidate list expansion accelerates reformulation away from bisphenol-A epoxies toward alternative resin backbones with equivalent dielectric performance.
- Semiconductor packaging clustering:South Korea's advanced packaging fabs drive demand for ultra-thin, low-outgassing bonding films in flip-chip and wafer-level applications.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin prices track bisphenol-A and epichlorohydrin spot markets, compressing compounder margins during crude oil swings.
- Solvent-based asset stranding:European and Chinese manufacturers face write-down risks on legacy solvent coating lines as MEE and REACH timelines accelerate.
- Ceramic coating substitution:Select aerospace and high-frequency applications adopt plasma-sprayed alumina or Parylene conformal coatings where thermal shock tolerance exceeds organic resin limits.
Strategic Opportunities
- India motor manufacturing buildout:PLI scheme incentives for domestic EV and industrial motor production create first-mover advantage for varnish suppliers establishing local technical service presence.
- UV-curable formulation expansion:Electronics manufacturers in Japan and Taiwan adopt cationic UV epoxy systems for rapid-process stator impregnation, eliminating thermal cure bottlenecks.
- Transformer refurbishment service bundling:North American utilities and industrial motor rewind shops shift toward performance-contracting models that lock in recurring varnish and technical service revenue.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in high-temperature dielectric resin design concentrates among aging technical staff at incumbent compounders, constraining new entrant R&D velocity.
- Dual-technology certification lag:Qualifying equivalent water-based and solvent-based variants for the same OEM specification demands parallel UL 1446 thermal aging protocols, extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bonding Varnish Market |
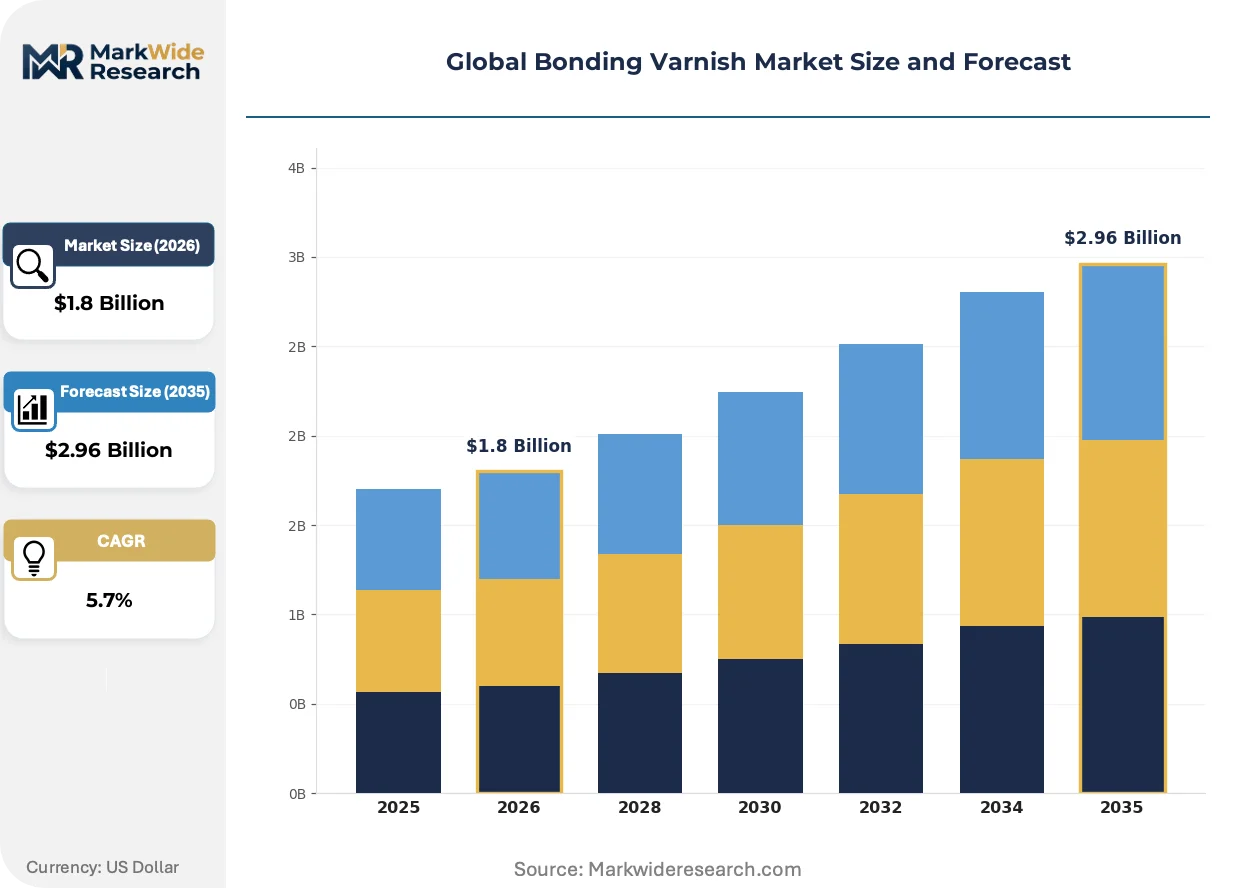
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Alkyd, Acrylic End User: Automotive, Electronics, Aerospace, Furniture Grade: Industrial, Commercial, Specialty, Premium Technology: Solvent-Based, Water-Based, UV-Curable, Heat-Curable |
| Companies Covered | Axalta, SWD AG, ERICH GRAU GMBH, KANSAI HELIOS Austria, Voltatex, PPG Industries, Sherwin-Williams, AkzoNobel, Helios Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bonding Varnish Market Emerging Trajectories
Formulation chemistry is bifurcating between ultra-high-temperature automotive specifications and ambient-cure electronics applications, with process automation and regulatory compliance emerging as the decisive competitive differentiators rather than base resin cost alone.
Nano-silica modified epoxy systems are hybridizing conventional bonding varnish with ceramic filler reinforcement, delivering 15-20°C thermal class upgrades without sacrificing impregnation viscosity. Tier-1 automotive suppliers in Germany and Japan qualify these hybrids for 800V inverter-fed traction motors where partial discharge resistance is critical. The technology is hybridizing supplier value chains, forcing traditional varnish compounders into partnerships with specialty filler producers or captive nanomaterial synthesis.
China's MEE emission standards and dual carbon goals are accelerating solvent-based phase-out timelines beyond earlier provincial pilot programs, compelling domestic manufacturers to retrofit or retire conventional dip-and-bake lines. The policy cascade affects primarily small and mid-tier motor rewind operations in Guangdong and Jiangsu provinces, which face capital constraints for aqueous system conversion. Multinational suppliers with established water-based portfolios capture displaced demand through technical service bundling.
Aftermarket motor rewind operators are unbundling varnish supply from legacy distributor relationships, establishing direct technical partnerships with formulators for application-specific specification support. The pattern is most visible across the US industrial maintenance sector, where independent rewind shops consolidate purchasing through cooperative procurement networks. These aggregators negotiate formulation customization and bulk pricing previously reserved for OEM direct accounts, compressing traditional industrial coatings distributor margins.
Global Bonding Varnish Market Segmentation
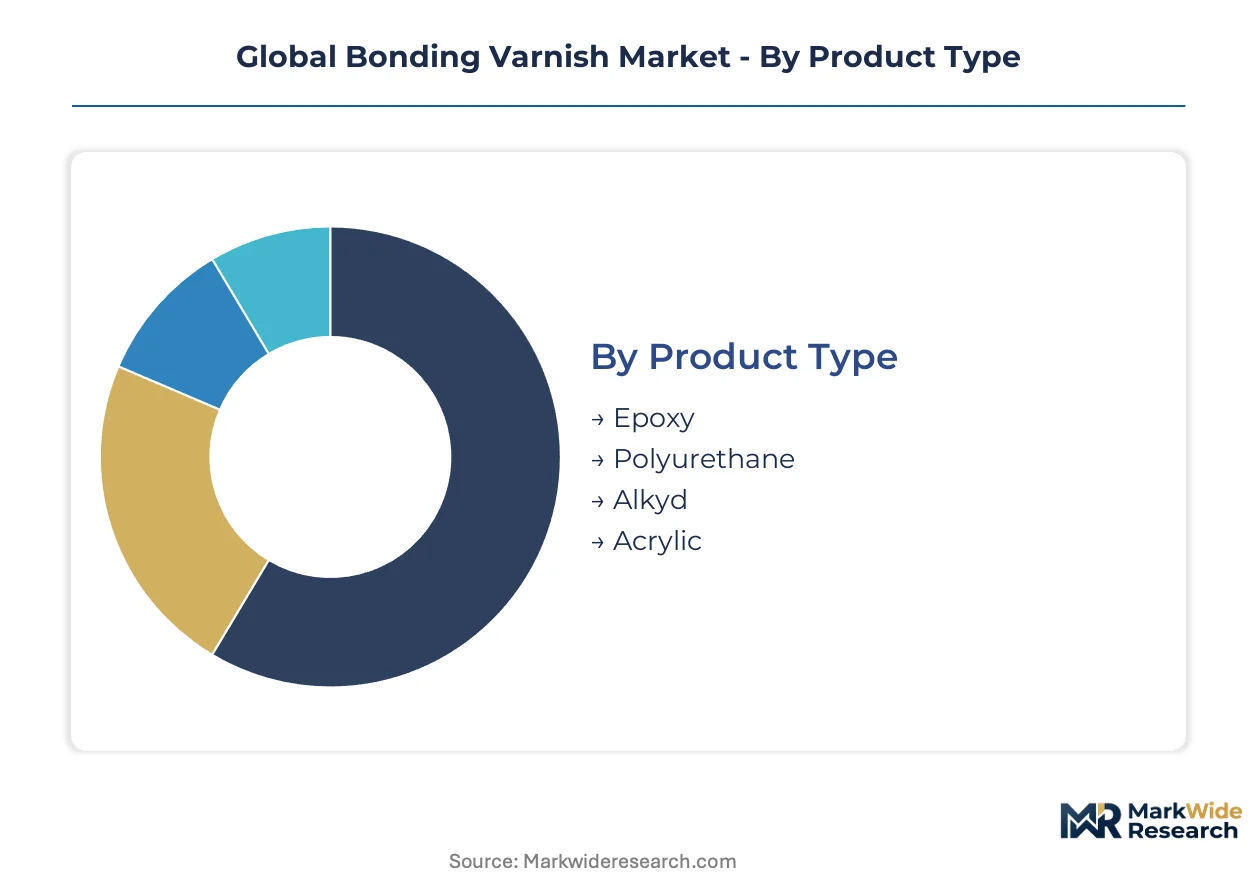
Segmentation in bonding varnish reveals divergent margin profiles and qualification timelines across chemistries and end-uses. Product type and technology choices determine capital intensity for applicators, while grade tiering separates specification-driven OEM procurement from price-sensitive maintenance markets.
Product Type:
Epoxy systems turn inventory fastest in automotive traction motor lines, while alkyd formulations linger in legacy industrial maintenance channels with extended replacement cycles.
- Epoxy:Formulated from bisphenol-A or bisphenol-F resin backbones with anhydride or amine curing agents, epoxy bonding varnishes deliver thermal class ratings from 180°C to 220°C. German and Chinese EV drivetrain manufacturers specify these systems for 800V inverter-fed permanent magnet motors where partial discharge resistance is mandatory under IEC 60034-18-41. REACH SVHC pressure on bisphenol-A is forcing accelerated reformulation timelines.
- Polyurethane:These flexible resin systems cure through isocyanate-hydroxyl reactions to form elastomeric films with superior moisture resistance and thermal shock tolerance. Japanese precision motor suppliers and South Korean semiconductor packaging operations specify polyurethane for hermetic motor windings and flip-chip underfill applications where coefficient of thermal expansion matching is critical.
- Alkyd:Oil-modified polyester resins dominate legacy motor rewind operations in India and Southeast Asia due to lower raw material costs and ambient cure compatibility.
- Acrylic:Thermoplastic acrylic formulations serve specialty electronics conformal coating applications requiring reworkability and low-temperature processing.
Established volume favors epoxy; emerging adoption favors polyurethane.
End User:
Automotive qualification cycles stretch 18-24 months for new traction motor specifications, while furniture coating approvals complete in 3-6 months.
- Automotive:OEMs specify Class H and Class N bonding varnishes for EV traction motors, with thermal aging protocols under UL 1446 creating steep certification barriers. German and Chinese drivetrain manufacturers drive specification tightening.
- Electronics:South Korean advanced packaging fabs and Japanese precision motor suppliers demand ultra-low outgassing formulations for semiconductor and micro-motor applications. UV-curable systems are gaining share fastest in this segment.
- Aerospace:Plasma-sprayed ceramic alternatives constrain organic varnish adoption in turbine generator applications where thermal shock exceeds 300°C.
- Furniture:Decorative and functional coating applications for electrical components in residential and commercial fixtures represent price-competitive, specification-light demand concentrated in Chinese manufacturing clusters.
Automotive commands specification authority; electronics offers the steepest expansion trajectory.
Grade:
Premium grade qualification demands parallel solvent-based and water-based certifications, doubling time-to-revenue versus industrial grade single-technology approval.
- Industrial:Standard thermal class formulations for general-purpose motors and transformers serve high-volume, price-sensitive procurement through distributor channels.
- Commercial:Mid-tier specifications balance performance and cost for HVAC, appliance, and power tool motor manufacturers.
- Specialty:Application-specific formulations for rail traction, wind turbine generators, and submersible pumps require customized viscosity and cure profiles.
- Premium:Nanoparticle-modified epoxies and ultra-high-purity systems for aerospace and medical device motors carry qualification documentation burdens and technical service bundling requirements.
Industrial grade captures volume share; premium grade captures margin expansion.
Technology:
Water-based system conversions require 12-18 month line retrofit timelines, while UV-curable installations achieve operational status within 90 days.
- Solvent-Based:Conventional dip-and-bake systems retain position in aerospace and select automotive applications where film integrity under thermal shock outweighs VOC compliance costs. China's MEE standards and REACH timelines are compressing viable deployment windows.
- Water-Based:Aqueous epoxy and polyurethane dispersions are displacing solvent systems in European and Chinese automotive plants under tightening emission regulations. Axalta and KANSAI HELIOS Austria compete on technical service bundling for conversion support.
- UV-Curable:Cationic epoxy systems enable rapid-process stator impregnation without thermal cure bottlenecks. Japanese and Taiwanese electronics manufacturers are adopting these for high-mix, low-volume production.
- Heat-Curable:Conventional thermal cure systems persist in heavy-duty motor and transformer applications where thick film build and complete core saturation are non-negotiable.
Heat-curable retains installed base; water-based and UV-curable systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia demonstrate acute price sensitivity on standard-grade alkyd formulations, while German and Japanese automotive OEMs absorb 40-60% premiums for Class H and Class N epoxy certifications without volume elasticity.
China
EV drivetrain manufacturers in Shanghai and Shenzhen are scaling procurement of 180°C-220°C epoxy systems for 800V traction motors. The Ministry of Ecology and Environment (MEE) emission standards and dual carbon goals are accelerating solvent-based phase-outs in Guangdong and Jiangsu provinces. Domestic motor rewind operations in these coastal clusters face capital constraints for aqueous system conversion, creating technical service opportunities for multinational suppliers with established water-based portfolios.
Germany
BMW, Volkswagen, and Bosch specify Class N bonding varnishes for next-generation permanent magnet motors with partial discharge resistance under IEC 60034-18-41. REACH SVHC candidate list expansion pressures reformulation away from bisphenol-A epoxy backbones. The Baden-Württemberg and Bavaria automotive corridors concentrate qualification activity, with Tier-1 suppliers demanding parallel solvent-based and water-based certifications for equivalent OEM specifications.
United States
North American utilities and industrial motor rewind shops are shifting toward performance-contracting models that bundle varnish supply with recurring technical service revenue. EPA regulations restrict solvent content and mandate hazard communication across the supply chain. The Great Lakes manufacturing belt and Texas Gulf Coast petrochemical corridors host the densest concentrations of transformer refurbishment operations unbundling legacy distributor relationships.
Japan
Precision motor suppliers and semiconductor packaging operations in Tokyo-Osaka-Nagoya demand ultra-low outgassing polyurethane formulations for hermetic windings and flip-chip underfill. METI industrial standards and JIS certification requirements create steep technical barriers for import-dependent buyers. Cationic UV epoxy systems are gaining fastest adoption in Kansai-region electronics manufacturing for rapid-process stator impregnation without thermal cure bottlenecks.
South Korea
Samsung and SK Hynix advanced packaging fabs drive demand for ultra-thin, low-outgassing bonding films in flip-chip and wafer-level applications. MFDS chemical safety regulations and national semiconductor self-sufficiency initiatives elevate local qualification requirements. The Seoul Capital Area and Busan-Ulsan electronics clusters concentrate specification authority for next-generation die-attach and underfill varnish systems.
Global Bonding Varnish Market Vendor Landscape
Capability concentration sits with specialty formulators possessing UL 1446 thermal aging protocols and nanoparticle modification expertise; scale advantage sits with diversified coatings multinationals leveraging global coil coatings infrastructure. The vendor base organizes into three tiers: integrated industrial coatings houses with electrical OEM channel access, regional specialists competing on rail traction and wind turbine specifications, and commodity compounders serving price-sensitive motor rewind maintenance markets. Dominant competitive moves include cross-selling bonding varnish solutions through existing coil coatings distribution networks and technical service bundling for water-based system conversions.
Within the integrated coatings tier, Axalta and Sherwin-Williams exemplify scale-driven positioning. Axalta leverages its global coil coatings infrastructure to cross-sell bonding varnish solutions into electrical OEM channels, while Sherwin-Williams anchors North American distribution through dedicated industrial coatings branches serving motor repair shops. KANSAI HELIOS Austria represents the regional specialist archetype, occupying a position defined by specialty formulations for traction motors in European rail systems. These three anchors illustrate the competitive spectrum from diversified scale to focused technical specialization.
| Leading Market Players |
|---|
| Axalta |
| SWD AG |
| ERICH GRAU GMBH |
| KANSAI HELIOS Austria |
| Voltatex |
| PPG Industries |
| Sherwin-Williams |
| AkzoNobel |
| Helios Group |
| Others |
Supply Flow & Price Mechanics
Guangdong and Jiangsu provinces anchor solvent-based bonding varnish capacity for China's motor rewind sector, yet MEE emission standards and dual carbon goals are accelerating line retirements faster than aqueous conversion timelines, compressing regional supply and elevating pricing power for multinational water-based suppliers with established technical service networks.
Pricing Analysis
Aftermarket technical service contracts now drive lifetime value more than initial varnish sales, with three-tier pricing structure across premium, standard, and economy levels separating UL 1446-certified epoxy systems for automotive OEMs from commodity alkyd formulations for Indian maintenance shops. Certification tier and volume scale differentiate price bands, while cost compression in solvent-based industrial grades intensifies as stranded asset risks mount. Price sensitivity concentrates among Southeast Asian motor rewind operators; German EV drivetrain manufacturers absorb substantial premiums for Class N thermal ratings without volume elasticity.
Supply Chain Analysis
Bisphenol-A and epichlorohydrin feedstock markets in China, Germany, and the United States tether epoxy resin pricing to crude oil volatility, with specialty nanofiller producers in Japan and South Korea supplying thermal class upgrade additives. Raw material dependencies span petrochemical intermediates, anhydride curing agents, and cationic photoinitiators for UV systems. Single-source vulnerability concentrates in high-purity resin backbones for semiconductor packaging applications. Distribution runs through industrial coatings branches serving motor repair shops and direct technical partnerships with automotive Tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global bonding varnish demand sits in early-cycle expansion as EV drivetrain production scales and water-based formulation conversions create replacement demand beyond organic growth. Penetration headroom remains substantial in India's PLI-backed motor manufacturing buildout.
For Market Incumbents: Harden UL 1446 certification barriers by accelerating parallel water-based and solvent-based qualification timelines for equivalent OEM specifications, insulating against emerging Asian compounders with lower compliance overhead. Deepen backward integration into specialty nanofiller synthesis to secure thermal class upgrade supply. Prioritize technical service bundling to capture stranded demand from China's solvent-based line retirements. For New Entrants and Emerging Players: Establish a beachhead in India's domestic EV and industrial motor production corridors by partnering with PLI scheme beneficiaries for localized formulation support and application engineering. Target UV-curable system adoption in Japanese electronics manufacturing where rapid-process stator impregnation eliminates incumbent thermal cure advantages. Lead with cationic epoxy expertise rather than commodity epoxy volume. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty formulators possessing nanoparticle modification expertise and established UL 1446 protocols over diversified coatings houses with channel scale but aging resin backbones. Long-term viability hinges on dual-technology production flexibility across solvent, water-based, and UV-curable platforms. Watch ECHA SVHC candidate list expansion velocity as inflection indicator for reformulation investment cycles and stranded inventory risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nanofiller Synthesis | Captures thermal class upgrade value previously shared with Japanese specialty chemical suppliers. |
| Dual-Technology Certification Investment | Secures OEM specification lock-in as REACH and MEE timelines compress solvent-based deployment windows. |
| Technical Service Bundling Expansion | Transforms transactional varnish sales into recurring revenue streams with North American motor rewind networks. |
| UV-Curable Formulation Launch | Eliminates thermal cure bottlenecks for Japanese and Taiwanese electronics manufacturers in high-mix production. |
| Joint Venture in Indian Motor Corridor | Captures PLI scheme incentives while establishing local application engineering presence for domestic OEM qualification. |
Methodological Framework
A spread of perspectives from varnish formulation chemists, automotive OEM procurement leads, motor rewind shop operators, and industrial coatings distributors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC filings of diversified coatings multinationals, IEC standard documentation, and ECHA regulatory filings. Bottom-up segment sizing triangulated against top-down market aggregation across chemistry, end-use, and grade dimensions.
Demand-supply-balance framing anchored the forecast framework, with segmentation across product type, end-use industry, grade tier, and technology platform modeled throughout the projection horizon. CAGRs derived from elasticity-adjusted adoption curves for water-based and UV-curable systems, feedstock cost pass-through assumptions, and regulatory phase-out timelines. Industry-specific inputs included EV drivetrain production forecasts, semiconductor packaging capacity buildouts, and motor rewind shop consolidation patterns.
Sensitivities concentrate around ECHA SVHC list expansion timing, MEE enforcement intensity in Chinese provinces, and ceramic coating substitution rates in aerospace applications. Forecasts reflect documented assumptions on feedstock price corridors and qualification cycle durations. Cross-checking against IEC 60034-18-41 partial discharge resistance adoption rates and UL 1446 certification database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
Global Acrylic Adhesives Market
Adhesives & Sealants
Moisture Curing Adhesives Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Asia-Pacific EVA Adhesives Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
2-Octyl Cyanoacrylate Adhesives Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
UV Glue Market
Adhesives & Sealants
Wood Adhesives and Binders Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
North America Epoxy Curing Agents Market
Adhesives & Sealants
Europe Cyanoacrylate Adhesives Market
Adhesives & Sealants
Laminating Adhesives Market