
 Pyromellitic Dianhydride Market | 2026-2036
Pyromellitic Dianhydride Market Size, Share, and Industry Trends Forecast 2026-2036
Pyromellitic Dianhydride Market Analytics
Polyimide precursor chemistry is consolidating around pyromellitic dianhydride as the preferred building block for high-temperature aromatic polymers. Evonik leverages its specialty chemicals portfolio to sustain premium-grade PMDA supply for aerospace-qualified polyimide film. Puyang Shenghuade Chemical anchors Chinese domestic production through backward integration into catalytic oxidation of durene feedstock. Lonza differentiates via pharmaceutical-grade PMDA derivatives for drug-delivery polymer systems.
Pyromellitic dianhydride is a cyclic tetracarboxylic acid anhydride with molecular formula C10H2O6, synthesized via vapor-phase catalytic oxidation of durene or pseudocumene and melting at 286 degrees Celsius. The compound serves primarily as a monomer and curing agent for polyimide resins, polyetherimides, and high-performance epoxy formulations requiring thermal stability above 300 degrees Celsius. Powder-grade material dominates volume throughput due to its handling efficiency in continuous polymer reactors, while liquid formulations represent the fastest-growing category as resin compounders seek metered-dose processing compatibility. Electronics end-use applications command the deepest margin pools, driven by polyimide film demand for flexible circuit substrates and semiconductor passivation layers.
EPA oversight of air emissions from catalytic oxidation units shapes US manufacturing economics, while REACH registration requirements in Europe constrain importer flexibility on purity documentation. China's MEE enforces wastewater discharge standards that raise operating costs for coal-chemical based PMDA producers. Stakeholders must monitor feedstock durene availability from petroleum reformate streams, as refinery configuration shifts alter aromatic byproduct supply.
Market Dynamics
Polyimide film manufacturers are consolidating supply relationships around integrated PMDA-to-polyimide producers, compressing merchant market volumes while elevating purity specifications for remaining spot buyers.
Growth Catalysts
- Flexible electronics substrate demand:Polyimide film consumption for foldable display backplanes and semiconductor passivation layers is accelerating PMDA consumption in East Asian manufacturing clusters.
- REACH polymer-grade purity mandates:European ECHA registration requirements for substances above one ton annually are filtering out substandard imports and consolidating qualified supplier pools.
- Vapor-phase catalytic oxidation yield improvements:Process intensification at Chinese coal-chemical complexes is expanding nameplate capacity without proportional feedstock expansion.
Market Restraints
- Durene feedstock volatility:Petroleum reformate yield shifts at US Gulf Coast refineries are tightening aromatic byproduct availability for oxidation unit feed.
- Merchant market concentration:Three integrated producers in China's Jiangsu and Shandong provinces control over sixty percent of exportable powder-grade material.
- Epoxy anhydride substitution ceiling:Methylnadic anhydride and hexahydrophthalic anhydride alternatives cap pricing power in lower-temperature curing applications below two hundred degrees Celsius.
Strategic Opportunities
- India specialty chemicals corridor:Gujarat and Maharashtra state industrial zones lack indigenous PMDA production, creating import substitution potential for polymer-grade material.
- Pharmaceutical-grade derivative expansion:Drug-delivery polymer systems using PMDA-based polyimides command five-to-ten-fold premia over electronics-grade equivalents.
- Liquid formulation metered-dose compatibility:Resin compounders in automotive under-the-hood applications are converting from powder handling to liquid dosing systems.
Industry Challenges
- Catalytic oxidation unit capex intensity:New vapor-phase reactor trains require hundred-million-dollar investments with five-year commissioning timelines.
- Polymer-grade certification latency:Aerospace-qualified polyimide film supply chains demand eighteen-to-twenty-four-month qualification protocols for new PMDA sources.
- Wastewater treatment compliance:China's MEE discharge standards for maleic anhydride byproduct streams are raising operating costs for coal-chemical based producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyromellitic Dianhydride Market |
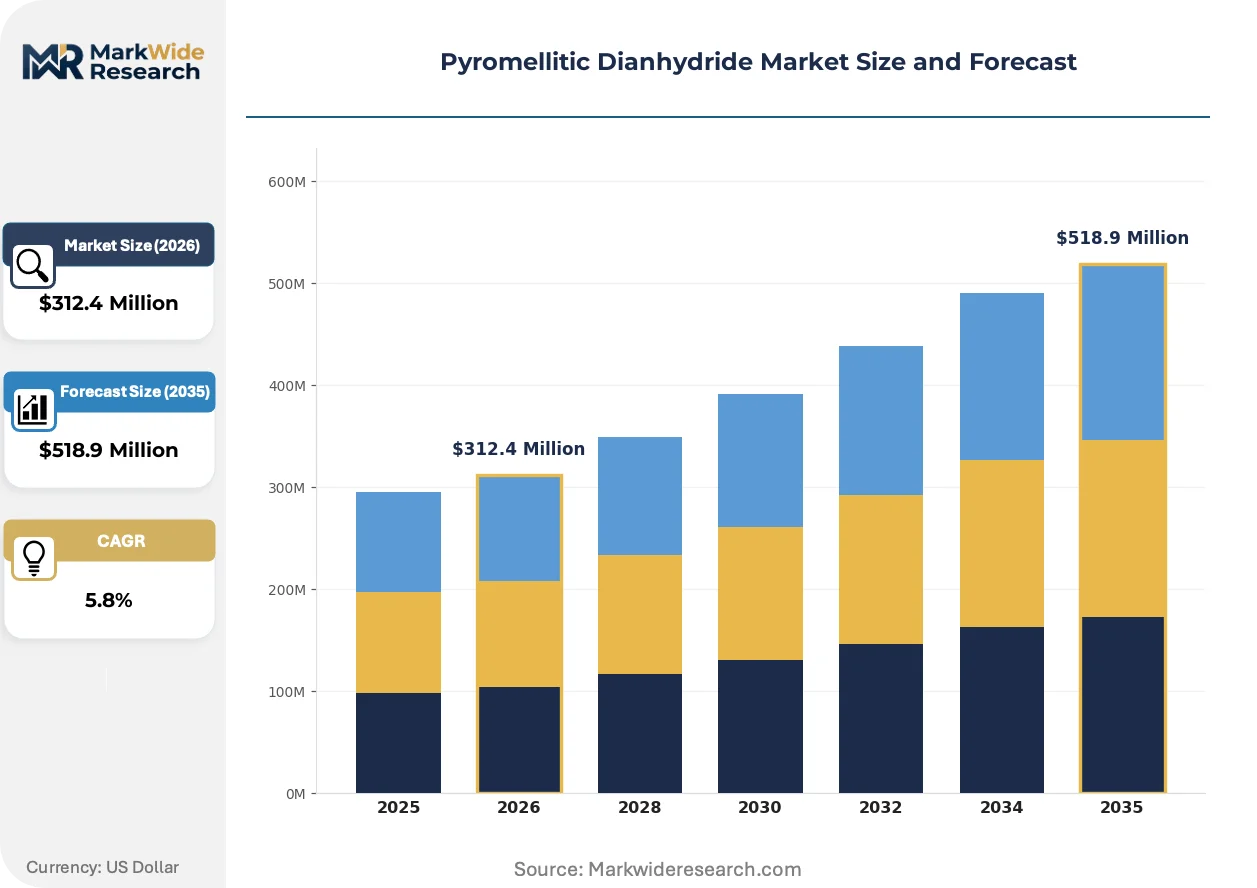
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Crystalline End Use Industry: Aerospace, Automotive, Electronics, Coatings Application: Polymer Production, Resin Formulation, Speciality Chemicals, Composites Distribution Channel: Direct Sales, Online Platforms, Distributors, Retail |
| Companies Covered | Evonik, Puyang Shenghuade Chemical, Lonza, Shijiazhuang Hope Chemical, Sigma-Aldrich, Jiangsu Hualun Chemical, Arxada, Dalian Dragon Win Catalytic, Puyang Hengfeng Electronic Insulation Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyromellitic Dianhydride Market Evolving Landscape
Process chemistry advances and regulatory tightening are converging to reshape competitive positioning around purity tiers, liquid formulation capabilities, and integrated supply chain control.
Continuous vapor-phase oxidation reactor designs are integrating real-time spectroscopic monitoring to maintain sub-ppm impurity profiles required for semiconductor-grade polyimide precursor synthesis. Japanese polyimide film manufacturers have adopted these systems fastest, compressing batch-to-batch variability to one-third of legacy stirred-tank operations. This integration is enabling single-source qualification for advanced packaging substrates that previously required dual-qualified suppliers.
REACH registration dossier updates through ECHA are mandating enhanced toxicological data for cyclic anhydride substances above ten-ton annual thresholds, raising compliance costs for importers without EU-based manufacturing assets. Specialty chemical distributors are consolidating their supplier panels to reduce documentation overhead. Polymer-grade material is bearing disproportionate cost pass-through as downstream aerospace and medical device customers demand full supply chain transparency.
Resin compounders serving automotive power electronics are consolidating purchase volumes through direct mill relationships, bypassing traditional chemical distributor networks that previously handled sub-containerload powder orders. Tier-one automotive suppliers in Germany and South Korea are driving this disintermediation, seeking lot-traceability and technical service proximity for thermal interface material formulations. Channel compression is most visible where polyimide precursor volumes exceed twenty metric tons annually per compounder site.
Pyromellitic Dianhydride Market Segmentation
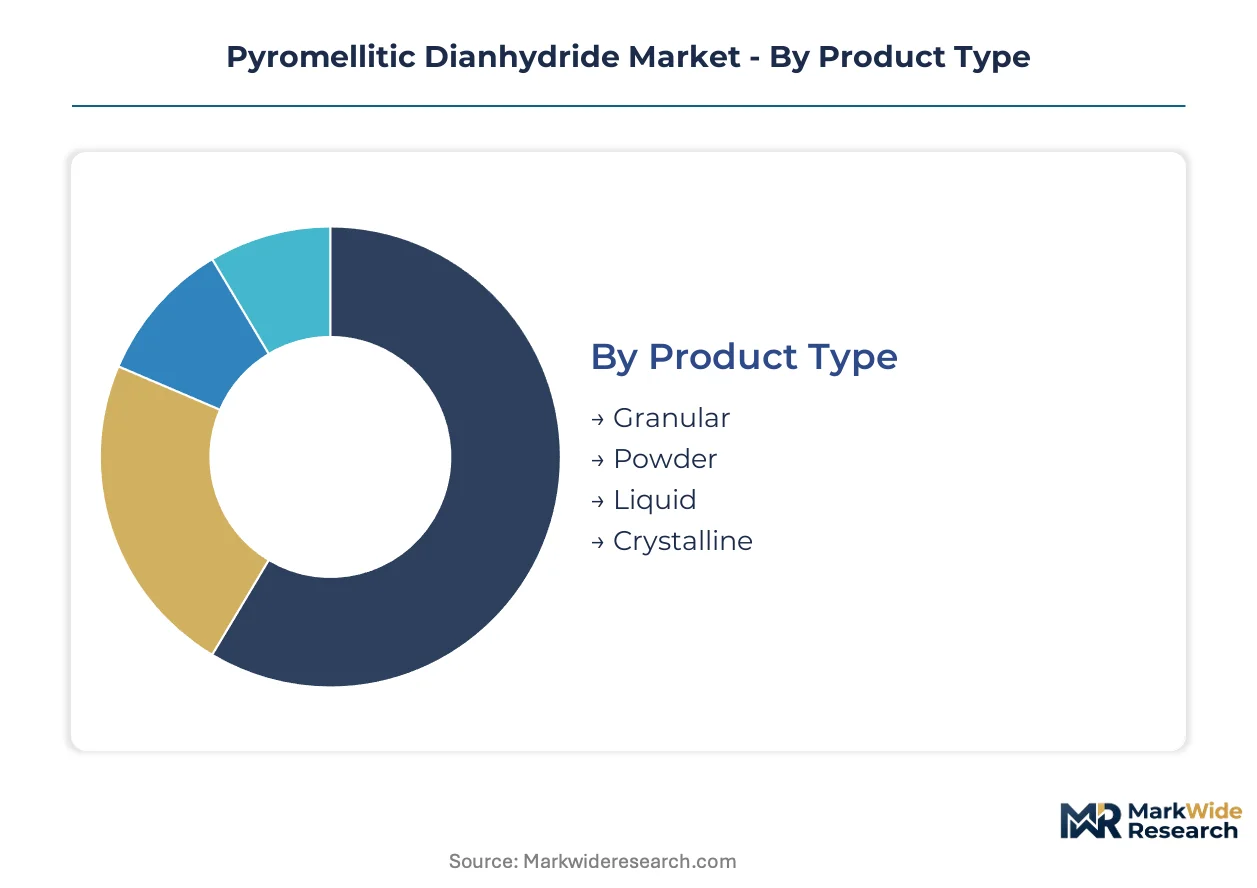
PMDA procurement patterns diverge sharply across physical form factors and end-use certifications, with polymer-grade purity requirements creating tiered supply access. Electronics and aerospace customers dominate margin capture while automotive and coatings segments compete on handling efficiency and formulation compatibility.
Product Type:
Supply concentration in vapor-phase oxidation units favors producers with integrated milling and classification capabilities, locking in powder-grade dominance while liquid formulations attract compounder investment.
- Powder:Fine particulate material with controlled particle size distribution enables homogeneous dispersion in continuous polyimide reactors. Electronics manufacturers in Japan and South Korea specify sub-50-micron grades for semiconductor passivation layer precursors, with dual-qualified supplier requirements compressing spot market availability.
- Liquid:Molten or solvent-dissolved formulations eliminate dust handling hazards and enable metered-dose processing in automated resin compounding lines. Automotive under-the-hood thermal interface material producers in Germany are converting from powder systems, with lot-traceability demands driving direct mill relationships.
- Granular:Free-flowing agglomerated particles reduce caking during bulk transport and storage.
- Crystalline:High-purity single-crystal forms serve pharmaceutical-grade derivative synthesis with enhanced batch consistency.
Today's leader: Powder. Tomorrow's challenger: Liquid.
End Use Industry:
Margin stratification across end-use tiers reflects certification latency and qualification protocol stringency, with aerospace and electronics commanding premium pricing over volume-driven automotive and coatings segments.
- Electronics:Polyimide film consumption for flexible circuit substrates and advanced packaging drives the deepest specification requirements. Foldable display backplane manufacturers in East Asian manufacturing clusters require sub-ppm metallic impurity profiles, with REACH registration dossiers filtering substandard imports from European supply chains.
- Aerospace:Qualified polyimide film supply chains for engine components and thermal protection systems demand eighteen-to-twenty-four-month source approval timelines. Evonik sustains premium-grade supply positions through aerospace-qualified production assets with full batch documentation.
- Automotive:Power electronics thermal interface materials and wire enamel formulations prioritize handling efficiency over extreme purity.
- Coatings:High-temperature resistant finishes for industrial equipment represent volume-driven demand with standard-grade material sufficiency.
Electronics and aerospace dominate value capture; automotive and coatings expand volume throughput.
Application:
Application-level demand concentrates where thermal stability requirements exceed 300 degrees Celsius, with polymer production consuming the majority of nameplate oxidation capacity.
- Polymer Production:Aromatic polyimide precursor synthesis represents the foundational demand anchor, with PMDA reacting with aromatic diamines to form polyamic acid intermediates. Chinese integrated producers in Jiangsu and Shandong provinces control captive supply chains from durene feedstock through polyimide film extrusion.
- Resin Formulation:Epoxy curing agent applications compete with methylnadic anhydride and hexahydrophthalic anhydride alternatives below 200 degrees Celsius, constraining pricing power in lower-temperature segments.
- Speciality Chemicals:Pharmaceutical-grade derivatives for drug-delivery polymer systems command substantial premia over electronics-grade equivalents.
- Composites:High-performance matrix materials for aerospace structural components require qualified batch consistency.
Polymer production anchors capacity planning; speciality chemicals offer the steepest expansion trajectory.
Distribution Channel:
Channel compression accelerates where annual volumes exceed twenty metric tons per site, with tier-one compounders bypassing traditional distributor networks.
- Direct Sales:Mill-direct relationships provide lot-traceability and technical service proximity for high-volume automotive and electronics compounders. German and South Korean automotive suppliers drive disintermediation, consolidating purchase volumes through single-source qualification protocols.
- Distributors:Chemical distribution networks retain relevance for sub-containerload powder orders and multi-product procurement efficiency. REACH registration documentation overhead is pushing specialty distributors toward consolidated supplier panels.
- Online Platforms:Digital procurement channels serve spot market requirements with limited technical service support.
- Retail:Small-quantity packaging for research and development applications represents minimal volume contribution.
Direct sales deepen integration with qualified buyers; distributors defend position in fragmented demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern chemical manufacturing corridor concentrates pyromellitic dianhydride capacity through integrated PMDA-to-polyimide supply chains that deliver cost advantages to electronics substrate producers.
China
Jiangsu and Shandong province producers dominate exportable powder-grade material through vapor-phase catalytic oxidation units with backward integration into durene feedstock. MEE wastewater discharge standards for maleic anhydride byproduct streams raise operating costs for coal-chemical based manufacturers. Integrated producers in the Yangtze River Delta region control captive supply chains from feedstock through polyimide film extrusion.
United States
Polyimide film demand for aerospace engine components and semiconductor passivation layers sustains qualified supply relationships with premium-grade producers. EPA oversight of air emissions from catalytic oxidation units shapes manufacturing economics for domestic producers. Gulf Coast refinery configuration shifts alter durene availability from petroleum reformate streams, tightening aromatic byproduct feedstock.
Germany
Tier-one automotive suppliers drive disintermediation in resin compounder procurement, consolidating purchase volumes through direct mill relationships for thermal interface material formulations. REACH registration dossier updates through ECHA mandate enhanced toxicological data for cyclic anhydride substances above ten-ton annual thresholds. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate polyimide precursor demand for power electronics applications.
Japan
Polyimide film manufacturers for flexible circuit substrates and advanced packaging have adopted continuous vapor-phase oxidation reactor designs with real-time spectroscopic monitoring fastest. METI industrial standards support sub-ppm impurity profile requirements for semiconductor-grade precursor synthesis. Kanto and Kansai manufacturing clusters require dual-qualified suppliers for foldable display backplane production.
South Korea
Electronics manufacturers specify sub-50-micron powder grades for semiconductor passivation layer precursors with strict lot-traceability requirements. MFDS pharmaceutical regulations create compliance pathways for drug-delivery polymer system derivatives. Seoul Capital Area and Busan-Ulsan industrial zones concentrate demand for high-temperature aromatic polymer precursors.
Pyromellitic Dianhydride Market Competitive Landscape
Global majors compete with regional champions across purity certification tiers, with integrated Chinese producers leveraging captive feedstock control while European and North American incumbents defend aerospace-qualified positions. The vendor base stratifies into three archetypes: backward-integrated coal-chemical operators, specialty-grade pharmaceutical derivative specialists, and distributor-dependent regional compounders. Dominant competitive moves include capacity expansion through process intensification at existing oxidation units and strategic partnerships for REACH registration dossier compliance.
Among German-headquartered specialty chemical producers, Evonik occupies a position exemplifying the aerospace-qualified premium tier through full batch documentation capabilities. Chinese producers including Puyang Shenghuade Chemical and Jiangsu Hualun Chemical represent the integrated manufacturing archetype with in-house durene oxidation and polyimide film extrusion assets. Lonza anchors the pharmaceutical-grade derivative segment where drug-delivery polymer systems command substantial premia over electronics-grade equivalents.
| Leading Market Players |
|---|
| Evonik |
| Puyang Shenghuade Chemical |
| Lonza |
| Shijiazhuang Hope Chemical |
| Sigma-Aldrich |
| Jiangsu Hualun Chemical |
| Arxada |
| Dalian Dragon Win Catalytic |
| Puyang Hengfeng Electronic Insulation Materials |
| Others |
Value Network & Pricing Analysis
Catalytic oxidation specialists in China's Jiangsu province anchor labor-cost differentials that widen spreads between polymer-grade and standard-grade material. REACH dossier compliance costs in Europe and MEE wastewater standards in China feed into tiered pricing structures that separate qualified aerospace suppliers from merchant-market exporters.
Pricing Analysis
Durene feedstock volatility passes through directly to powder-grade quotations, with Gulf Coast refinery yield shifts compressing margins for non-integrated producers. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified batch documentation from electronics-grade spot material and industrial coatings commodity supply. Pricing pressure stems from methylnadic anhydride substitution in sub-200-degree-Celsius epoxy curing applications. Automotive resin compounders exhibit highest price sensitivity due to volume consolidation and direct mill disintermediation, while pharmaceutical-grade derivative buyers accept steep premia for batch consistency.
Supply Chain Analysis
Containerized freight costs from Yangtze River Delta ports to German automotive clusters distort regional price competitiveness for non-integrated distributors. Supply concentrates in China, Japan, and Germany, with Jiangsu and Shandong province producers controlling captive durene oxidation through polyimide film extrusion. Feedstock draws from petroleum reformate byproduct streams and coal-chemical durene synthesis, with refinery configuration shifts creating single-source vulnerability for US Gulf Coast dependent producers. Distribution runs through direct mill relationships above twenty metric tons annually, with chemical distributors retaining sub-containerload fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pyromellitic dianhydride has matured into a late-cycle quality story as foldable display backplane specifications tighten sub-ppm metallic impurity requirements beyond legacy stirred-tank capabilities.
For Market Incumbents: Cement aerospace-qualified supply positions through eighteen-to-twenty-four-month source approval protocol maintenance, defending against Japanese continuous reactor adoption that compresses batch-to-batch variability. Expand in-house durene oxidation capacity in Yangtze River Delta chemical parks to offset MEE wastewater compliance cost pass-through. Lock pharmaceutical-grade derivative channels before Lonza consolidates drug-delivery polymer system supply. For New Entrants and Emerging Players: Real-time spectroscopic monitoring integration offers entry into semiconductor-grade precursor synthesis where legacy producers lag Japanese qualification timelines. Target India's Gujarat and Maharashtra specialty chemicals corridor for import substitution, leveraging absence of indigenous vapor-phase oxidation capacity. Pursue liquid formulation partnerships with German automotive thermal interface material compounders seeking metered-dose processing conversion. For Investors and Strategic Acquirers: Specialty chemical producers with aerospace-qualified assets are the most active acquirer in this space, seeking REACH registration dossier completeness and dual-qualified supplier status. Five-to-ten-year viability hinges on backward integration into durene feedstock or forward integration into polyimide film extrusion. Watch for ECHA toxicological data mandate enforcement above ten-ton thresholds as inflection indicator for importer compliance cost displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Reactor Technology Adoption | Japanese polyimide film manufacturers compress batch variability to one-third of legacy operations through real-time spectroscopic monitoring integration. |
| REACH Registration Dossier Expansion | ECHA toxicological data mandates above ten-ton thresholds filter substandard imports and consolidate qualified supplier pools. |
| Backward Integration into Durene Feedstock | Puyang Shenghuade Chemical anchors cost position through captive coal-chemical oxidation of durene feedstock. |
| Liquid Formulation Capacity Addition | Automotive resin compounders in Germany convert from powder handling to metered-dose processing for thermal interface materials. |
| Pharmaceutical-Grade Derivative Pipeline | Drug-delivery polymer systems command five-to-ten-fold premia over electronics-grade equivalents in MFDS-regulated South Korean markets. |
Research Methodology
Coverage spans China, Japan, Germany, South Korea, and the United States, with primary inputs from each region's polyimide film manufacturing clusters and catalytic oxidation unit operators. Primary interviews with plant managers at vapor-phase oxidation facilities, procurement leads at downstream electronics substrate manufacturers, distribution channel partners handling REACH documentation, and technical R&D directors at resin compounders combined with secondary validation. Secondary sources include customs and trade data from each jurisdiction, ACC and Cefic chemical industry reports, SEC 10-K filings from listed specialty chemical producers, and ECHA registration dossier databases. Bottom-up capacity and utilization estimates triangulate against top-down end-use consumption models.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window, with segmentation modeling across grade tier, end-use industry, physical form factor, and regional production hub. CAGRs derive from trend extrapolation of durene feedstock availability, polyimide film capacity expansion announcements, and regulatory compliance cost trajectories. Industry-specific forecast inputs include semiconductor passivation layer build rates at East Asian advanced packaging facilities and automotive power electronics thermal interface material formulation shifts.
The model holds under stable refinery reformate yields and continued REACH enforcement intensity; deviation in coal-chemical durene cost competitiveness or foldable display adoption slowdown would shift trajectory. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Egypt Acidulants Market
Chemicals
India Metal Treatment Chemical Market
Chemicals
Ferric Oxide Market
Chemicals
Linear Mercaptans Market
Chemicals
Cetostearyl Alcohol Market
Chemicals
Acetic Ether Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Global Aldehyde Market
Chemicals
Pyrogallol Market
Chemicals
Negative Photoresist Chemicals Market
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
North America Oxo-Alcohol Market
Chemicals
Valeryl Chloride Market