
 Formable Films Market | 2026-2036
Formable Films Market Size, Share, and Industry Trends Forecast 2026-2036
Formable Films Market Foresight
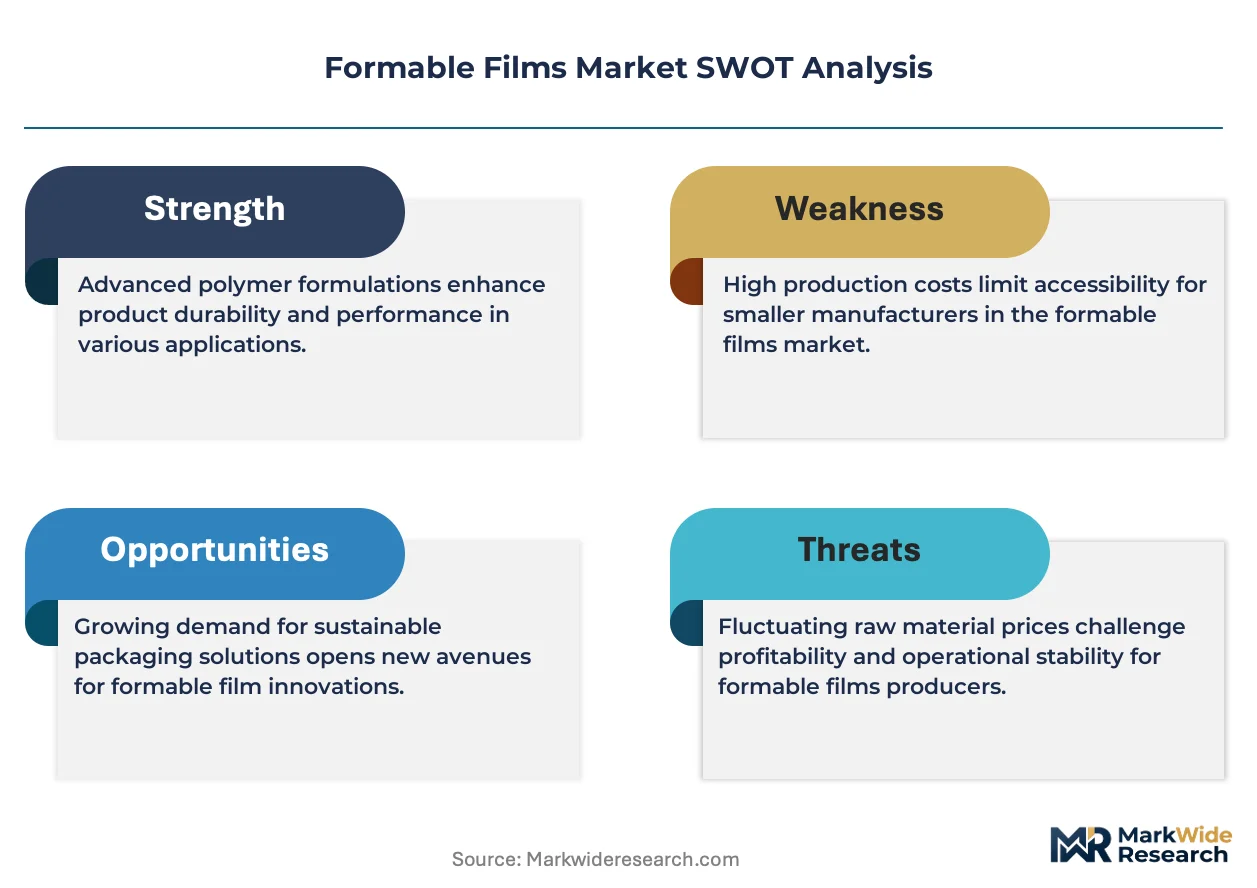
Asset-light leasing models for thermoforming equipment are reshaping competitive entry barriers in formable films, allowing mid-scale packaging converters to access high-performance PET and polypropylene lines without capital-intensive ownership. Amcor plc leverages its integrated resin-to-film platform across multiple continents to sustain cost advantages in pharmaceutical-grade barrier films. Berry Global Group anchors North American supply through controlled distribution networks for food-contact polypropylene. Toray Industries specializes in ultra-thin biaxially oriented films for consumer electronics, differentiating through precision thickness tolerances.
Formable films are thermoplastic sheets engineered to soften under controlled heat and conform to mold geometries, typically spanning 50 to 2,000 microns in gauge, with compositions ranging from amorphous PET to crystalline polypropylene designed for deep-draw thermoforming or vacuum forming. Their primary commercial purpose centers on creating rigid or semi-rigid containers, trays, and blister packs that protect shelf-stable and temperature-sensitive goods across distribution chains. Polyethylene Terephthalate dominates pharmaceutical blister applications where moisture and oxygen barrier properties command premium positioning. Flexible and semi-rigid polypropylene forms represent the fastest-expanding category, driven by hot-fill food packaging and automotive interior panel demand. Polystyrene occupies mature, cost-sensitive segments such as disposable food service trays where margin compression limits innovation investment.
FDA food-contact regulations and EPA emissions standards govern resin additives and extrusion processes in the United States, while REACH and EU MDR in Europe restrict phthalate plasticizers and mandate traceability for medical packaging films. These frameworks elevate compliance costs but simultaneously redirect procurement toward certified suppliers with documented material safety data. Stakeholders must monitor evolving extended producer responsibility mandates and bio-based content thresholds that will determine which resin platforms and form factors retain market access.
Market Dynamics
REACH and EU MDR compliance deadlines are forcing pharmaceutical packaging converters toward medical-grade polypropylene substitutions, compressing legacy PVC supply chains while asset-light equipment leasing models lower entry barriers for mid-scale producers.
Growth Catalysts
- Cold-chain pharmaceutical packaging:Temperature-sensitive biologics distribution is accelerating demand for multi-layer barrier films with validated thermal stability profiles across logistics networks.
- EU MDR traceability mandates:Medical device packaging regulations now require documented material safety data, redirecting procurement toward certified film suppliers with established compliance infrastructure.
- Automotive interior panel lightweighting:Polypropylene thermoformed components are displacing heavier ABS and metal substrates in electric vehicle cabin designs to extend range.
Market Restraints
- Resin price volatility:Propylene and ethylene feedstock costs swing with crude oil indices, squeezing converter margins on fixed-price annual contracts.
- German supply concentration:High-performance biaxially oriented PET capacity clusters in southern Germany, creating single-point vulnerability for European pharmaceutical blister supply.
- Technical thickness limitations:Ultra-thin films below 75 microns struggle to maintain barrier integrity in deep-draw thermoforming without micro-crack defects.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO compliance pathways for imported packaging materials remain underdeveloped, creating first-mover advantage for pre-certified medical-grade film suppliers.
- Bio-based content thresholds:EU Green Deal packaging waste directives will mandate minimum recycled and renewable content, favoring converters with established circular material streams.
- Digital print integration:Combination of thermoforming with inkjet personalization enables lot-level traceability without secondary labeling operations.
Industry Challenges
- Multi-layer coextrusion expertise:Shortage of process engineers capable of tuning barrier layer adhesion in seven-layer structures limits capacity expansion at mid-scale converters.
- MDR technical documentation timelines:European notified body backlogs extend certification cycles for new medical packaging film grades beyond eighteen months.
- Legacy thermoformer retrofit compatibility:Existing vacuum forming lines require tooling and heater zone modifications to process next-generation high-temperature polypropylene formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Formable Films Market |
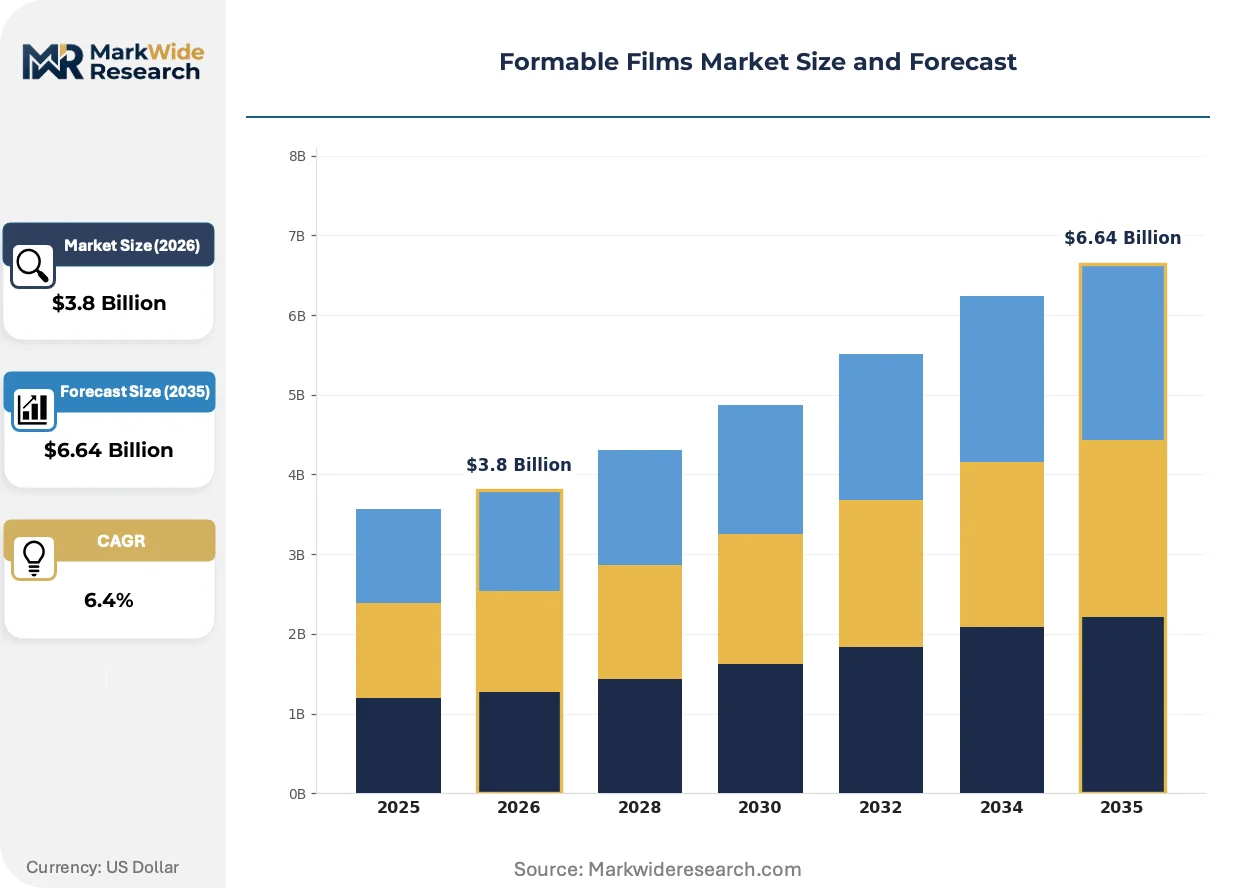
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, Polyvinyl Chloride, Polypropylene, Polystyrene, Polyamide Form: Rigid, Flexible, Semi-Rigid, Laminated, Coated Application: Food Packaging, Pharmaceutical Packaging, Consumer Electronics, Automotive Interiors, Personal Care Products End User: Packaging Manufacturers, Electronics Assemblers, Vehicle Interiors Producers, Cosmetics Firms, Healthcare Product Makers |
| Companies Covered | Amcor plc, Berry Global Group, Sealed Air Corporation, Taghleef Industries, Toray Industries, Jindal Poly Films, Inteplast Group, Sigma Plastics Group, Winpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Formable Films Market Shifts & Advancements
Active barrier technologies and circular material systems are restructuring competitive advantage in formable films, separating converters with integrated resin capabilities from commodity sheet suppliers.
Multi-layer coextrusion with active oxygen scavenging layers is collapsing the performance gap between standard PET and high-cost aluminum-laminated cold-form foils in pharmaceutical applications. Contract packagers serving temperature-sensitive biologics are adopting these structures at accelerated qualification timelines. The technology is collapsing aluminum foil demand in non-extreme barrier blister packs while opening mid-tier pricing bands previously unreachable for polymer-only solutions.
REACH restrictions on phthalate plasticizers in medical-contact materials are eliminating legacy PVC from European pharmaceutical packaging by enforcement deadlines. ECHA substance authorization processes have removed cost-competitive plasticizer alternatives from the approved list. Medical device manufacturers in Germany and Switzerland are completing validation of polypropylene and PETG alternatives ahead of supply contract renewals.
Leasing models for high-output thermoforming lines are displacing capital purchase as the dominant equipment access method among North American food packaging converters. Mid-scale producers now access pharmaceutical-grade cleanroom configurations without balance-sheet commitment. Equipment financiers in the US and Canada are structuring per-unit output contracts that align payment obligations with production volumes rather than fixed amortization schedules.
Formable Films Market Segmentation
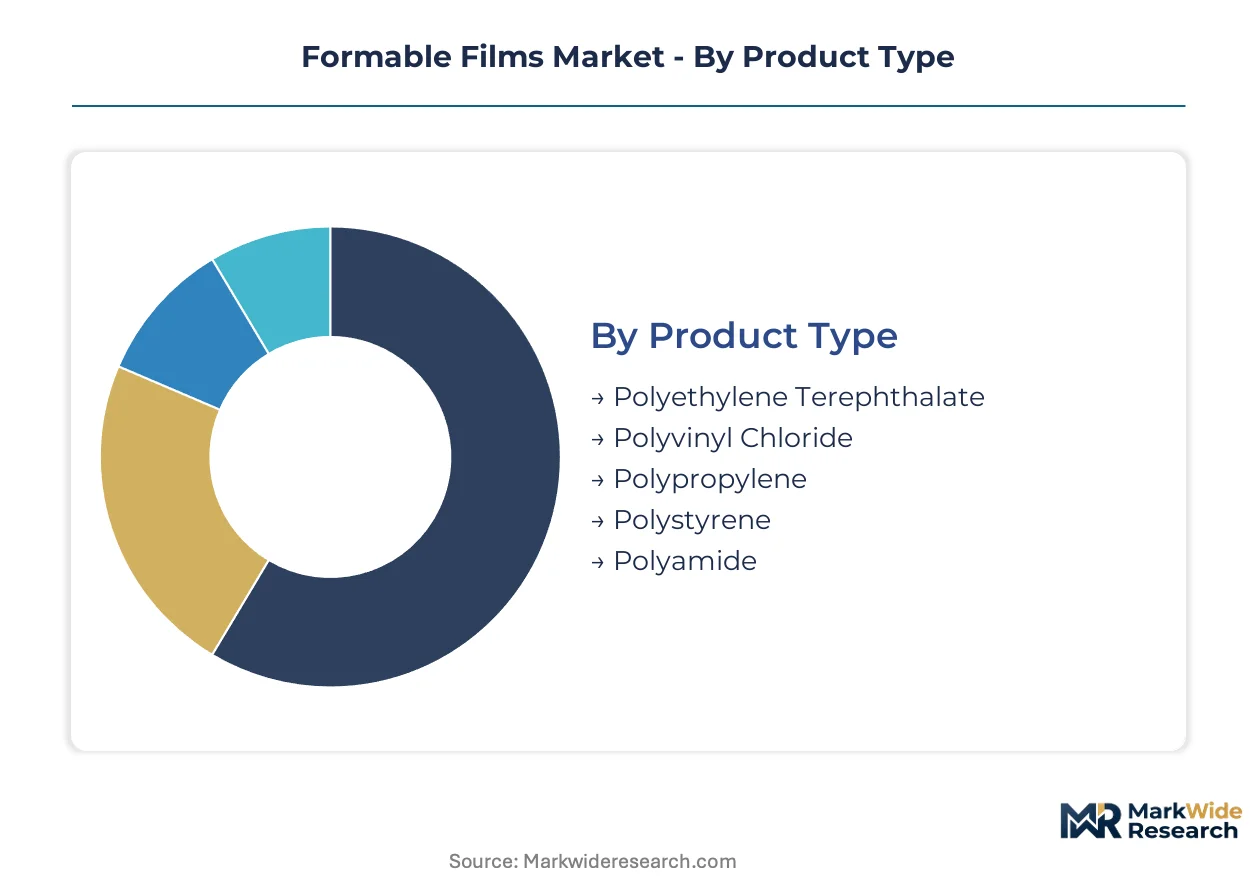
Segmentation in formable films reveals how resin chemistry, physical form, and end-use specifications create distinct competitive arenas with divergent margin structures and compliance requirements. Understanding these divisions exposes where converter capabilities align with buyer procurement criteria across pharmaceutical, food, and industrial applications.
Product Type:
Cost tier determines which resin platforms command premium positioning versus commodity substitution vulnerability in converter procurement decisions.
- Polyethylene Terephthalate:Amorphous and crystalline grades deliver moisture and oxygen barrier performance critical for pharmaceutical blister packs. Demand concentrates in Germany's pharmaceutical manufacturing corridors where EU MDR traceability mandates favor certified medical-grade suppliers with documented safety data.
- Polypropylene:Homopolymer and copolymer formulations span hot-fill food containers to automotive interior panels. Medical-grade specifications are displacing legacy PVC in European healthcare packaging as REACH restrictions eliminate phthalate plasticizers from approved substance lists.
- Polyvinyl Chloride:Legacy material facing accelerated substitution in medical-contact applications due to ECHA authorization barriers for plasticizer alternatives. Retains position in cost-sensitive food service trays where margin compression limits reformulation investment.
- Polystyrene:Crystal and high-impact grades serve disposable packaging segments with minimal barrier requirements. Volume demand clusters in North American quick-service restaurant supply chains.
- Polyamide:Nylon-based films provide puncture resistance and thermal stability for deep-draw automotive components and industrial packaging. Specifications require tight moisture conditioning before thermoforming.
Polyethylene Terephthalate holds installed capacity. Polypropylene is rotating up the share rankings.
Form:
Application requirements dictate whether rigidity, conformability, or multi-layer barrier integration determines specification selection.
- Flexible:Thin-gauge sheets below 200 microns enable wrap-around and pouch formats with heat-seal compatibility. Pharmaceutical contract packagers adopt these structures for biologics distribution where validated thermal stability profiles reduce cold-chain risk.
- Rigid:High-gauge structures above 800 microns maintain dimensional stability for structural trays and clamshells. Food packaging converters in North America leverage these forms for modified atmosphere packaging of fresh proteins.
- Semi-Rigid:Mid-gauge sheets balance formability with structural integrity for deep-draw pharmaceutical blisters and deli containers. This form is gaining share fastest in hot-fill polypropylene applications.
- Laminated:Multi-layer coextrusions combine barrier polymers with adhesive tie layers for oxygen and moisture protection. Active scavenging layers are collapsing performance gaps with aluminum-laminated cold-form foils.
- Coated:Surface-treated films with anti-fog, anti-static, or printable top layers serve display packaging and electronics protection. Specifications require precise coating weight control for optical clarity.
Flexible forms dominate unit volume. Laminated structures are climbing the fastest in value terms.
Application:
Customer type separates buyers with validated qualification requirements from those prioritizing unit cost minimization.
- Pharmaceutical Packaging:Blister packs, cold-form foils, and device trays demand multi-layer barrier films with documented extractables and leachables profiles. EU MDR compliance deadlines are compressing legacy PVC supply chains toward medical-grade polypropylene.
- Food Packaging:Thermoformed trays, cups, and lids span fresh produce to ready-meal segments. Hot-fill and retort applications drive specification toward high-temperature polypropylene with crystallinity control.
- Automotive Interiors:Door panels, instrument cluster housings, and seat backs utilize glass-filled polypropylene for weight reduction versus ABS and metal substrates. Electric vehicle manufacturers specify these components to extend driving range.
- Consumer Electronics:Ultra-thin biaxially oriented films protect displays and circuit boards during assembly and shipment. Thickness tolerances below 5 microns differentiate supplier capabilities.
- Personal Care Products:Cosmetic trays and dispensers emphasize aesthetic surface quality and fragrance barrier properties. Specifications often require custom color matching and embossed textures.
Food packaging holds installed capacity. Pharmaceutical packaging is rotating up the share rankings.
End User:
Supply concentration varies sharply between consolidated automotive tiers and fragmented packaging converters.
- Packaging Manufacturers:Thermoforming converters serving food, pharmaceutical, and consumer goods brands. Asset-light equipment leasing models are lowering entry barriers for mid-scale producers seeking pharmaceutical-grade cleanroom configurations.
- Vehicle Interiors Producers:Tier 1 and Tier 2 automotive suppliers specifying lightweight polypropylene panels. Production gravity centers on Germany's automotive manufacturing corridors with proximity to OEM assembly plants.
- Healthcare Product Makers:Medical device and diagnostics manufacturers with MDR-mandated traceability requirements. Procurement is redirecting toward certified film suppliers with established compliance infrastructure.
- Electronics Assemblers:Display and component manufacturers requiring static-dissipative and ultra-clean packaging. Specifications demand ISO 14644 cleanroom production environments.
- Cosmetics Firms:Beauty and personal care brands with premium positioning requirements. These buyers prioritize aesthetic differentiation and sustainable material credentials over unit cost.
Packaging manufacturers hold installed capacity. Healthcare product makers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in formable films tilts toward German pharmaceutical corridors where EU MDR compliance concentrates procurement among certified suppliers, while North American converters absorb resin volatility through shorter contract structures and equipment leasing flexibility.
United States
FDA food-contact regulations and EPA emissions standards govern resin additives across extrusion operations. Cold-chain biologics distribution accelerates multi-layer barrier film demand from Boston and Research Triangle pharmaceutical clusters. Asset-light thermoforming equipment leasing spreads through Midwestern food packaging converters seeking pharmaceutical-grade cleanroom access without capital commitment.
Germany
EU MDR traceability mandates compress legacy PVC supply chains toward medical-grade polypropylene alternatives. REACH restrictions on phthalate plasticizers eliminate cost-competitive options from approved substance lists. Bavarian pharmaceutical manufacturing corridors concentrate high-performance biaxially oriented PET capacity, creating single-point vulnerability for European blister pack supply.
China
NMPA pharmaceutical packaging regulations tighten material safety documentation requirements for imported films. Yangtze River Delta electronics assemblers drive ultra-thin biaxially oriented film specifications below 5-micron thickness tolerances. Domestic converters expand polypropylene thermoforming capacity for electric vehicle interior panel lightweighting programs.
India
CDSCO compliance pathways for imported medical packaging materials remain underdeveloped, creating qualification bottlenecks for foreign suppliers. Mumbai-Pune pharmaceutical manufacturing belts expand thermoformed tray demand for temperature-sensitive generics export. Domestic converters lack multi-layer coextrusion expertise for seven-layer barrier structures, constraining local supply.
Japan
METI circular economy directives accelerate bio-based content thresholds in packaging procurement guidelines. Kanto region electronics manufacturers specify static-dissipative films with ISO 14644 cleanroom production requirements. Precision thickness control capabilities in Chubu-Nagoya industrial corridors support display protection film demand from semiconductor assembly operations.
Formable Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin and film extrusion. The vendor base organizes around three strategic archetypes: integrated resin-to-film platforms with continental scale, regional converters leveraging leased equipment for flexible capacity, and precision specialists in ultra-thin biaxially oriented structures. Dominant competitive moves include backward integration into captive resin supply and geographic expansion through distribution network control rather than greenfield extrusion capacity.
Among integrated packaging platforms, Amcor plc and Berry Global Group exemplify the resin-to-film archetype with multi-continental production footprints. Toray Industries occupies a position within precision-oriented specialists, with its name signaling Japanese industrial origins in advanced materials. These three anchors illustrate how competitive positioning separates commodity sheet suppliers from converters with integrated formulation capabilities and established regulatory compliance infrastructure.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group |
| Sealed Air Corporation |
| Taghleef Industries |
| Toray Industries |
| Jindal Poly Films |
| Inteplast Group |
| Sigma Plastics Group |
| Winpak |
| Others |
Supply & Pricing Matrix
Bavarian pharmaceutical manufacturing corridors concentrate high-performance biaxially oriented PET capacity, granting certified suppliers pricing leverage over European blister pack converters facing EU MDR compliance deadlines. This geographic clustering feeds downstream cost absorption struggles among mid-scale packaging producers locked into fixed-price annual contracts.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across pharmaceutical and automotive segments. Price differentiation rests on FDA certification tier and volume scale, with medical-grade polypropylene commanding premiums over food-contact specifications. Cost compression in standard PET grades is intensifying because propylene feedstock volatility squeezes converter margins. Quick-service restaurant supply chains exhibit highest price sensitivity, while healthcare product makers prioritize compliance documentation over unit cost.
Supply Chain Analysis
Amcor plc and Berry Global Group hold dominant extrusion capacity across North American and European pharmaceutical corridors. Raw material flows draw from Saudi and Qatari petrochemical complexes for propylene monomer, with biaxially oriented PET resin sourcing from German and Japanese polymer plants. Single-source vulnerability clusters in southern Germany's specialty film capacity. Distribution runs through controlled networks of thermoforming converters with validated cleanroom certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formable films are cycling through a recovery phase as cold-chain pharmaceutical packaging demand rebounds from pandemic-era inventory destocking. Temperature-sensitive biologics distribution acceleration provides the cyclical justification.
For Market Incumbents: Insulate medical-grade polypropylene positions through backward integration into captive resin supply and accelerated EU MDR certification investments. Asset-light equipment leasing models from emerging financiers threaten traditional capital-sale revenue streams. Capacity addition in India's CDSCO-compliant corridors defends against first-mover entrants.
For New Entrants and Emerging Players: India's underpenetrated multi-layer coextrusion market offers immediate white-space opportunity, as domestic converters lack seven-layer barrier expertise for pharmaceutical applications. Brazil's ANVISA-compliant medical packaging segment presents secondary expansion terrain. Go-to-market positioning through pre-certified film import partnerships bypasses eighteen-month notified body backlogs.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision specialists with sub-5-micron thickness tolerance capabilities over commodity sheet suppliers. Long-term viability hinges on active barrier technology integration and circular material stream development. Acquisition targets should display established bio-based content sourcing. Watch for EU Green Deal packaging waste directive threshold announcements as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Resin Supply | Amcor plc's continental resin-to-film platform sustains cost advantages in pharmaceutical-grade barrier films. |
| Medical-Grade Certification Investment | ECHA REACH restrictions eliminate PVC alternatives, redirecting procurement toward certified polypropylene suppliers. |
| Asset-Light Equipment Leasing Expansion | Mid-scale North American converters access pharmaceutical cleanroom configurations without balance-sheet commitment. |
| Active Barrier Technology Integration | Oxygen scavenging layers collapse performance gaps with aluminum-laminated cold-form foils in biologics packaging. |
| India Market Pre-Certification Entry | CDSCO compliance pathways remain underdeveloped, creating qualification bottlenecks for unprepared foreign suppliers. |
Research Methodology
Cross-validation between primary interviews with thermoforming plant managers and secondary trade data anchors the qualitative findings. Stakeholder conversations included pharmaceutical packaging procurement leads, automotive Tier 1 supplier engineers, medical device regulatory affairs directors, and distribution channel partners. Secondary sources encompassed FDA 510(k) filings, ECHA substance authorization databases, customs import records, and SEC 10-K resin segment disclosures. Bottom-up capacity modeling triangulated against top-down end-use demand estimates.
Calibration against historical capacity utilization and resin price elasticity shaped the analytical framework across the analysis window. Segmentation dimensions spanned resin chemistry, gauge form, application vertical, and regional regulatory cluster. CAGRs derived from weighted average of demand-side adoption curves and supply-side expansion timelines. Forecast inputs incorporated electric vehicle interior panel lightweighting programs and cold-chain biologics distribution growth trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by commodity resin producers would shift outcomes. Quarterly review of EU MDR notified body backlog durations and ECHA substance authorization updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Italy Plastic Packaging Films Market
Poly film
Polyester Film Market
Poly film
Multi-Layer Blown Films Market
Poly film
Global Thermoplastic Films Market
Poly film
Brazil Plastic Packaging Films Market
Poly film
Poly Coated Kraft Paper Market
Poly film
North America Plastic Film Packaging Market
Poly film
Poland Plastic Packaging Films Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
Global Polycarbonate Sheets and Films Market
Poly film
Polylaminate Capsules Market
Poly film
APET Film Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
Vinyl Films Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
Polyolefin Battery Separator Films Market