
 Biaxially Oriented Polypropylene (BOPP) Films Market | 2026-2036
Biaxially Oriented Polypropylene (BOPP) Films Market Size, Share, and Industry Trends Forecast 2026-2036
Biaxially Oriented Polypropylene (BOPP) Films Market Outlook
Buyer concentration among multinational food and beverage packagers is hardening, squeezing margin pools for film converters. Taghleef Industries leverages its integrated film production network across Europe and the Americas to sustain supply security for these consolidated accounts. Jindal Poly Films anchors its position through massive manufacturing scale in India, while Cosmo Films Limited differentiates via specialized coatings for high-barrier packaging applications.
Biaxially oriented polypropylene film is a thermoplastic polymer sheet stretched in both machine and transverse directions to achieve high tensile strength, low elongation, and superior moisture barrier properties, serving primarily as a substrate for flexible packaging and label lamination. The 15 micron and 20 micron thickness grades dominate volume shipments due to their optimal balance of material economy and machinability on high-speed form-fill-seal lines. Print grade films command premium positioning in consumer goods labels, whereas metallized variants capture margin pools in snack and confectionery barrier packaging where oxygen and light exclusion determine shelf life.
REACH and RoHS frameworks in Europe restrict phthalate plasticizers and heavy metal additives in food-contact films, redirecting formulation investments toward compliant resin grades. The U.S. FDA maintains stringent migration limits for polypropylene substrates under 21 CFR 177.1520, shaping export qualification protocols for Asian manufacturers. India's BIS certification mandates mechanical and optical testing for domestic film sales, raising compliance costs for smaller extrusion houses. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border packaging supply chains.
Market Dynamics
Multinational food and beverage packagers are consolidating procurement volumes, squeezing margin pools for film converters while demanding supply security across dispersed production footprints. REACH compliance in Europe and BIS certification in India are tightening material standards, redirecting formulation investments toward compliant resin grades and raising barriers for smaller extrusion houses.
Growth Catalysts
- Flexible packaging consumption in India:Rising urbanization and organized retail expansion are accelerating demand for moisture-barrier food packaging substrates in South Asian markets.
- Metallized film technology:Oxygen and light exclusion capabilities in vacuum-metallized BOPP variants are extending shelf life for snack and confectionery applications.
- REACH framework compliance:European restrictions on phthalate plasticizers are redirecting investment toward food-contact-safe resin formulations.
Market Restraints
- Propylene feedstock volatility:Crude oil and naphtha price swings directly compress converter margins in polymer film extrusion.
- Supply concentration in India:Domestic production gravity centers on a handful of massive integrated manufacturers, limiting bargaining power for downstream converters.
- Polyethylene terephthalate substitution:PET films with superior optical clarity are capturing share in premium label applications.
Strategic Opportunities
- High-barrier coatings for pharmaceuticals:Specialized BOPP substrates with enhanced moisture and oxygen resistance are penetrating drug blister packaging.
- E-commerce fulfillment packaging:Tamper-evident and printable film laminates are capturing demand from direct-to-consumer food shipments.
- EU Green Deal alignment:Recyclable mono-material flexible packaging mandates are favoring polypropylene-based solutions over multi-layer alternatives.
Industry Challenges
- Migration testing protocols:FDA 21 CFR 177.1520 qualification timelines stretch 12-18 months for Asian exporters seeking U.S. food-contact approval.
- Twin-screw extrusion expertise:Thin-gauge film production requires specialized process engineering talent scarce outside established manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biaxially Oriented Polypropylene (BOPP) Films Market |
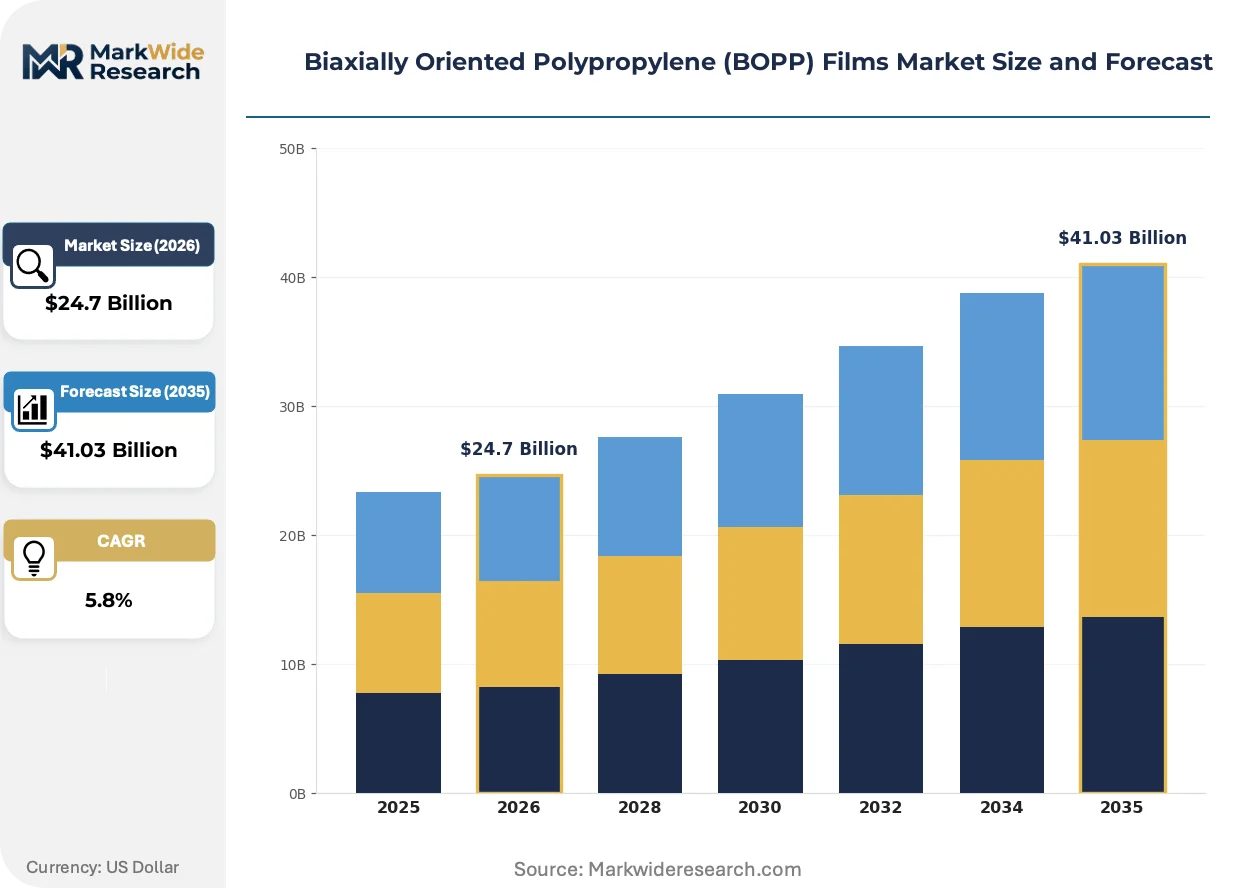
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $41.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Print Grade, Heat Sealable, Transparent, Metallized Application: Packaging, Banking, Labels, Agriculture End User: Food & Beverage, Consumer Goods, Automotive, Healthcare Thickness: 12 Micron, 15 Micron, 20 Micron, 30 Micron |
| Companies Covered | Cosmo Films Limited, Taghleef Industries, Jindal Poly Films, CCL Industries, Uflex Ltd., Toray Industries, Sibur Holdings, Inteplast Group, Zhejiang Kinlead Innovative Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biaxially Oriented Polypropylene (BOPP) Films Market Strategic Shifts
Digital printing compatibility and sustainability certification are reshaping technical specifications across BOPP film procurement. Converter investments now prioritize substrate performance on high-speed inkjet lines and compliance with emerging recyclability frameworks.
Simultaneous stretching line technology is consolidating production economics in the BOPP film sector. High-output tenter frame configurations reduce unit conversion costs by 15-20 percent compared to sequential stretching systems. Major flexible packaging converters in Germany and the United States are specifying these substrates for high-volume snack packaging contracts. The technology is consolidating capacity among integrated producers capable of capital-intensive equipment upgrades.
REACH Annex XVII restrictions on heavy metal additives are forcing reformulation of masterbatch colorants across European food-contact films. ECHA enforcement actions against non-compliant imports have accelerated third-party testing expenditures for Asian exporters. Print-grade film shipments to the European Union now require comprehensive migration documentation, with converters in Italy and Poland investing in in-house analytical laboratories.
Brand-owner sustainability scorecards are rewiring supplier selection criteria in packaged goods. Nestlé and Unilever procurement teams now weight recyclability certifications above price in flexible packaging tenders. Mono-material polypropylene laminates are displacing multi-layer structures in confectionery and bakery applications. This behavioral shift is most visible in Western European markets where extended producer responsibility fees penalize complex packaging constructions.
Biaxially Oriented Polypropylene (BOPP) Films Market Segmentation
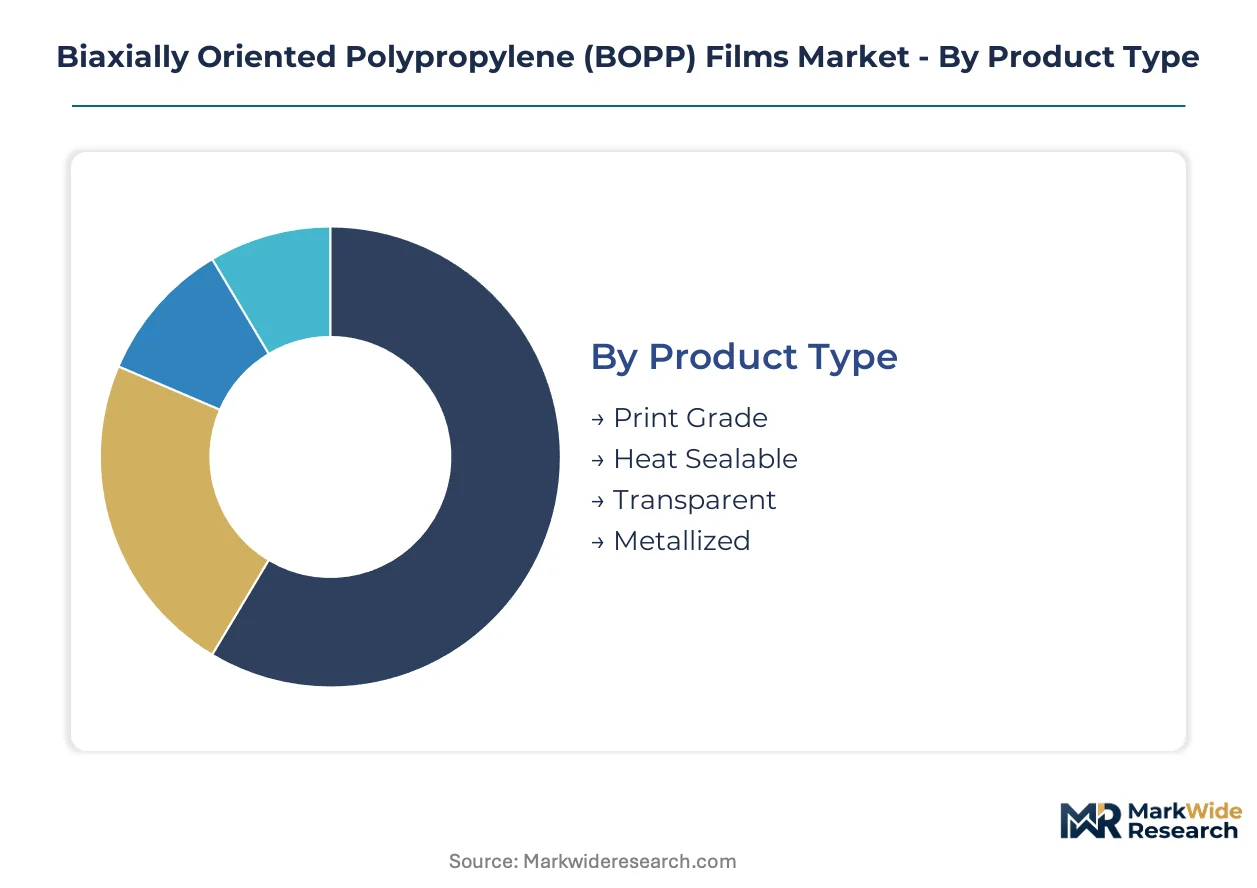
BOPP film specifications diverge sharply across end-use requirements, with thickness grades and surface treatments determining machinability on high-speed packaging lines. Converter procurement teams segment specifications by barrier performance, print receptivity, and seal temperature windows to match substrate performance to application demands.
Product Type:
Equipment refresh cycles in flexible packaging are driving specification upgrades as converters replace legacy lines with digital-capable systems demanding enhanced surface energy control.
- Print Grade:Corona-treated surfaces with dyne levels above 38 mN/m ensure ink adhesion on flexographic and gravure presses. Nestlé and Unilever procurement specifications now mandate print-grade substrates for premium label laminates in Western European markets.
- Metallized:Vacuum-deposited aluminum layers achieve oxygen transmission rates below 0.8 cc/m²/day, extending shelf life for snack and confectionery barrier packaging. Demand concentrates in Germany and Italy where extended producer responsibility fees penalize complex multi-layer alternatives.
- Heat Sealable:Co-extruded sealant layers enable hermetic closure on form-fill-seal equipment at temperatures between 120°C and 140°C.
- Transparent:Optical-grade clarity specifications serve windowed bakery packaging and retail display applications requiring product visibility.
Metallized films sit at the top of the volume ranking, with print grade climbing the fastest as brand-owners prioritize shelf differentiation.
Application:
Cost-tier differentiation separates commodity volume plays from specialized performance segments where technical qualification barriers protect margin pools.
- Packaging:Moisture-barrier substrates for snack, confectionery, and bakery applications constitute the dominant volume segment. Indian flexible packaging consumption is accelerating as organized retail expansion drives demand for extended-shelf-life food substrates in Mumbai and Delhi manufacturing corridors.
- Labels:Pressure-sensitive adhesive face stocks and in-mold label substrates command premium positioning. REACH Annex XVII compliance requirements are redirecting European label converter investments toward phthalate-free resin formulations.
- Banking:Security-grade films with embedded holographic features serve document protection and tamper-evidence applications.
- Agriculture:UV-stabilized greenhouse films and crop protection substrates leverage BOPP's dimensional stability under thermal cycling.
Packaging dominates absolute volume, with labels gaining share fastest on digital printing compatibility requirements.
End User:
Customer-type concentration among multinational packagers is hardening procurement leverage, squeezing converter margins while demanding supply security across dispersed production footprints.
- Food & Beverage:The dominant demand concentration spans moisture-sensitive snacks, confectionery, and ready-to-eat meals. FDA 21 CFR 177.1520 migration limits shape export qualification protocols for Asian manufacturers seeking U.S. market access.
- Consumer Goods:Personal care and household product packaging requires chemical resistance and aesthetic surface finishes. EU Green Deal alignment is favoring mono-material polypropylene laminates over multi-layer structures in Western European markets.
- Healthcare:Sterile barrier packaging and pharmaceutical blister substrates demand enhanced moisture and oxygen resistance.
- Automotive:Interior trim laminates and battery separator applications exploit BOPP's dielectric properties and dimensional stability.
Food and beverage commands the volume base, with healthcare expanding most quickly on high-barrier coating penetration into drug packaging.
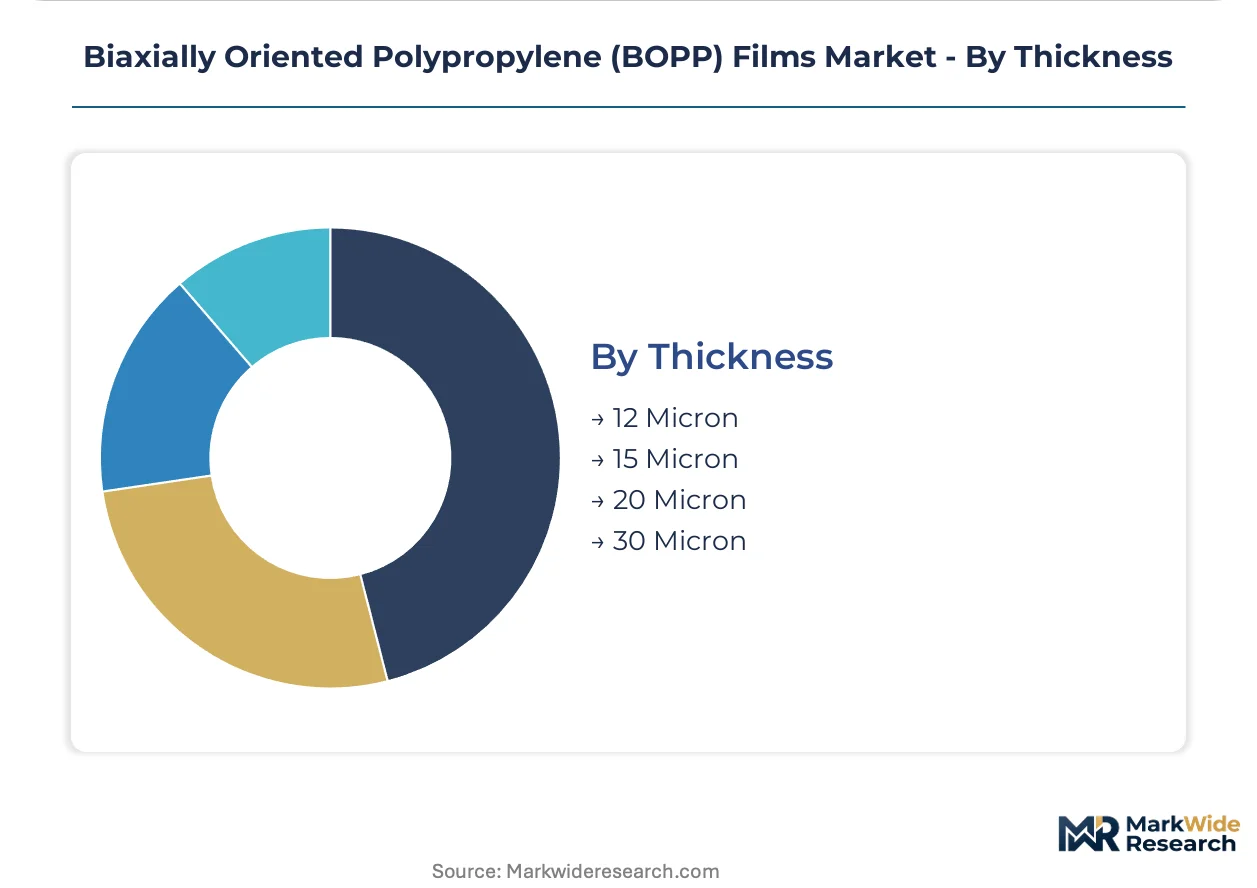
Thickness:
Material economy versus performance trade-offs stratify procurement specifications, with thin-gauge films capturing volume and heavy gauges defending specialty margins.
- 15 Micron:The workhorse specification balances material economy with machinability on high-speed form-fill-seal lines. Indian converters specify this grade for commodity snack packaging where cost compression dominates procurement criteria.
- 20 Micron:Enhanced stiffness and barrier performance serve premium confectionery and bakery applications. BIS certification mandates mechanical testing for domestic sales, raising compliance barriers for smaller extrusion houses.
- 12 Micron:Ultra-thin specifications maximize yield for cost-sensitive label and overwrap applications.
- 30 Micron:Heavy-gauge structural films serve industrial laminates and specialized barrier constructions.
15 micron holds the volume leadership position, with 20 micron gaining fastest on premium packaging specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized extrusion engineers cluster in established manufacturing corridors across Germany, India, China, the United States, and Italy. These technical workforces anchor regional supply networks for high-speed tenter frame operations.
Germany
Automotive interior laminates and battery separator applications drive technical film demand. REACH Annex XVII restrictions on heavy metal additives redirect masterbatch investments toward compliant resin systems. The Ruhr industrial corridor hosts converter operations supplying flexible packaging to Nestlé and Unilever procurement teams.
India
Organized retail expansion in Mumbai and Delhi accelerates consumption of moisture-barrier snack packaging substrates. BIS certification mandates mechanical and optical testing for domestic film sales, raising compliance barriers for smaller extrusion houses. Jindal Poly Films anchors massive manufacturing scale in the national market.
China
E-commerce fulfillment packaging for direct-to-consumer food shipments expands substrate demand. GB standards for food-contact plastics shape formulation protocols for export-oriented extrusion houses. The Yangtze River Delta concentration serves both domestic flexible packaging converters and international label laminators.
United States
High-speed form-fill-seal line upgrades specification requirements for 15 micron and 20 micron grades. FDA 21 CFR 177.1520 migration limits stretch qualification timelines to 12-18 months for Asian exporters. The Midwest manufacturing belt concentrates converter operations serving Frito-Lay and Mondelez procurement contracts.
Italy
Extended producer responsibility fees penalize complex multi-layer packaging constructions, favoring mono-material polypropylene laminates. ECHA enforcement actions against non-compliant imports accelerate third-party testing expenditures. Northern Italian converter clusters invest in in-house analytical laboratories for migration documentation.
Biaxially Oriented Polypropylene (BOPP) Films Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the BOPP film sector. The market structure consolidates around integrated resin-to-film producers capable of capital-intensive simultaneous stretching line upgrades. Three archetypes dominate: massive integrated manufacturers with captive resin supply, specialized coating technology providers, and regional extrusion houses serving domestic procurement contracts. Competitive moves center on backward integration into propylene feedstock and geographic expansion into high-growth flexible packaging corridors.
Within the integrated manufacturing tier, Jindal Poly Films and Taghleef Industries exemplify scale-driven positioning. Cosmo Films Limited occupies a specialist position in high-barrier coating applications. These three entities anchor the competitive landscape through distinct strategic postures—Indian manufacturing scale, transatlantic production networks, and differentiated surface technology respectively.
| Leading Market Players |
|---|
| Cosmo Films Limited |
| Taghleef Industries |
| Jindal Poly Films |
| CCL Industries |
| Uflex Ltd. |
| Toray Industries |
| Sibur Holdings |
| Inteplast Group |
| Zhejiang Kinlead Innovative Materials |
| Others |
Value Chain & Pricing Dynamics
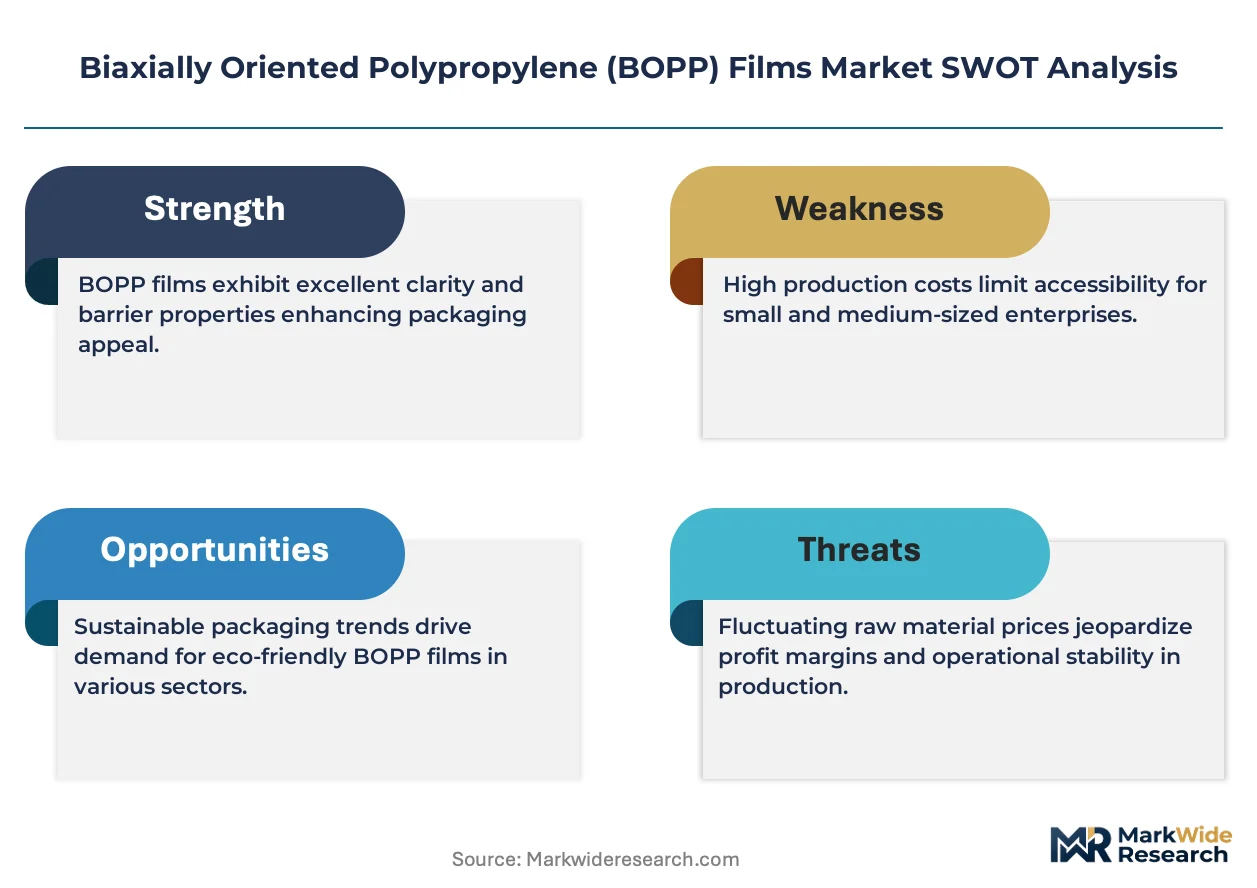
Certification-grade divergence between FDA-qualified export tiers and domestic commodity grades splits pricing power across converter segments, with REACH-compliant metallized films commanding sustained premiums while uncertified commodity extrusions face margin compression from propylene feedstock volatility. This bifurcation concentrates supply security investments among integrated producers capable of captive resin supply and in-house migration testing laboratories.
Pricing Analysis
Capacity additions in India are reshaping price floors for 15-micron commodity grades, forcing smaller extrusion houses toward thinner-gauge specialization or coating differentiation to escape cost compression. Contract-based long-term offtake agreements dominate procurement between multinational packagers and integrated manufacturers, with price differentiation resting on BIS certification status and FDA 21 CFR 177.1520 qualification completion. Margins are tightening in the standard-grade segment due to buyer consolidation among Nestlé and Unilever procurement teams, while premium metallized variants defend pricing power through oxygen-barrier performance specifications. Commodity snack packaging converters exhibit highest price sensitivity, whereas pharmaceutical blister packaging buyers prioritize barrier certification over unit cost.
Supply Chain Analysis
Direct-to-converter channels handle high-volume procurement from integrated manufacturers, with distributor networks serving fragmented label and agricultural film demand. Propylene feedstock draws from naphtha crackers concentrated in India, China, and Germany, with polymer resin supply anchored in integrated petrochemical corridors along the Yangtze River Delta and Gujarat industrial belt. Twin-screw extrusion equipment and specialized tenter frame engineering create single-source vulnerability for thin-gauge production capability. Distribution runs through converter operations in Mumbai, Delhi, and the Ruhr corridor before reaching downstream flexible packaging laminators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification upgrades toward high-barrier pharmaceutical grades and EU Green Deal-aligned mono-material laminates reward technical differentiation over volume scale.
For Market Incumbents: Deploy simultaneous stretching line technology to consolidate unit conversion economics against sequential system competitors. Backward integration into propylene feedstock secures margin defense against naphtha price volatility, while in-house migration testing laboratories accelerate FDA qualification timelines threatened by Asian export competition. Capacity rationalization in commodity grades preserves capital for high-barrier coating R&D where Cosmo Films Limited has established technical leadership. For New Entrants and Emerging Players: Specialty pharmaceutical converters represent the most penetrable buyer archetype, underserved by qualified suppliers capable of enhanced moisture and oxygen resistance specifications. E-commerce fulfillment packaging for direct-to-consumer food shipments offers white-space demand with shorter qualification cycles than FDA-regulated segments. A coating-technology-first go-to-market angle bypasses capital-intensive extrusion scale requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where simultaneous stretching line capability concentrates among integrated producers capable of capital-intensive equipment upgrades. Long-term viability favors asset-light coating specialists with pharmaceutical qualification pathways over commodity extrusion exposure. The signal to watch is extended producer responsibility fee expansion beyond Western Europe into Asian markets, accelerating mono-material polypropylene laminate demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstock | Captive resin supply insulates Jindal Poly Films from naphtha price volatility compressing converter margins. |
| High-Barrier Coating Technology Investment | Specialized moisture and oxygen resistance penetrates pharmaceutical blister packaging with technical qualification barriers. |
| Simultaneous Stretching Line Upgrade | High-output tenter frame configurations reduce unit conversion costs by consolidating production economics. |
| FDA 21 CFR 177.1520 Qualification Acceleration | In-house migration testing laboratories compress 12-18 month approval timelines for Asian export market access. |
| EU Green Deal Alignment Certification | Recyclable mono-material laminates capture extended producer responsibility fee advantages in German and Italian markets. |
Study Parameters
Coverage spans Germany, India, China, the United States, and Italy, with primary inputs from each regional manufacturing corridor. Plant managers at integrated film extrusion facilities, procurement leads at multinational food and beverage packagers, distribution channel partners serving label converters, and technical R&D directors in coating formulation provided structured interviews. Secondary validation drew from customs and trade data, BIS and FDA regulatory filings, SEC 10-K disclosures from listed packaging conglomerates, and flexible packaging industry association reports. Bottom-up capacity and utilization estimates triangulated against top-down demand modeling from end-use consumption patterns.
Rate-of-change decomposition across the analysis window separates volume growth from specification mix-shift toward premium grades. Segmentation dimensions modeled include product type, application end-use, thickness grade, and regional production hub concentration. CAGRs were derived from fitted growth curves against historical extrusion capacity additions and converter procurement survey data. Industry-specific forecast inputs incorporated propylene feedstock price scenario modeling and REACH regulatory amendment tracking.
Underlying measurement precision varies by segment; metallized and pharmaceutical-grade specifications carry tighter precision than commodity snack packaging due to concentrated supplier bases. Forecasts reflect assumptions regarding organized retail expansion rates in India, EU Green Deal implementation timelines, and propylene supply-demand balances. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyethylene Cast Film Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
Brazil Plastic Packaging Films Market
Poly film
Americas Polypropylene (PP) Films Market
Poly film
US Cleanroom Film and Bags Market
Poly film
Global BOPP Films Market
Poly film
Nylon Films Market
Poly film
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Light Reflective Film Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Soft Touch Film Market
Poly film
Global Cast Polypropylene Packaging Films Market
Poly film
Isotropic Film Market
Poly film
UAE Plastic Packaging Films Market
Poly film
Cast Stretch Packaging Films Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market