
 Americas Polypropylene (PP) Films Market | 2026-2036
Americas Polypropylene (PP) Films Market Size, Share, and Industry Trends Forecast 2026-2036
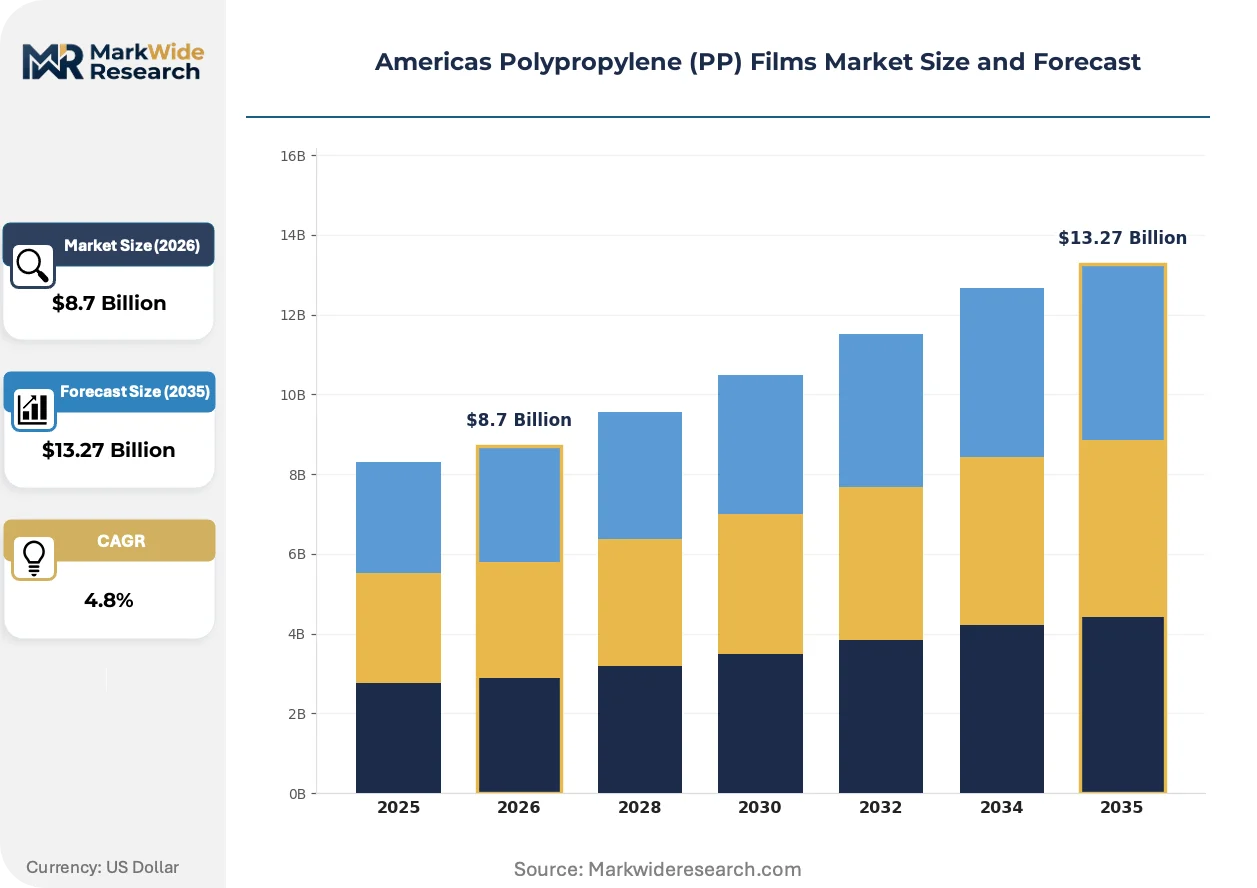
Americas Polypropylene (PP) Films Market Outlook
Multilayer coextrusion is tilting manufacturing economics toward higher-performance barrier films. Toray Plastics (America) Inc. leverages Japanese-origin biaxial orientation technology to anchor premium optical-grade supply to North American label converters. Berry Global Inc. sustains massive thermoforming feedstock capacity across its integrated film-to-container operations. Inteplast Group Corporation dominates commodity-grade cast film output through Gulf Coast resin proximity and captive rail logistics.
Americas Polypropylene (PP) Films are thermoplastic polymer sheets produced via cast, blown, or biaxially oriented processes, typically spanning 10 to 150 microns in thickness, engineered for moisture resistance, heat sealability, and print receptivity across packaging and industrial laminations. Flexible Films command the largest volume share due to snack food, confectionery, and fresh produce wrapping requirements, while Biodegradable Films represent the fastest-expanding margin pool as brand owners face extended producer responsibility frameworks. Rigid Films retain structural importance in thermoformed medical trays and automotive interior cladding where dimensional stability exceeds flexibility requirements.
FDA food-contact compliance under 21 CFR 177.1520 governs resin additives and migration limits, directly constraining formulation choices for healthcare and food packaging grades. California's SB 54 mandates source reduction and recyclability benchmarks that PP film converters must meet by specified compliance windows, while Mexico's COFEPRIS aligns pharmaceutical blister packaging with USP Class VI standards for cross-border medical device supply. Stakeholders must monitor how evolving state-level extended producer responsibility laws interact with federal preemption debates to determine where compliance investment yields durable competitive position.
Market Dynamics
Multilayer coextrusion technology is compressing unit economics for barrier-grade films while California's SB 54 mandates force rapid reformulation across the US flexible packaging base, creating simultaneous pull and push forces on converter margins.
Growth Catalysts
- Source reduction mandates:California SB 54 and New York's extended producer responsibility frameworks are compelling brand owners to specify recyclable mono-material structures, directly expanding addressable demand for PP-based flexible packaging solutions.
- Snacks and fresh produce wrapping:North American food processors are migrating from multi-material laminations to oriented PP films to achieve heat-seal integrity and moisture barrier performance without compromising mechanical recycling streams.
- Biaxial orientation lines:Capital deployment across the US Gulf Coast and Mexico's Bajío region is expanding capacity for optical-grade label films serving premium beverage and personal care segments.
Market Restraints
- Propylene feedstock volatility:Gulf Coast cracker maintenance cycles and ethane-propane price spreads create margin compression for non-integrated film converters lacking captive resin supply.
- Recycling infrastructure gaps:Mechanical recycling streams for PP films remain underdeveloped across most Latin American collection systems, limiting circular economy claims and post-consumer content incorporation.
- Polyethylene substitution:Linear low-density polyethylene films retain cost advantages in non-barrier applications, constraining PP penetration in commodity bread bags and overwrap segments.
Strategic Opportunities
- Mexico pharmaceutical blister films:COFEPRIS alignment with USP Class VI standards for medical device packaging creates export-qualified capacity expansion potential serving North American healthcare supply chains.
- Chemical recycling feedstock partnerships:Pyrolysis-based monomer recovery investments by resin producers enable certified-circular PP film grades commanding premium positioning against virgin-only competitors.
- E-commerce protective mailers:Lightweight bubble and quilted film formats are displacing paper-based cushioning in parcel logistics, opening specialty PP foam-lamination demand from fulfillment operators.
Industry Challenges
- Migration testing protocols:FDA 21 CFR 177.1520 compliance for food-contact additives requires extended laboratory validation timelines that delay new product commercialization by quarters.
- Legacy equipment retrofit costs:Converting lines originally configured for PVC or PET films demand substantial die and cooling modifications to achieve gauge uniformity with PP melt rheology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Polypropylene (PP) Films Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Films, Rigid Films, Coated Films, Biodegradable Films End Use Industry: Packaging, Automotive, Construction, Healthcare Thickness: Below 20 Microns, 20-50 Microns, 51-100 Microns, Above 100 Microns Delivery Mode: Rolls, Sheets, Custom Sizes, Pre-formed Bags |
| Companies Covered | Toray Plastics (America) Inc., Inteplast Group Corporation, Taghleef Industries LLC, Altopro S.A. de C.V., Oben Holding Group S.A., Berry Global Inc., Amcor PLC, Cheever Specialty Paper & Film, Cosmo Films Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Polypropylene (PP) Films Market Strategic Shifts
Process control systems and material formulation science are converging to enable thinner-gauge films with preserved performance, compressing resin intensity per packaging unit while meeting escalating barrier specifications from brand owners.
Machine-vision inspection systems paired with real-time thickness profiling are digitizing quality assurance across biaxial orientation lines. Premium label converters in the US Northeast are adopting these platforms to eliminate manual sampling delays and reduce off-spec roll generation. The technology is digitizing how optical-grade film producers defend margin position against commodity competitors through yield optimization rather than volume scaling.
FDA's evolving guidance on post-consumer recycled content in food-contact applications is tightening additive purity requirements for mechanical recycling streams. This regulatory trajectory favors film converters with established relationships to certified-clean PCR suppliers over opportunistic spot-market sourcing. Healthcare and infant nutrition packaging segments are responding most aggressively, specifying virgin-only resins pending clearer compliance pathways for recycled incorporation.
Brand-owner sustainability scorecards are compressing supplier qualification cycles from annual reviews to quarterly performance audits. Major North American beverage and snack companies are unbundling film supply agreements into shorter-term contracts with embedded recyclability milestones. This pattern is most pronounced among CPG headquarters clusters in Chicago and Minneapolis, where procurement functions have consolidated sustainability accountability within direct materials sourcing teams.
Americas Polypropylene (PP) Films Market Segmentation
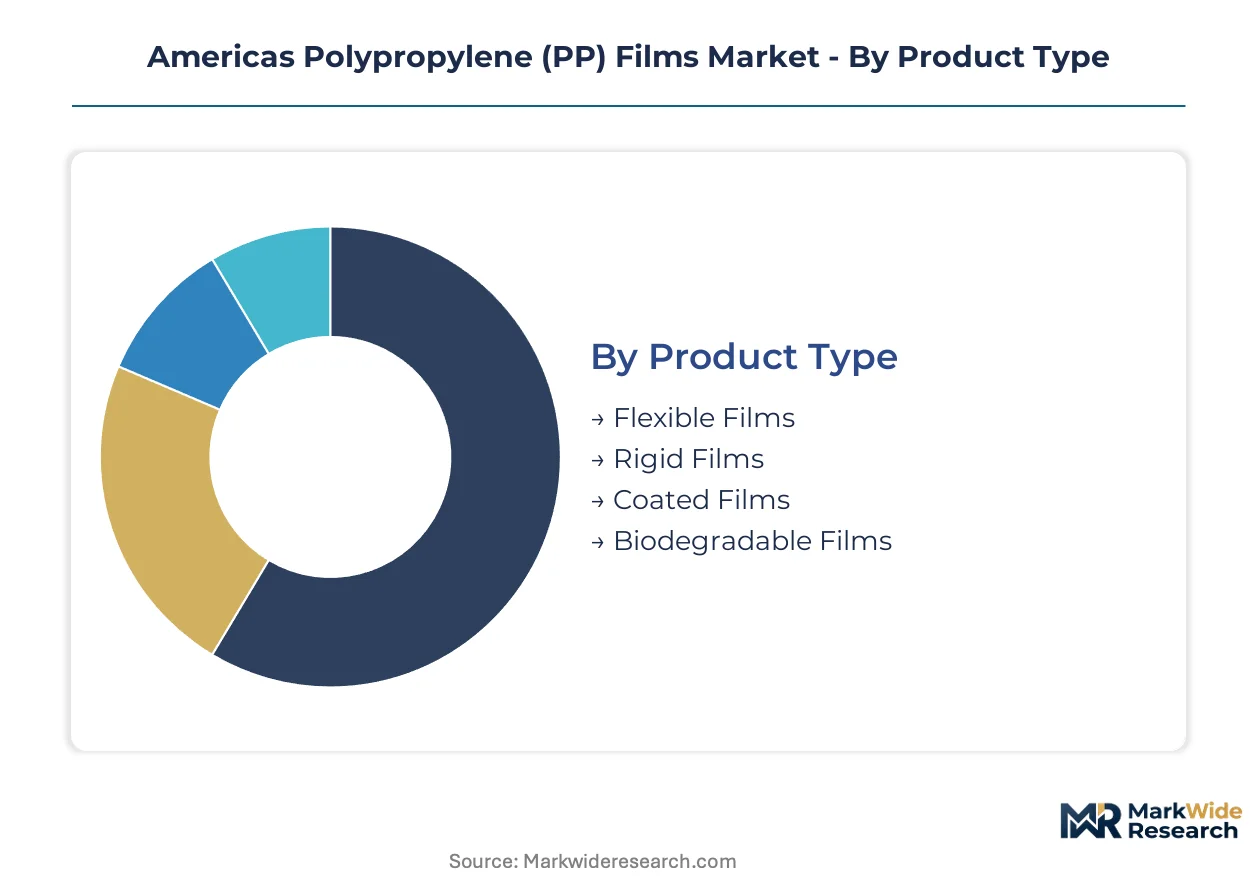
Segmentation in Americas Polypropylene Films reveals how resin grade, gauge tolerance, and delivery format interact to determine converter margins and customer lock-in. Each dimension carries distinct supply chain logic that shapes procurement patterns across the US Gulf Coast and Mexican conversion corridors.
Product Type:
Cost tier differentiation separates commodity-grade output from barrier-performance and sustainability-premium categories across converter portfolios.
- Flexible Films:Cast and blown processes yield 10-50 micron gauges optimized for heat-seal layers and print receptivity. Snack food and fresh produce wrapping in the US Midwest and Mexico's Bajío region concentrate demand as brand owners migrate from multi-material laminations to mono-material recyclable structures.
- Biodegradable Films:Additive-modified or bio-based resin formulations degrade under industrial composting conditions. California's SB 54 compliance windows and New York extended producer responsibility frameworks are accelerating brand-owner specifications for certified-compostable flexible packaging in food-contact applications.
- Rigid Films:Higher-crystallinity grades deliver dimensional stability for thermoforming operations. Medical tray production and automotive interior cladding in Michigan and Ohio represent core demand clusters.
- Coated Films:PVDC or acrylic surface treatments enhance oxygen and moisture barrier performance. Premium beverage label converters in the US Northeast specify coated biaxially oriented grades for shelf-life extension.
Flexible Films commands the established base. The steepest expansion runs through Biodegradable Films.
End Use Industry:
Application-specific performance requirements create divergent specification regimes across FDA-regulated and industrial-grade segments.
- Packaging:Food, beverage, and personal care flexible wrapping absorbs the majority of regional film tonnage. FDA 21 CFR 177.1520 compliance for migration limits and California SB 54 recyclability mandates are simultaneously constraining formulation choices and expanding addressable demand for mono-material PP solutions.
- Healthcare:Pharmaceutical blister packs and medical device pouches demand USP Class VI resin purity and COFEPRIS alignment for cross-border Mexican supply. Thermoformed tray sterilization compatibility and seal integrity requirements exceed standard packaging specifications.
- Automotive:Interior cladding, acoustic insulation facing, and composite reinforcement applications favor rigid and filled film grades. Michigan and Ohio assembly plant proximity drives regional converter concentration.
- Construction:Vapor barriers, roofing underlayment, and geotextile applications specify UV-stabilized heavy-gauge films. Texas and Florida building code compliance for moisture management shapes regional demand patterns.
Packaging absorbs the dominant volume share. Healthcare is climbing the fastest on regulatory premium and cross-border qualification requirements.
Thickness:
Volume economics and performance thresholds stratify across gauge bands that determine line speed, yield rates, and end-use suitability.
- 20-50 Microns:The workhorse range for flexible food packaging, label facestock, and lamination substrates. Biaxial orientation lines across the US Gulf Coast optimize output for this gauge band to balance mechanical properties with resin efficiency.
- Below 20 Microns:Ultra-thin downgauging for source reduction mandates and lightweight e-commerce mailers. California SB 54 source reduction benchmarks and brand-owner sustainability scorecards are accelerating specifications for sub-20 micron structures that preserve barrier performance.
- 51-100 Microns:Heavy-duty industrial wrapping and construction-grade vapor barriers. Texas petrochemical corridor converters supply this band for export to Latin American infrastructure projects.
- Above 100 Microns:Thermoforming feedstock and rigid structural applications. Medical tray deep-draw requirements and automotive interior forming operations in Michigan specify these gauges for dimensional stability.
20-50 Microns dominates current output. Below 20 Microns is gaining share fastest on source reduction compliance and e-commerce lightweighting.
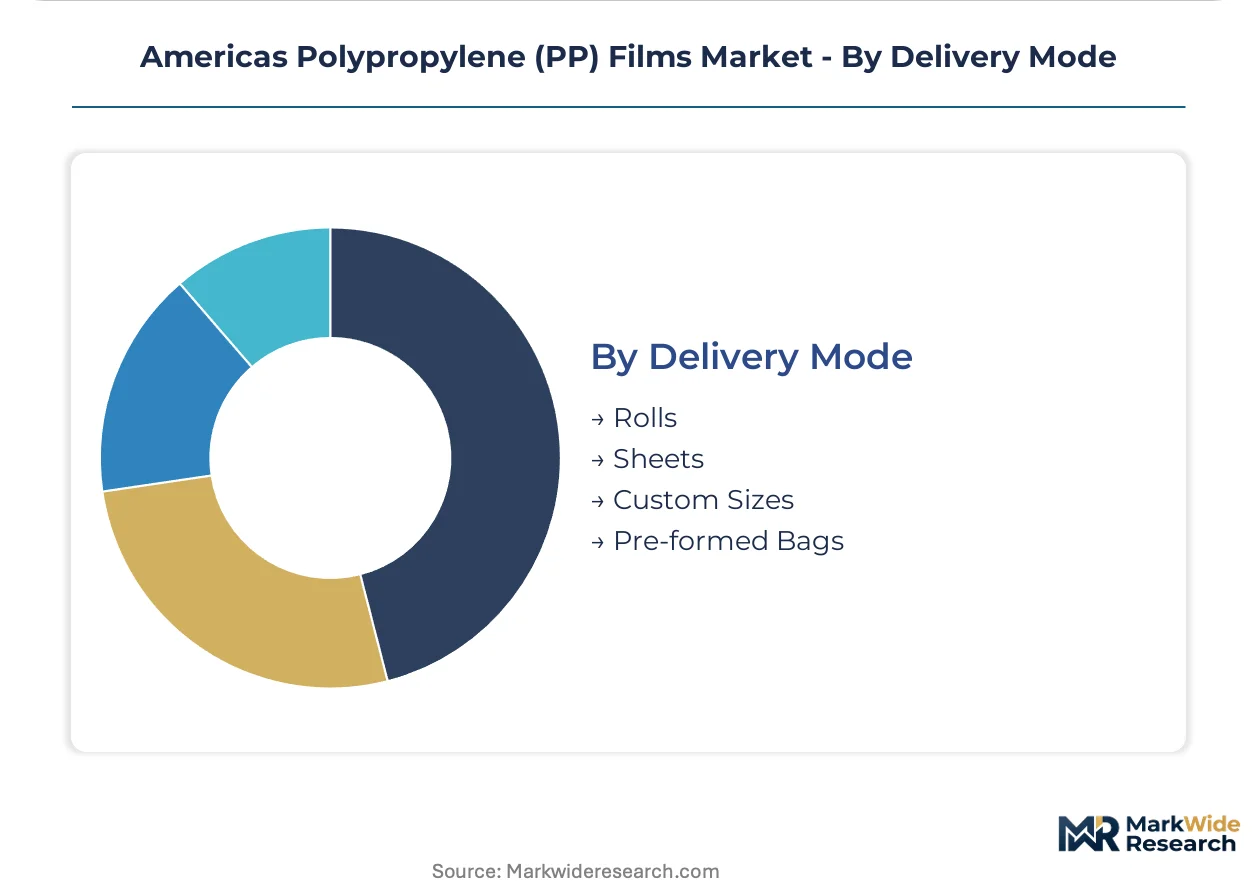
Delivery Mode:
Customer type and operational integration determine format preferences that reshape converter logistics and working capital requirements.
- Rolls:Standard mill-width wound formats for high-volume flexible packaging converters. Gulf Coast resin proximity and captive rail logistics enable competitive delivered pricing to Midwest and Northeast label and lamination operations.
- Sheets:Cut-to-size formats for thermoforming and printing operations lacking slitting capability. Mexican Bajío region automotive and medical device converters favor sheet delivery to minimize in-house processing investment.
- Pre-formed Bags:Finished flexible packaging for direct food processor and fulfillment operator integration. Chicago and Minneapolis CPG headquarters procurement teams are consolidating specifications for pre-formed recyclable mono-material bags.
- Custom Sizes:Non-standard widths and lengths for specialized industrial and construction applications. Project-based demand from Latin American infrastructure developments drives spot-market activity in this segment.
Rolls represents the volume anchor. Pre-formed Bags is expanding most quickly as brand owners outsource conversion steps and consolidate supplier bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican converters in the Bajío region export pharmaceutical-grade films to US healthcare distributors, while Gulf Coast producers supply flexible packaging substrates to Midwest food processors. This cross-border trade architecture shapes capacity deployment and regulatory compliance investment across the hemisphere.
United States
California SB 54 mandates are accelerating mono-material PP specifications for snack food and fresh produce wrapping. FDA 21 CFR 177.1520 compliance requirements constrain additive choices for food-contact grades. The US Gulf Coast petrochemical corridor anchors biaxial orientation capacity expansion serving premium beverage label converters.
Mexico
COFEPRIS alignment with USP Class VI standards is driving pharmaceutical blister film qualification for cross-border medical device supply. The Bajío region—spanning Guanajuato, Querétaro, and Aguascalientes—hosts automotive and medical device clusters demanding thermoforming-grade rigid films. Nuevo León's Monterrey metro area concentrates pre-formed bag conversion for US e-commerce fulfillment operators.
Canada
Health Canada food-contact regulations parallel FDA migration limits, enabling integrated North American qualification protocols for flexible packaging exporters. Ontario's manufacturing belt near Toronto sustains demand for coated barrier films serving premium personal care brands. Prairie province agriculture processors specify heavy-gauge industrial wrapping for grain and fertilizer export logistics.
Brazil
ANVISA pharmaceutical packaging standards are converging with USP benchmarks, opening qualified film export potential to North American healthcare supply chains. São Paulo state's food processing corridor drives flexible film consumption for snack and confectionery wrapping. Rio Grande do Sul's petrochemical complex supports cast film output for regional flexible packaging converters.
Chile
Fresh produce export logistics—particularly salmon and fruit cold-chain packaging—generate specialized barrier film demand from Valparaíso and Santiago logistics hubs. The country's extended producer responsibility framework is accelerating specifications for recyclable mono-material structures. Northern mining regions specify UV-stabilized heavy-gauge films for industrial equipment wrapping and geotextile applications.
Americas Polypropylene (PP) Films Market Competitive Environment
Channel-controlling players compete with product-specialist players across three discernible tiers. Integrated resin-to-film operators leverage Gulf Coast feedstock proximity against independent converters dependent on spot resin markets. Japanese-origin technology licensors, North American packaging conglomerates, and Latin American regional specialists represent the dominant strategic archetypes. Capacity expansion and backward integration into captive resin supply constitute the primary competitive moves reshaping margin structures.
Among Japanese-technology players, Toray Plastics (America) Inc. exemplifies premium optical-grade positioning through biaxial orientation expertise. Berry Global Inc. and Amcor PLC occupy positions within the integrated packaging conglomerate tier, commanding thermoforming feedstock and flexible packaging conversion networks. Inteplast Group Corporation anchors commodity-grade cast film supply through captive logistics infrastructure.
| Leading Market Players |
|---|
| Toray Plastics (America) Inc. |
| Inteplast Group Corporation |
| Taghleef Industries LLC |
| Altopro S.A. de C.V. |
| Oben Holding Group S.A. |
| Berry Global Inc. |
| Amcor PLC |
| Cheever Specialty Paper & Film |
| Cosmo Films Inc. |
| Others |
Value Chain & Pricing Dynamics
Gulf Coast cracker utilization rates above 85% are compressing spot resin availability and tilting converter procurement toward contract offtake structures. This tightness propagates through biaxial orientation lines as integrated producers capture margin through captive supply while independent converters absorb volatility.
Pricing Analysis
Biaxial orientation line generation gaps separate premium optical-grade pricing from commodity cast film tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier performance and FDA food-contact certification grade. Pricing pressure stems from polyethylene substitution in bread bag and overwrap segments where LLDPE retains cost advantages. Brand owners in Chicago and Minneapolis procurement clusters exhibit highest price sensitivity, while pharmaceutical blister film buyers prioritize USP Class VI compliance over unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard across Gulf Coast resin suppliers financing converter working capital. Geographic supply concentration centers on the US Gulf Coast, Mexico's Bajío region, and São Paulo state's petrochemical corridor. Raw material dependencies draw from propylene monomer, ethane-propane feedstock blends, and additive masterbatches. Single-source vulnerability runs through Japanese-origin biaxial orientation technology licensors. Distribution runs through captive rail logistics to Midwest flexible packaging converters and cross-border trucking to Mexican medical device clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas Polypropylene Films Market sits in early-cycle expansion as California SB 54 and New York extended producer responsibility frameworks accelerate mono-material specification shifts. Regulatory tailwinds are expanding addressable demand faster than capacity deployment.
For Market Incumbents: Entrench Gulf Coast resin integration through backward control over cracker output and biaxial orientation line expansion. Berry Global and Toray Plastics should deepen certification investment for FDA 21 CFR 177.1520 and USP Class VI tiers to defend against polyethylene substitution in non-barrier segments. Channel control through pre-formed bag supply agreements with Chicago and Minneapolis CPG headquarters consolidates volume commitment.
For New Entrants and Emerging Players: Build out Mexico pharmaceutical blister film capacity serving cross-border US healthcare supply chains where COFEPRIS-USP alignment creates qualification barriers. The Bajío region automotive and medical device clusters present underpenetrated rigid film demand. A go-to-market angle targeting e-commerce protective mailer specifications for lightweight bubble and quilted formats bypasses entrenched food packaging incumbents.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biaxial orientation capacity as optical-grade line deployments require $50-100 million per installation. Long-term viability favors integrated resin-to-film operators with Gulf Coast feedstock proximity over spot-market-dependent converters. Acquisition targets should exhibit captive rail logistics or established PCR supplier relationships. The signal to watch is pyrolysis-based chemical recycling partnership announcements by major resin producers enabling certified-circular premium positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Gulf Coast cracker proximity secures margin capture against propylene feedstock volatility. |
| Biaxial Orientation Line Expansion | US Gulf Coast and Mexico Bajío deployment serves premium beverage label converter demand. |
| FDA 21 CFR 177.1520 Certification Investment | Extended laboratory validation timelines create qualification moats for food-contact grades. |
| Chemical Recycling Feedstock Partnership | Pyrolysis-based monomer recovery enables certified-circular PP film premium positioning. |
| Pre-formed Bag Conversion Capacity | Chicago and Minneapolis CPG procurement consolidation favors outsourced flexible packaging supply. |
Study Parameters
A standing panel of biaxial orientation line operators, flexible packaging procurement managers at CPG headquarters, pharmaceutical blister film quality directors, and Gulf Coast resin supply planners provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FDA 21 CFR filings, California SB 54 regulatory text, SEC 10-K disclosures by packaging conglomerates, and ACC petrochemical capacity databases. Bottom-up volume modeling triangulated against top-down value estimates derived from trade flow analysis.
Scenario-bracketing framed low, base, and high cases across the projection horizon without prescribing probability weights. Segmentation dimensions modeled include product type tier, end-use industry vertical, thickness gauge band, and delivery mode format. CAGRs were synthesized from capacity utilization trajectories, regulatory compliance timeline assumptions, and substitution elasticity estimates between PP and polyethylene films. Feedstock cost curves and extended producer responsibility policy implementation schedules served as industry-specific forecast inputs.
Sensitivities concentrate around California SB 54 enforcement rigor, Gulf Coast cracker maintenance cycle timing, and chemical recycling scale-up velocity. Forecasts embed assumptions regarding mono-material adoption rates and cross-border pharmaceutical qualification alignment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
US Cleanroom Film and Bags Market
Poly film
Global Polyethylene Packaging Market
Poly film
Isotropic Film Market
Poly film
Poly Tubing Market
Poly film
Egypt Plastic Packaging Films Market
Poly film
Formable Films Market
Poly film
Brazil Plastic Packaging Films Market
Poly film
Global Cast Polypropylene Packaging Films Market
Poly film
Cellulose Film Packaging Market
Poly film
Global BOPET Packaging Films Market
Poly film
Italy Plastic Packaging Films Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
PVC Film for Medical Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
Wrap Around Label Films Market
Poly film
Polypropylene Film Market