
 Polyethylene Furanoate (PEF) Barrier Resin Market | 2026-2036
Polyethylene Furanoate (PEF) Barrier Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Furanoate (PEF) Barrier Resin Market Insights
Capital-intensity divergence between pilot-scale biorefinery operators and incumbent petrochemical resin giants is redrawing competitive boundaries in PEF barrier resin. Avantium leverages its proprietary YXY technology and integrated FDCA-to-PEF pilot plant in Geleen to anchor European supply chain development. Origin Materials sustains a biomass-to-chemicals platform focused on chloromethylfurfural intermediates, positioning for downstream PEF copolymer supply. ALPLA competes through blow-molding expertise and packaging format partnerships that bridge resin availability to finished beverage bottle demand.
Polyethylene Furanoate (PEF) barrier resin is a furan-based aromatic polyester synthesized from 2,5-furandicarboxylic acid (FDCA) and monoethylene glycol, exhibiting oxygen permeability roughly tenfold lower than conventional polyethylene terephthalate (PET) and enabling monolayer packaging without additional barrier coatings. Its primary industrial purpose centers on replacing multilayer and metalized packaging structures in oxygen-sensitive applications while maintaining mechanical recyclability within existing PET streams. Homopolymer grades currently dominate pilot production volumes due to simpler process chemistry and clearer regulatory pathways for food-contact approval, though copolymer formulations incorporating comonomers like isosorbide are gaining traction for tunable thermal and barrier properties in pharmaceutical container segments. Blow molding applications for beverage bottles concentrate the largest near-term margin pools, while film and sheet formats for food packaging represent faster-growing channels as downstream coating and thermoforming infrastructure adapts.
The European Food Safety Authority (EFSA) and U.S. FDA regulate food-contact substance notifications for novel bio-based polymers, with EFSA's evolving guidance on recycling processes for PEF-PET coprocessing streams directly shaping market access timelines. EU REACH compliance for FDCA monomer registration and the Packaging and Packaging Waste Regulation's escalating recycled content thresholds are accelerating brand-owner procurement mandates that favor PEF's drop-in compatibility. Stakeholders must monitor FDA premarket notification pathways for copolymer variants and the pace at which EU member states transpose extended producer responsibility rules into national enforcement frameworks.
Market Dynamics
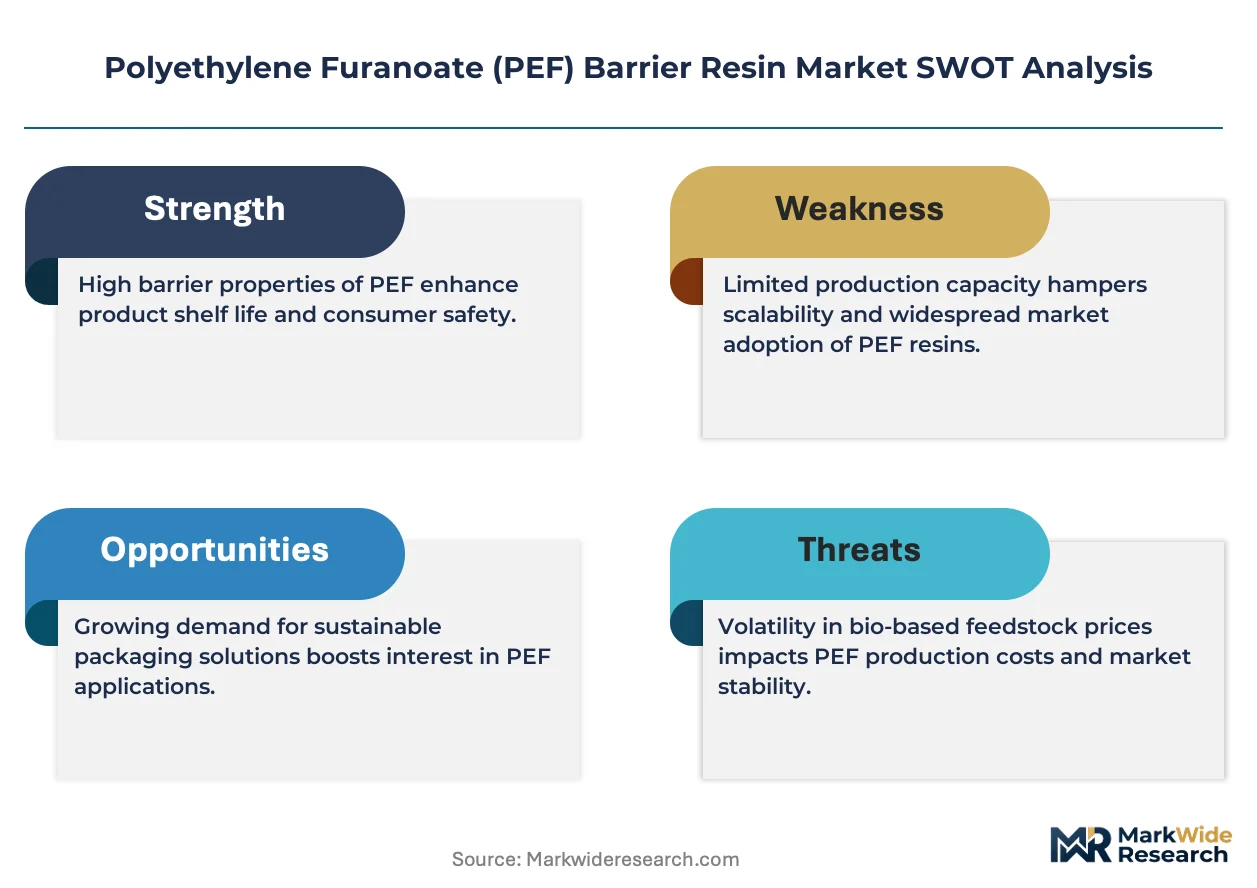
Commercial-scale FDCA production scarcity concentrates PEF resin supply in a single Dutch facility, creating a bottleneck that shapes procurement timelines and pricing power across European beverage packaging supply chains.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Escalating recycled content mandates push brand owners toward bio-based drop-in alternatives compatible with existing PET recycling infrastructure.
- Beverage bottlers:Carbonated soft drink and still water producers are scaling PEF procurement for monolayer oxygen barrier bottles that eliminate multilayer complexity.
- Oxygen permeability performance:PEF's tenfold barrier improvement over conventional PET enables thinner-wall designs and reduced material intensity in sensitive food applications.
Market Restraints
- FDCA feedstock concentration:Pilot-scale biorefinery output limits resin availability, with European supply anchored to a single Geleen production cluster.
- Capital intensity gap:Petrochemical incumbents command scale advantages in incumbent polyester production that bio-based challengers cannot yet match.
- Food-contact approval pathways:EFSA and FDA notification timelines for novel polymer grades extend commercialization horizons beyond typical investment cycles.
Strategic Opportunities
- Pharmaceutical container segments:Copolymer formulations incorporating isosorbide offer tunable thermal properties for vial and blister pack applications.
- Film and sheet formats:Thermoforming infrastructure adaptation is opening faster-growing channels beyond beverage blow molding.
- Extended producer responsibility frameworks:EU member state transposition of packaging waste rules creates procurement mandates favoring mechanically recyclable bio-based structures.
Industry Challenges
- Process chemistry expertise:FDCA-to-PEF polymerization requires specialized catalysis knowledge scarce outside dedicated biorefinery operations.
- Coprocessing standardization:Sorting and reprocessing infrastructure for PEF-PET mixed streams remains underdeveloped, complicating circular economy claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Furanoate (PEF) Barrier Resin Market |
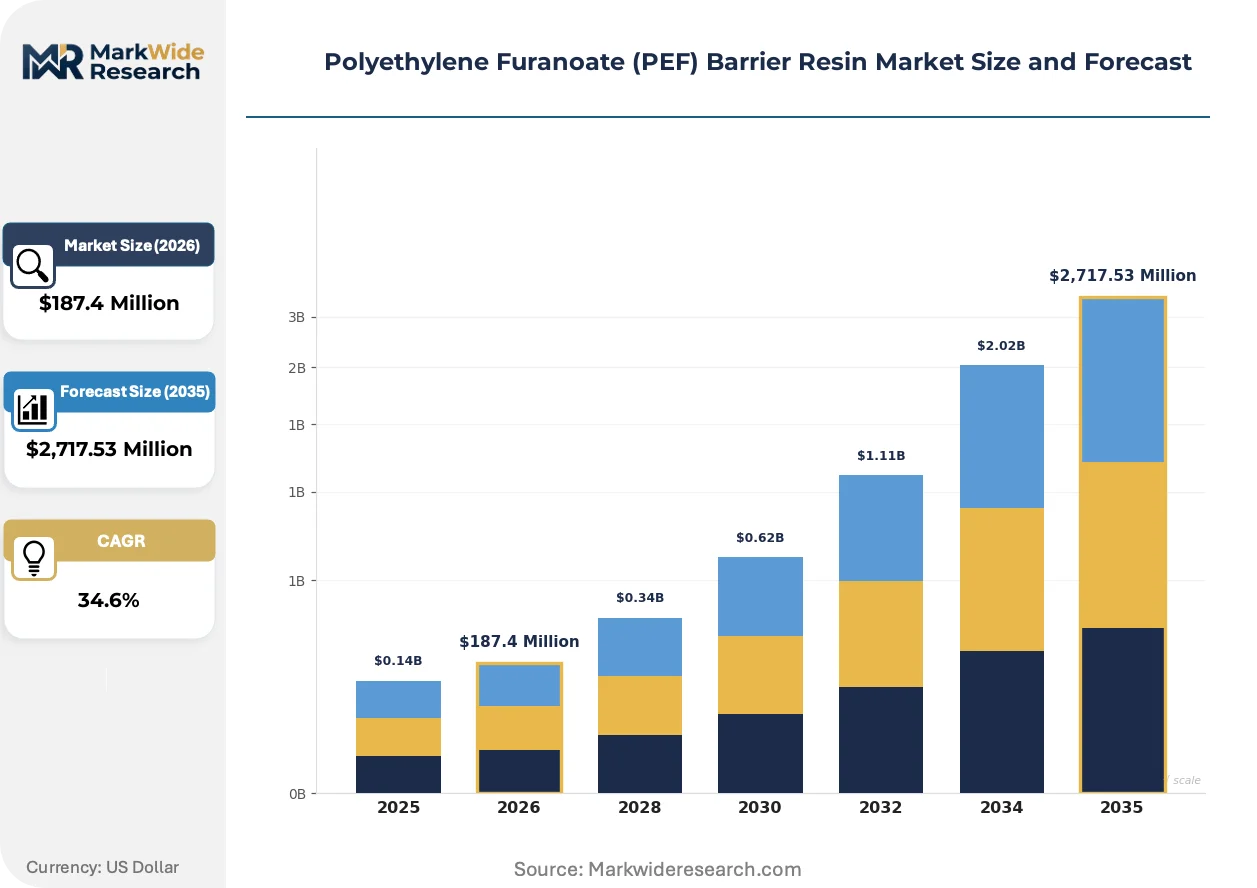
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,717.53 Million |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Resin Type: Homopolymer, Copolymer, Terpolymer, Composite Application: Beverage Bottles, Food Packaging, Pharmaceutical Containers, Cosmetic Jars End User Industry: Beverage Manufacturers, Food Producers, Pharmaceutical Companies, Personal Care Brands Packaging Format: Film, Sheet, Injection Molding, Blow Molding |
| Companies Covered | Avantium, ALPLA, Toyobo Co., Ltd., Mitsubishi Chemical Group, Teijin Limited, Sulzer Ltd, Origin Materials, Danone, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Furanoate (PEF) Barrier Resin Market Trends and Innovations
Process intensification and regulatory harmonization are compressing development cycles for bio-based barrier materials, with pilot-to-commercial transitions now determining competitive positioning.
Continuous flow reactor designs for FDCA catalytic oxidation are decomposing batch production bottlenecks that historically constrained furan platform chemical output. Specialty chemical operators in the Netherlands and Germany are retrofitting existing oxidation assets to accommodate sugar-derived feedstocks. This technology diffusion is compressing capital requirements for regional PEF resin entrants.
REACH registration requirements for FDCA monomer variants are tightening substance documentation obligations for bio-based polymer suppliers seeking European market access. ECHA's evolving guidance on polymer notification thresholds is forcing reformulation strategies for copolymer grades. Food-contact applications face the steepest compliance burden, with registrants prioritizing homopolymer dossiers.
Direct resin procurement from biorefinery operators is displacing traditional petrochemical distributor networks among mid-sized beverage converters. Brand-owned sustainability targets are shortening supplier qualification cycles and compressing incumbent resin incumbents' specification lock-in. This channel restructuring is most visible in Benelux and northern Germany, where proximity to pilot production enables just-in-time offtake arrangements.
Polyethylene Furanoate (PEF) Barrier Resin Market Segmentation
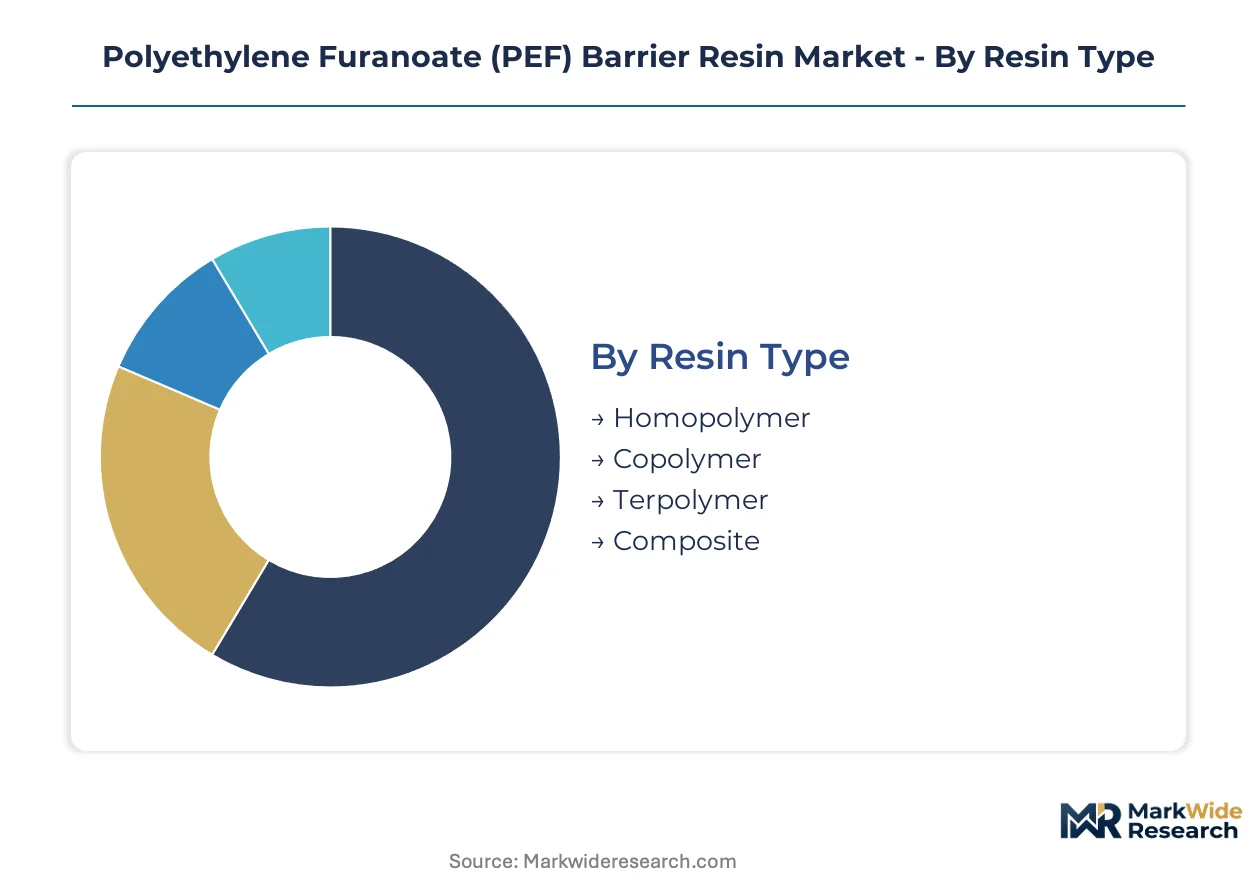
PEF barrier resin segmentation reveals how polymer chemistry, application requirements, and processing constraints interact to shape procurement decisions across oxygen-sensitive packaging categories. Understanding these segment boundaries helps identify where bio-based alternatives face the strongest substitution pressure from incumbent materials.
Resin Type:
Substitution pressure from conventional PET and bio-based PLA concentrates most intensely on simpler polymer architectures with established regulatory pathways.
- Homopolymer:Pure FDCA-ethylene glycol polyester chains deliver the highest oxygen barrier performance and crystallinity. Beverage bottlers in the Netherlands and Germany concentrate procurement here due to clearer EFSA food-contact approval timelines and straightforward mechanical recyclability within existing PET streams.
- Copolymer:Incorporation of comonomers like isosorbide or succinic acid tunes thermal properties and processing windows. Pharmaceutical container manufacturers favor these grades for vial applications requiring sterilization compatibility, though FDA notification pathways extend commercialization cycles.
- Terpolymer:Three-monomer systems balance barrier, clarity, and ductility for specialized film extrusion.
- Composite:Mineral-filled or nanoclay-reinforced formulations target cost reduction in non-food industrial packaging.
Homopolymer retains volume leadership; copolymer holds the steepest expansion curve.
Application:
Cost tier stratification separates premium oxygen-sensitive applications from commodity formats where PEF's performance advantages struggle to justify price premiums.
- Beverage Bottles:Carbonated soft drink and still water packaging demands maximum oxygen ingress protection with monolayer construction. Avantium's Dutch production cluster anchors European supply to Coca-Cola and Carlsberg procurement programs targeting recycled-content compliance.
- Food Packaging:Thermoformed trays and flexible films for meat, cheese, and ready meals represent faster-growing channels as coating infrastructure adapts. German and Italian converters pilot PEF sheet extrusion for modified-atmosphere applications.
- Pharmaceutical Containers:Blister packs and prescription vials require extractables testing and USP compliance.
- Cosmetic Jars:Premium skincare packaging leverages bio-based marketing claims over functional barrier requirements.
Beverage bottles command the dominant revenue share; food packaging is expanding most quickly.
End User Industry:
Customer type determines specification stringency, with regulated industries imposing qualification barriers that filter out smaller resin suppliers.
- Beverage Manufacturers:Scale procurement and sustainability mandates from Coca-Cola, PepsiCo, and Danone compress supplier qualification timelines. Direct offtake agreements with biorefinery operators displace traditional petrochemical distributors in Benelux supply chains.
- Food Producers:Nestlé and Unilever pilot programs concentrate on extended shelf-life meat and dairy applications.
- Pharmaceutical Companies:Bayer and Novo Nordisk evaluate PEF for primary packaging with stringent extractables profiles.
- Personal Care Brands:L'Oréal and Beiersdorf test bio-based jar formats for premium positioning.
Beverage manufacturers anchor procurement volume; pharmaceutical companies present the longest adoption runway.
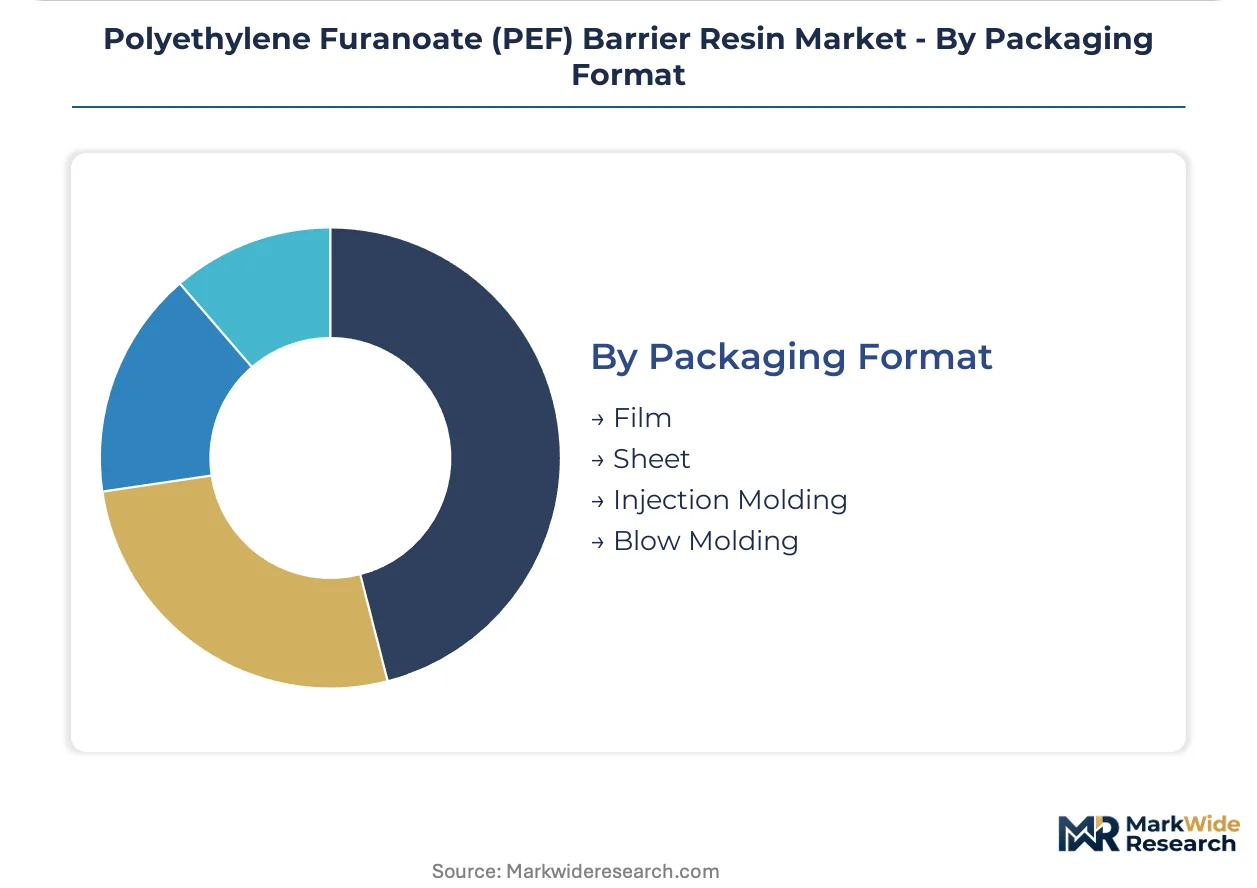
Packaging Format:
Processing maturity varies sharply across conversion technologies, with blow molding infrastructure adaptation outpacing film and sheet thermoforming.
- Blow Molding:Stretch-blow equipment for carbonated beverage bottles requires minimal retrofit for PEF's slightly narrower processing window. ALPLA and Sidel collaborate on line trials at Dutch pilot facilities.
- Film:Cast and blown film extrusion for flexible food packaging demands slower crystallization control. German converters retrofit lines for PEF-PE multilayer structures.
- Sheet:Thermoforming feedstock for trays and clamshells requires nucleation optimization.
- Injection Molding:Preform and cosmetic jar production leverages existing PET toolsets with temperature adjustments.
Blow molding dominates near-term resin absorption; film extrusion is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage bottlers in the Netherlands absorb PEF resin at price premiums that German converters reject, while Japanese pharmaceutical packers prioritize performance over cost. This demand-elasticity contrast shapes regional procurement patterns across the forecast window.
Netherlands
Coca-Cola and Carlsberg procurement programs anchor European PEF offtake for carbonated beverage bottles. The EU Packaging and Packaging Waste Regulation tightens recycled content mandates that favor bio-based drop-in compatibility. Avantium's Geleen production cluster concentrates pilot-scale FDCA supply, with direct resin agreements displacing traditional petrochemical distributors.
Germany
Food packaging converters pilot PEF sheet extrusion for modified-atmosphere meat and dairy trays. ECHA's REACH registration requirements for FDCA monomer variants tighten substance documentation obligations for suppliers. The Ruhr industrial corridor hosts thermoforming line retrofits as coating infrastructure adapts to bio-based barrier materials.
United States
Origin Materials sustains biomass-to-chemicals platform development for downstream PEF copolymer supply. FDA premarket notification pathways for novel polymer grades extend commercialization timelines beyond typical investment cycles. The Southeast packaging belt evaluates PEF-PE multilayer structures for flexible food applications.
Japan
Pharmaceutical container manufacturers favor copolymer grades with tunable thermal properties for vial and blister pack sterilization compatibility. METI's bio-economy strategy supports furan platform chemical development through public-private partnerships. The Osaka-Kobe industrial zone concentrates polymer processing expertise for oxygen-sensitive medical packaging.
China
Domestic beverage brands test PEF monolayer bottles for premium water positioning against multilayer PET alternatives. MIIT's dual carbon goals accelerate bio-based material substitution mandates in coastal manufacturing zones. The Yangtze River Delta hosts pilot blow-molding trials as local converters assess processing window compatibility.
Polyethylene Furanoate (PEF) Barrier Resin Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with biorefinery operators commanding catalysis expertise while petrochemical incumbents retain scale advantages in polyester production. The market structure concentrates around pilot-scale FDCA producers with integrated polymerization capabilities, creating a supply bottleneck that shapes procurement timelines. Three archetypes dominate: proprietary technology licensors, packaging converters with blow-molding partnerships, and diversified chemical groups with oxidation asset retrofit potential. Competitive moves center on capacity expansion at commercial-scale FDCA facilities and strategic partnerships bridging resin availability to finished packaging demand.
Among Dutch-anchored technology developers, Avantium occupies a position exemplifying integrated FDCA-to-PEF production. ALPLA represents the packaging converter archetype, sitting within blow-molding expertise that bridges resin supply to beverage bottle demand. Origin Materials anchors the biomass-to-chemicals platform approach, with a focus on chloromethylfurfural intermediates positioning for downstream copolymer supply.
| Leading Market Players |
|---|
| Avantium |
| ALPLA |
| Toyobo Co., Ltd. |
| Mitsubishi Chemical Group |
| Teijin Limited |
| Sulzer Ltd |
| Origin Materials |
| Danone |
| Amcor |
| Others |
Pricing and Supply Chain Analysis
FDCA-to-PEF substitution of petroleum-derived PTA in polyester synthesis simultaneously concentrates supply geography around Dutch pilot-scale biorefineries and inflates pricing power for integrated producers commanding scarce catalysis expertise. Brand-owner procurement mandates under EU recycled-content rules compress negotiation leverage for mid-sized beverage converters.
Pricing Analysis
After-sales service bundling around technical support and regulatory compliance documentation drives lifetime value for PEF resin suppliers. Three-tier pricing structure across pharmaceutical-grade copolymers, food-contact homopolymers, and industrial composite grades reflects EFSA certification status and volume scale. Cost compression in beverage-grade homopolymers intensifies as Avantium's Geleen facility expands pilot output. Mid-sized German food converters exhibit highest price sensitivity; Japanese pharmaceutical packers prioritize barrier performance over cost.
Supply Chain Analysis
Inventory lead times stretching 12-18 months for commercial-scale FDCA offtake agreements reflect polymerization capacity scarcity. Supply concentrates in the Netherlands, with secondary sourcing emerging from German specialty chemical retrofits and US biomass-to-chemicals platforms. Feedstock dependencies on fructose-derived intermediates, monoethylene glycol, and proprietary YXY catalyst systems create single-source vulnerability around Avantium's technology licensing. Direct procurement from biorefinery operators displaces traditional petrochemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat story, where EFSA and FDA food-contact approval timelines create switching costs that cement early movers' positions against late entrants.
For Market Incumbents: Shield market position by accelerating backward integration into FDCA feedstock production and securing long-term fructose supply agreements with agricultural processors. Patent thickets around continuous-flow oxidation catalysis deter emerging biorefinery competitors. Prioritize EFSA homopolymer dossier completion to extend specification lock-in with Coca-Cola and Carlsberg procurement programs.
For New Entrants and Emerging Players: Service-layer gaps in pharmaceutical copolymer technical support and extractables testing documentation present white-space opportunities. Target Japanese and German pharmaceutical container segments where FDA notification expertise commands premium pricing. Pursue joint development agreements with thermoforming equipment manufacturers to bypass beverage bottle channel saturation.
For Investors and Strategic Acquirers: The market sits at a pilot-to-commercial transition phase that favors integrated technology licensors with captive catalysis platforms. Five-to-ten-year viability hinges on FDCA production cost curves achieving parity with PTA. Acquisition targets should display oxidation asset retrofit capability and REACH registration progress. Monitor EU member state transposition of extended producer responsibility rules as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Commercial-Scale FDCA Capacity Expansion | Avantium's Geleen plant debottlenecking determines European resin availability for beverage bottlers. |
| Backward Integration into Feedstock Supply | Origin Materials' biomass platform secures fructose supply chains independent of commodity sugar markets. |
| Pharmaceutical Copolymer Certification Investment | Isosorbide-modified grades unlock sterilization-compatible vial applications with USP compliance pathways. |
| Long-Term Supply Agreement with Brand Owners | Direct offtake contracts with Danone and Nestlé displace distributor intermediaries in Benelux procurement. |
| Joint Venture with Blow-Molding Equipment OEM | ALPLA's Sidel collaboration accelerates line trial data for stretch-blow processing window optimization. |
Research Methodology
Initial hypotheses were tested against primary input from biorefinery operations directors, beverage procurement leads, pharmaceutical packaging engineers, and EFSA regulatory consultants, then refined through secondary validation. Bottom-up resin volume estimates triangulated against top-down brand-owner sustainability procurement disclosures. Secondary sources included REACH registration dossiers, EU Packaging and Packaging Waste Regulation impact assessments, and customs trade data for FDCA intermediate flows.
Variance decomposition across resin type, application, packaging format, and regional production hub shaped the analytical framework. CAGRs derived from segment-level adoption curves weighted by EFSA approval timeline probabilities. Forecast inputs incorporated pilot plant capacity announcements, brand-owner recycled-content target trajectories, and thermoforming infrastructure adaptation rates.
Underlying assumptions cover sustained EU regulatory enforcement of bio-based procurement mandates, with deviation risk concentrated in FDA notification delays for copolymer variants and FDCA feedstock cost volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Thermosetting Plastics Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
Middle-East and Africa Thermoplastics Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Expanded Polystyrene (EPS) Market
Polymers & Resins
Antimicrobial Plastics Market
Polymers & Resins
Asia-Pacific Polymer Emulsion Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
BPA-Free Epoxy Resins Market
Polymers & Resins
Nylon 4-6 Market
Polymers & Resins
Global Corrosion Resistant Resin Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Flexible Epoxy Resin Market