
 Global Structural Foam Market | 2026-2036
Global Structural Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Global Structural Foam Market Foresight
The capability gap between integrated resin producers and standalone foam converters is collapsing as raw material volatility squeezes mid-tier margins. BASF SE leverages captive polyol supply chains to sustain cost leadership across European automotive programs. SABIC anchors its position through high-performance thermoplastic formulations that compete in aerospace load-bearing applications. Diab International AB specializes in PET and PMI core technologies that dominate wind energy blade manufacturing.
Structural foam denotes a cellular polymer material with integral dense skins and lower-density cores, typically achieving densities of 100–800 kg/m³ through controlled gas nucleation during processing. Manufacturers deploy these materials to achieve stiffness-to-weight ratios that rival unfoamed solids at substantially reduced mass. Polyurethane foam type leads value generation due to its versatility across reaction injection molding and pouring processes for automotive components and structural panels. Phenolic foam occupies niche high-temperature insulation applications where fire resistance commands premium positioning. The application segment for insulation panels draws concentrated investment as building energy codes tighten across multiple jurisdictions.
The EPA regulates volatile organic compound emissions from polyurethane foam production facilities under Clean Air Act provisions, while REACH restricts isocyanate and blowing agent chemistries in the European Union. China's MEE enforces GB standards on formaldehyde emissions from phenolic foams used in construction applications. Stakeholders must monitor regulatory divergence on per- and polyfluoroalkyl substance restrictions, as these constraints threaten incumbent blowing agent technologies and favor next-generation hydroolefin formulations.
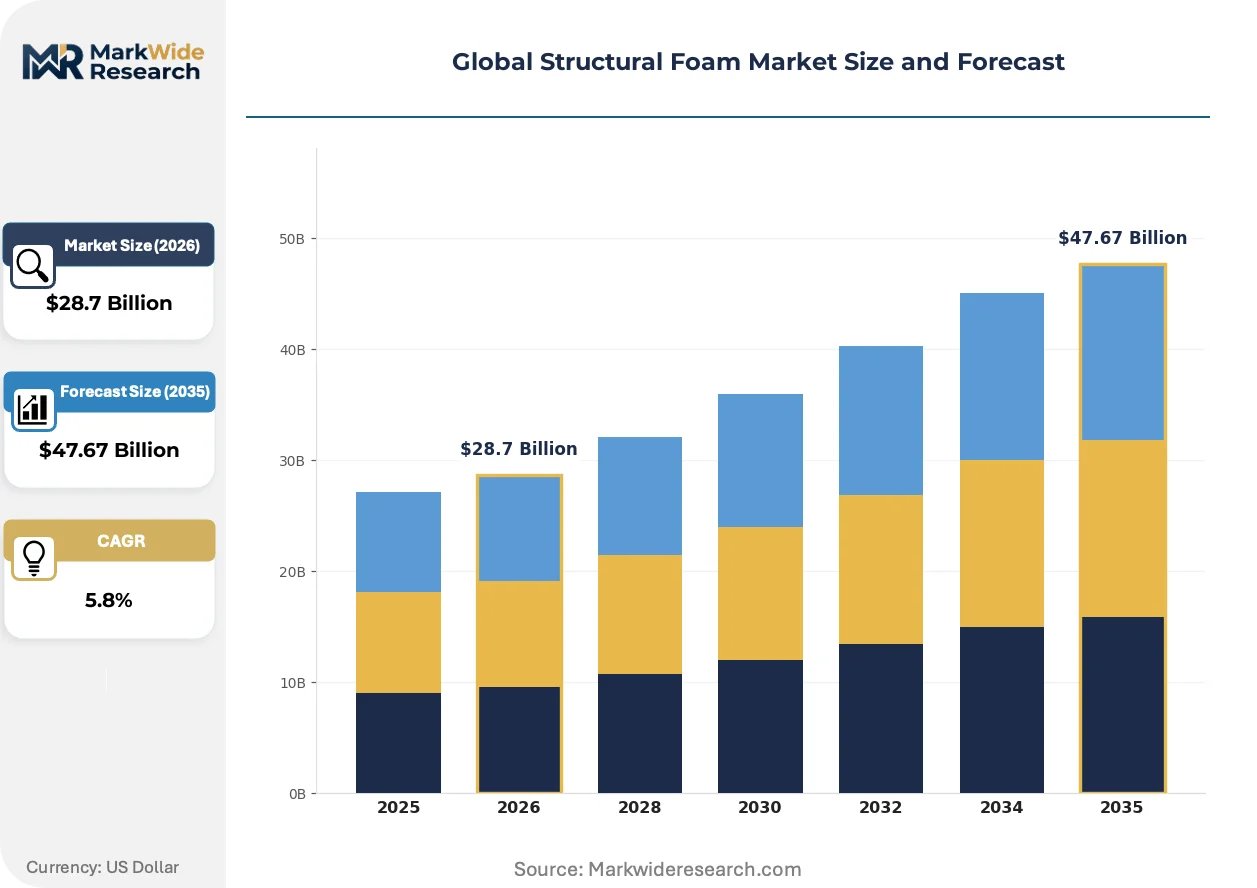
Market Dynamics
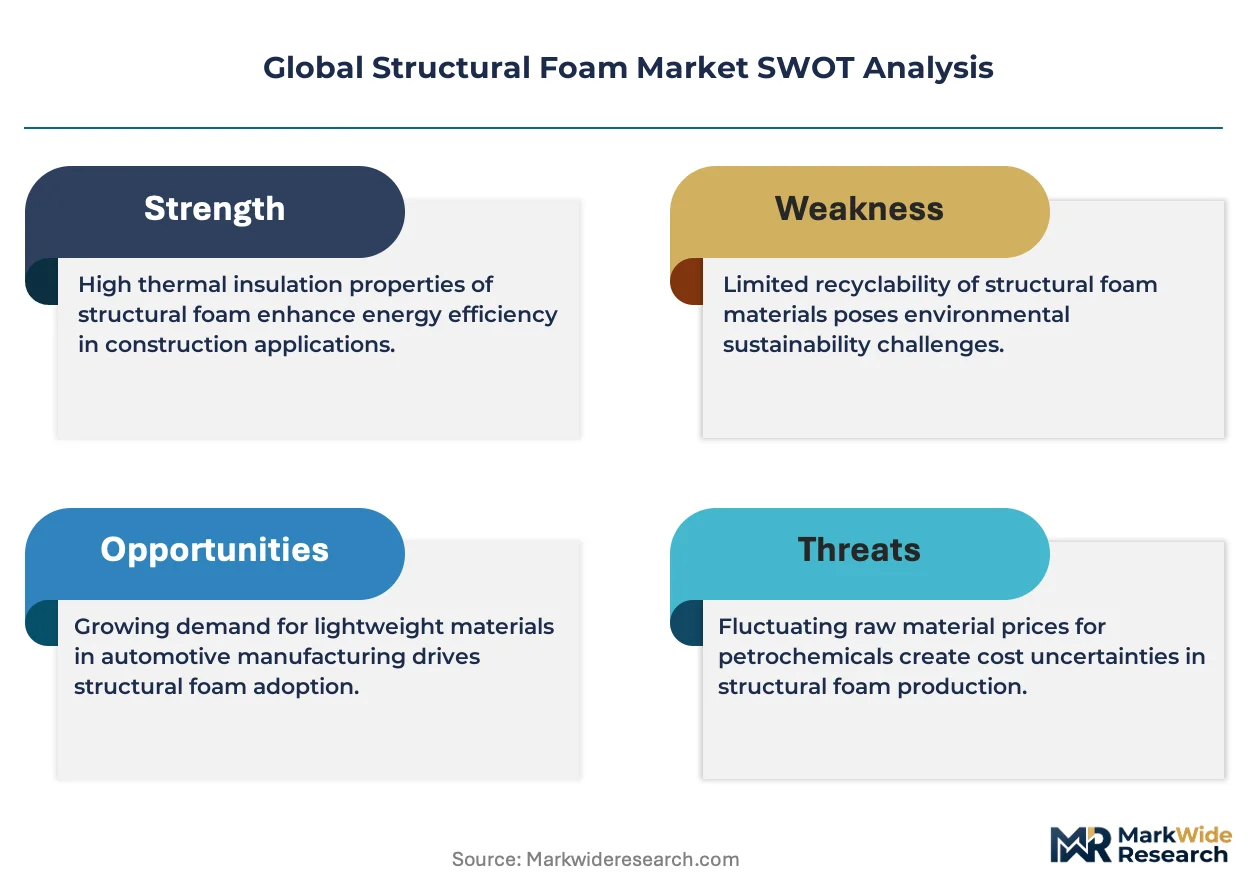
Automotive lightweighting mandates and wind blade scaling requirements are compressing the traditional separation between resin producers and foam converters, forcing mid-tier processors to secure captive polyol supply or exit European and Chinese automotive programs entirely.
Growth Catalysts
- REACH chemical compliance deadlines:European automotive OEMs are accelerating polyurethane structural foam adoption to meet 2025 fleet weight targets, pulling demand through German Tier-1 suppliers.
- Wind turbine blade scaling:Offshore wind projects in China's eastern manufacturing corridor require longer, lighter blades that integrate PET and PMI core materials from Ningbo-based fabricators.
- Reaction injection molding automation:Pouring process improvements are reducing cycle times for automotive structural panels, enabling just-in-sequence delivery to assembly plants.
Market Restraints
- Isocyanate price volatility:MDI and TDI feedstock costs fluctuate with crude oil and natural gas benchmarks, squeezing converter margins without long-term resin supply contracts.
- Blowing agent transition costs:F-Gas Regulation phase-downs in Europe and evolving EPA standards are forcing capital expenditure on hydroolefin equipment before cost curves flatten.
- High-performance thermoplastic substitution:SABIC's thermoplastic formulations are capturing aerospace load-bearing applications that previously specified thermoset polyurethane cores.
Strategic Opportunities
- India construction insulation penetration:BIS energy code enforcement in commercial buildings is opening demand for phenolic foam panels in Mumbai and Delhi NCR markets.
- Recyclable PET core technology:Diab International's thermoplastic core formulations align with EU Green Deal circularity mandates for end-of-life wind blade processing.
- Electric vehicle battery enclosure integration:Chinese EV producers near Shanghai are specifying structural foam for thermal runaway protection and pack structural rigidity.
Industry Challenges
- Multi-jurisdiction chemical registration:Simultaneous REACH, EPA, and China MEE compliance requires dedicated regulatory affairs capacity that mid-tier converters lack.
- Reaction injection molding technician scarcity:Skilled process engineers who can optimize gas nucleation parameters across variable humidity conditions command premium compensation in automotive manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Structural Foam Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $47.67 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Foam Type: Polyurethane, Polystyrene, Polyvinyl Chloride, Polyethylene, Phenolic, Epoxy End Use Industry: Construction, Consumer Goods, Packaging, Marine, Aerospace, Electrical & Electronics Manufacturing Process: Injection Molding, Compression Molding, Extrusion, Reaction Injection Molding, Pouring Application: Insulation Panels, Automotive Components, Structural Panels, Furniture, Tooling, Sports Equipment |
| Companies Covered | Evonik Industries AG, SABIC, SEKISUI CHEMICAL CO., LTD., Covestro AG, BASF SE, ARMACELL, The Dow Chemical Company, Diab International AB, Carpenter Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Structural Foam Market Shifts & Advancements
Processing technology convergence and regulatory chemistry restrictions are actively restructuring competitive advantage away from formulation secrecy toward equipment integration and supply chain control.
Bio-based polyol formulations derived from castor oil and soy feedstocks are supplanting petroleum-derived polyols in European automotive seating and interior panel applications. German OEMs have accelerated qualification timelines from thirty-six to eighteen months for these materials. The shift is compressing incumbent petrochemical suppliers' pricing power while rewarding converters with backward integration into agricultural supply partnerships.
REACH restrictions on isocyanate exposure limits and F-Gas Regulation hydrofluorocarbon phase-downs are forcing reformulation of blowing agent chemistries across European foam production. Manufacturers are retrofitting production lines for hydroolefin and water-blown systems at capital costs that disadvantage smaller converters. Wind energy blade producers in Denmark and Spain are absorbing premium core material pricing to maintain EU market access.
Direct procurement relationships between wind farm developers and core material suppliers are disintermediating traditional distributor networks in offshore wind supply chains. Vestas and Siemens Gamesa have established long-term offtake agreements with PET and PMI core specialists, bypassing regional foam distributors entirely. This pattern concentrates most visibly in China's eastern manufacturing corridor and the North Sea offshore cluster.
Global Structural Foam Market Segmentation
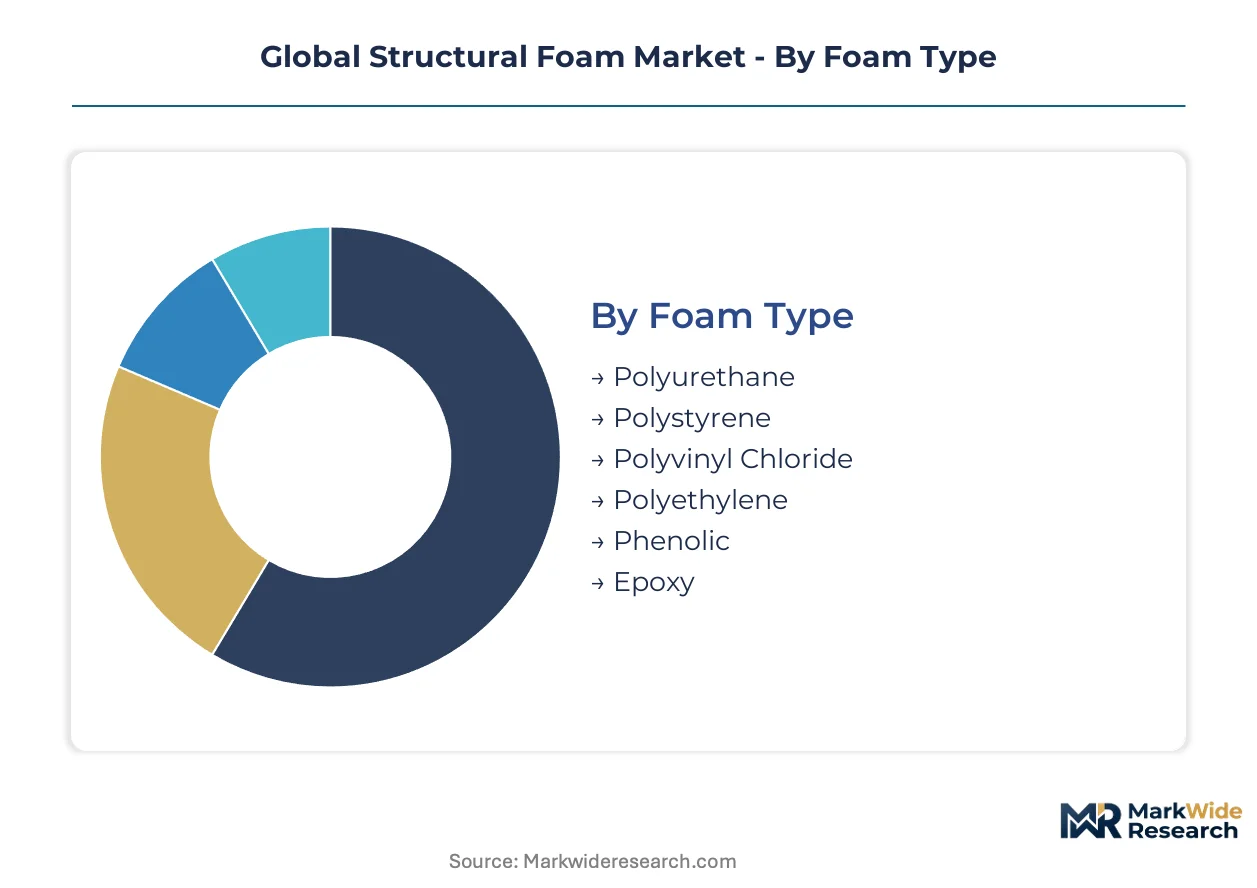
Structural foam markets fragment across material chemistry, end-use specifications, and processing requirements that dictate channel economics. Manufacturers optimize segment mix against captive resin access, regulatory compliance burdens, and automation thresholds that separate profitable from marginal production.
Foam Type:
Polyurethane and phenolic formulations flow through automotive direct-procurement channels, while polystyrene and polyethylene grades distribute through construction-material wholesalers.
- Polyurethane:Closed-cell thermoset polymer achieving 100–800 kg/m³ densities through controlled gas nucleation during reaction injection molding. German automotive OEMs specify this chemistry for lightweight structural panels meeting fleet weight mandates. REACH isocyanate restrictions compress converter margins without long-term MDI supply contracts.
- Phenolic:Thermoset foam with inherent fire resistance and low smoke emission characteristics. China's eastern manufacturing corridor absorbs premium pricing for wind blade core applications where thermal stability commands specification priority. GB standards on formaldehyde emissions constrain formulation flexibility for construction panels.
- Polystyrene:Expandable bead foam dominating cost-sensitive construction insulation through extruded and molded block formats.
- Polyvinyl Chloride:Rigid cellular formulation serving marine and electrical enclosure applications requiring moisture resistance.
- Polyethylene:Rotationally molded and extruded grades for packaging dunnage and marine flotation where chemical inertness outweighs stiffness requirements.
- Epoxy:High-performance thermoset cores for aerospace load-bearing sandwich structures with elevated temperature tolerance.
By volume, polystyrene leads through construction insulation penetration. By growth pace, polyurethane is climbing the fastest on automotive lightweighting pull-through.
End Use Industry:
Margin concentration follows application complexity tiers: aerospace and marine command premium pricing, while packaging and consumer goods compete on throughput scale.
- Construction:Insulation panel and structural sheathing applications governed by tightening energy codes across multiple jurisdictions. BIS enforcement in Indian commercial buildings opens demand for phenolic foam panels in Mumbai and Delhi NCR markets. F-Gas Regulation phase-downs force blowing agent transitions that disadvantage smaller regional converters.
- Aerospace:Load-bearing sandwich core applications specifying PMI and high-performance thermoplastic formulations from qualified suppliers. SABIC's thermoplastic grades capture share from thermoset incumbents in wing and fuselage structures. FAA certification timelines extend 18–36 months for new core material qualifications.
- Marine:Buoyancy and deck core applications requiring moisture resistance and fatigue tolerance in saltwater environments.
- Consumer Goods:Furniture cushioning and appliance insulation where cost minimization dominates supplier selection.
- Packaging:Protective dunnage and returnable container formats prioritizing impact absorption per unit cost.
- Electrical & Electronics:Enclosure insulation and potting compounds where dielectric properties and thermal management converge.
Construction generates the highest absolute volume. Aerospace delivers the steepest margin expansion trajectory.
Manufacturing Process:
Process selection locks manufacturers into capital intensity tiers that determine customer access and geographic viability.
- Reaction Injection Molding:High-pressure impingement mixing of polyol and isocyanate components with simultaneous mold filling and foaming. German Tier-1 automotive suppliers deploy this process for just-in-sequence delivery of structural panels. Skilled technician scarcity for gas nucleation optimization commands premium compensation in manufacturing clusters.
- Injection Molding:Conventional thermoplastic foam molding with physical or chemical blowing agents for high-volume packaging and consumer goods.
- Compression Molding:Matched-die forming of pre-expanded beads or sheets for construction block and marine core production.
- Extrusion:Continuous profile and sheet foaming for insulation board and packaging film applications.
- Pouring:Open-mold or cavity-filling processes for prototype tooling, furniture, and custom industrial applications.
Injection molding dominates unit volume. Reaction injection molding is expanding most quickly on automotive automation investment.
Application:
Application mix shifts with regulatory energy codes and transportation electrification timelines that reweight insulation against structural demands.
- Insulation Panels:Building envelope and cold-chain applications where thermal resistance per unit thickness drives specification. EU Green Deal circularity mandates favor recyclable PET core technologies for end-of-life processing compliance. Multiple jurisdiction energy codes tighten simultaneously, compressing product development cycles.
- Automotive Components:Interior panels, bumper cores, and battery enclosure structures for electric vehicle thermal runaway protection. Chinese EV producers near Shanghai specify structural foam for pack rigidity and crashworthiness. EPA VOC emission regulations constrain production facility siting decisions.
- Structural Panels:Load-bearing sandwich constructions for transportation and industrial equipment housing.
- Furniture:Seating and bedding cores where comfort density and durability trade against material cost.
- Tooling:Pattern and mold substrates for composite manufacturing where dimensional stability and machinability matter.
- Sports Equipment:Protective gear and board cores balancing impact absorption with mass minimization.
Insulation panels lead by installed volume. Automotive components are gaining share fastest on electrification-driven battery enclosure demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. European automotive OEMs absorb premium core material pricing to maintain regulatory compliance, while Indian construction buyers prioritize cost minimization in phenolic foam panel procurement. Chinese wind blade fabricators occupy the middle ground, trading margin for scale in offshore project offtake agreements.
China
Electric vehicle battery enclosure demand from producers near Shanghai and Ningbo pulls polyurethane structural foam volumes through eastern manufacturing corridors. MEE enforces GB standards on formaldehyde emissions from phenolic foams used in construction applications. Wind blade fabricators in the Yangtze River Delta integrate PET and PMI cores for offshore turbine scaling requirements.
Germany
Automotive lightweighting mandates from KBA drive polyurethane adoption for structural panels meeting fleet weight targets. REACH isocyanate exposure limits and F-Gas Regulation hydrofluorocarbon phase-downs force blowing agent reformulation across foam production. Tier-1 suppliers in Baden-Württemberg deploy reaction injection molding for just-in-sequence delivery to assembly plants.
United States
EPA Clean Air Act provisions regulate volatile organic compound emissions from polyurethane foam production facilities, constraining facility siting decisions. Aerospace load-bearing applications in the Pacific Northwest and Southeast specify high-performance thermoplastic formulations. Construction insulation demand concentrates in California and Texas where energy codes tighten building envelope requirements.
India
BIS energy code enforcement in Mumbai and Delhi NCR commercial buildings opens demand for phenolic foam insulation panels. Price-sensitive procurement dominates construction segment supplier selection. Western and southern manufacturing clusters absorb technology transfer from European foam converters seeking cost-competitive production bases.
Denmark
Offshore wind project developers absorb premium core material pricing to maintain EU market access under circularity mandates. Vestas establishes direct procurement relationships with PET and PMI core specialists, bypassing traditional distributor networks. Copenhagen-based engineering clusters drive qualification timelines for recyclable thermoplastic core technologies.
Global Structural Foam Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated resin producers with captive polyol supply chains command cost positions in high-volume automotive programs, while specialized core material developers capture premium pricing in aerospace and wind energy applications. Three archetypes dominate: petrochemical majors with backward integration into raw materials, performance-focused specialists in high-tolerance segments, and regional converters competing on throughput scale. Dominant competitive moves include strategic partnerships securing long-term resin supply and portfolio diversification into recyclable thermoplastic formulations.
Among German and Saudi Arabian chemical conglomerates, BASF SE and SABIC occupy positions reflecting distinct strategic vectors. BASF SE exemplifies the integrated petrochemical archetype with captive polyol capabilities sustaining cost leadership across European automotive supply chains. SABIC represents the high-performance materials specialist, anchoring aerospace and industrial applications through thermoplastic formulation expertise. Diab International AB sits within the dedicated core technology tier, specializing in PET and PMI formulations for wind energy blade manufacturing.
| Leading Market Players |
|---|
| Evonik Industries AG |
| SABIC |
| SEKISUI CHEMICAL CO., LTD. |
| Covestro AG |
| BASF SE |
| ARMACELL |
| The Dow Chemical Company |
| Diab International AB |
| Carpenter Co. |
| Others |
Supply & Pricing Matrix
Hydroolefin blowing agent substitution for hydrofluorocarbon systems is redrawing procurement geography and compressing converter economics across European and North American production clusters. German automotive Tier-1 suppliers now absorb capital equipment premiums to maintain REACH compliance, while Chinese wind blade fabricators leverage scale concentration to negotiate long-term PET core offtake pricing.
Pricing Analysis
After-market technical service and extended formulation support contracts generate disproportionate lifetime value for incumbent resin suppliers. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified PMI cores from construction-grade polystyrene insulation and automotive commodity polyurethane panels. Pricing pressure stems from MDI feedstock volatility squeezing converter margins without captive polyol supply. Construction buyers in India exhibit highest price sensitivity, while German OEMs prioritize compliance certification over unit cost.
Supply Chain Analysis
Just-in-time polyol delivery dominates German automotive reaction injection molding clusters, while Chinese wind blade fabricators maintain strategic stockpiles of PET and PMI core materials against offshore project deadlines. Supply concentration rests on Germany, China, and the United States for high-performance foam production. Raw material dependencies draw from crude oil derivatives, natural gas feedstocks, and bio-based castor oil polyols. Single-source vulnerability around isocyanate precursors from specific petrochemical complexes creates systemic exposure. Distribution runs through direct procurement relationships in wind energy, bypassing traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Structural foam markets are approaching a platform-economics inflection where direct procurement portals and formulation-as-a-service models disintermediate traditional distributor layers. Interoperability between resin qualification databases and OEM material selection systems is consolidating specification authority among integrated suppliers.
For Market Incumbents: Secure captive polyol supply chains through backward integration or long-term offtake agreements with petrochemical majors to defend against MDI price volatility. Invest in REACH-compliant hydroolefin production capacity before F-Gas Regulation phase-down deadlines harden qualification barriers. Channel control through technical service bundling protects margin position against emerging bio-based polyol specialists. For New Entrants and Emerging Players: Lead with recyclable PET core formulations targeting EU Green Deal circularity mandates in Danish and Spanish offshore wind markets. White-space opportunity concentrates in Indian phenolic foam construction insulation where BIS energy code enforcement outpaces domestic supply capability. Go-to-market angle should emphasize direct procurement relationships with Vestas-scale developers, bypassing distributor markups entirely. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated resin-to-foam specialists with regulatory affairs capacity across REACH, EPA, and MEE jurisdictions. Long-term viability hinges on backward integration depth and certification asset bases rather than throughput scale alone. Signal to watch is acceleration of direct procurement portal adoption among wind farm developers, indicating distributor disintermediation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Supply | BASF SE's captive MDI production sustains cost leadership across German automotive programs. |
| Recyclable Thermoplastic Core Development | Diab International's PET formulations align with EU Green Deal wind blade end-of-life mandates. |
| Direct Procurement Relationship Establishment | Vestas and Siemens Gamesa bypass distributors through long-term PMI and PET core offtake agreements. |
| Reaction Injection Molding Automation Investment | German Tier-1 suppliers achieve just-in-sequence delivery capability for OEM structural panel demand. |
| Bio-Based Polyol Qualification Acceleration | German OEMs compressed qualification timelines from thirty-six to eighteen months for castor oil-derived formulations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from listed chemical conglomerates, and ECHA regulatory registration databases. Plant managers at polyurethane conversion facilities, procurement leads at German Tier-1 automotive suppliers, distribution channel partners in Chinese wind energy corridors, and technical R&D directors at core material specialists provided operational perspective. Bottom-up demand modeling from end-use application volumes triangulates against top-down supply-side capacity assessments across major production hubs.
Segmentation dimensions modeled include foam chemistry tier, end-use industry vertical, manufacturing process capital intensity, and geographic regulatory cluster across the analysis window. CAGRs derive from trend extrapolation of automotive lightweighting adoption curves, wind turbine blade scaling requirements, and construction energy code enforcement trajectories. Industry-specific forecast inputs incorporate reaction injection molding automation investment cycles and blowing agent transition capital expenditure patterns.
Forecasts assume regulatory continuity in REACH, EPA Clean Air Act, and China MEE enforcement regimes; material policy shifts would require re-modeling of supplier qualification timelines and capital allocation patterns. Specific risk factors include accelerated per- and polyfluoroalkyl substance restrictions, isocyanate exposure limit tightening, and trade policy disruption to petrochemical feedstock flows. Revision becomes warranted when direct procurement portal adoption crosses threshold penetration among offshore wind developers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Phthalonitrile Resin Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Bio Based Resin Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Global Thermosetting Polymer Market
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Global Acrylic Solid Surface Market
Polymers & Resins
PET Foam Core Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Epoxy Casting Potting Resin Market
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
Emulsion PVC Market