
 BPA-Free Epoxy Resins Market | 2026-2036
BPA-Free Epoxy Resins Market Size, Share, and Industry Trends Forecast 2026-2036
BPA-Free Epoxy Resins Market Analysis
Food-contact grade certification is unwinding legacy supply arrangements across the BPA-free epoxy resins landscape. Huntsman Corporation leverages its amine curing agent expertise to anchor North American electronics coating demand. BASF SE sustains European supply continuity through backward integration into bisphenol F feedstock. Kukdo Chemical dominates Asian volume production with specialized liquid formulations for automotive OEMs.
BPA-free epoxy resins are thermosetting polymers synthesized from alternative bisphenol feedstocks—primarily bisphenol F and novolac variants—that cure through epoxide crosslinking to achieve glass transition temperatures exceeding 150 degrees Celsius for structural adhesion and corrosion protection. Novolac-based grades command premium positioning in aerospace laminates where thermal resistance and flame-retardant specifications determine qualification status. Electrical and electronics applications represent the fastest-expanding end-use segment as high-voltage battery encapsulation requirements drive amine-cured system adoption. Powder formulations retain mature utility in construction rebar coatings while liquid systems capture marginal growth in automotive lightweighting programs.
EPA scrutiny of bisphenol A under the Toxic Substances Control Act converges with FDA food-contact substance notifications to create dual compliance thresholds for US-market suppliers. ECHA REACH restrictions on endocrine-disrupting chemicals and the EU F-Gas Regulation indirectly reinforce BPA substitution incentives through broader chemical safety frameworks. Manufacturers must monitor evolving state-level disclosure mandates in California and New York that extend beyond federal minimums. Stakeholders should prioritize curing agent chemistry portfolios that satisfy both electronics flame-retardancy standards and emerging food-contact migration limits without reformulation redundancy.
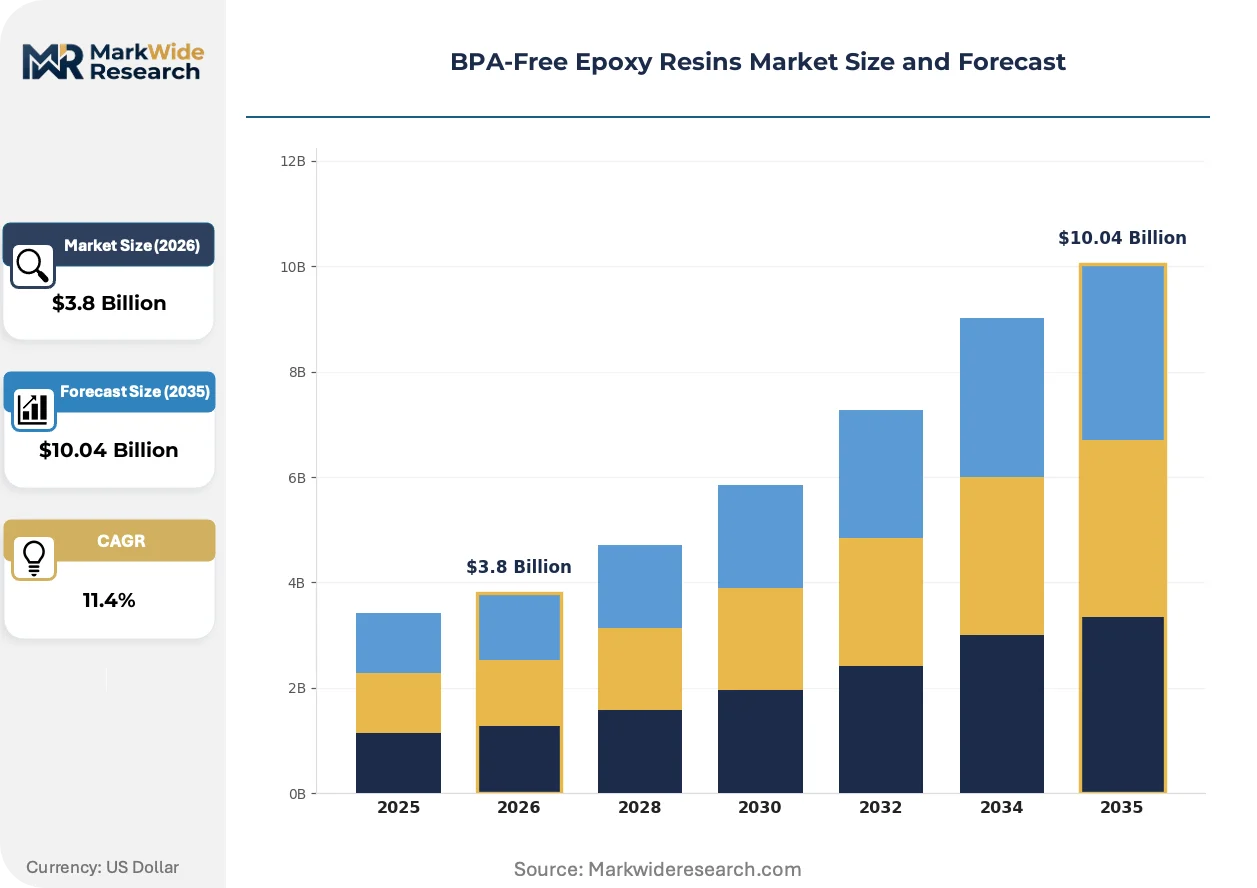
Market Dynamics
REACH restrictions in Europe and FDA food-contact notifications in the United States are compressing substitution timelines for legacy bisphenol A formulations, forcing resin manufacturers to requalify entire curing agent portfolios under dual compliance thresholds.
Growth Catalysts
- Food-contact coating mandates:Metal packaging manufacturers in Germany and the United States are abandoning traditional epoxy formulations to satisfy EFSA migration limits and FDA substance notifications for can linings.
- Automotive electronics encapsulation:High-voltage battery production is pulling amine-cured systems into thermal management applications where glass transition thresholds exceed 150 degrees Celsius.
- REACH Article 57 endocrine disruptor listings:ECHA classification of bisphenol A as a substance of very high concern is accelerating procurement switches across European coating supply chains.
Market Restraints
- Bisphenol F feedstock concentration:Backward-integrated producers in Northeast Asia control critical novolac precursor supply, creating input cost volatility for non-integrated formulators.
- Curing agent compatibility gaps:Amine systems qualified for electronics flame-retardancy specifications often fail emerging food-contact migration testing without reformulation.
- Substitution from polyester powder coatings:Construction rebar applications are seeing partial displacement by hybrid polyester alternatives in cost-sensitive municipal infrastructure projects.
Strategic Opportunities
- Underpenetrated aerospace laminates:Novolac-based grades with enhanced thermal resistance remain below 15 percent penetration in commercial aircraft interior composites.
- EU F-Gas Regulation alignment:Refrigeration equipment manufacturers seeking low-global-warming-potential insulation are qualifying BPA-free systems for compressor encapsulation.
- Digital formulation platforms:Machine-learning accelerated curing agent selection is compressing qualification cycles from 18 months to sub-6-month intervals for specialty electronics grades.
Industry Challenges
- Migration testing protocol fragmentation:Divergent FDA, EFSA, and state-level California Proposition 65 disclosure requirements force redundant analytical expenditure.
- Epoxy-anhydride curing expertise scarcity:Formulation chemists with simultaneous competence in electronics flame-retardancy and food-contact compliance command premium compensation.
- Legacy coating line retrofit costs:Metal packaging plants require capital-intensive application equipment modifications to handle higher-viscosity BPA-free liquid systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BPA-Free Epoxy Resins Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bisphenol A, Bisphenol F, Novolac, Others End Use Industry: Aerospace, Automotive, Construction, Electrical & Electronics Formulation Type: Liquid, Solid, Powder, Prepreg Curing Agent: Amine, Anhydride, Phenolic, Others |
| Companies Covered | Akzo Nobel N.V., Olin Corporation, BASF SE, Evonik Industries, Hexion, Huntsman Corporation, Allnex Group, Kukdo Chemical, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BPA-Free Epoxy Resins Market Emerging Trajectories
Formulation chemistry is splitting along application-specific performance requirements rather than converging on universal substitutes, creating parallel development tracks for electronics-grade and food-contact-grade systems.
Bio-based epichlorohydrin feedstocks derived from glycerol is bifurcating sustainability positioning in European packaging markets. Premium metal can manufacturers in Germany and France are adopting mass-balance-certified resins to satisfy retailer ESG scorecards. This feedstock shift is compressing price premiums for conventional petroleum-derived alternatives in Western European procurement tenders.
EPA scrutiny under the Toxic Substances Control Act Section 6 is tightening industrial chemical evaluation timelines for bisphenol alternatives. The agency's systematic review of structural analogs is forcing resin suppliers to pre-submit full toxicity datasets before commercialization. US-based coating formulators are responding by front-loading regulatory consulting expenditure into early R&D phases.
Certificate-of-analysis requirements are migrating upstream from finished goods manufacturers to raw material suppliers. Automotive OEMs in Michigan and Bavaria now mandate lot-level migration testing documentation from epoxy resin vendors. This documentation burden is most visible in battery encapsulation supply chains where thermal performance and chemical purity must be simultaneously guaranteed.
BPA-Free Epoxy Resins Market Segmentation
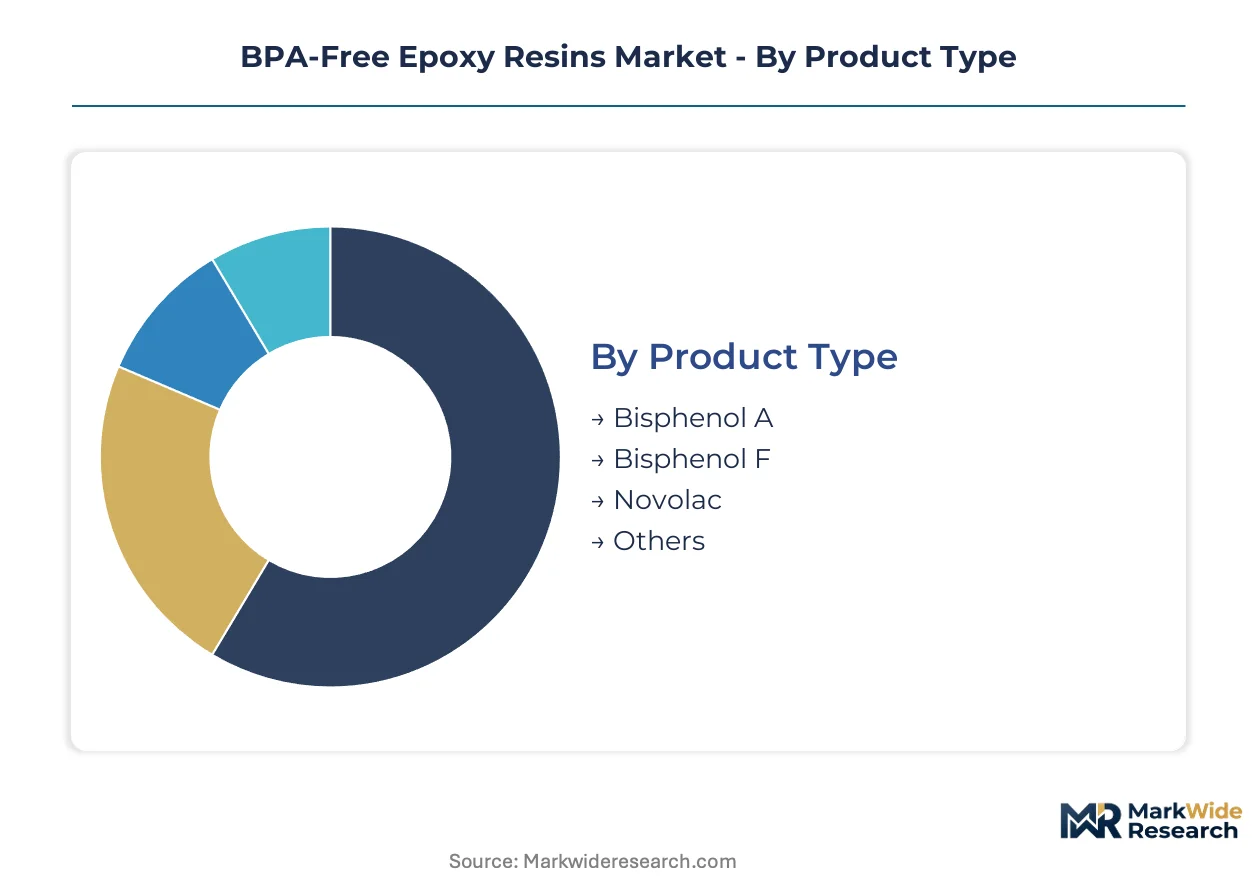
BPA-free epoxy resin formulations diverge sharply across end-use specifications, with food-contact migration limits and electronics flame-retardancy standards driving incompatible technical requirements. Manufacturers must maintain parallel product lines rather than converging on universal substitutes.
Product Type:
Regulatory differentiation separates feedstocks by migration limits and thermal performance thresholds.
- Bisphenol F:Synthesized from paraformaldehyde and phenol condensation, this feedstock achieves lower viscosity than bisphenol A analogs while satisfying EFSA migration limits for metal can linings. German packaging manufacturers specify bisphenol F grades for high-acid food applications where extraction testing is most stringent.
- Novolac:Crosslinked phenol-formaldehyde precursors deliver glass transition temperatures exceeding 170 degrees Celsius through higher functionality. Aerospace laminates in France and Germany qualify novolac-based systems for interior composites where flame-retardant specifications determine airworthiness certification.
- Bisphenol A:Legacy reference standard now restricted under REACH Article 57 SVHC listings; remaining applications concentrate in non-food industrial coatings with grandfathered regulatory status.
- Others:Hydrogenated bisphenol and specialty dicyclopentadiene variants serve niche optical and medical device encapsulation.
Bisphenol F handles the majority of throughput; novolac is the fastest mover on share.
End Use Industry:
Application-specific qualification cycles create divergent margin structures across customer segments.
- Electrical & Electronics:Amine-cured systems for high-voltage battery encapsulation require simultaneous thermal management above 150 degrees Celsius and dielectric strength validation. Michigan-based automotive OEMs mandate lot-level migration documentation from epoxy vendors for electric vehicle powertrain assemblies.
- Automotive:Lightweighting programs in Bavaria and South Carolina specify liquid formulations for structural adhesive bonding of aluminum-intensive body-in-white architectures.
- Aerospace:Novolac-based prepregs for commercial aircraft interiors remain below 15 percent penetration despite superior flame-retardant performance.
- Construction:Powder formulations for rebar coatings face displacement pressure from hybrid polyester alternatives in municipal infrastructure tenders.
Electrical & Electronics captures the steepest expansion trajectory; construction maintains volume concentration through mature rebar protection specifications.
Formulation Type:
Viscosity and application equipment compatibility dictate segment selection across coating line configurations.
- Liquid:Low-viscosity systems enable spray and roll-coat application for metal packaging linings; higher-viscosity BPA-free variants require capital-intensive equipment retrofits.
- Powder:Electrostatic spray deposition dominates construction rebar and pipeline coating with mature application infrastructure.
- Solid:Flake and pellet forms support hot-melt adhesive compounding for automotive assembly operations.
- Prepreg:Reinforced fiber-resin combinations serve aerospace autoclave processing with controlled volatile emission profiles.
Powder formulations anchor current volume; liquid systems are climbing fastest as food-contact coating mandates expand.
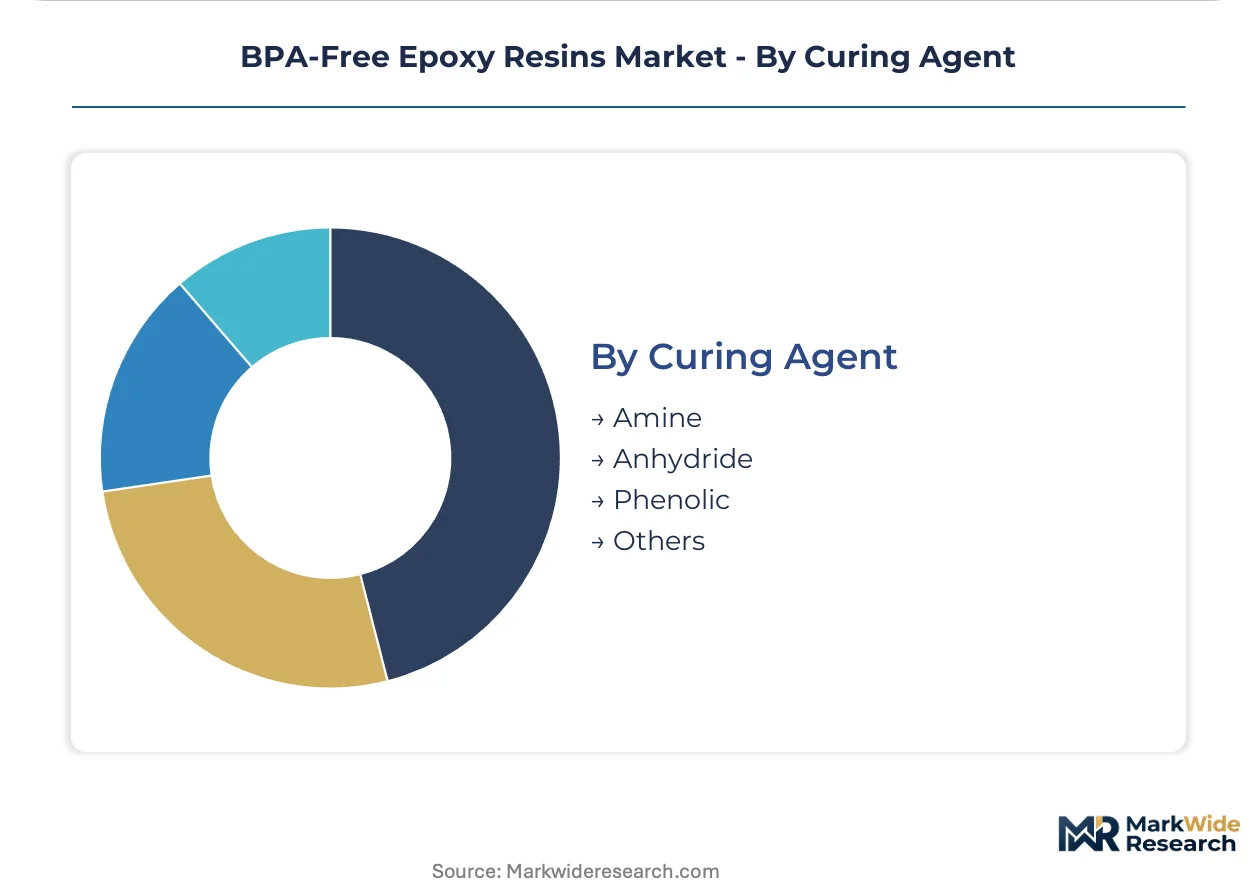
Curing Agent:
Chemistry selection determines dual-compliance feasibility across electronics and food-contact specifications.
- Amine:Aliphatic and cycloaliphatic variants dominate electronics encapsulation with rapid room-temperature cure kinetics; Huntsman Corporation anchors North American supply through specialized amine curing agent portfolios.
- Anhydride:Elevated temperature cure systems deliver superior thermal resistance for aerospace laminates; formulation chemists with combined electronics and food-contact expertise command premium compensation.
- Phenolic:Novolac hardeners achieve highest crosslink density for corrosion-resistant industrial coatings.
- Others:Isocyanate and catalytic latent systems serve specialty adhesive and tooling applications.
Amine curing agents process the largest throughput; anhydride systems are expanding most quickly in aerospace qualification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Backward-integrated producers in Northeast Asia control critical novolac precursor supply, while German and US formulators navigate dual compliance thresholds for electronics and food-contact specifications. This geographic asymmetry shapes procurement patterns across coating supply chains.
Germany
Metal packaging manufacturers in Bavaria and North Rhine-Westphalia specify bisphenol F grades for high-acid food can linings. ECHA REACH Article 57 SVHC listings for bisphenol A compress substitution timelines for legacy formulations. BASF SE's Ludwigshafen complex anchors European supply continuity through captive bisphenol F feedstock production.
United States
Michigan-based automotive OEMs mandate lot-level migration documentation for electric vehicle battery encapsulation resins. EPA scrutiny under TSCA Section 6 converges with FDA food-contact substance notifications to create dual compliance thresholds. Coating formulators in Ohio and Texas front-load regulatory consulting expenditure into early R&D phases.
China
Automotive lightweighting programs in Shanghai and Guangdong pull liquid formulations for aluminum-intensive body-in-white architectures. MIIT emissions standards and SAMR food-contact safety frameworks accelerate BPA substitution in domestic metal packaging. Kukdo Chemical's Jiangsu operations dominate Asian volume production with specialized liquid systems.
France
Premium metal can manufacturers in Île-de-France adopt mass-balance-certified resins to satisfy retailer ESG scorecards. ANSM oversight of food-contact materials reinforces EFSA migration limit enforcement. Novolac-based prepregs for aerospace laminates in Toulouse remain below penetration thresholds despite superior flame-retardant performance.
Japan
Electronics encapsulation demand in Kanto and Kansai regions drives amine-cured system adoption for high-voltage thermal management. METI chemical safety guidelines align with international BPA substitution incentives. Formulators in Nagoya and Osaka specialize in dielectric strength validation for automotive powertrain assemblies.
BPA-Free Epoxy Resins Market Vendor Landscape
Concentration sits with diversified chemical conglomerates and regional specialists rather than pure-play epoxy resin producers. The vendor base spans three tiers: backward-integrated feedstock controllers, formulation technology licensors, and application-specific compounders. Strategic moves center on curing agent portfolio requalification under dual compliance thresholds and geographic expansion through regional distribution partnerships.
Among European-based chemical conglomerates, BASF SE exemplifies feedstock-integrated positioning through captive bisphenol F production. Huntsman Corporation and Kukdo Chemical occupy distinct archetypes in amine curing agent supply and Asian volume manufacturing respectively. These three anchors represent divergent competitive vectors: European regulatory compliance leadership, North American electronics coating specialization, and Northeast Asian scale production.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Olin Corporation |
| BASF SE |
| Evonik Industries |
| Hexion |
| Huntsman Corporation |
| Allnex Group |
| Kukdo Chemical |
| PPG Industries |
| Others |
Supply Flow & Price Mechanics
REACH Article 57 SVHC listings for bisphenol A simultaneously gate supplier qualification and stratify price tiers across European coating supply chains, forcing formulators to absorb dual certification costs or surrender margin to backward-integrated competitors.
Pricing Analysis
REACH Article 57 SVHC listings dictate the pricing tier structure across BPA-free epoxy resin procurement. Three-tier pricing structure across premium, standard, and economy levels separates novolac-based aerospace grades from bisphenol F food-contact systems and commodity construction powders. Certification tier—specifically EFSA migration limit compliance versus electronics flame-retardancy validation—drives the widest price spreads. Cost compression in standard-grade bisphenol F is intensifying because Northeast Asian feedstock controllers are expanding captive production. Municipal infrastructure buyers exhibit highest price sensitivity, while automotive OEMs in Michigan and Bavaria prioritize lot-level documentation over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for novolac precursor shipments, compressing margins for non-integrated European formulators. Supply concentrates in China, Germany, and South Korea, with Kukdo Chemical's Jiangsu complex and BASF SE's Ludwigshafen facility anchoring regional production. Critical inputs draw from paraformaldehyde, phenol, and epichlorohydrin feedstocks, with bio-based glycerol-derived variants gaining share in Western European tenders. Single-source vulnerability sits with Northeast Asian novolac hardener supply, where three producers control majority capacity. Distribution runs through regional chemical distributors with formulation technical service capabilities, bypassing commodity traders for specialty grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in regulatory consulting and lot-level certification documentation are expanding faster than base resin volumes, creating recurring revenue layers that command 40-60% gross margins versus 15-20% for commodity formulations.
For Market Incumbents: Consolidate curing agent portfolio requalification efforts under unified compliance frameworks to eliminate redundant analytical expenditure across FDA and EFSA submission cycles. BASF SE's captive bisphenol F integration provides the template for margin defense against feedstock volatility. Prioritize digital formulation platforms that compress 18-month qualification windows to sub-6-month intervals, as Huntsman Corporation has demonstrated in North American electronics coating supply. For New Entrants and Emerging Players: FDA food-contact substance notification fast-tracks offer the most penetrable entry vector for specialty compounders lacking legacy bisphenol A infrastructure. Aerospace laminates in France and Germany remain below 15 percent penetration despite superior novolac thermal performance, presenting white-space for qualification-focused entrants. Partner with metal packaging OEMs in Bavaria and Ohio seeking to outsource migration testing documentation burdens. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates where epoxy resin divisions represent sub-5% of revenue but carry disproportionate regulatory compliance overhead. Five-to-ten-year viability hinges on curing agent chemistry portfolios that satisfy dual electronics and food-contact specifications without reformulation redundancy. Watch for EPA TSCA Section 6 enforcement acceleration as the inflection signal that triggers distressed asset availability among non-compliant formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol F Feedstock | BASF SE's Ludwigshafen complex eliminates novolac precursor exposure for European coating supply. |
| Digital Formulation Platform Deployment | Machine-learning curing agent selection compresses qualification cycles for Michigan automotive OEMs. |
| Mass-Balance Certification Adoption | German and French can manufacturers satisfy retailer ESG scorecards through bio-based epichlorohydrin sourcing. |
| Long-term Supply Agreement with Automotive OEMs | Bavarian and South Carolina lightweighting programs lock in liquid formulation volumes for body-in-white bonding. |
| Joint Venture for Aerospace Prepreg Qualification | Toulouse laminates suppliers gain novolac thermal resistance certification for commercial aircraft interiors. |
Methodological Framework
A standing panel of plant managers at coating formulation facilities, procurement leads at metal packaging OEMs, distribution channel partners with technical service capabilities, and R&D directors specializing in curing agent chemistry provided ongoing calibration throughout the study period. Primary interviews with these stakeholders were cross-referenced against customs and trade data from Germany's Federal Statistical Office and China's General Administration of Customs, SEC 10-K filings from diversified chemical conglomerates, and Cefic sector reports on European epoxy resin consumption. Bottom-up volume estimates from end-use application modeling were reconciled with top-down value projections derived from producer revenue disclosures.
Consistency checks validated volume and value outputs against external benchmarks including IHS Markit chemical production databases and national trade association statistics across the analysis window. Segmentation modeling incorporated product type differentiation by feedstock chemistry, end-use industry qualification requirements, formulation viscosity class, and curing agent compatibility, with geographic production clusters as an additional dimension. CAGRs were derived from regression analysis of historical consumption patterns and projected substitution timelines for legacy bisphenol A formulations, incorporating EPA TSCA Section 6 enforcement probability and ECHA SVHC listing expansion as scenario inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained REACH enforcement and FDA food-contact notification compliance; material deviation in regulatory timelines or feedstock cost trajectories would warrant model refresh. Practitioners should keep alternative scenarios live as EPA structural analog review scope and bio-based epichlorohydrin cost parity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Silane-Modified Polymers Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Polytrimethylene Terephthalate Market
Polymers & Resins
Bio-Based Polymer Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
US Acrylic Solid Surface Market
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
Aromatic Ketone Polymer Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Thermoplastic Polyolefin Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Expanded Polypropylene Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Construction Polymer Market