
 Nylon 4-6 Market | 2026-2036
Nylon 4-6 Market Size, Share, and Industry Trends Forecast 2026-2036
Nylon 4-6 Market Analytics
Specialty polymer distribution is narrowing as regional distributors consolidate inventory positions around high-performance grades. DuPont leverages its upstream adipic acid capabilities to sustain margin capture across the value chain. DSM Engineering Materials anchors European supply through its Netherlands-based compounding network, while Lanxess competes on automotive-certified resin portfolios.
Nylon 4-6 is a semi-crystalline polyamide synthesized from 1,4-diaminobutane and adipic acid, distinguished by a melting point near 295°C that exceeds standard PA6 and PA66 grades. The polymer serves critical load-bearing and thermal-management roles in automotive, electrical, and industrial systems where dimensional stability under sustained heat defines performance. Engineering plastics command the dominant value share given their specification intensity in powertrain and connector applications, while resin segments for film and fiber extrusion represent faster volume expansion as Asian packaging converters qualify alternatives to conventional polyamides. Injection molding remains the most margin-rich processing technique due to tooling complexity and part-precision requirements.
REACH registration requirements in Europe constrain monomer sourcing flexibility for non-EEA producers, while China's SAMR enforces GB standards that elevate flame-retardancy thresholds in electrical applications. The US EPA oversees adipic acid emissions protocols that indirectly shape Nylon 4-6 production economics. Stakeholders must track regulatory divergence on per- and polyfluoroalkyl substance restrictions, as alternative flame-retardant chemistries in electrical insulation grades face divergent approval timelines across jurisdictions.
Market Dynamics
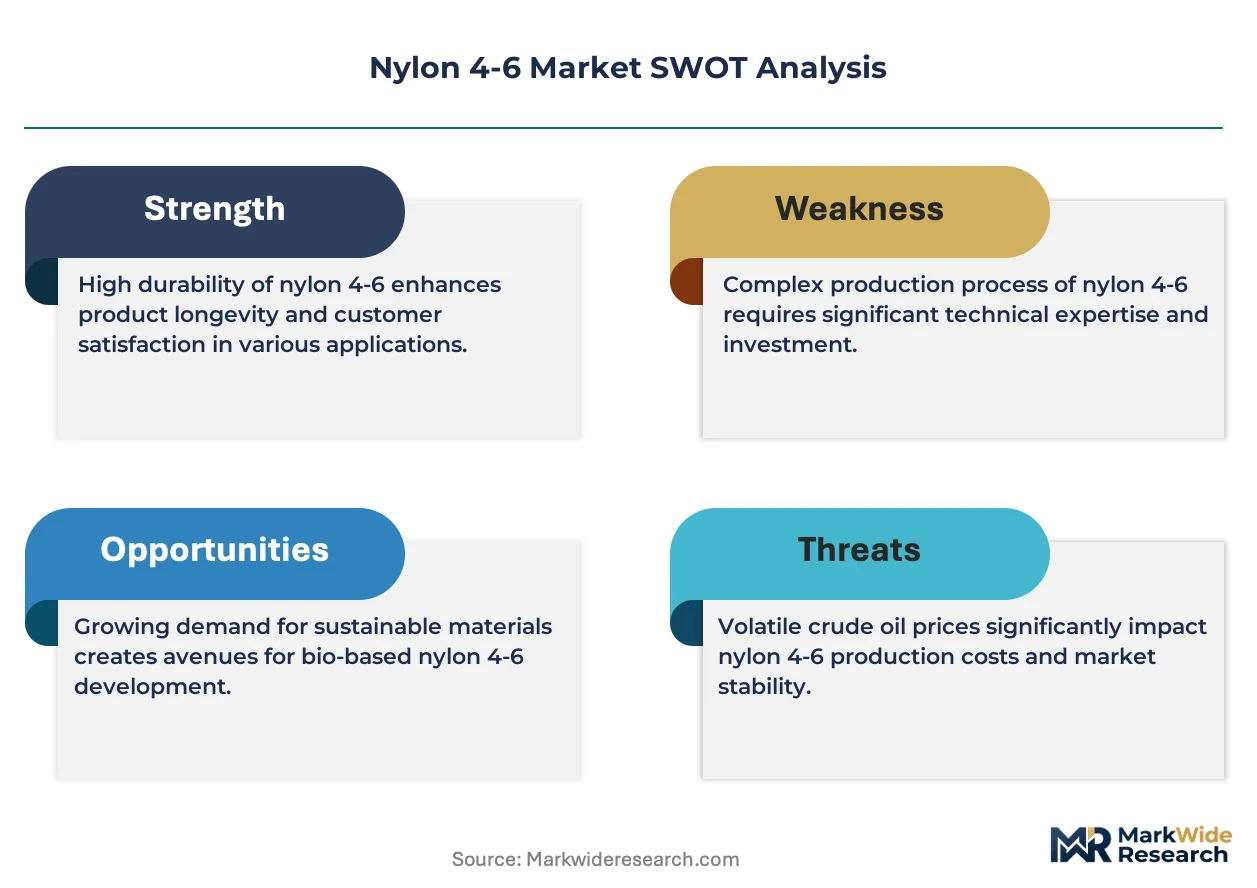
Automotive OEM thermal management requirements are compressing material qualification cycles as powertrain electrification elevates sustained operating temperatures beyond PA66 capabilities.
Growth Catalysts
- GB 18352.6-2016 emission standards:China's tightening vehicle emission protocols are forcing under-the-hood component redesigns that favor Nylon 4-6's heat resistance profile in turbocharger systems and transmission modules.
- Electrical connector miniaturization:Downsizing trends in high-voltage automotive and industrial electronics are pulling demand for polymers that maintain dielectric stability at elevated thermal loads.
- Adipic acid supply concentration:Captive production of the key monomer by integrated petrochemical complexes in East Asia is stabilizing feedstock access for regional compounders.
Market Restraints
- Monomer cost volatility:Adipic acid pricing sensitivity to benzene and cyclohexane feedstock swings compresses margin predictability for non-integrated producers.
- REACH registration barriers:ECHA chemical registration requirements for 1,4-diaminobutane constrain European market entry for Asian resin exporters lacking EEA-based legal entities.
- High-performance polyarylamide substitution:PA6T and PA9T grades with equivalent thermal performance threaten Nylon 4-6 in connector applications where moisture absorption tolerance is critical.
Strategic Opportunities
- India automotive manufacturing:PLI scheme incentives for electric vehicle component localization create first-mover positioning for heat-resistant polymer qualification with domestic Tier-1 suppliers.
- Film extrusion for high-temperature packaging:Retort pouch and aseptic packaging converters are testing Nylon 4-6 coextrusion structures as replacements for EVOH barriers in Asian food processing.
- Flame-retardant electrical insulation:EU F-Gas Regulation phase-down of fluorinated chemistries is opening formulation space for halogen-free Nylon 4-6 grades in switchgear and EV charging infrastructure.
Industry Challenges
- Compounding technician scarcity:Specialized knowledge of high-temperature polyamide rheology and moisture management during processing remains concentrated among veteran operators in established manufacturing clusters.
- Automotive PPAP timeline compression:Accelerated EV platform development cycles are squeezing the production part approval process for new resin grades from 18 months toward 12-month windows.
- Legacy injection molding equipment retrofit costs:Conversion of standard PA66 tooling for Nylon 4-6's higher melt temperature and crystallization kinetics requires barrel, screw, and hot-runner system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nylon 4-6 Market |
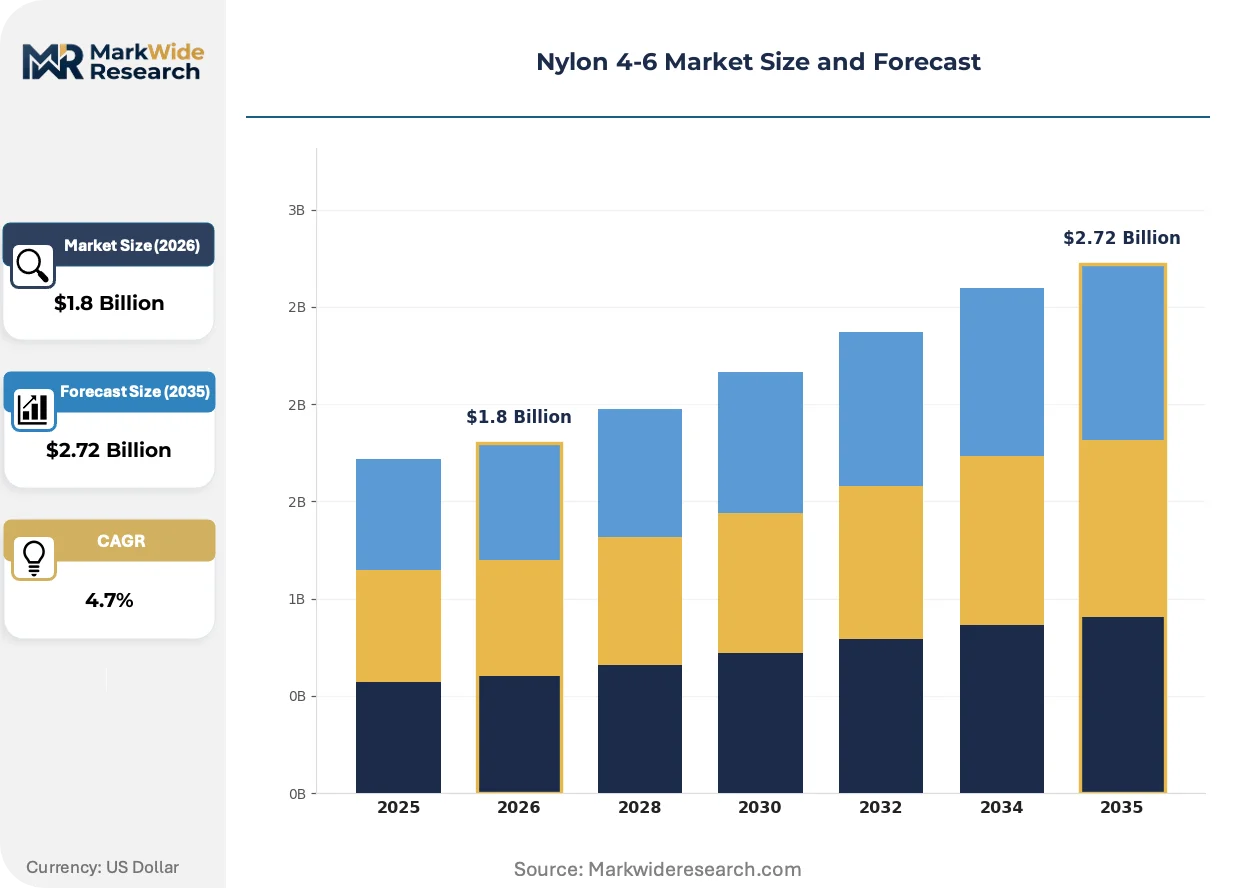
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filament, Staple Fiber, Resin, Engineering Plastics End User: Textiles, Automotive, Electronics, Consumer Goods Application: Apparel, Automotive Parts, Electrical Insulation, Packaging Processing Technique: Injection Molding, Extrusion, Blow Molding, Fibers Spinning |
| Companies Covered | DuPont, BASF, DSM Engineering Materials, Lanxess, EMS-Chemie Holding AG, Arkema Group, Honeywell International, Sabic Innovative Plastics, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nylon 4-6 Market Evolving Landscape
Process control digitization and regulatory chemistry restrictions are converging to reshape how specialty polyamide producers qualify grades and capture specification lock-in with automotive and electrical OEMs.
Real-time rheological monitoring systems are digitizing injection molding process windows for Nylon 4-6 components. Tier-1 automotive suppliers in Germany and Japan are deploying in-cavity pressure and temperature sensors to reduce scrap rates in thin-wall turbocharger duct applications. The technology is digitizing quality assurance workflows that previously relied on post-mold dimensional inspection, compressing cycle validation from weeks to days.
EU REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of flame-retardant Nylon 4-6 grades for electrical connectors. Compounders must validate phosphorus-nitrogen synergist systems that maintain UL94 V-0 ratings without PFAS-based drip suppressants. The regulation is most acutely affecting German and French automotive wiring harness producers who supply Stellantis and BMW electrified platforms.
Automotive OEMs are consolidating resin specifications around platform-common polymer families to simplify recycling compliance with EU End-of-Life Vehicle directives. Procurement teams at major European and Chinese manufacturers are reducing approved material lists from 15+ heat-resistant polyamides toward 5-6 core grades. The consolidation is most visible in Shanghai-based EV platform engineering centers where Nylon 4-6 competes for position against PA6T in unified thermal management module designs.
Nylon 4-6 Market Segmentation
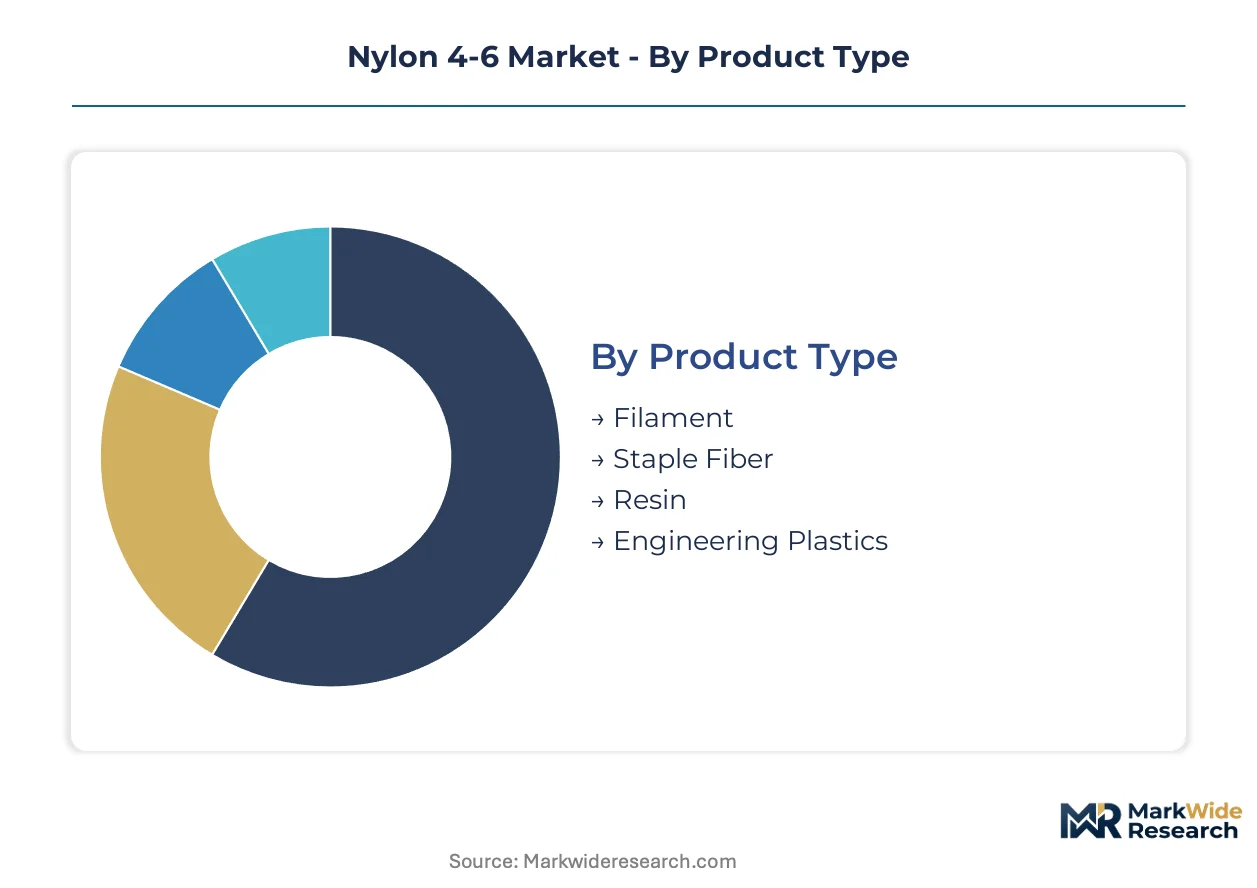
Segmentation in the Nylon 4-6 market reveals how material specifications diverge across thermal-load requirements and processing economics. Understanding these divides exposes where margin concentrates and which qualification pathways offer entry points for new suppliers.
Product Type:
Cost tier structures separate commodity-grade outputs from specification-intensive engineered materials, with margin capture scaling directly with technical complexity.
- Engineering Plastics:High-performance compounded grades with glass fiber or mineral reinforcement deliver dimensional stability under sustained thermal loads above 250°C. Automotive powertrain modules in Germany and Japan specify these grades for turbocharger ducts and transmission components where PA66 fails.
- Resin:Unfilled polymer pellets serve compounders and converters requiring customized additive packages for electrical or film applications. China's Yangtze River Delta hosts the densest concentration of resin toll compounders serving domestic automotive Tier-1s.
- Filament:Continuous fiber forms for industrial textile weaving and tire cord applications.
- Staple Fiber:Short-cut fiber grades for nonwoven felts and technical textile blends.
Engineering plastics commands the established base. The steepest expansion runs through resin grades as Asian packaging converters qualify alternatives to EVOH barriers.
End User:
Application maturity varies sharply across end-use sectors, with qualification timelines and specification lock-in determining competitive defensibility.
- Automotive:Under-the-hood thermal management components represent the most specification-intensive demand pool, with OEMs consolidating approved material lists around 5-6 core heat-resistant polyamides. China's GB 18352.6-2016 emission standards are forcing turbocharger and transmission module redesigns that favor Nylon 4-6's heat resistance profile.
- Electronics:High-voltage connector and switchgear applications require flame-retardant grades meeting UL94 V-0 without PFAS-based drip suppressants under EU REACH restrictions. German and French wiring harness producers supplying Stellantis and BMW electrified platforms face acute reformulation pressure.
- Textiles:Industrial fiber applications for tire cord and technical fabrics.
- Consumer Goods:Specialty packaging and appliance components with moderate thermal requirements.
Automotive anchors the revenue base. Electronics is climbing the fastest as connector miniaturization elevates thermal-load specifications.
Application:
Volume concentration maps directly onto processing technique compatibility and regional manufacturing cluster specialization.
- Automotive Parts:Load-bearing and thermal-management components including turbocharger ducts, transmission modules, and cooling system housings. Shanghai-based EV platform engineering centers are consolidating specifications around unified thermal management module designs where Nylon 4-6 competes against PA6T.
- Electrical Insulation:High-voltage connectors, switchgear, and EV charging infrastructure components requiring halogen-free flame-retardant grades. The EU F-Gas Regulation phase-down of fluorinated chemistries is opening formulation space for Nylon 4-6 in this category.
- Apparel:Technical textile applications leveraging high-tenacity fiber properties.
- Packaging:Retort pouch and aseptic packaging coextrusion structures testing Nylon 4-6 as EVOH replacements in Asian food processing.
Automotive parts holds the specification depth. Packaging is gaining share fastest as barrier property requirements intensify.
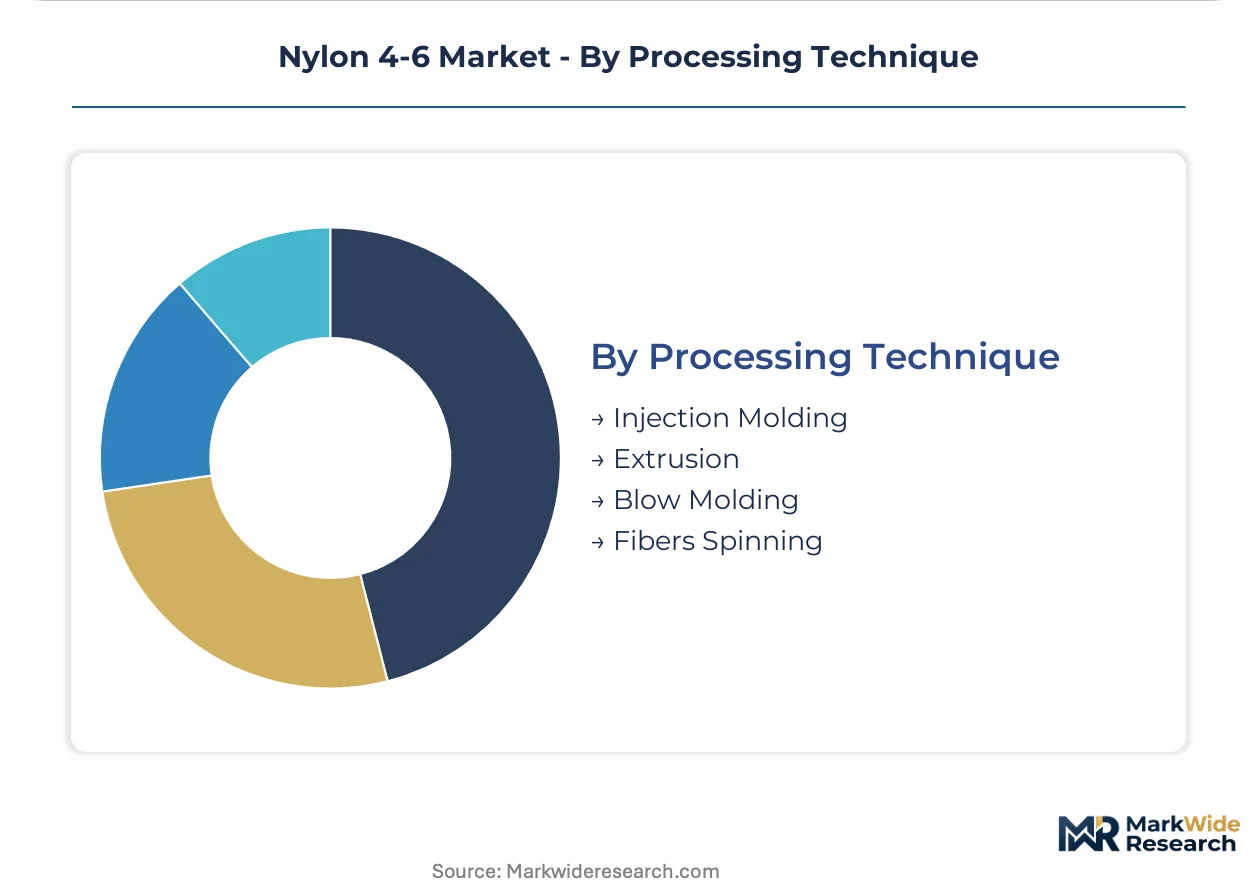
Processing Technique:
Margin capture scales with tooling complexity and process control requirements, creating distinct competitive moats around technical capabilities.
- Injection Molding:The most margin-rich technique demanding precise control of melt temperature, crystallization kinetics, and moisture management. Real-time rheological monitoring systems in German and Japanese Tier-1 facilities are digitizing quality assurance workflows for thin-wall turbocharger duct applications.
- Extrusion:Film and sheet production for packaging and electrical insulation applications with faster volume expansion but thinner margins. Legacy equipment retrofit costs for Nylon 4-6's higher melt temperature requirements constrain converter adoption.
- Fibers Spinning:Continuous and staple fiber production for textile applications.
- Blow Molding:Hollow component production for fluid handling and reservoir applications.
Injection molding secures the premium tier. Extrusion is expanding most quickly as Asian packaging converters scale qualification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp pipeline corridor underwrites European Nylon 4-6 logistics, while Shanghai's Yangshan deep-water port anchors Asian monomer import flows. These infrastructure assets shape where compounding capacity concentrates and which regulatory jurisdictions dominate qualification protocols.
China
GB 18352.6-2016 emission standards are forcing turbocharger redesigns that exploit Nylon 4-6's thermal ceiling. SAMR enforces these protocols through vehicle type-approval inspections that reject PA66-based legacy designs. The Yangtze River Delta around Shanghai hosts the densest toll-compounder cluster serving domestic Tier-1s.
Germany
Stellantis and BMW electrified platforms are compressing PPAP timelines for heat-resistant polymers. ECHA REACH registration requirements for 1,4-diaminobutane constrain Asian resin entry, protecting domestic compounders. The Cologne-Düsseldorf industrial corridor anchors DSM Engineering Materials' compounding network and KBA-certified automotive resin production.
United States
EPA adipic acid emissions protocols indirectly shape Nylon 4-6 production economics through feedstock cost structures. NHTSA fuel economy standards elevate under-the-hood thermal management requirements that favor high-melt polyamides. The Gulf Coast petrochemical corridor supplies captive adipic acid to integrated producers.
Japan
METI carbon neutrality roadmaps are accelerating EV platform development cycles that squeeze material qualification windows. JIS standards for automotive plastics maintain strict dimensional stability thresholds that Nylon 4-6 satisfies. The Nagoya-Toyota industrial zone concentrates Tier-1 injection molding capacity for hybrid powertrain modules.
India
PLI scheme incentives for EV component localization are opening first-mover positioning for heat-resistant polymer qualification. BIS automotive material standards are evolving toward harmonization with UN ECE regulations. The Pune-Chennai automotive belt is consolidating Tier-1 supplier parks where domestic compounders seek specification lock-in.
Nylon 4-6 Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in monomer and base resin supply. The vendor base concentrates around petrochemical majors with captive adipic acid positions and engineering plastics compounders with automotive certification depth. Three archetypes dominate: integrated petrochemical platforms with backward control over adipic acid, specialized engineering materials divisions of diversified chemical groups, and regional toll compounders serving single-country automotive supply chains. Capacity expansion and strategic partnerships represent the dominant competitive vectors as producers secure feedstock access and qualification bandwidth.
Among integrated petrochemical platforms, DuPont and BASF exemplify archetypes combining upstream monomer control with downstream compounding expertise. DSM Engineering Materials occupies a distinct position as a European-centered engineering plastics specialist with Netherlands-based manufacturing infrastructure. These three anchors illustrate how competitive positioning depends on feedstock integration depth and automotive OEM certification heritage rather than scale alone.
| Leading Market Players |
|---|
| DuPont |
| BASF |
| DSM Engineering Materials |
| Lanxess |
| EMS-Chemie Holding AG |
| Arkema Group |
| Honeywell International |
| Sabic Innovative Plastics |
| Evonik Industries |
| Others |
Value Network & Pricing Analysis
East Asian petrochemical complexes with captive adipic acid production anchor upstream supply and capture disproportionate margin pools in downstream compounding. Their integrated positions allow cost pass-through flexibility that non-integrated European and North American compounders cannot match, compressing pricing power for resin toll compounders serving single-country automotive supply chains.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automotive-certified engineering plastics from unfilled resin grades and commodity fiber outputs. Price differentiation hinges on OEM certification depth and volume scale, with injection molding compounders commanding premiums over extrusion-grade suppliers. Cost compression in standard resin tiers is intensifying as Chinese toll compounders expand capacity. Tier-1 automotive buyers exhibit lowest price sensitivity due to PPAP lock-in, while packaging converters driving extrusion demand remain highly sensitive to resin cost swings.
Supply Chain Analysis
Toll compounders in China's Yangtze River Delta and Germany's Cologne-Düsseldorf corridor hold the densest contract-manufacturing capacity for automotive-certified grades. Raw material flows draw from benzene and cyclohexane feedstocks concentrated in Gulf Coast and East Asian petrochemical hubs. Single-source vulnerability runs through adipic acid supply where non-integrated producers lack backward integration buffers. Distribution runs through regional distributor networks consolidating inventory positions around high-performance grades for just-in-time automotive delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty polyamide demand is fragmenting across electrification-driven thermal management niches and regulatory-forced flame-retardant reformulations. These demand-side shifts create white-space opportunities for compounders with targeted certification capabilities outside established automotive supply chains.
For Market Incumbents: Harden specification lock-in with Stellantis and BMW electrified platforms through accelerated PPAP completion for halogen-free grades. Deepen captive adipic acid positions via tolling arrangements with Yangtze River Delta compounders facing REACH registration barriers. PA6T substitution threats in connector applications demand sustained R&D investment in moisture-resistant formulations to defend automotive-approved material list positions. For New Entrants and Emerging Players: Build out flame-retardant electrical insulation capabilities targeting EU F-Gas Regulation-driven reformulation demand from German and French wiring harness producers. India's PLI scheme-supported EV component localization offers the most penetrable geography for first-mover qualification with Pune-Chennai Tier-1 suppliers. A technical service-led go-to-market model emphasizing rapid mold-flow analysis and processing support differentiates against incumbent distributors lacking application engineering depth. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European engineering plastics specialists holding KBA certification but limited Asian toll-compounder relationships. Long-term viability in this market centers on dual-hemisphere qualification bandwidth and PFAS-free formulation pipelines. Monitor EU REACH restriction timelines on per- and polyfluoroalkyl substances as the critical inflection signal for compounder repositioning value.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adipic Acid | Captive monomer supply insulates margin capture from benzene feedstock volatility at Rotterdam-Antwerp hubs. |
| Automotive Certification Investment | KBA and SAMR-approved grade portfolios secure specification lock-in with Stellantis and Shanghai-based OEM platform teams. |
| PFAS-Free Formulation Development | Phosphorus-nitrogen synergist systems open substitution revenue as EU REACH restricts fluorinated drip suppressants. |
| Toll Compounder Partnership | East Asian contract-manufacturing access bypasses ECHA registration barriers for European resin suppliers. |
| Real-Time Process Control Deployment | In-cavity sensor systems digitize quality assurance for thin-wall turbocharger ducts at German Tier-1 facilities. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with polymer procurement managers at automotive Tier-1 suppliers, technical directors at toll compounders, and regulatory affairs leads at ECHA-registered producers; alongside secondary validation through customs trade databases, SEC 10-K filings of listed petrochemical groups, and GB standard evolution tracking from SAMR. Bottom-up resin volume estimates triangulated against top-down automotive content-per-vehicle models.
Forecast inputs span grade tier differentiation, end-use industry thermal-load requirements, regional production hub specialization, and processing technique margin capture. CAGRs derive from segment-level volume trajectories cross-referenced with price elasticity assumptions across the projection horizon. Automotive electrification platform timelines and EU F-Gas Regulation phase-down schedules constitute industry-specific demand shapers.
Sensitivities concentrate around adipic acid feedstock cost swings, REACH registration timeline extensions for 1,4-diaminobutane, and PA6T substitution acceleration in moisture-critical connector applications. Forecasts reflect assumptions on OEM specification consolidation velocity and compounder capacity expansion cadence. Quarterly review of SAMR type-approval data and ECHA restriction proposal advancements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Phthalonitrile Resin Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
Polyamide Precursors Market
Polymers & Resins
Global Polyol and Polyurethane Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
South-East Asia Low-Density Polyethylene (LDPE) Market
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
Methacrylate Monomers Market
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
Water Soluble Polymers Market