
 Nerve Ablation Devices Market | 2026-2036
Nerve Ablation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Nerve Ablation Devices Market Analytics
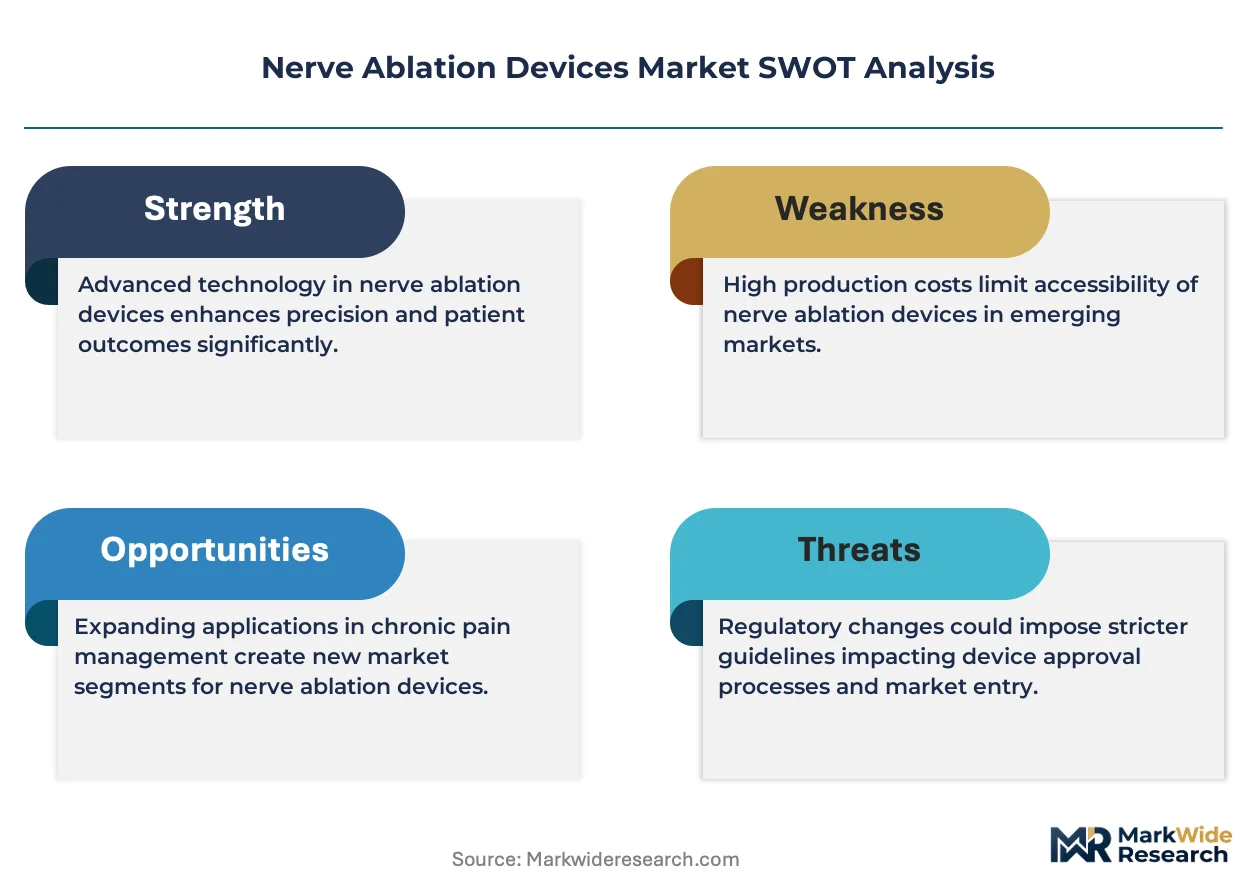
Hospital procurement channels for nerve ablation systems is narrowing as integrated delivery networks consolidate vendor lists. Medtronic leverages its broad catheter portfolio to sustain long-term supply agreements with major health systems. Boston Scientific Corporation competes through specialized radiofrequency platforms designed for chronic pain intervention.
Nerve ablation devices deliver targeted thermal or cryogenic energy to interrupt pain-signaling neural pathways, typically operating at temperatures between 60°C and 90°C for radiofrequency modalities or minus 40°C for cryoablation cycles. These instruments serve primarily to reduce pharmaceutical dependence in chronic pain and oncology patients. Radiofrequency ablation dominates current procedural volumes due to established reimbursement and physician familiarity, while cryoablation captures expanding share in cardiac and cancer applications where tissue preservation matters. Ultrasound-guided technology leads growth trajectories as real-time visualization reduces complication rates and shortens operator learning curves.
FDA 510(k) pathways and EU MDR conformity requirements shape product development timelines and clinical evidence thresholds for market authorization. The EPA regulates device sterilization emissions, adding compliance layers to manufacturing operations. Stakeholders must monitor evolving CMS reimbursement decisions for outpatient ablation procedures and adapt clinical trial designs to satisfy simultaneous FDA and EMA data expectations.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins and forcing device manufacturers toward integrated service contracts that bundle capital equipment with disposable catheter supply guarantees.
Growth Catalysts
- Ambulatory Surgical Center Expansion:CMS reimbursement clarity for outpatient ablation procedures accelerates procedural volume migration from inpatient settings. United States ASC networks now represent the fastest-growing installation base for radiofrequency systems.
- EU MDR Streamlined Pathways:The Medical Device Regulation's predicate device framework reduces clinical evidence requirements for next-generation cryoablation platforms. European manufacturers leverage this to compress time-to-market for cardiac applications.
- Ultrasound-Guided Visualization:Real-time imaging integration reduces operator training duration and complication rates. Japanese teaching hospitals have standardized this modality for chronic pain interventions.
Market Restraints
- Single-Use Catheter Cost Concentration:Polymer and electrode material inputs face petroleum price volatility. German health system tenders now require five-year total cost-of-ownership guarantees.
- Reimbursement Fragmentation:Japan's MHLW maintains procedure-specific fee schedules that lag technology adoption cycles. PMDA-cleared devices await Chuikyo pricing decisions for eighteen to thirty-six months post-approval.
- Pharmacological Substitution:Extended-release opioid formulations and neuromodulation implants compete for chronic pain budgets. United States payers impose step-therapy requirements that delay ablation authorization.
Strategic Opportunities
- Underpenetrated Oncology Applications:Liver and renal tumor ablation in India remains below Western procedural density. CDSCO's accelerated approval track for cancer devices creates first-mover positioning.
- Integrated Pain Management Platforms:Convergence of radiofrequency generators with AI-guided targeting software enables procedure standardization. United States integrated delivery networks bundle these systems across multi-hospital contracts.
- Home-Based Recovery Models:Same-day discharge protocols expand addressable patient populations. German ambulatory surgery centers capture margin premiums through reduced facility overhead.
Industry Challenges
- Interventional Pain Specialist Shortage:Fellowship-trained physicians concentrate in urban academic centers. Rural United States markets face twelve-to-eighteen month recruitment timelines for ablation-capable practitioners.
- Legacy EMR Integration Complexity:Procedural documentation requirements vary across Epic, Cerner, and Meditech installations. Device vendors maintain fifteen-plus interface configurations.
- EPA Sterilization Compliance:Ethylene oxide emission regulations force manufacturing facility retrofits. United States production sites absorb capital expenditure burdens for scrubber system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nerve Ablation Devices Market |
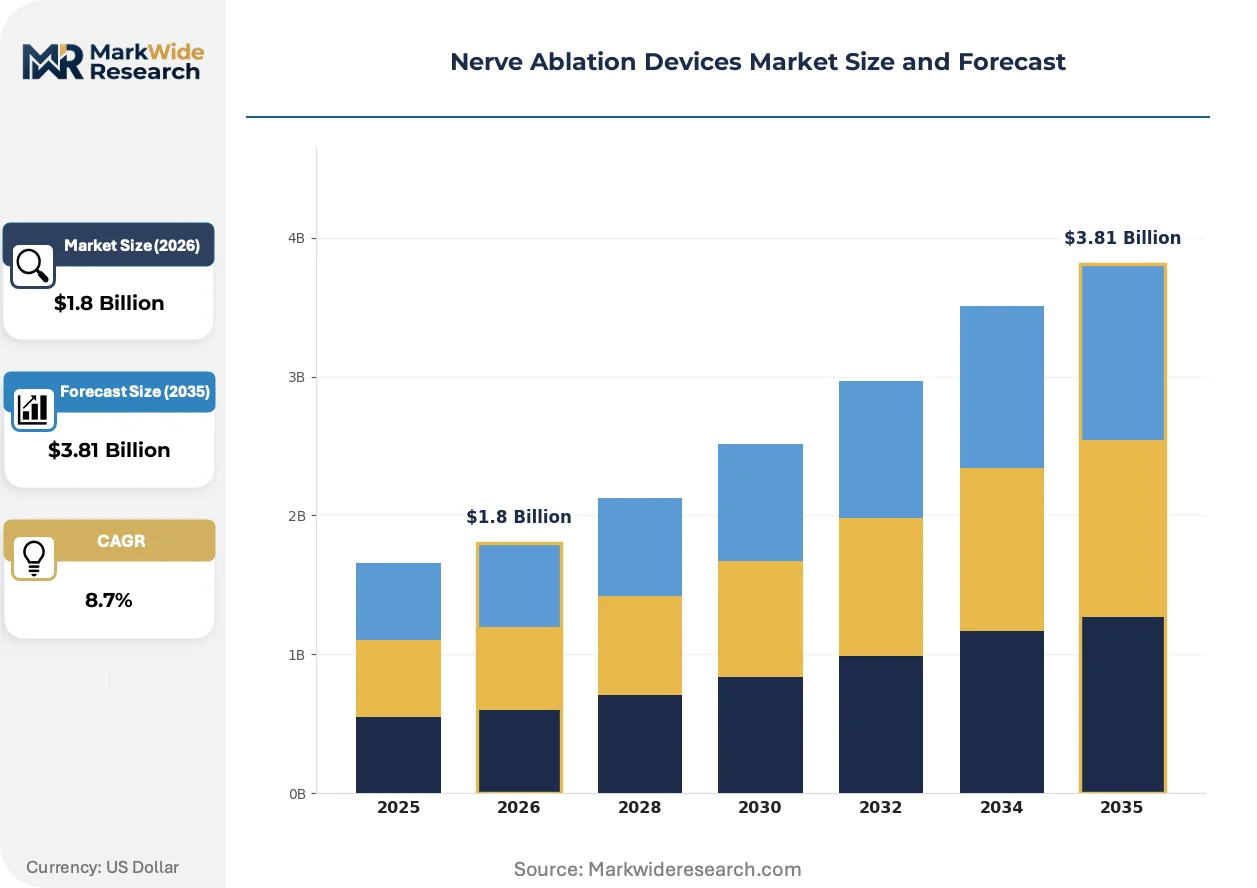
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency Ablation, Cryoablation, Microwave Ablation, Laser Ablation Technology: Ultrasound-Guided, X-ray Guided, Endoscopic, Fluoroscopy Application: Pain Management, Cancer Treatment, Cardiac Procedures, Neurological Disorders End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Institutions |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, Johnson & Johnson, Stryker, AngioDynamics, AtriCure, Inc., Olympus Corporation, Smith+Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nerve Ablation Devices Market Evolving Landscape
Device architecture is pivoting toward disposable-component modularity, while energy delivery protocols integrate real-time tissue impedance monitoring to prevent overtreatment complications.
Radiofrequency ablation is migrating from fixed-temperature algorithms to closed-loop impedance-controlled systems that adjust power delivery based on tissue characteristics. United States academic medical centers lead adoption, with seventeen of twenty top-ranked pain programs converting generator fleets within thirty-six months. This migration from legacy hardware compresses equipment replacement cycles and elevates service contract renewal rates for integrated vendors.
EU MDR's post-market surveillance requirements are mandating systematic real-world evidence collection for Class IIb active devices. Manufacturers must establish pan-European patient registries tracking five-year safety outcomes. Cardiac cryoablation platforms face the steepest compliance burden, with notified bodies demanding expanded clinical follow-up protocols that extend certification timelines by eight to fourteen months.
Integrated delivery networks in the United States are consolidating vendor relationships through sole-source agreements that span multiple procedural categories. Hospital procurement committees now evaluate nerve ablation systems alongside electrosurgical and laparoscopic platforms. This concentration favors suppliers with broad catheter portfolios capable of serving orthopedic, cardiac, and oncology service lines under unified contract terms.
Nerve Ablation Devices Market Segmentation
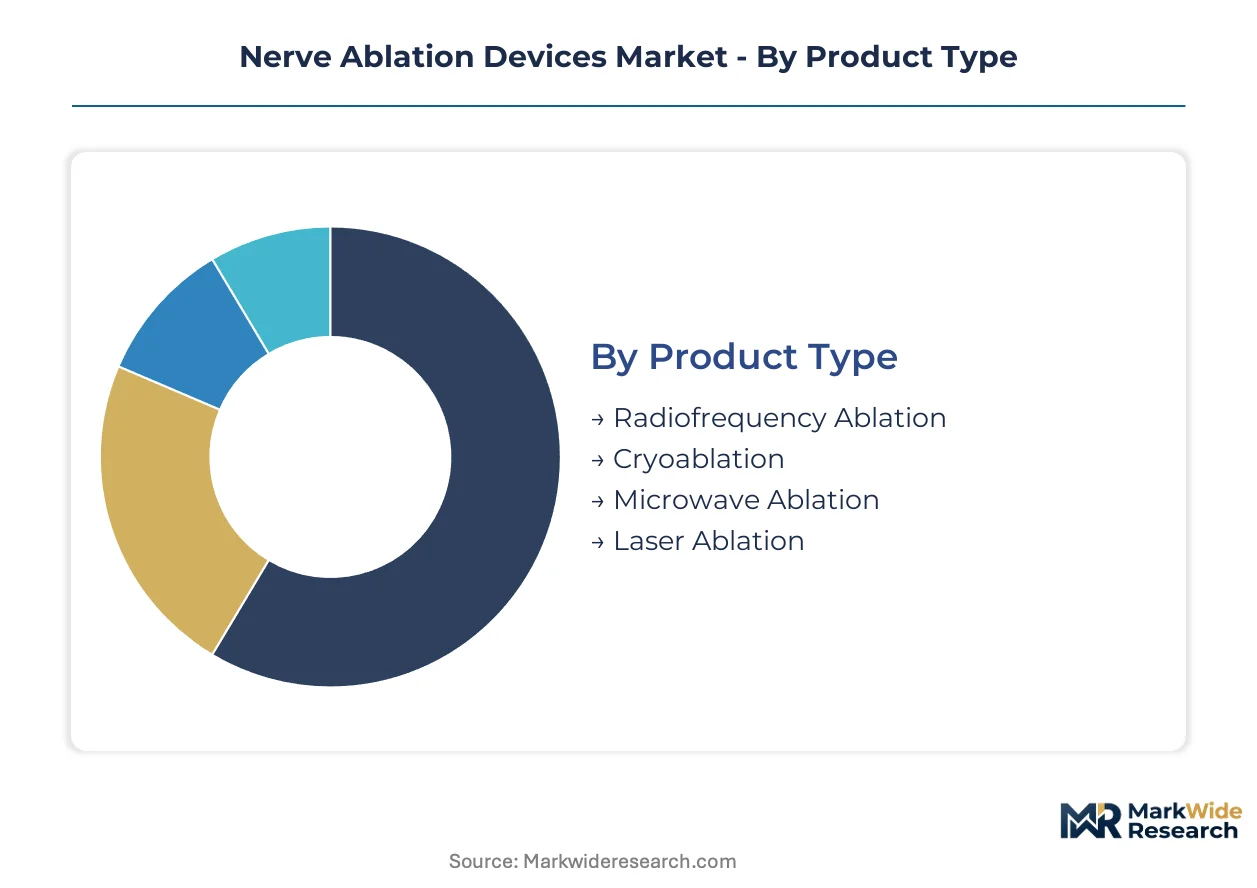
Device segmentation in nerve ablation reveals divergent replacement cycles across hardware and consumables. Generator systems operate on seven-to-ten year depreciation schedules while single-use catheters turn over per procedure. Understanding these velocity differences shapes inventory planning and capital allocation strategies for procurement teams.
Product Type:
Radiofrequency and cryoablation platforms command the longest capital cycles, while microwave and laser systems refresh more rapidly as diode technology advances.
- Radiofrequency Ablation:Thermal lesioning systems operating at 60°C to 90°C deliver controlled coagulation through impedance-monitored electrodes. United States hospital networks concentrate demand here due to established CPT reimbursement codes and physician training infrastructure. Generator replacement cycles extend to eight years when service contracts include hardware refresh guarantees.
- Cryoablation:Minus 40°C nitrogen- or argon-based freezing cycles preserve extracellular architecture for cardiac and oncologic applications. German cardiac centers drive procedural volume where tissue preservation outweighs thermal destruction. Disposable balloon catheter costs dominate total procedure economics.
- Microwave Ablation:Electromagnetic field heating achieves faster ablation zones than radiofrequency modalities. Japanese liver cancer protocols incorporate this technology where tumor proximity to heat-sink vessels complicates thermal approaches.
- Laser Ablation:Nd:YAG and diode laser systems target intradiscal and small-nerve applications. Research institutions in the United States evaluate this modality for precision neural targeting.
Radiofrequency ablation anchors the volume base while cryoablation gains share at the steepest rate.
Technology:
Imaging modality selection tracks procedure complexity and reimbursement tier, with ultrasound commanding premium positioning in outpatient settings.
- Ultrasound-Guided:Real-time soft-tissue visualization eliminates radiation exposure and enables same-day discharge protocols. Ambulatory surgical centers in the United States standardize on this approach for lumbar medial branch blocks. Transducer compatibility requirements lock facilities into specific generator ecosystems.
- X-ray Guided:Fluoroscopic confirmation remains mandatory for spinal interventions near neural foramina. Hospital-based pain programs maintain C-arm suites for complex anatomical targets. Capital equipment depreciation spans seven years.
- Endoscopic:Direct visualization through working channels enables intradiscal and facet joint approaches. Specialty clinics in Germany deploy this technology for refractory discogenic pain.
- Fluoroscopy:Continuous X-ray imaging supports electrode positioning in cardiac and deep visceral applications. Research institutions utilize this modality for investigational protocols.
Ultrasound-guided technology commands the highest margin tier while X-ray guided procedures retain the largest installed base.
Application:
Clinical indication determines device specification, with chronic pain interventions consuming the highest catheter volumes per patient.
- Pain Management:Lumbar and cervical medial branch neurotomy dominates procedural frequency. United States ASC networks perform these interventions under local anesthesia with same-day discharge. Radiofrequency generators with multi-electrode capability reduce procedure time.
- Cancer Treatment:Liver, renal, and lung tumor ablation requires larger-diameter electrodes and temperature monitoring. Indian oncology centers expand cryoablation adoption where surgical resection carries prohibitive morbidity.
- Cardiac Procedures:Pulmonary vein isolation for atrial fibrillation drives balloon cryoablation demand. Japanese electrophysiology labs standardize on second-generation cryoballoon platforms.
- Neurological Disorders:Trigeminal neuralgia and occipital neuralgia interventions target cranial nerve branches. Specialty clinics in the United States combine diagnostic blocks with permanent ablation.
Pain management procedures generate the highest catheter consumption while cancer treatment applications expand most quickly.
End User:
Facility type dictates capital intensity and service contract structure, with ambulatory migration compressing equipment footprints.
- Hospitals:Integrated delivery networks negotiate multi-system contracts spanning cardiac, oncology, and pain service lines. United States health systems consolidate vendor relationships through sole-source agreements. Equipment utilization rates drive per-procedure cost allocation.
- Ambulatory Surgical Centers:CMS reimbursement clarity enables outpatient ablation volume migration. German ASCs capture margin premiums through reduced overhead and faster turnover. Generator portability requirements favor compact, cart-based designs.
- Specialty Clinics:Pain-focused practices concentrate radiofrequency procedures in urban markets. Fellowship-trained physician recruitment challenges limit rural penetration.
- Research Institutions:Academic medical centers evaluate next-generation modalities and train interventional specialists. Japanese teaching hospitals standardize ultrasound-guided protocols.
Hospitals retain the dominant capital base while ambulatory surgical centers climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's medical device logistics hub underwrites Germany's distribution dominance for European nerve ablation systems. FedEx's Memphis superhub anchors United States next-day catheter replenishment to ambulatory surgical centers. Singapore's Changi cargo terminals facilitate just-in-time generator deliveries across Southeast Asian hospital networks.
United States
CMS reimbursement clarity for outpatient ablation procedures accelerates procedural volume migration from inpatient settings. FDA 510(k) pathways compress time-to-market for radiofrequency platform iterations. The Dallas-Fort Worth metroplex concentrates ASC network headquarters where procurement committees negotiate sole-source vendor agreements.
Germany
Aging demographics and established chronic pain management infrastructure sustain procedural density in lumbar neurotomy. EU MDR conformity requirements shape post-market surveillance obligations for Class IIb active devices. The Rhine-Ruhr industrial corridor hosts sterilization facilities retrofitting ethylene oxide scrubber systems under EPA-aligned emission standards.
Japan
PMDA-cleared devices await Chuikyo pricing decisions that lag technology adoption cycles by eighteen to thirty-six months. METI's medical device innovation programs subsidize next-generation cryoablation platform development. Tokyo's teaching hospitals standardize ultrasound-guided protocols that reduce operator training duration.
India
CDSCO's accelerated approval track for cancer devices creates first-mover positioning in liver and renal tumor ablation. The country's national pharmaceutical regulator maintains predicate device frameworks that reduce clinical evidence burdens for next-generation platforms. Hyderabad's medical technology cluster concentrates contract manufacturing for disposable catheter components.
United Kingdom
NICE technology appraisals determine NHS commissioning eligibility for novel ablation modalities. The Medicines and Healthcare products Regulatory Agency enforces post-Brexit device registration requirements that parallel EU MDR standards. London's integrated care systems pilot bundled payment models spanning diagnostic blocks through permanent neurotomy procedures.
Nerve Ablation Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in electrode and catheter fabrication. The vendor base concentrates around diversified medical technology conglomerates with broad interventional portfolios and mid-cap specialists with pain-focused positioning. Three archetypes dominate: diversified system suppliers with multi-service-line contracts, cryoablation pure-plays with cardiac specialization, and radiofrequency platform vendors with ASC-focused portability. Competitive moves center on integrated service contracts bundling capital equipment with disposable supply guarantees, plus backward integration into electrode manufacturing to buffer petroleum price volatility.
Among diversified system suppliers, Medtronic and Boston Scientific Corporation occupy positions exemplifying the breadth-driven archetype. Medtronic leverages catheter portfolio breadth to sustain long-term supply agreements with major health systems. Boston Scientific Corporation represents specialized radiofrequency platform positioning designed for chronic pain intervention. Both entities anchor the competitive structure through multi-hospital contract consolidation rather than single-modality dominance.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| Johnson & Johnson |
| Stryker |
| AngioDynamics |
| AtriCure, Inc. |
| Olympus Corporation |
| Smith+Nephew |
| Others |
Value Network & Pricing Analysis
Hyderabad's medical technology cluster concentrates disposable catheter component manufacturing, with capacity utilization rates directly shaping downstream generator pricing power for integrated vendors negotiating multi-year hospital contracts.
Pricing Analysis
Volume-discount tiering structures stratify across premium cryoablation platforms, standard radiofrequency systems, and economy-grade microwave generators. Price differentiation rests on FDA 510(k) clearance tier and bundled service contract scope. Cost compression in the economy tier intensifies as petroleum-linked polymer electrode inputs face volatility. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while integrated delivery networks leverage scale for preferential standard-tier access.
Supply Chain Analysis
Polymer feedstock and precision electrode manufacturing draw from Germany, Japan, and the United States. Nitrous oxide refrigerant and argon gas supplies feed from industrial gas specialists. Single-source vulnerability concentrates in cryoablation balloon catheter production. Distribution runs through hospital procurement committees and GPO contracts with FedEx medical logistics hubs enabling next-day replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA 510(k) predicate pathways and CMS reimbursement code establishment creates substantial switching costs for hospital systems.
For Market Incumbents: Build switching-cost moats through EMR integration depth and multi-modality generator platforms that lock facilities into proprietary catheter ecosystems. Deepen backward integration into electrode manufacturing to buffer petroleum price volatility. Consolidate vendor-of-choice status through sole-source agreements spanning cardiac, oncology, and pain service lines before emerging cryoablation pure-plays secure cardiac center share.
For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated liver and renal tumor ablation segment where CDSCO accelerated approval tracks compress time-to-market. Target German ambulatory surgery centers with portable ultrasound-guided systems optimized for same-day discharge protocols. Pursue white-label manufacturing partnerships with Hyderabad component clusters to neutralize capital barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because integrated delivery network procurement concentration favors diversified system suppliers with multi-service-line breadth over single-modality specialists. Acquisition targets should demonstrate established Chuikyo pricing in Japan or CMS reimbursement clarity in the United States. Monitor PMDA approval-to-pricing lag duration as the inflection signal for Japanese market entry viability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device pathways compress clinical evidence requirements for next-generation radiofrequency platforms. |
| CE Marking Pathway | EU MDR post-market surveillance mandates shape five-year safety registry investments for Class IIb devices. |
| Hospital System Partnership | Sole-source agreements with integrated delivery networks lock competitors out of multi-hospital catheter supply. |
| Software Companion Development | AI-guided targeting modules differentiate generator platforms and elevate service contract renewal rates. |
| Reimbursement Strategy | CMS outpatient procedure code establishment determines ambulatory surgical center addressable market expansion. |
Research Methodology
A spread of perspectives from interventional pain specialists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying this analysis. Primary interview insights combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body guidance documents. Bottom-up procedure volume estimates triangulated against top-down market size assessments across the analysis window.
Demand-supply-balance framing anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include ablation modality, imaging guidance technology, clinical application, and facility type. CAGRs derived from procedure volume trajectories and per-procedure catheter consumption rates. Forecast inputs incorporated PMDA approval-to-pricing lag assumptions and EU MDR certification timeline extensions for cryoablation platforms.
Stress conditions across petroleum price volatility, EPA ethylene oxide emission compliance costs, and interventional specialist recruitment timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement clarity progression and regulatory pathway efficiency. Cross-checking against CMS outpatient procedure volume benchmarks and notified body certification databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nephrostomy Devices Market
Medical Devices
China Artificial Organs and Bionic Implants Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
Operating Room Integration Market
Medical Devices
Needle-Free Vaccine Injectors Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Middle East and Africa Aligner Sheet Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Global Enteral Feeding Tubes Market
Medical Devices
South Africa Ultrasound Devices Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Europe Clear Aligners Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Smart Syringe Pumps Market
Medical Devices
Clear Aligners Market