
 Global Contrast Media Injector Market | 2026-2036
Global Contrast Media Injector Market Size, Share, and Industry Trends Forecast 2026-2036
Global Contrast Media Injector Market Foresight
Hospital procurement consortiums is rewriting how contrast media injector contracts are negotiated across integrated delivery networks. Bayer AG leverages its radiology portfolio breadth to sustain long-term supply agreements with major health systems. Siemens Healthineers anchors its position through direct equipment-software bundling with imaging modalities. Shenzhen Antmed Co., Ltd. competes on manufacturing scale to occupy cost-sensitive procurement tiers in emerging markets.
A contrast media injector is a precision electromechanical device designed to deliver iodinated or gadolinium-based contrast agents at controlled flow rates, typically ranging from 0.5 to 10 mL per second, to enhance visualization during diagnostic imaging procedures. The device integrates pressure monitoring, programmable injection protocols, and safety interlocks to prevent extravasation and ensure patient safety during computed tomography and magnetic resonance imaging examinations. Automated injectors command the dominant share of product value due to their integration with PACS and dose-tracking requirements, while dual-syringe configurations capture expanding demand in cardiac catheterization laboratories where saline chaser protocols improve image quality. Electronic control systems represent the fastest-growing technology segment as facilities replace mechanical units to meet Joint Commission medication safety standards.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access costs for manufacturers serving Western markets. China's NMPA registration pathways and Japan's PMDA quality system inspections create additional compliance layers for companies seeking full geographic coverage. Stakeholders must monitor evolving radiation dose reporting mandates and contrast agent shortage contingency protocols as these regulatory and supply variables determine capital allocation priorities across imaging departments.
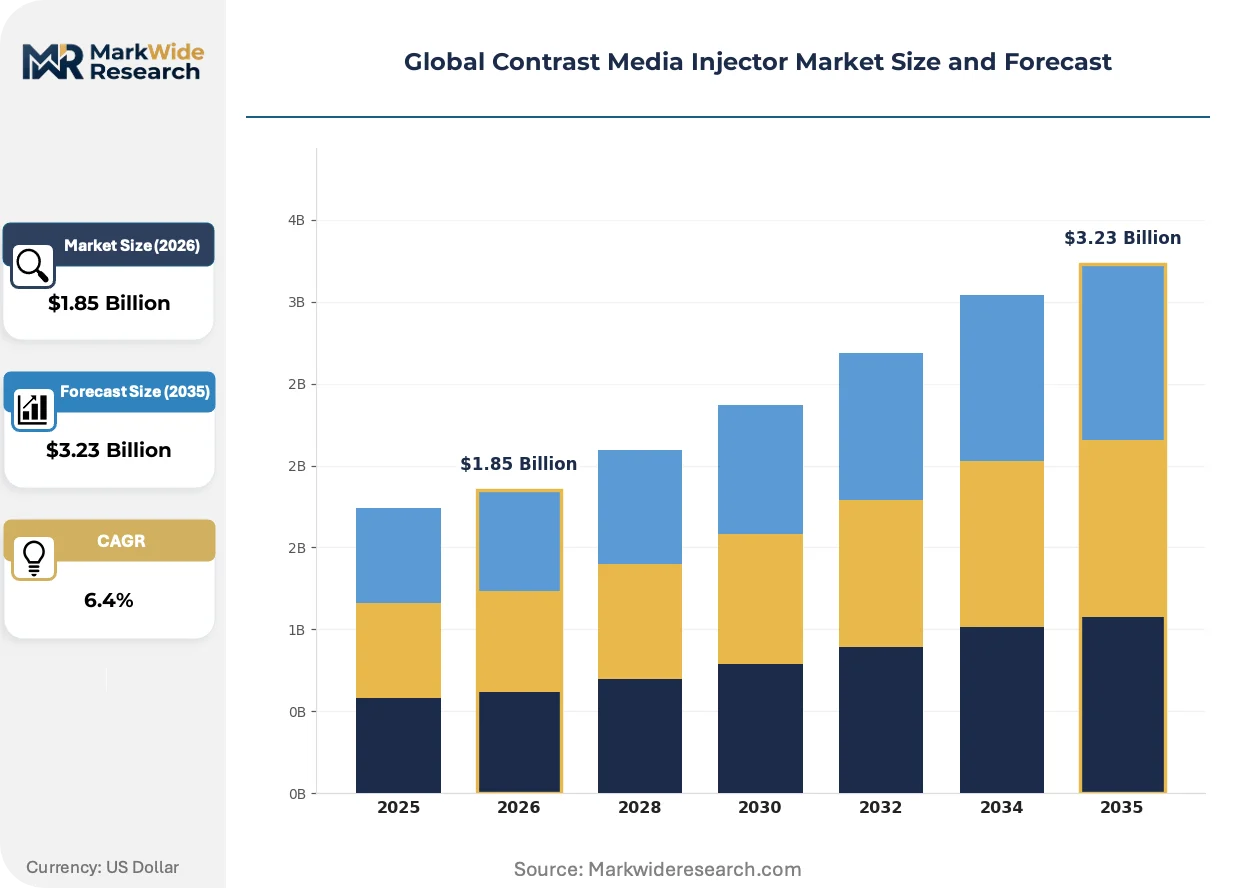
Market Dynamics
Automated injection systems are displacing mechanical units as hospital systems prioritize PACS integration and dose-tracking compliance to satisfy Joint Commission medication safety mandates.
Growth Catalysts
- Cardiology Expansion:Cardiac catheterization laboratories are upgrading to dual-syringe configurations to execute saline chaser protocols that improve coronary angiography image quality.
- EU MDR Compliance Windows:The Medical Device Regulation's technical documentation obligations are accelerating replacement cycles for legacy mechanical injectors across German and French hospital networks.
- Contrast Agent Protocol Standardization:Iodinated and gadolinium-based agent delivery precision requirements are pulling facilities toward programmable electromechanical systems with pressure monitoring interlocks.
Market Restraints
- Iodine Supply Volatility:Contrast agent precursor shortages originating from concentrated Chilean and Japanese iodine processing capacity create injector utilization uncertainty.
- Capital Equipment Intensity:Electronic control system manufacturing depends on semiconductor components facing extended lead times from Taiwanese and South Korean foundries.
- FDA 510(k) Timeline Friction:Predicate device identification challenges and substantial equivalence documentation requirements extend market access delays for novel injector architectures.
Strategic Opportunities
- China Imaging Infrastructure Buildout:NMPA registration pathway familiarity creates first-mover positioning for automated injector vendors targeting tier-two and tier-three hospital expansion.
- AI-Enabled Dose Optimization:Machine learning algorithms converging with injector control systems enable patient-specific flow rate adjustment based on anthropometric data.
- India Diagnostic Center Channel:Standalone imaging centers outside hospital systems represent an underpenetrated procurement tier seeking cost-optimized single-syringe configurations.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Electromechanical system maintenance and pressure calibration expertise shortages complicate service network expansion across distributed hospital systems.
- Legacy PACS Integration Complexity:DICOM connectivity standard version mismatches between aging radiology IT infrastructure and modern injector communication protocols demand costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Contrast Media Injector Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Injectors, Manual Injectors, Dual-Syringe Injectors, Power Injectors, Balloon Injectors Technology: Mechanical, Electromechanical, Pneumatic, Hydraulic, Electronic Control Systems Application: Computed Tomography, Magnetic Resonance Imaging, Ultrasound, Angiography, Cardiology End User: Diagnostic Centers, Radiology Clinics, Imaging Laboratories, Research Institutes, Specialty Clinics |
| Companies Covered | Ulrich GmbH & Co. KG, Medtron AG, Bayer AG, Shenzhen Antmed Co., Ltd., GE HealthCare, Bracco Imaging S.p.A., Nemoto Kyorindo, Siemens Healthineers, Guerbet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Contrast Media Injector Market Shifts & Advancements
Radiology departments are reconfiguring capital allocation around software-defined injection control, regulatory data architecture, and consolidated procurement authority.
Electronic control systems with programmable flow rate algorithms and real-time pressure feedback loops are rendering obsolete mechanical syringe pumps across outpatient imaging centers and academic medical centers. Cardiology and radiology departments in the United States and Germany are prioritizing these upgrades during routine equipment refresh cycles. The shift compresses service revenue for mechanical unit maintenance providers while expanding software subscription attach rates for injector manufacturers.
EU MDR Article 10 technical documentation requirements and post-market surveillance obligations are restructuring product development resourcing across European manufacturing operations. Manufacturers must maintain clinical evaluation reports and periodic safety update reports that extend time-to-market for iterative hardware modifications. Small and mid-sized injector producers are consolidating regulatory affairs functions or exiting the European market entirely, concentrating supply among firms with dedicated MDR compliance infrastructure.
Integrated delivery networks in the United States are centralizing contrast media injector procurement through single-source contracting arrangements that bundle devices with multi-year contrast agent supply agreements. Hospital procurement consortiums are displacing decentralized department-level purchasing authority that previously allowed radiology chiefs to select preferred vendors. This concentration is most visible in the southeastern and midwestern states where health system mergers have created multi-hospital networks with standardized capital equipment policies.
Global Contrast Media Injector Market Segmentation
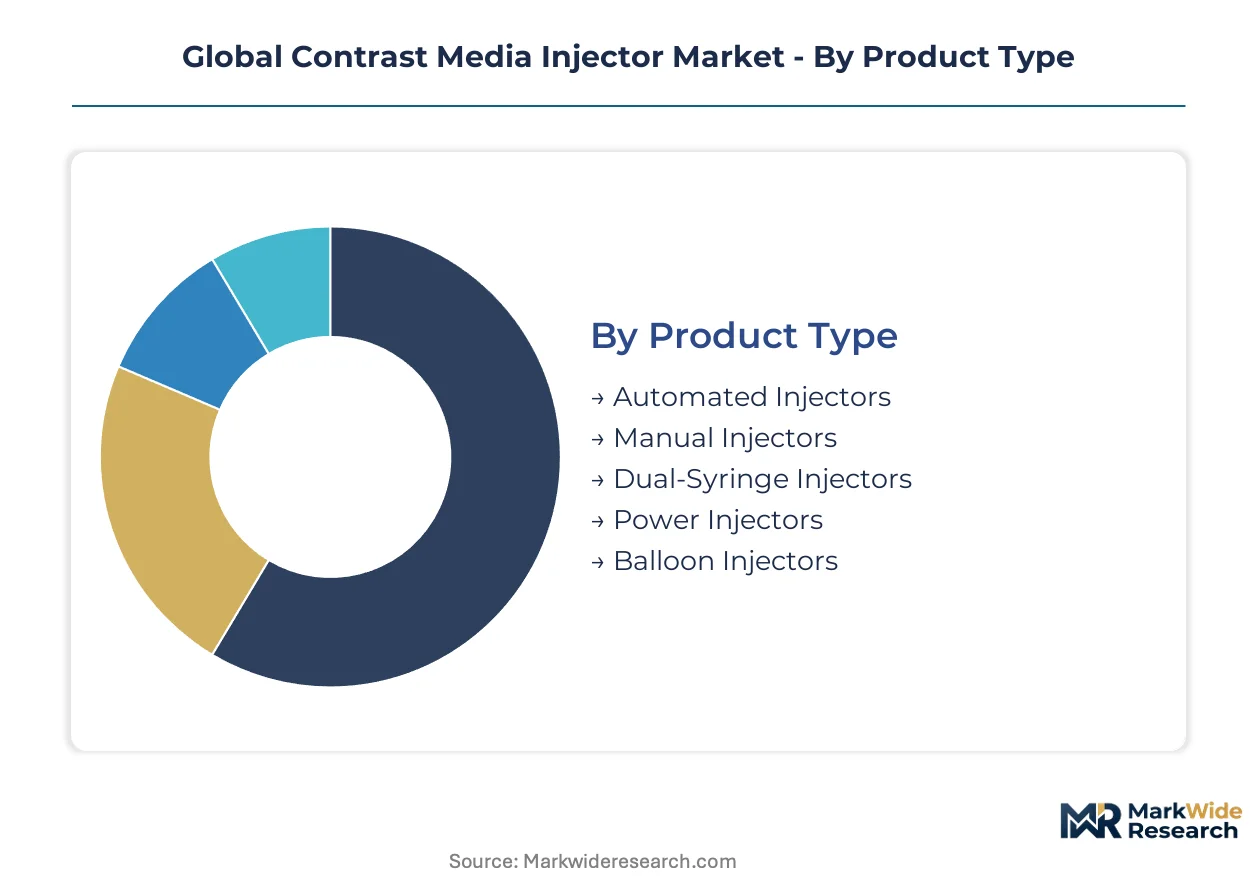
Segmentation reveals how service intensity, regulatory compliance burdens, and procurement consolidation reshape competitive positioning across injector categories. Each dimension carries distinct margin profiles and aftermarket revenue potential that determine vendor resource allocation.
Product Type:
After-sales-service intensity varies dramatically across injector configurations, with automated systems demanding multi-year software maintenance contracts while manual units require minimal field support.
- Automated Injectors:These precision electromechanical systems integrate programmable flow algorithms, real-time pressure monitoring, and PACS connectivity modules. Demand concentrates in United States academic medical centers and German hospital networks where Joint Commission and EU MDR compliance mandates drive replacement of legacy mechanical units. Recurring software subscription revenue and remote diagnostic capabilities define the vendor economics.
- Dual-Syringe Injectors:Configured for simultaneous contrast and saline delivery, these systems enable chaser protocols that reduce artifacts in cardiac catheterization procedures. Cardiology departments in Cleveland Clinic-class institutions and Charité Berlin-scale facilities prioritize these configurations for coronary angiography suites, with procurement bundled under multi-year contrast agent supply agreements.
- Manual Injectors:Hand-operated syringe pumps serve cost-constrained settings with minimal electromechanical complexity and negligible service attach rates.
- Power Injectors:High-pressure systems designed for CT angiography applications where rapid bolus delivery exceeds manual capability thresholds.
- Balloon Injectors:Specialized configurations for interventional radiology procedures requiring controlled inflation media delivery alongside contrast agents.
Automated injectors hold the largest share; momentum sits with dual-syringe configurations.
Technology:
Cost tier stratification separates premium electronic control platforms from legacy mechanical alternatives, with semiconductor component intensity determining manufacturing scale requirements.
- Electronic Control Systems:Microprocessor-driven architectures with programmable protocols, touchscreen interfaces, and DICOM-compliant data logging. United States outpatient imaging centers and Japanese diagnostic chains adopt these platforms to satisfy radiation dose reporting mandates from FDA and PMDA jurisdictions. Firmware update cycles and cybersecurity patch management create recurring revenue streams absent in mechanical alternatives.
- Electromechanical:Hybrid systems combining electric motor actuation with mechanical pressure sensing, occupying mid-tier procurement budgets in tier-two Chinese hospitals and Indian diagnostic chains.
- Mechanical:Spring-loaded or gravity-fed syringe pumps with no electronic components, dominant in emerging market rural clinics where service infrastructure is sparse.
- Pneumatic:Compressed gas-driven delivery systems with limited adoption outside specialized veterinary and preclinical research applications.
- Hydraulic:Fluid-pressure mechanisms rarely deployed in human diagnostic imaging due to contamination risk and maintenance complexity.
Electronic control systems command premium pricing; electromechanical alternatives are climbing the fastest in volume terms.
Application:
Application-specific protocol requirements dictate injector specification, with cardiac procedures demanding higher precision than routine body imaging.
- Cardiology:Coronary angiography and electrophysiology procedures require dual-syringe configurations with pressure-limited delivery and ECG-synchronized injection timing. German cardiac centers and United States heart hospitals anchor demand, with reimbursement tied to image quality metrics that saline chaser protocols improve.
- Computed Tomography:High-flow CT angiography drives power injector adoption across emergency departments and outpatient imaging networks in China and the United States.
- Magnetic Resonance Imaging:Gadolinium-based agent delivery at lower flow rates, with MRI-specific injector designs preventing ferromagnetic contamination.
- Angiography:Peripheral vascular procedures utilizing standard single-syringe automated systems in interventional radiology suites.
- Ultrasound:Microbubble contrast for echocardiography represents a niche application with specialized low-volume injector requirements.
CT applications hold the largest installed base; cardiology is gaining share fastest as cath lab construction accelerates.
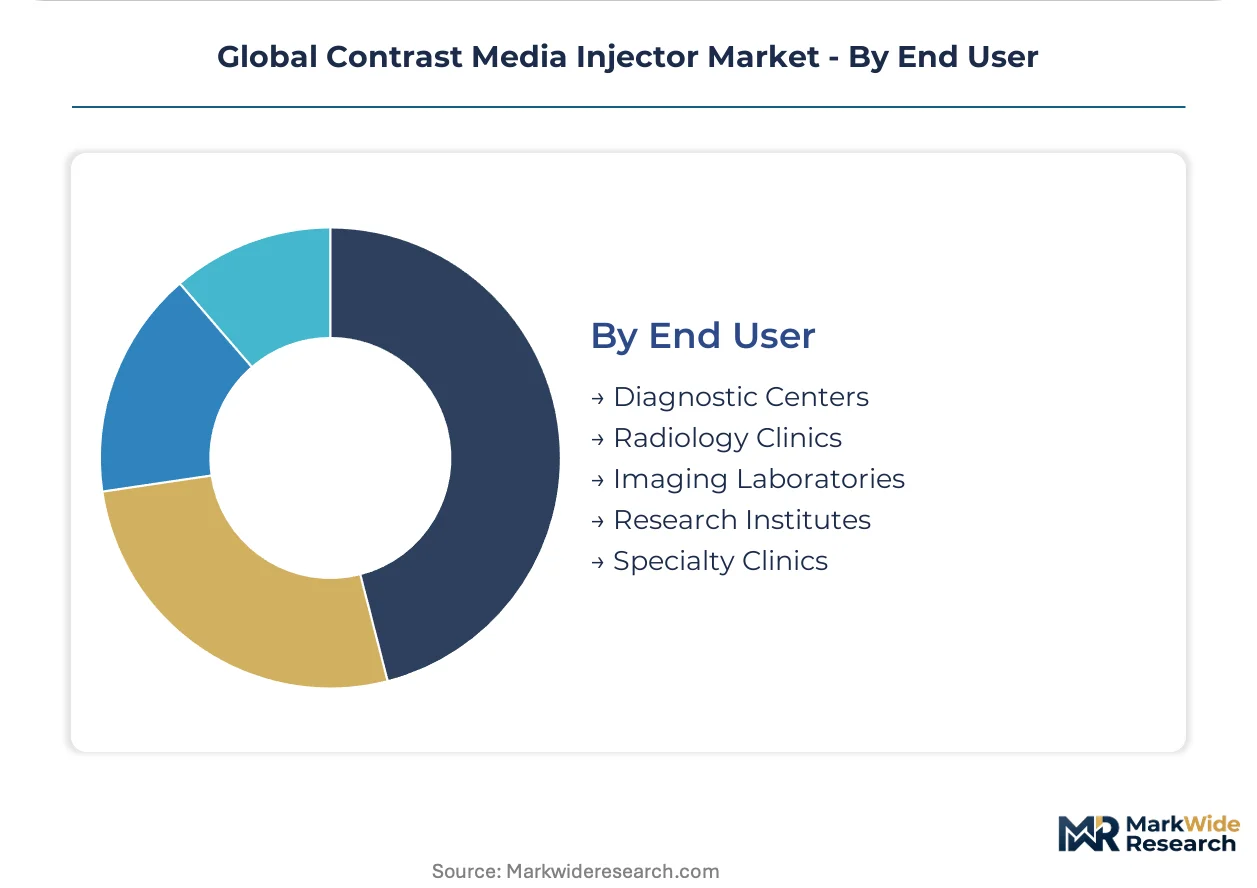
End User:
Customer type determines procurement authority concentration, with hospital-integrated networks exercising greater bundling leverage than independent operators.
- Diagnostic Centers:Standalone imaging facilities outside hospital systems, prevalent in India's metropolitan corridors and Brazil's urban centers, prioritize cost-optimized single-syringe configurations with minimal service contracts.
- Radiology Clinics:Physician-owned outpatient practices in United States suburban markets and German private healthcare clusters, where equipment financing and lease structures influence vendor selection.
- Imaging Laboratories:Hospital-embedded departments with centralized procurement through integrated delivery networks, particularly concentrated in United States southeastern and midwestern health systems.
- Research Institutes:Academic medical centers and contract research organizations requiring protocol flexibility and data export capabilities for clinical trial applications.
- Specialty Clinics:Cardiology-focused ambulatory surgery centers and orthopedic imaging practices with narrow procedure mixes and standardized injector requirements.
Imaging laboratories hold the largest share; diagnostic centers are expanding most quickly in emerging market urbanization corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for precision electromechanical components, while Shenzhen Bao'an International Airport freight corridors expedite Asian manufacturing scale. These infrastructure nodes synchronize injector assembly lines across three continents.
United States
Academic medical centers in Boston and Cleveland drive automated injector procurement for Joint Commission compliance. FDA 510(k) clearance timelines extend market access for novel architectures. The Research Triangle Park cluster in North Carolina concentrates biomedical engineering talent for service network expansion.
Germany
Charité Berlin and Heidelberg University Hospital anchor cardiac catheterization laboratory construction. EU MDR Article 10 technical documentation obligations accelerate replacement cycles for legacy mechanical units. The Baden-Württemberg medical technology corridor sustains precision manufacturing for pressure monitoring components.
China
Tier-two and tier-three hospital expansion in Sichuan and Shandong provinces pulls automated injector demand. NMPA registration pathway familiarity creates first-mover positioning for vendors targeting imaging infrastructure buildout. The Yangtze River Delta manufacturing basin supplies electromechanical subassemblies at scale.
Japan
Diagnostic chains in Tokyo and Osaka adopt electronic control platforms for PMDA radiation dose reporting mandates. PMDA quality system inspections create additional compliance layers for full geographic coverage. The Kansai medical device cluster specializes in DICOM-compliant data logging modules.
India
Standalone imaging centers in Mumbai and Bengaluru metropolitan corridors seek cost-optimized single-syringe configurations. CDSCO medical device registration requirements structure import substitution incentives for domestic assembly. The Hyderabad medical technology zone incubates electromechanical system maintenance training programs.
Global Contrast Media Injector Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in pressure sensor and flow control modules. Market structure concentrates among diversified health technology conglomerates and dedicated radiology equipment manufacturers. Three archetypes dominate: imaging modality bundlers, contrast agent portfolio owners, and manufacturing-scale specialists. Consolidation through multi-year supply agreements and equipment-software bundling displaces decentralized department-level purchasing authority.
Within the diversified health technology tier, Bayer AG and Siemens Healthineers exemplify platform breadth through radiology portfolio integration and direct modality bundling. Shenzhen Antmed Co., Ltd. occupies a position among manufacturing-scale specialists targeting cost-sensitive procurement tiers. These three anchors illustrate how vendor economics diverge between recurring software subscription revenue and hardware margin capture.
| Leading Market Players |
|---|
| Ulrich GmbH & Co. KG |
| Medtron AG |
| Bayer AG |
| Shenzhen Antmed Co., Ltd. |
| GE HealthCare |
| Bracco Imaging S.p.A. |
| Nemoto Kyorindo |
| Siemens Healthineers |
| Guerbet |
| Others |
Supply & Pricing Matrix
Undercapacity in Taiwanese semiconductor foundries is compressing margins for electronic control system manufacturers while simultaneously elevating pricing power for integrated device vendors with captive component supply. This utilization squeeze propagates through injector assembly lines in Germany and China, forcing procurement managers toward long-term offtake contracts that lock in volume-commitment discounts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared automated systems from CE-marked electromechanical units and unregulated manual alternatives. Price differentiation rests on certification tier and after-sales service bundling, with Joint Commission-compliant configurations commanding substantial premiums. Cost compression in the economy tier is intensifying because Shenzhen-based manufacturers are flooding tier-three Chinese hospitals with stripped-down single-syringe units. Diagnostic centers in India exhibit the highest price sensitivity, while United States academic medical centers prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn and Jabil for electronic control modules, while pressure sensor fabrication feeds from Bosch Sensortec and TE Connectivity facilities. Geographic supply concentration centers on Taiwan for semiconductors, Germany for precision electromechanical components, and China for molded plastic housings and cable assemblies. Raw material dependencies draw from Chilean iodine processing for contrast agent precursors, South Korean display panels for touchscreen interfaces, and Japanese rare earth elements for motor magnets. Single-source vulnerability in Taiwanese foundry capacity represents the dominant structural risk. Distribution runs through hospital procurement consortiums and integrated delivery networks that consolidate formerly fragmented department-level purchasing authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment erects substantial barriers: FDA 510(k) clearance timelines and EU MDR technical documentation obligations create switching costs that cement incumbent positions across multi-year hospital contracts.
For Market Incumbents: Insulate installed-base revenue by embedding software subscription tiers that monetize dose-tracking compliance and remote diagnostic capabilities. Deepen backward integration into pressure sensor manufacturing to offset semiconductor supply volatility. The emerging threat of AI-native injector startups with cloud-native architectures demands preemptive firmware investment in machine learning-enabled flow optimization. For New Entrants and Emerging Players: Establish a beachhead in India's standalone diagnostic center channel where cost-optimized single-syringe configurations face minimal regulatory friction and limited incumbent service coverage. White-space targets include tier-two Chinese hospitals outside the Yangtze River Delta manufacturing basin and Latin American private imaging networks. A direct-sales go-to-market angle leveraging equipment financing partnerships bypasses GPO contracting barriers that protect established vendors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated injector vendors with multi-year software maintenance attach rates above sixty percent, positioning these archetypes for premium valuation multiples. Long-term viability over the coming decade favors manufacturers with integrated contrast agent portfolios that enable bundling leverage in procurement negotiations. Acquisition targets should display NMPA registration pathway expertise for China market access. The critical inflection signal to monitor is iodine supply disruption frequency originating from Chilean processing concentration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates replacement cycles for legacy mechanical units across German hospital networks. |
| AI-Enabled Dose Optimization Development | Enables patient-specific flow rate adjustment based on anthropometric data in CT suites. |
| Hospital System Partnership Expansion | Secures multi-year bundled contracts with integrated delivery networks in the United States. |
| NMPA Registration Pathway Completion | Unlocks first-mover positioning in tier-two and tier-three Chinese hospital construction. |
| Software Companion Development | Generates recurring subscription revenue through PACS-integrated dose-tracking modules. |
Research Methodology
Cross-validation between primary interviews with hospital procurement managers, biomedical engineers, and GPO contracts specialists and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, and hospital capital equipment expenditure records anchors the qualitative findings. Bottom-up triangulation aggregates unit shipment estimates by product configuration and geography, while top-down reconciliation cross-checks against aggregate imaging modality installation data. The analysis draws from customs trade statistics for electromechanical component flows and PMDA quality system inspection reports for Japanese market access patterns.
Calibration against historical replacement cycle data for mechanical-to-electronic injector upgrades informs the projection framework across the analysis window. Segmentation dimensions modeled include product type, technology tier, application specialty, and end-user procurement authority concentration. CAGRs derive from weighted average of equipment refresh timelines and regulatory compliance-driven replacement mandates. Industry-specific forecast inputs incorporate Joint Commission medication safety standard adoption curves and EU MDR transition deadline impacts on European hospital capital budgets.
Sensitivities concentrate around iodine supply disruption scenarios, semiconductor foundry capacity utilization swings, and FDA 510(k) clearance timeline extensions for novel injector architectures. Forecasts reflect assumptions regarding continued consolidation of hospital procurement authority and sustained imaging infrastructure investment in China. Quarterly review of contrast agent precursor inventory levels, Taiwanese foundry utilization reports, and integrated delivery network merger activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Incontinence Devices and Ostomy Market
Medical Devices
Global Catheter Stabilization Devices Market
Medical Devices
Polyethersulfone Dialyzer Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Global Heart Valve Devices Market
Medical Devices
Operating Room Integration Market
Medical Devices
Wireless Surgical Cameras Market
Medical Devices
Oxygenator Market
Medical Devices
Ingestible Thermometers Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Radiotherapy Devices Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
Peripheral Vascular Guide Wire Market
Medical Devices
Tinnitus Maskers Market
Medical Devices
Transportable Ventilator Market
Medical Devices
India Biopsy Devices Market