
 Myoglobin Reagents Market | 2026-2036
Myoglobin Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Myoglobin Reagents Market Foresight
Aftermarket service revenue for reagent supply contracts is tilting toward platform-locked consumable models. Abbott Laboratories leverages its integrated diagnostic systems to secure multi-year reagent commitments across hospital networks. Roche Diagnostics anchors its position through proprietary electrochemiluminescence immunoassay architectures that bind customers to recurring reagent purchases. Siemens Healthineers competes by extending its Atellica platform with myoglobin assay menu expansions.
Myoglobin reagents comprise purified antibodies, calibrators, and control materials formulated for quantitative detection of the low-molecular-weight heme protein in human serum or plasma, typically utilizing immunoturbidimetric or chemiluminescent detection methods with analytical sensitivity thresholds below 10 ng/mL for early myocardial injury identification. Assay kits occupy the dominant product category due to bundled instrument-reagent agreements, while antibodies represent the fastest-expanding segment as third-party manufacturers develop open-system compatible polyclonal and monoclonal reagents. Clinical diagnostics generates the primary demand volume, though biopharmaceutical applications in cardiac toxicity screening during drug development are emerging as a structurally distinct margin pool.
FDA enforces Class II medical device controls over myoglobin assay systems through premarket notification pathways, while the EU MDR and IVDR frameworks impose strengthened post-market surveillance and performance verification obligations on reagent manufacturers seeking CE marking. ISO 13485 quality management certification functions as a de facto market access threshold for suppliers serving regulated jurisdictions. Stakeholders must monitor evolving harmonization between FDA and IVDR clinical evidence requirements when prioritizing geographic expansion or product registration sequencing.
Market Dynamics
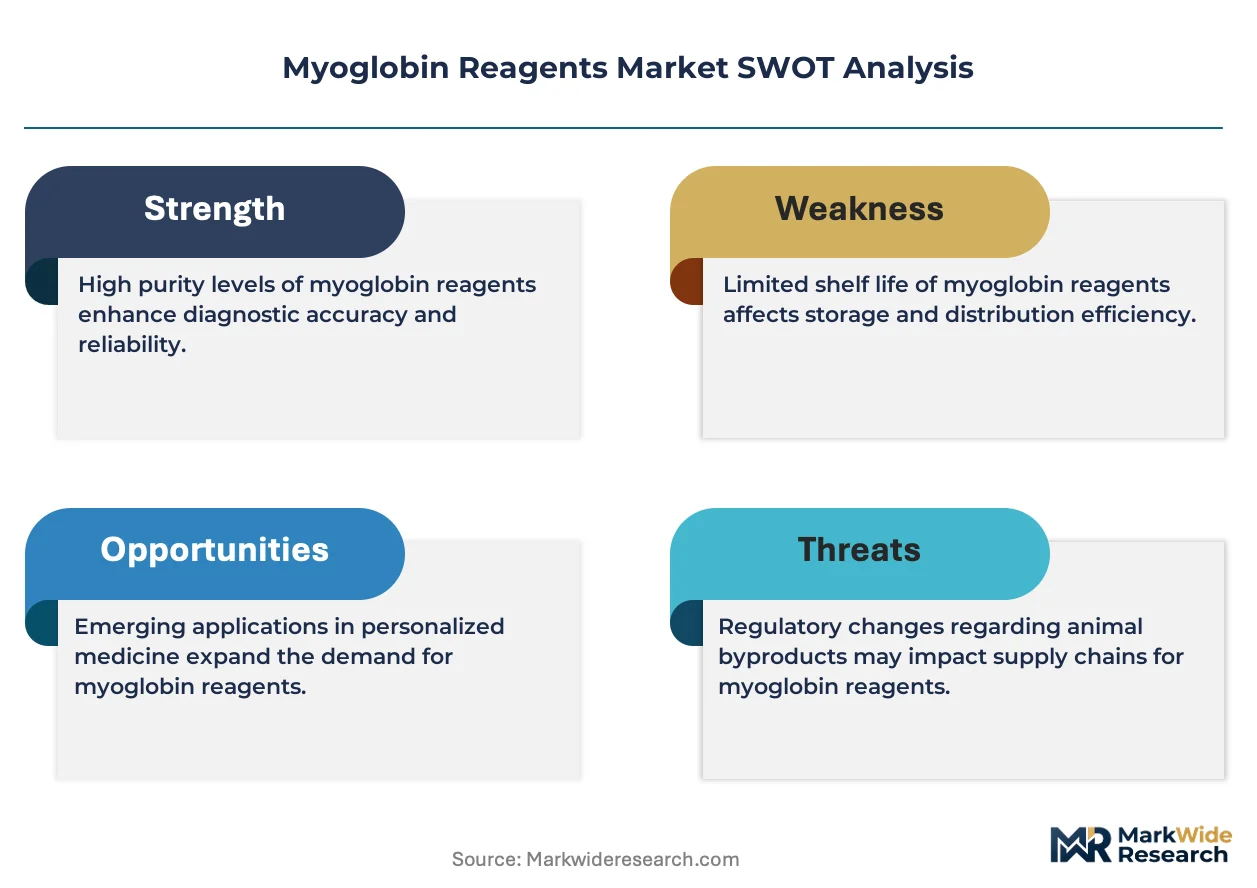
Platform-locked consumable models are consolidating procurement power among integrated diagnostic system vendors, compressing third-party reagent margins while embedding multi-year supply commitments into hospital capital equipment decisions.
Growth Catalysts
- High-sensitivity troponin companion testing:FDA clearance pathways for myoglobin assays used alongside cardiac biomarker panels are accelerating validation timelines and expanding test menus in US emergency departments.
- Centralized laboratory networks:Germany's hospital laboratory consolidation is standardizing myoglobin panels across regional networks, creating volume commitments that stabilize reagent demand.
- Immunoturbidimetric platform upgrades:Analytical sensitivity thresholds below 10 ng/mL are enabling earlier myocardial injury detection, extending test utility beyond traditional triage protocols.
Market Restraints
- Antibody input concentration:Purified polyclonal and monoclonal antibody supply is concentrated among a limited base of specialized bioreagent manufacturers, exposing reagent producers to batch-to-batch variability and price volatility.
- EU MDR compliance burden:Strengthened post-market surveillance and performance verification obligations under IVDR frameworks are extending CE marking timelines and elevating documentation costs for reagent manufacturers.
- High-sensitivity troponin substitution:Advances in troponin-I and troponin-T assay sensitivity are compressing myoglobin's diagnostic window in some acute coronary syndrome protocols, particularly in high-resource settings.
Strategic Opportunities
- Biopharmaceutical cardiac toxicity screening:Drug developers are adopting myoglobin reagents for preclinical and clinical-stage cardiotoxicity monitoring, creating a structurally distinct margin pool outside clinical diagnostics.
- Open-system antibody supply:Third-party manufacturers are developing platform-agnostic polyclonal and monoclonal reagents, enabling independent reagent vendors to bypass integrated system lock-in.
- ISO 13485 certification arbitrage:Quality management certification is functioning as a de facto market access threshold, allowing early-compliant suppliers to capture share in regulated jurisdictions before harmonization between FDA and IVDR evidence requirements completes.
Industry Challenges
- Electrochemiluminescence immunoassay expertise scarcity:The specialized technical workforce required for proprietary ECLIA architecture development and troubleshooting is concentrated among incumbent diagnostic platforms, constraining competitive entry.
- Legacy instrument-reagent contract integration:Hospital networks with embedded multi-year bundled agreements face switching costs that complicate competitive reagent procurement, forcing new entrants to front-load capital for buyout offers or parallel validation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myoglobin Reagents Market |
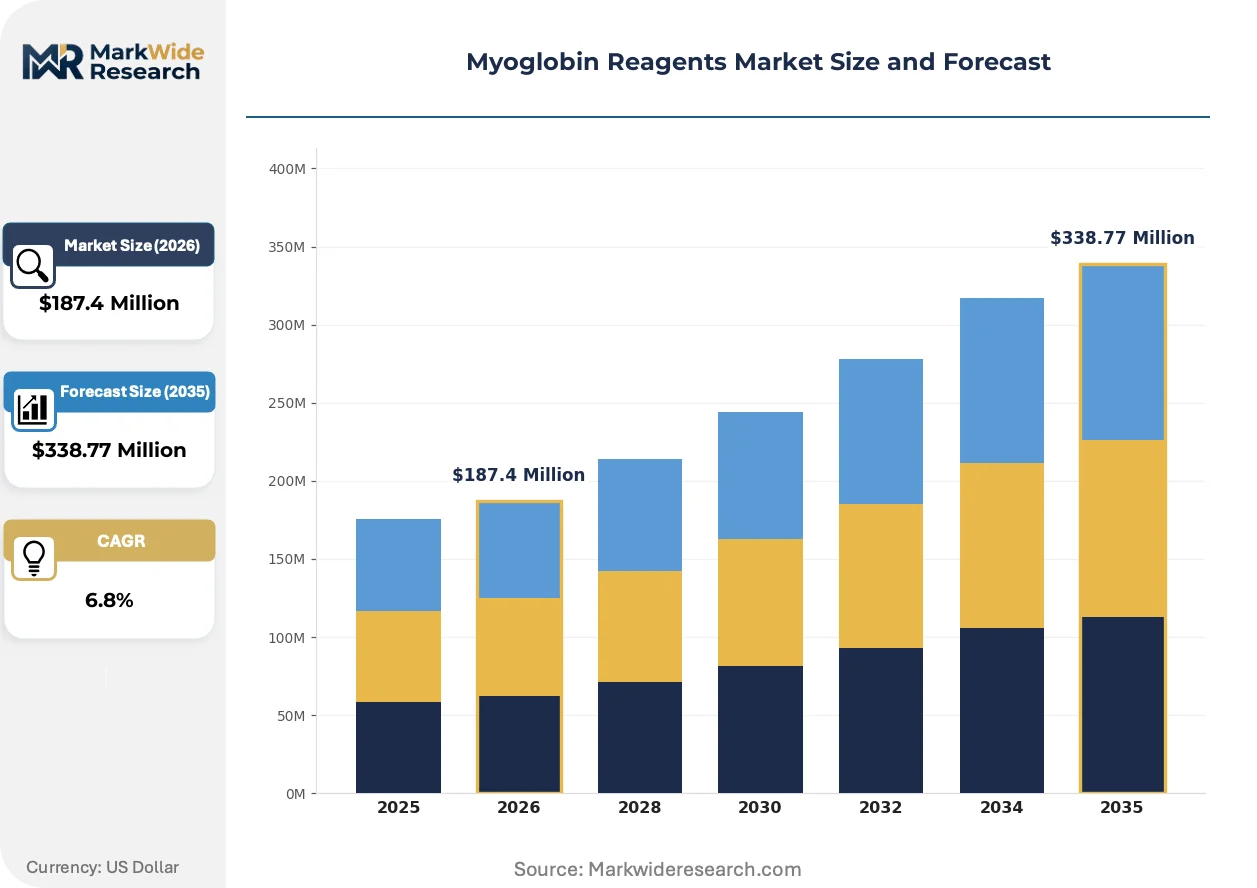
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibodies, Assay Kits, Controls, Standards Application: Clinical Diagnostics, Research Laboratories, Biopharmaceuticals, Quality Control End User: Hospitals, Diagnostic Centers, Academic Institutions, Pharmaceutical Companies Delivery Mode: Liquid, Lyophilized, Pre-mixed, Ready-to-use |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Thermo Fisher Scientific, Bio-Rad Laboratories, PerkinElmer, Randox Laboratories, Merck KGaA, Beckman Coulter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myoglobin Reagents Market Shifts & Advancements
Detection chemistry evolution and procurement model restructuring are compressing traditional competitive moats while elevating regulatory compliance as a strategic differentiator in reagent supply.
Next-generation chemiluminescent substrates with enhanced signal stability are extending assay shelf life and reducing calibration frequency. Reference laboratories in the United States are adopting these formulations to minimize quality control labor. Conventional enzymatic detection methods with shorter stability windows are rendering obsolete in high-throughput environments where uptime metrics determine contract renewals.
EU IVDR performance verification requirements are mandating expanded clinical evidence packages for myoglobin assay CE marking. Reagent manufacturers are restructuring regulatory affairs functions to manage parallel FDA and IVDR submission tracks. The antibody and calibrator supplier segment is most affected, with several third-party vendors delaying EU market entry until notified body capacity expands.
Hospital procurement departments are unbundling after-sales service from reagent supply contracts, separately negotiating platform maintenance and consumable pricing. Integrated diagnostic vendors are responding by tightening instrument-reagent bundling terms in initial equipment leases. This behavior is most visible in Germany, where centralized purchasing cooperatives leverage network scale to extract service unbundling concessions.
Myoglobin Reagents Market Segmentation
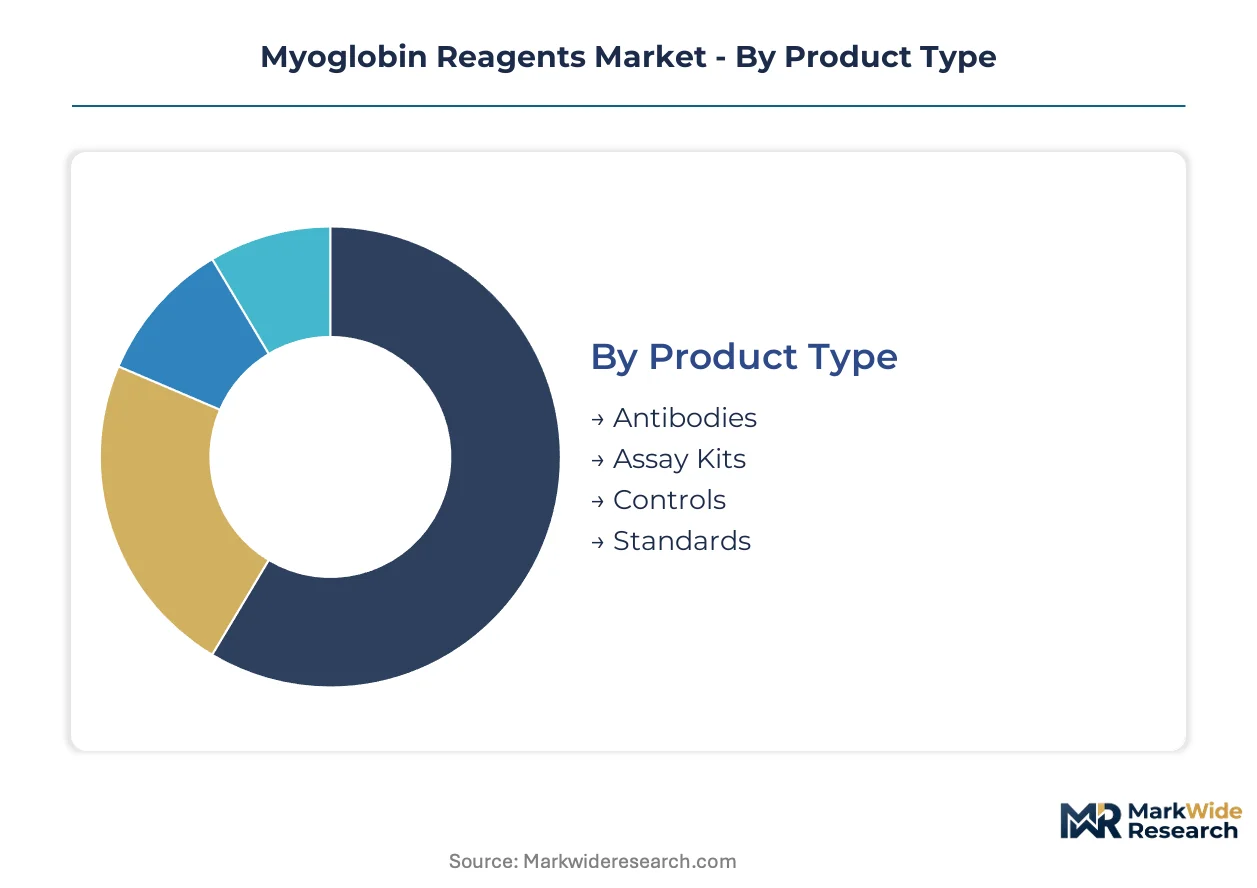
Myoglobin reagent procurement patterns diverge sharply across product formats and institutional settings, with after-sales service intensity varying from instrument-locked consumable bundles to discrete antibody supply contracts. Platform integration depth and regulatory validation requirements reshape margin structures within each segment category.
Product Type:
After-sales service intensity peaks with assay kits requiring ongoing calibration support and quality control troubleshooting, while antibody supply operates through simpler replenishment models with lower technical touch requirements.
- Assay Kits:Bundled instrument-reagent agreements dominate hospital procurement, embedding multi-year consumable commitments within capital equipment leases. Siemens Healthineers extends its Atellica platform menu through integrated myoglobin assay kits, capturing recurring revenue streams across German hospital networks. By volume, Assay Kits leads. By growth pace, Antibodies is ahead.
- Antibodies:Purified polyclonal and monoclonal formulations for immunoturbidimetric and chemiluminescent detection are expanding fastest as third-party manufacturers develop open-system compatible reagents. Batch-to-batch variability from concentrated bioreagent suppliers constrains pricing power for independent reagent vendors in the United States.
- Controls:Quality control materials with defined myoglobin concentrations stabilize assay performance across calibration cycles. Reference laboratories in Germany adopt these formulations to maintain IVDR compliance under strengthened post-market surveillance obligations.
- Standards:Calibrator materials traceable to international reference preparations anchor quantitative accuracy. ISO 13485-certified suppliers leverage these products as market access enablers in regulated jurisdictions.
Cost tier stratification separates premium instrument-locked kits from commoditized antibody supply, with mid-tier open-system reagents gaining procurement traction.
Application:
Volume concentration and margin structure diverge between high-throughput clinical testing environments and emerging biopharmaceutical screening protocols with distinct technical specifications.
- Clinical Diagnostics:Emergency department triage for acute myocardial infarction generates the dominant demand volume, with high-sensitivity troponin companion testing accelerating FDA validation timelines for myoglobin panels. US hospital laboratories are expanding testing protocols under cleared assay pathways. By volume, Clinical Diagnostics leads. By growth pace, Biopharmaceuticals is ahead.
- Biopharmaceuticals:Preclinical and clinical-stage cardiotoxicity monitoring during drug development creates a structurally distinct margin pool with specialized sensitivity requirements. Drug developers in the United States adopt myoglobin reagents for cardiac safety pharmacology studies.
- Research Laboratories:Academic and institutional investigators utilize myoglobin detection for mechanistic studies of muscle injury and oxidative stress. Funding concentration at major US medical centers shapes regional demand patterns.
- Quality Control:Manufacturing batch release testing and stability monitoring for therapeutic proteins drives consistent low-volume demand. ISO 13485 certification functions as a de facto supplier qualification threshold.
Margin concentration tilts toward biopharmaceutical applications despite smaller absolute volume, while clinical diagnostics anchors revenue stability through embedded supply contracts.
End User:
Procurement sophistication and contract negotiation leverage vary systematically across centralized hospital networks, fragmented diagnostic centers, and research-oriented institutions with distinct funding mechanisms.
- Hospitals:Centralized laboratory networks in Germany standardize cardiac biomarker panels across regional systems, creating volume commitments that stabilize reagent demand. Multi-year bundled agreements with integrated diagnostic vendors compress third-party competitive entry.
- Diagnostic Centers:Independent reference laboratories in the United States prioritize assay throughput and uptime metrics in contract renewals, favoring next-generation chemiluminescent substrates with extended stability windows.
- Academic Institutions:Research funding cycles and grant-dependent purchasing create irregular procurement patterns with price sensitivity elevated relative to clinical settings.
- Pharmaceutical Companies:Cardiac safety pharmacology groups within large drug developers specify myoglobin reagents for GLP-compliant toxicology studies, requiring extensive documentation packages.
Hospital networks command the steepest volume discounts through cooperative purchasing, while pharmaceutical end users absorb premium pricing for specialized validation support.
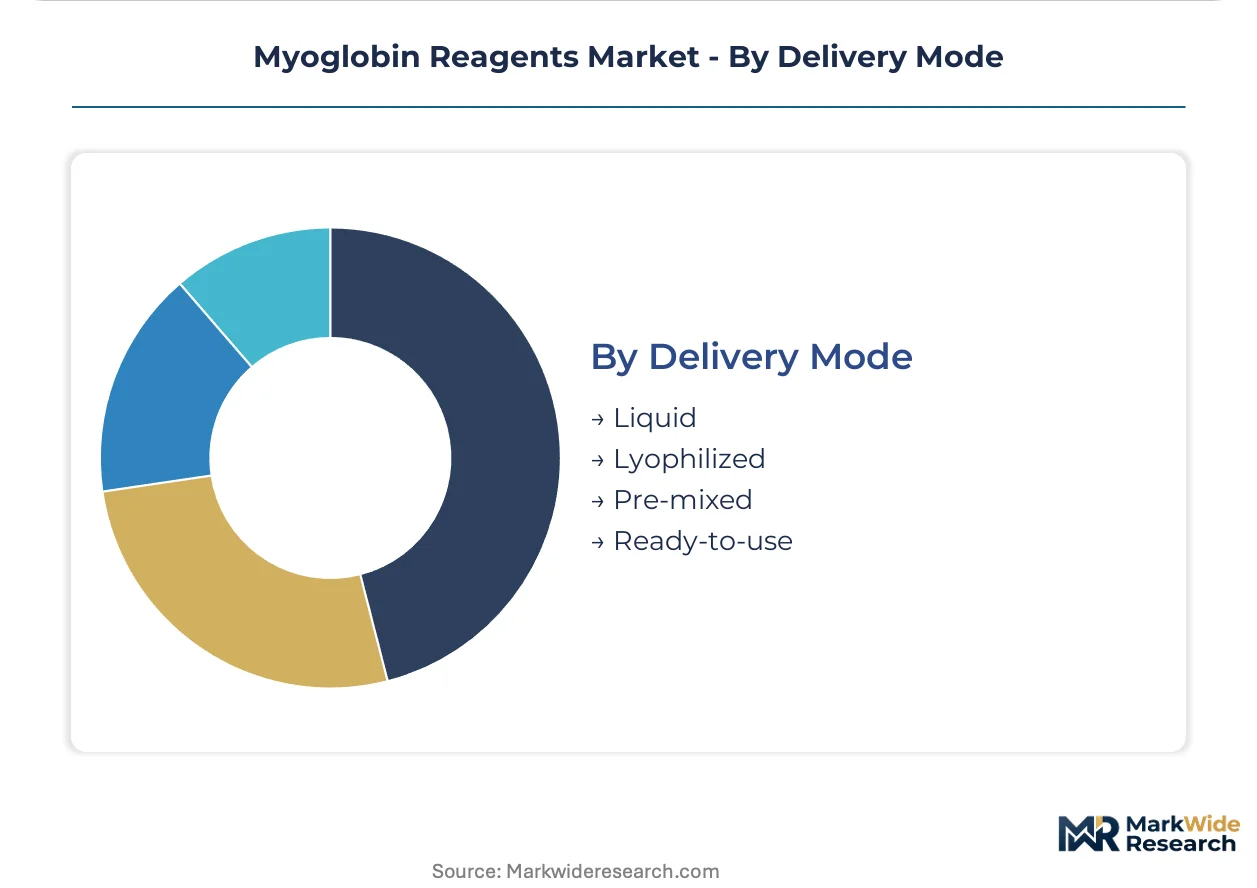
Delivery Mode:
Supply chain configuration and shelf-life economics reshape competitive positioning across formulation types with distinct stability profiles and handling requirements.
- Liquid:Ready-to-use formulations minimize preparation labor in high-throughput clinical environments. Roche Diagnostics anchors its proprietary electrochemiluminescence immunoassay architectures with liquid-stable reagents that reduce calibration frequency.
- Ready-to-use:Pre-formulated reagents with defined analytical sensitivity below 10 ng/mL enable early myocardial injury detection without end-user preparation. US emergency departments favor these formats for rapid turnaround requirements.
- Lyophilized:Freeze-dried formulations extend shelf life for antibody and control materials shipped to distributed laboratory networks. Reconstitution protocols add technical training burdens for smaller diagnostic centers.
- Pre-mixed:Blended reagent cocktails streamline workflow for specific instrument platforms, binding customers to proprietary consumable supply.
Ready-to-use formats are displacing lyophilized alternatives in time-sensitive clinical applications, while lyophilized antibodies retain cost advantages for research and quality control settings with lower throughput requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams in Germany absorb premium pricing for integrated diagnostic systems, while independent reference laboratories in the United States negotiate aggressively on reagent unit costs. Price elasticity diverges sharply between centralized European networks and fragmented North American buyers.
United States
Emergency departments in Cleveland Clinic and Mayo Clinic networks are expanding myoglobin testing protocols for acute myocardial infarction triage. FDA premarket notification pathways for high-sensitivity troponin companion assays are compressing validation timelines for reagent manufacturers. The Boston-Cambridge biopharmaceutical corridor is driving demand for cardiac toxicity screening reagents in drug development pipelines.
Germany
Centralized hospital laboratory networks in North Rhine-Westphalia and Bavaria are standardizing cardiac biomarker panels across regional systems. EU IVDR performance verification obligations are extending CE marking timelines for reagent producers seeking market access. The Heidelberg-Mannheim medical technology cluster hosts specialized bioreagent manufacturers supplying purified antibodies to diagnostic platforms.
China
Domestic diagnostic reagent producers in Shanghai and Suzhou are developing open-system compatible myoglobin antibodies to bypass integrated platform lock-in. NMPA Class II medical device registration requirements are strengthening quality management system audits for imported reagent suppliers. The Yangtze River Delta concentration of IVD manufacturers is accelerating localization of chemiluminescent substrate production.
Japan
Academic medical centers in Tokyo and Osaka are adopting next-generation chemiluminescent formulations with extended shelf stability. PMDA quality management regulations align with ISO 13485 standards for reagent importation and distribution. The Kobe biomedical innovation cluster supports specialized antibody suppliers serving domestic diagnostic instrument manufacturers.
United Kingdom
NHS pathology networks in London and Manchester are consolidating cardiac biomarker testing into centralized hub laboratories. MHRA post-Brexit regulatory frameworks maintain alignment with IVDR technical standards for reagent market authorization. The Cambridge life sciences corridor is emerging as a demand center for research-grade myoglobin reagents in mechanistic muscle injury studies.
Myoglobin Reagents Market Competitive Landscape
Capability concentration sits with integrated diagnostic system vendors commanding proprietary electrochemiluminescence architectures; scale advantage sits with diversified life science conglomerates distributing reagents across fragmented laboratory networks. The market structures around three archetypes: platform-locked consumable suppliers embedding multi-year commitments, open-system antibody specialists bypassing instrument bundling, and reference standard providers anchoring quantitative accuracy. Dominant competitive moves include strategic partnerships between instrument manufacturers and bioreagent suppliers, plus geographic expansion through ISO 13485-certified distribution subsidiaries.
Within the integrated platform tier, Abbott Laboratories and Roche Diagnostics exemplify the instrument-reagent bundling model that captures recurring revenue across hospital networks. Siemens Healthineers occupies a position bridging proprietary platform extensions with menu expansion strategies. Among diversified suppliers, Thermo Fisher Scientific represents the scale-driven archetype leveraging broad life science distribution infrastructure.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| PerkinElmer |
| Randox Laboratories |
| Merck KGaA |
| Beckman Coulter |
| Others |
Supply & Pricing Matrix
Purified antibody supply from specialized bioreagent manufacturers in Germany and the United States anchors margin distribution downstream, with platform-locked consumable models capturing recurring revenue pools while independent reagent vendors compete on batch consistency and open-system compatibility.
Pricing Analysis
After-sales service revenue from multi-year reagent supply contracts drives lifetime value for integrated diagnostic vendors. Three-tier pricing structure across premium instrument-locked kits, mid-tier open-system reagents, and commoditized antibody supply segments the market. Price differentiation rests on ISO 13485 certification grade and after-sales bundling intensity. Cost compression in the antibody tier is intensifying because concentrated bioreagent suppliers expose reagent producers to batch-to-batch variability. Academic institutions exhibit the highest price sensitivity; pharmaceutical end users absorb premium pricing for specialized validation support.
Supply Chain Analysis
Upstream feedstock of purified polyclonal and monoclonal antibodies draws from specialized bioreagent manufacturers concentrated in Germany, the United States, and Japan. Critical inputs include recombinant protein expression systems, affinity chromatography resins, and international reference standard preparations. Single-source vulnerability from limited qualified antibody suppliers constrains reagent producer flexibility. Distribution runs through direct sales forces for hospital networks and specialized life science distributors for research and biopharmaceutical end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA premarket notification and EU IVDR CE marking creates durable barriers against competitive replication.
For Market Incumbents: Build switching-cost moats by tightening instrument-reagent bundling terms in initial equipment leases to compress third-party competitive entry. Extend proprietary electrochemiluminescence immunoassay architectures with expanded myoglobin assay menus to capture recurring revenue across hospital networks. High-sensitivity troponin substitution pressure demands countermeasures through companion testing protocol development.
For New Entrants and Emerging Players: Build out open-system antibody supply capabilities to bypass integrated platform lock-in and serve fragmented diagnostic centers. Biopharmaceutical cardiac toxicity screening represents the most penetrable application segment with structurally distinct margin pools and lower incumbent concentration. Target ISO 13485 certification arbitrage to capture share in regulated jurisdictions before FDA-IVDR harmonization completes.
For Investors and Strategic Acquirers: Capital is best deployed toward platform-agnostic bioreagent specialists with established antibody supply relationships and regulatory affairs infrastructure. Long-term viability across the projection horizon hinges on diversification beyond clinical diagnostics into biopharmaceutical safety pharmacology. Monitor notified body capacity expansion in the EU as an inflection indicator for CE marking timeline normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Performance Verification Pathway | Expands clinical evidence packages for CE marking to meet notified body requirements. |
| Hospital System Partnership | Secures multi-year reagent commitments through embedded instrument-reagent bundling. |
| Open-System Antibody Development | Enables third-party vendors to bypass proprietary platform lock-in and capture share. |
| Biopharmaceutical Segment Expansion | Diversifies revenue into cardiac toxicity screening with specialized sensitivity requirements. |
| ISO 13485 Certification Investment | Functions as de facto market access threshold in regulated jurisdictions. |
Research Methodology
A spread of perspectives from diagnostic platform engineers, hospital laboratory directors, regulatory affairs specialists, and biopharmaceutical safety pharmacologists converged on the working assumptions driving this analysis. Primary interviews combined with secondary validation from FDA 510(k) filings, EU IVDR technical documentation, hospital procurement databases, and GPO contract records. Bottom-up reagent volume estimates triangulated against top-down diagnostic platform installed base data.
Demand-supply balance modeling across the analysis window integrated assay kit, antibody, control, and standard product segments with clinical diagnostics, biopharmaceutical, research laboratory, and quality control applications. End-user stratification captured hospitals, diagnostic centers, academic institutions, and pharmaceutical companies. CAGRs derived from segment-level growth trajectory convergence. Forecast inputs included high-sensitivity troponin companion testing adoption curves and IVDR notified body capacity constraints.
Stress conditions across antibody supply concentration, regulatory timeline extension, and troponin substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from technological shifts or harmonization between FDA and IVDR clinical evidence requirements. Cross-checking against hospital capital equipment procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
Organ Function Assays Market
Laboratory Services
Pathology Laboratories Market
Laboratory Services
Sera and Reagents Market
Laboratory Services
Cytotoxicity Assays Market
Laboratory Services
AI in Laboratory Solution Market
Laboratory Services
Lab Mailers Market
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Latin America Clinical Laboratory Services Market
Laboratory Services
Global Virology Specimen Collection Market
Laboratory Services
Central Lab Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
Karyotyping Service Market
Laboratory Services
Pathology Services Market