
 Cervical Fusion Market | 2026-2036
Cervical Fusion Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Fusion Market Analysis
Leasing arrangements for robotic navigation suites and spinal implant consignment inventory is reconfiguring capital deployment across the competitive landscape. Medtronic leverages its integrated spine platform to anchor hospital system contracts through bundled procedural economics. Stryker Corporation sustains competitive positioning via dedicated sales forces aligned with ambulatory surgery center channels. Globus Medical differentiates through manufacturing scale in titanium and PEEK interbody devices.
Cervical fusion encompasses surgical arthrodesis of adjacent cervical vertebrae using interbody spacers, anterior plating, and posterior screw-rod constructs to eliminate motion and decompress neural elements, typically performed at C3-C7 levels with titanium or polyether ether ketone implants achieving 90% or greater fusion rates at 24 months. Interbody devices and spinal stabilization systems command the dominant share of product revenue as hospitals standardize on integrated construct systems rather than component purchasing. Minimally invasive techniques represent the fastest-expanding technique segment, driven by reduced hospital length of stay and expanding ASC eligibility for single-level procedures. Titanium and polyether ether ketone materials partition the implant landscape, with titanium favored in osteoporotic bone and PEEK selected for radiolucent postoperative assessment.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access costs for implant manufacturers across North America and Europe. ISO 10993 biocompatibility testing and ASTM F2077 mechanical standards govern material qualification and fatigue performance for cervical plate and screw systems. Stakeholders must monitor evolving CMS procedural payment adjustments and site-of-care migration patterns to align portfolio positioning with where cervical fusion volumes will concentrate.
Market Dynamics
Site-of-care migration from inpatient hospitals to ambulatory surgical centers is compressing procedure economics and forcing implant manufacturers to reconfigure pricing and inventory deployment models around lower-reimbursement settings.
Growth Catalysts
- EU MDR streamlining:The Medical Device Regulation's refined technical documentation pathways for spinal implant conformity assessment are accelerating market access timelines for titanium interbody cage manufacturers targeting European hospital systems.
- ASC eligibility expansion:Payor authorization for single-level cervical fusion in ambulatory settings is pulling procedure volumes away from inpatient facilities and into specialized outpatient surgical centers.
- Titanium surface engineering:Advanced additive manufacturing of porous titanium interbodies with optimized bone ingrowth architecture is improving fusion rates in osteoporotic patient populations.
Market Restraints
- PEEK raw material concentration:Polyether ether ketone resin supply for radiolucent implants concentrates among a limited set of European chemical suppliers, exposing manufacturers to input cost volatility.
- FDA 510(k) substantive review:FDA's heightened scrutiny of cervical plate biomechanical testing data is extending clearance timelines for novel screw-rod construct designs.
- Motion-preserving substitution:Cervical disc arthroplasty systems are capturing select patient indications previously routed toward fusion, particularly among younger demographics with preserved segmental motion.
Strategic Opportunities
- German KBA reimbursement tailwind:Hospital reimbursement reforms under Germany's KBA framework are favoring both motion-preserving and fusion-based cervical interventions, creating dual-pathway market expansion.
- Robotic navigation convergence:Integration of intraoperative navigation with interbody placement workflows is enabling precise screw trajectory planning and reducing revision rates.
- Direct-to-ASC distribution:Implant consignment inventory models bypassing traditional hospital supply chains are capturing preference among independent ambulatory surgical centers seeking working capital efficiency.
Industry Challenges
- Biomechanical testing capacity:ISO 10993 and ASTM F2077 qualification requirements for fatigue performance validation are creating bottlenecks at specialized spinal implant testing laboratories.
- Sales force reconfiguration:Transition from hospital-based to ASC-focused account management demands new clinical education capabilities and compressed case-support response times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Fusion Market |
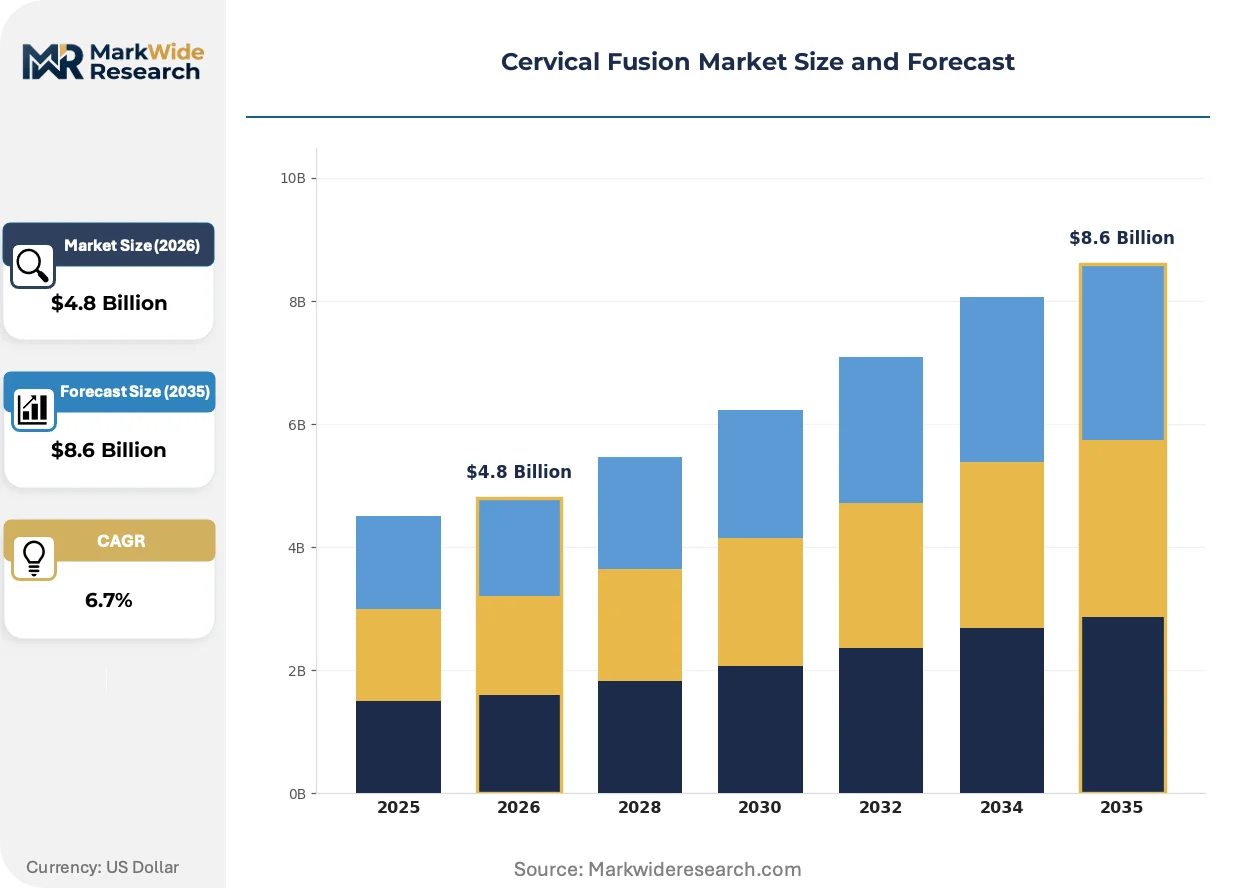
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interbody Devices, Spinal Stabilization Systems, Plates, Screws End User: Hospitals, Surgical Centers, Orthopedic Clinics, Rehabilitation Facilities Technique: Anterior Approaches, Posterior Approaches, Minimally Invasive Techniques, Hybrid Techniques Material: Titanium, Polyether Ether Ketone, Ceramic, Biodegradable Polymers |
| Companies Covered | Medtronic, DePuy Synthes, Stryker Corporation, Zimmer Biomet Holdings, Globus Medical, NuVasive, Orthofix, B. Braun, Alphatec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Fusion Market Emerging Trajectories
Digital surgical planning and intraoperative guidance systems are virtualizing traditional open-procedure workflows, while material science advances and reimbursement recalibration simultaneously reshape competitive positioning across implant categories.
Patient-specific interbody cages derived from preoperative CT segmentation are virtualizing the implant selection process for complex cervical anatomy. High-volume ASC networks are adopting these planning workflows to reduce operative time and implant misfit revisions. The technology is virtualizing the role of standard-sized implant inventories and compressing the economics of bulk device procurement.
FDA's refined 510(k) pathway for titanium interbody cages is compressing approval timelines for US market entrants while maintaining mechanical performance standards. Manufacturers are responding by front-loading biomechanical testing investments and prioritizing predicate device alignment strategies. The regulatory refinement most directly benefits mid-tier manufacturers seeking to challenge incumbent integrated spine platform providers.
Buyer concentration among consolidated hospital systems and specialized ASC chains is consolidating procurement leverage and unbundling after-sales technical support from device pricing. Independent surgery centers are negotiating direct manufacturer relationships that displace traditional distributor intermediaries. This channel restructuring is most visible in Florida and Texas, where ASC ownership consolidation has created regional purchasing cooperatives with standardized implant preference lists.
Cervical Fusion Market Segmentation
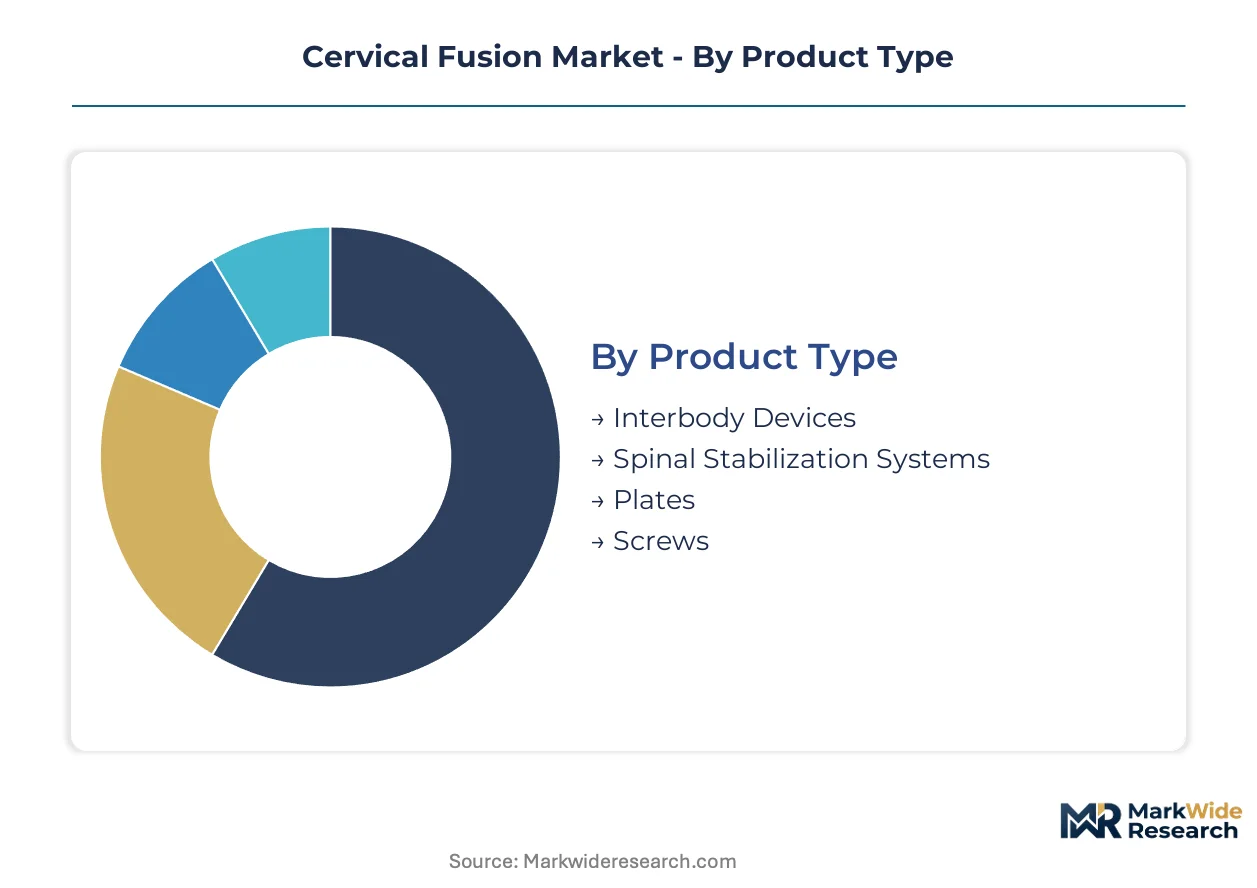
Implant manufacturers configure R&D pipelines and sales force deployment around distinct product-material-technique combinations. Segmentation clarity determines which cervical fusion categories warrant manufacturing scale investments versus niche positioning.
Product Type:
Interbody devices and spinal stabilization systems command the longest sales cycles due to hospital capital committee approvals, while plates and screws turn over faster through routine replenishment purchasing.
- Interbody Devices:Titanium and PEEK cages inserted between vertebral bodies restore disc height and enable bone ingrowth. Demand concentrates in Germany where KBA reimbursement reforms favor integrated construct systems.
- Spinal Stabilization Systems:Screw-rod constructs spanning multiple vertebral levels provide posterior fixation. Academic medical centers in the United States drive specifications for these systems as FDA 510(k) clearance timelines compress for predicate-aligned designs.
- Plates:Anterior cervical plates lock interbody spacers in position. Ambulatory surgical centers favor streamlined plating systems with reduced screw profiles.
- Screws:Pedicle and lateral mass screws anchor rod constructs. High-volume spine centers in Texas and Florida negotiate direct manufacturer contracts for screw replenishment.
Interbody devices dominate installed base. Spinal stabilization systems are where expansion concentrates.
End User:
Procurement sophistication varies sharply across settings, with hospital system GPOs demanding bundled pricing while independent surgical centers prioritize consignment inventory flexibility.
- Hospitals:Inpatient facilities perform multi-level fusions with extended length-of-stay requirements. Consolidated US hospital systems leverage purchasing cooperatives to unbundle technical support from device pricing.
- Surgical Centers:Ambulatory settings execute single-level procedures under compressed reimbursement schedules. Independent ASC networks in Florida and Texas are adopting direct-to-manufacturer distribution models.
- Orthopedic Clinics:Specialist practices provide preoperative planning and postoperative monitoring. German orthopedic clinics coordinate with KBA-accredited hospitals for motion-preserving referral pathways.
- Rehabilitation Facilities:Post-acute centers manage fusion recovery protocols. Medicare reimbursement adjustments shape referral patterns to these settings.
Hospitals retain the deepest implant inventories. Surgical centers are gaining share fastest.
Technique:
Training requirements and capital equipment needs create diverging margin profiles across anterior, posterior, and minimally invasive approaches.
- Anterior Approaches:Anterior cervical discectomy and fusion accesses the spine through the neck. This technique maintains volume concentration in US hospital systems with established ACDF protocols.
- Posterior Approaches:Laminectomy and fusion address posterior element pathology. Academic centers favor posterior techniques for complex deformity correction.
- Minimally Invasive Techniques:Lateral and percutaneous access reduce tissue disruption. ASC eligibility expansion is pulling these procedures into outpatient settings.
- Hybrid Techniques:Combined anterior-posterior approaches address multi-level pathology. German hospitals deploy hybrid techniques under KBA framework reimbursement for complex cases.
Anterior approaches anchor current procedure volumes. Minimally invasive techniques are climbing the fastest.
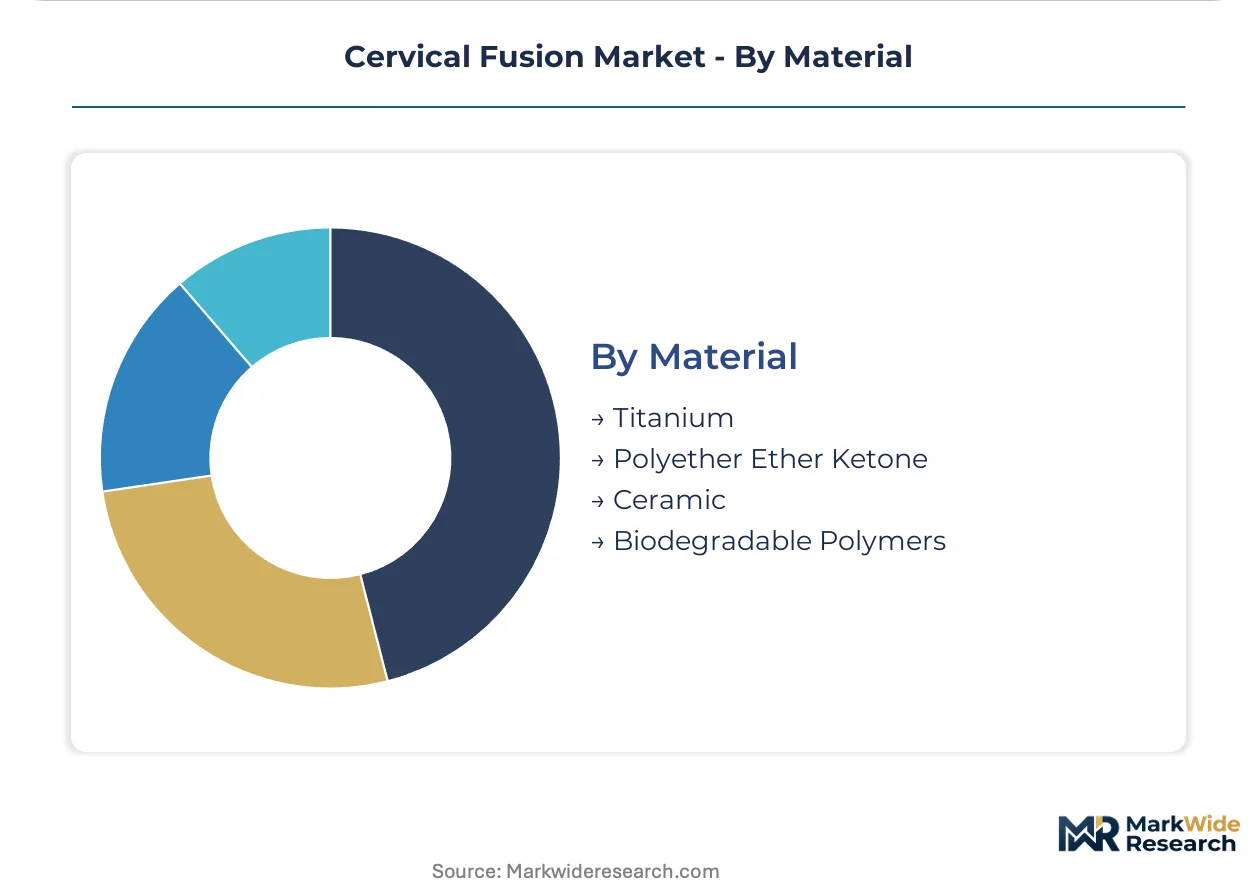
Material:
Raw material sourcing concentration and biocompatibility testing burdens stratify competitive economics across implant substrates.
- Titanium:Porous additive-manufactured titanium interbodies optimize bone ingrowth architecture. Osteoporotic patient populations in the United States favor titanium for fixation security.
- Polyether Ether Ketone:Radiolucent PEEK enables clear postoperative CT assessment. European chemical suppliers concentrate PEEK resin supply, exposing manufacturers to input cost volatility.
- Ceramic:Alumina and zirconia compositions offer wear resistance. Ceramic interbodies occupy niche positioning for motion-preserving adjacent segments.
- Biodegradable Polymers:Resorbable scaffolds eliminate long-term implant presence. Early-stage clinical adoption concentrates in German and Swiss research hospitals.
Titanium and PEEK partition commercial volume. Titanium surface engineering is where R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net import dependence for titanium interbody cages concentrates in the United States and Germany, while China and India remain net importers of precision-machined spinal instrumentation. Trade flows reflect specialized manufacturing capabilities clustered around regulatory approval hubs.
United States
FDA 510(k) clearance compresses approval timelines for predicate-aligned titanium cage designs. Ambulatory surgical centers in Florida and Texas are consolidating into regional purchasing cooperatives with standardized implant preference lists. The Southeast corridor anchors the fastest site-of-care migration volume.
Germany
KBA hospital reimbursement reforms favor integrated construct systems for motion-preserving and fusion-based interventions. The Medical Device Regulation's streamlined conformity assessment accelerates market access for titanium interbody manufacturers. Baden-Württemberg hosts concentrated spine technology R&D clusters serving European hospital systems.
China
NMPA regulatory pathways for imported spinal implants create extended registration timelines for foreign manufacturers. Domestic titanium additive manufacturing capabilities are expanding in Jiangsu and Zhejiang provinces. Shanghai medical device zones concentrate localization partnerships for multinational spine platforms.
Japan
PMDA reimbursement pricing for cervical fusion procedures under universal health coverage shapes implant procurement economics. Aging demographics drive procedural volume concentration in Kanto and Kansai metropolitan hospital networks. Osaka-based orthopedic distributors coordinate inventory deployment for specialized spine centers.
India
CDSCO medical device rules classify cervical plates and screws under regulated import categories with quality certification requirements. Corporate hospital chains in Maharashtra and Karnataka standardize on titanium interbody systems for cost-sensitive patient segments. Chennai orthopedic device distributors negotiate direct manufacturer relationships bypassing traditional intermediaries.
Cervical Fusion Market Vendor Landscape
On the supply side, the industry is consolidating around integrated spine platforms with bundled procedural economics. Tiered competitive strata separate multinational platform providers from specialized interbody manufacturers and regional instrumentation suppliers. Strategic archetypes include full-platform integrators, material-science specialists, and ASC-focused distributors. Dominant competitive moves encompass hospital system contract anchoring and direct-to-ASC distribution model deployment.
Within the integrated platform tier, Medtronic and Stryker Corporation represent archetypal full-solution providers with hospital system contract depth. Globus Medical occupies a position exemplifying manufacturing-scale specialization in titanium and PEEK interbody segments. These three entities anchor the competitive structure through divergent channel strategies spanning inpatient capital committees and ambulatory surgical center procurement.
| Leading Market Players |
|---|
| Medtronic |
| DePuy Synthes |
| Stryker Corporation |
| Zimmer Biomet Holdings |
| Globus Medical |
| NuVasive |
| Orthofix |
| B. Braun |
| Alphatec |
| Others |
Supply Flow & Price Mechanics
PEEK resin supply concentration among European chemical suppliers in Germany and the Netherlands funnels pricing power downstream toward implant manufacturers, while titanium sponge sourcing from Japanese and Chinese smelters creates divergent margin pools for additive-manufactured versus machined interbody devices.
Pricing Analysis
Hospital system GPO buyers anchor contract-based long-term pricing structures, with premium-mid-economy pricing differentiation driven by FDA 510(k) predicate alignment and after-sales technical support bundling. Price erosion runs through ambulatory surgical center tiers as direct-to-manufacturer distribution disintermediates traditional distributor markups. Independent ASC networks in Florida and Texas exhibit highest price sensitivity, while consolidated hospital systems with integrated spine platform contracts demonstrate lowest sensitivity due to bundled procedural economics.
Supply Chain Analysis
Export control regimes limiting advanced additive manufacturing equipment flows constrain titanium porous interbody production capacity expansion outside established regulatory hubs. Supply concentrates in the United States, Germany, and Switzerland for precision-machined spinal instrumentation, while PEEK resin feedstock draws from German and Dutch chemical suppliers. Single-source vulnerability pervades the PEEK polymer tier, with distribution running through specialized orthopedic device distributors coordinating consignment inventory for hospital and ASC channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Site-of-care fragmentation from inpatient hospitals to ambulatory surgical centers creates niche positioning opportunities for manufacturers configuring distinct pricing and inventory models around lower-reimbursement settings.
For Market Incumbents: Insulate hospital system contract depth by embedding robotic navigation suites into bundled procedural offerings, while accelerating backward integration into titanium additive manufacturing to offset PEEK resin cost volatility from European chemical suppliers. For New Entrants and Emerging Players: Build out direct-to-ASC distribution capabilities targeting independent surgery center networks in Texas and Florida, leveraging FDA 510(k) pathway refinements for predicate-aligned titanium cage designs to compress market entry timelines. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier manufacturers with manufacturing-scale specialization in titanium surface engineering, as reimbursement tailwinds from German KBA reforms and US site-of-care migration signal long-term viability across the analysis window; monitor FDA 510(k) clearance velocity for novel screw-rod constructs as an inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Compressed approval timelines for predicate-aligned titanium interbody cages accelerate US market access. |
| CE Marking Pathway | EU MDR streamlined conformity assessment reduces technical documentation burden for European hospital entry. |
| Hospital System Partnership | Bundled procedural economics with integrated spine platforms anchor long-term contract relationships. |
| Software Companion Development | Digital surgical planning tools reduce operative time and implant misfit revisions for ASC networks. |
| Reimbursement Strategy | Alignment with German KBA reforms and US site-of-care migration captures volume concentration shifts. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) databases, EU MDR technical documentation filings, hospital procurement records, and CMS Medicare reimbursement data. Spine surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and ASC operations directors provided structured input. Bottom-up implant volume modeling triangulates against top-down market sizing from regulatory approval trajectories and site-of-care migration patterns.
Forecast inputs span product type, material substrate, surgical technique, end-user setting, and regional regulatory cluster across the projection horizon. CAGRs derive from segmented volume trajectory analysis incorporating reimbursement schedule adjustments, procedural eligibility expansion, and manufacturing capacity buildout timelines. Titanium surface engineering R&D pipelines and ASC network consolidation rates feed directly into growth assumptions.
Practitioners should monitor FDA substantive review intensity for novel screw-rod constructs and EU MDR notified body capacity constraints for early signals. Forecasts reflect assumptions around KBA reimbursement stability and PEEK resin supply continuity. Material shifts in CMS site-of-care payment differentials or German hospital reimbursement frameworks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bunion Correction Systems Market
Medical Devices
Transcatheter Pulmonary Valve Replacement Market
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
Digital Respiratory Devices Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Knee Reconstruction Devices Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
India Respiratory Devices Market
Medical Devices
Transcatheter Aortic Valve Implantation (TAVI) Market
Medical Devices
Morcellators Market
Medical Devices
United States Aesthetic Devices Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
IoT Medical Devices Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Skull Clamp Market