
 Global Industrial Labels Market | 2026-2036
Global Industrial Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Labels Market Foresight
Direct-to-manufacturer digital procurement channels is tilting volume away from traditional distributor networks. Avery Dennison Corporation leverages its materials science portfolio to dominate premium pressure-sensitive substrates. Brady Corporation specializes in safety identification systems for electrical equipment and chemical production environments. CCL Industries Inc. extends its position through in-mold and shrink sleeve capabilities serving food processing and pharmaceutical packaging lines.
Industrial labels are engineered substrates—polyester, polyimide, or vinyl films coated with pressure-sensitive adhesives or thermal transfer receptive layers—designed to withstand abrasion, chemical exposure, and temperature extremes while conveying identification, tracking, or hazard information. Thermal transfer technology leads in durability-critical applications where solvent resistance and print longevity justify higher equipment investment, while digital printing is capturing shorter-run, variable-data orders from warehousing operators and quality control units seeking reduced setup waste and faster turnaround.
OSHA's Hazard Communication Standard and the EU's REACH regulation shape material selection by restricting certain solvent-based adhesives and mandating standardized pictogram formats for chemical labels. The FDA's Unique Device Identification requirements and EPA's FIFRA labeling rules add compliance layers for pharmaceutical manufacturing and agricultural chemical production respectively. Stakeholders must monitor evolving substrate sustainability mandates and digital printing substrate compatibility as regulatory thresholds tighten and brand owners demand recyclable label constructions.
Market Dynamics
Digital procurement channels are collapsing traditional distributor hierarchies as manufacturers demand direct substrate sourcing with faster turnaround and lower markup structures. REACH substrate disclosure mandates and OSHA HazCom pictogram standardization are simultaneously tightening material specifications while opening specification windows for compliant suppliers.
Growth Catalysts
- REACH chemical disclosure mandates:ECHA's substrate toxicity reporting requirements force label converters to qualify new adhesive formulations, expanding procurement volumes for compliant material suppliers serving EU chemical exporters.
- GHS hazard communication standardization:Chemical production facilities in Germany's industrial corridor require multi-language durable labels with standardized pictograms, concentrating demand for polyester and polyimide substrates with solvent-resistant coatings.
- Thermal transfer durability advantages:Machinery OEMs specify thermal transfer-receptive layers for equipment identification labels exposed to abrasion and temperature cycling, justifying premium substrate investments over direct thermal alternatives.
Market Restraints
- Petrochemical input volatility:Polyester and vinyl film substrates depend on purified terephthalate and vinyl chloride monomer feedstocks, exposing converters to margin compression when energy prices spike.
- Adhesive supply concentration:Pressure-sensitive adhesive formulation expertise concentrates among a limited set of European and North American chemical suppliers, creating qualification bottlenecks for new market entrants.
- Legacy thermal transfer equipment lock-in:Warehousing operators with installed ribbon-based printing infrastructure face capital barriers when evaluating digital alternatives with lower per-label variable costs.
Strategic Opportunities
- India pharmaceutical serialization mandates:CDSCO track-and-trace regulations for exported medicines create demand for tamper-evident labels with variable data capabilities, opening a white space for substrate suppliers with regional production.
- Recyclable label construction:EU Green Deal circular economy requirements pressure brand owners to specify mono-material PET constructions compatible with container recycling streams, rewarding converters with wash-off adhesive portfolios.
- RFID-thermal transfer convergence:Food processing and pharmaceutical packaging lines seek combined visual and electronic identification, enabling premium pricing for inlays integrated with durable printable faces.
Industry Challenges
- Substrate-digital press compatibility gaps:UV inkjet and toner-based production systems require surface energy modifications unproven across temperature and humidity extremes, forcing extended qualification cycles with end-users.
- Multi-jurisdiction certification complexity:Labels serving cross-border chemical shipments must simultaneously satisfy OSHA HazCom, REACH, and transport regulations (ADR, IMDG), extending design-to-shipment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Labels Market |
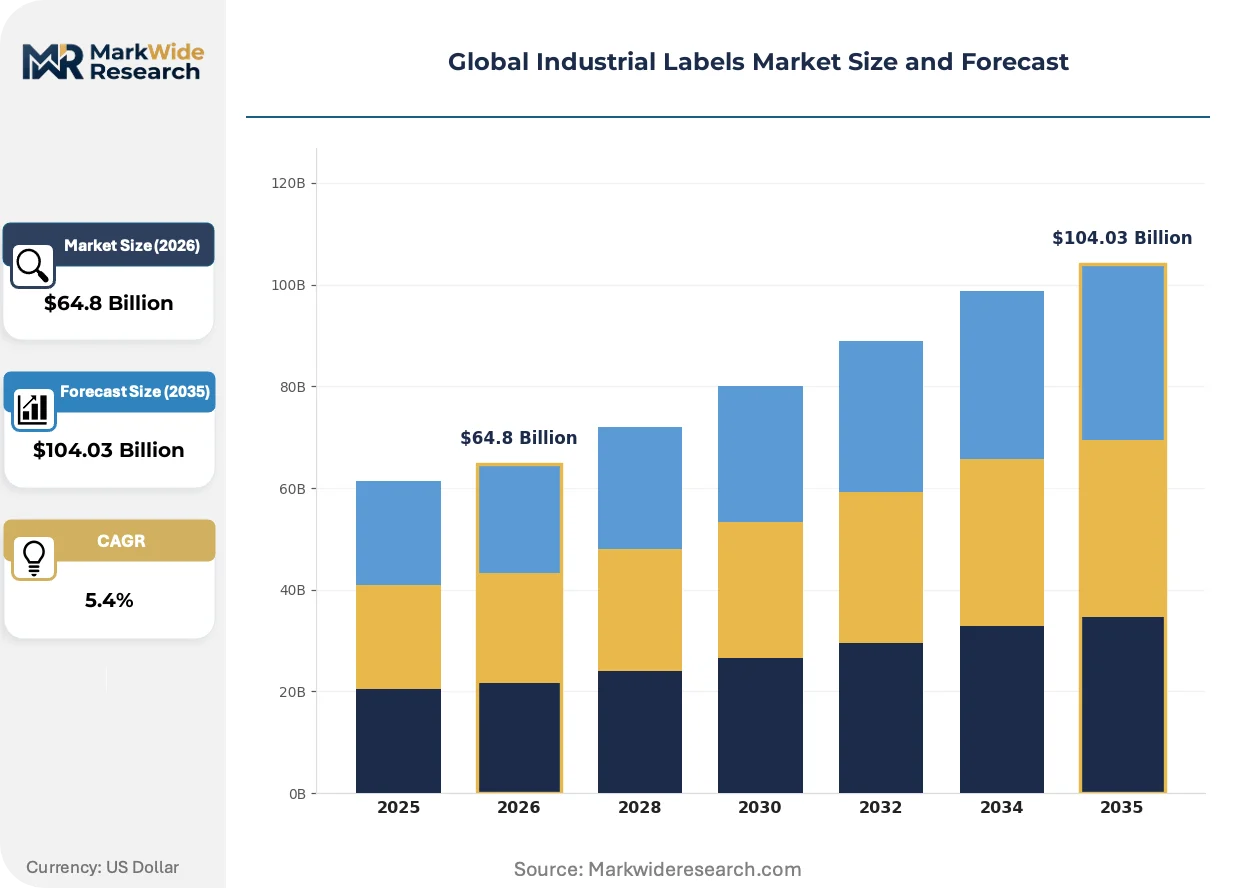
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $104.03 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive, Shrink Sleeves, In-Mold, Wrap-Around, Tag & Label, Heat Transfer Technology: Thermal Transfer, Flexographic, Digital Printing, Inkjet, Laser, Rotary Screen Application: Electrical Equipment, Food Processing Plants, Chemical Production, Heavy Machinery, Packaging Lines, Pharmaceuticals Manufacturing End User: Manufacturing Facilities, Warehousing Operators, Equipment Suppliers, Distribution Centers, Quality Control Units, Packaging Companies |
| Companies Covered | Avery Dennison Corporation, 3M Company, CCL Industries Inc., Zebra Technologies Corporation, Brady Corporation, UPM-Kymmene Corporation, Multi-Color Corporation, HID Global, Herma GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Labels Market Shifts & Advancements
Label production workflows are compressing setup and changeover intervals as digital presses capture shorter-run orders previously uneconomical for thermal transfer. Three material and process developments are restructuring competitive positioning.
Water-based adhesive formulations are collapsing solvent-dependent coating lines as converters face MEE enforcement of volatile organic compound limits in China's manufacturing clusters. Food processing exporters to EU markets specify these constructions to preempt EFSA migration concerns. The transition eliminates thermal drying stages, reducing energy intensity but requiring reformulated release liners.
EU CSRD sustainability disclosure rules now extend to packaging supply chains, compelling industrial label purchasers to document substrate carbon intensity and recyclability pathways. Machinery OEMs in Germany's Ruhr region are embedding these requirements into supplier scorecards. Polyester film producers respond with mass-balance certified feedstocks and third-party lifecycle assessments.
Direct-to-manufacturer digital platforms are disintermediating regional distributors for standard substrate grades, compressing price discovery cycles from weeks to hours. Chemical production facilities with predictable consumption patterns leverage these channels for blanket orders with call-off flexibility. The shift concentrates in North American and Western European markets with mature e-procurement infrastructure.
Global Industrial Labels Market Segmentation
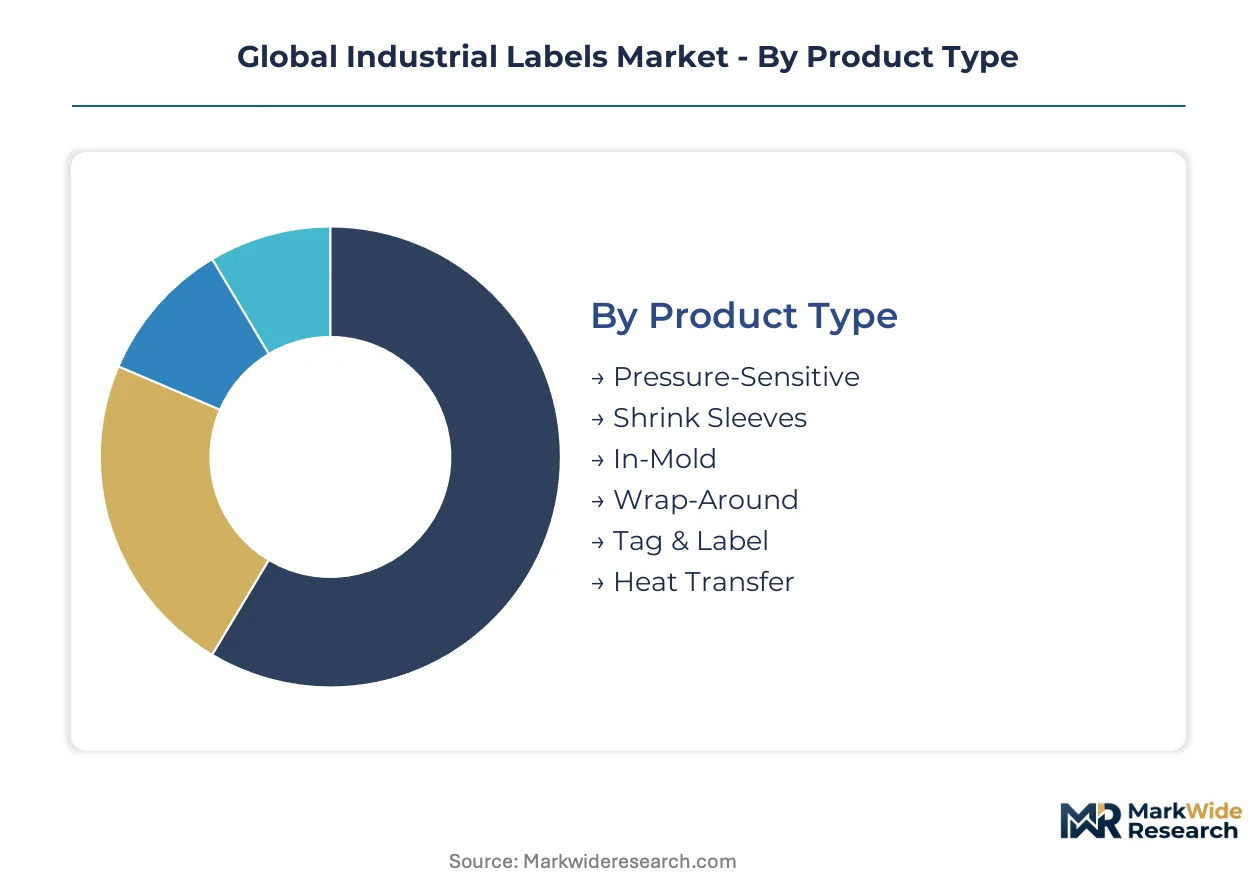
Segmentation in industrial labels reveals how procurement cycles, compliance burdens, and durability requirements fragment demand across substrate technologies and end-use environments. Understanding these divisions exposes where converters can capture premium pricing versus where volume concentrates in commoditized grades.
Product Type:
Cycle times vary dramatically across product categories, with disposable tag-and-label formats turning over in weeks while permanent in-mold constructions lock in specifications for years.
- Pressure-Sensitive:Acrylic or rubber-based adhesives coated onto polyester, vinyl, or polyimide facestocks enable rapid application without heat activation. Germany's machinery OEMs specify solvent-resistant pressure-sensitive constructions for equipment identification labels exposed to hydraulic fluids and temperature cycling.
- Shrink Sleeves:Polyolefin or PETG films that conform to container contours through heat application, delivering 360-degree graphics coverage. Food processing exporters to EU markets specify these for tamper-evident seals and multilingual ingredient panels, driven by EFSA migration testing requirements and CSRD packaging disclosure mandates.
- In-Mold:Polypropylene labels fused directly into injection-molded containers during forming, creating permanent decoration.
- Wrap-Around:Paper or film labels glued around cylindrical containers, common in chemical drum identification.
- Tag & Label:Cardstock or synthetic tags for temporary identification, warehousing, and shipping.
- Heat Transfer:Wax-resin or resin ribbons that bond to synthetic substrates through thermal printhead pressure.
Pressure-sensitive substrates anchor the volume base while shrink sleeves gain share at the steepest rate.
Technology:
Cost tiers separate legacy analog processes from digital alternatives, with capital intensity and per-unit economics determining which technology serves which order profile.
- Thermal Transfer:Ribbon-based imaging that deposits wax-resin or pure resin inks onto receptive substrates, delivering abrasion and solvent resistance. Chemical production facilities in Germany's Ruhr corridor specify thermal transfer for GHS-compliant hazard labels requiring multi-language pictogram durability.
- Digital Printing:UV inkjet or toner-based systems enabling variable data and shorter runs without plate costs. Warehousing operators in North American markets adopt these for lot-specific inventory labels, driven by demand for reduced setup waste and same-day turnaround.
- Flexographic:Rotary relief printing with photopolymer plates for high-volume, consistent graphics.
- Inkjet:Piezoelectric or thermal drop-on-demand systems for marking and coding applications.
- Laser:Ablation or engraving systems for permanent marking on metalized or specialty substrates.
- Rotary Screen:Stencil-based printing for thick ink deposits and tactile effects.
Thermal transfer dominates durable applications while digital printing climbs fastest in variable-data warehousing and quality control environments.
Application:
Application segments map directly to regulatory exposure, with chemical and pharmaceutical manufacturing carrying the heaviest compliance burdens and thus the most stringent substrate specifications.
- Chemical Production:Labels must survive solvent exposure, outdoor UV, and temperature extremes while displaying standardized GHS pictograms. REACH and OSHA HazCom mandates in Germany and the United States drive specification of polyester and polyimide substrates with permanent pressure-sensitive adhesives.
- Pharmaceuticals Manufacturing:FDA Unique Device Identification and CDSCO track-and-trace requirements for exported medicines demand tamper-evident constructions with serialization capabilities. Indian pharmaceutical exporters specify these for compliance with both domestic and destination-market regulations.
- Electrical Equipment:Arc-flash and voltage warning labels requiring flame-retardant substrates.
- Food Processing Plants:Wash-down resistant labels with indirect food contact approvals.
- Heavy Machinery:Equipment identification and safety marking for OEM and aftermarket service.
- Packaging Lines:Primary and secondary container decoration with barcode and RFID integration.
Chemical production anchors the volume base while pharmaceuticals manufacturing expands most quickly on regulatory serialization mandates.
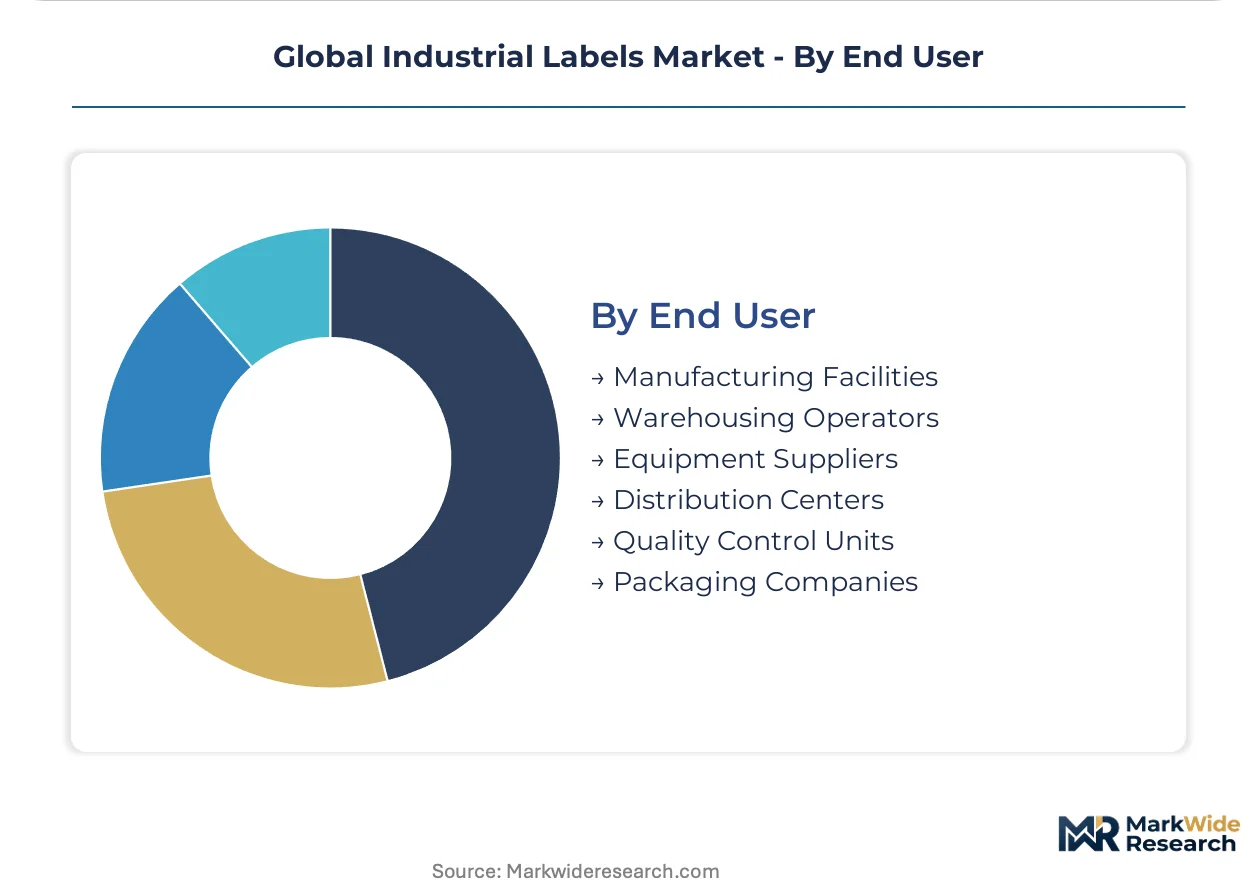
End User:
Customer type determines procurement behavior, with manufacturing facilities locking in annual contracts while warehousing operators purchase opportunistically through digital channels.
- Manufacturing Facilities:Chemical plants, pharmaceutical producers, and machinery OEMs with predictable label consumption patterns. These buyers in Germany's industrial corridor negotiate blanket orders with call-off flexibility, specifying multi-language durable substrates for export compliance.
- Warehousing Operators:Third-party logistics providers and distribution centers with variable, short-run requirements. North American operators leverage direct-to-manufacturer digital platforms for rapid replenishment of shipping and inventory labels.
- Equipment Suppliers:OEMs integrating identification labels into capital goods before shipment.
- Distribution Centers:Cross-dock facilities requiring temporary identification and routing labels.
- Quality Control Units:Inspection and testing departments with specialized marking needs.
- Packaging Companies:Converters and co-packers serving brand owners with diverse decoration requirements.
Manufacturing facilities anchor the volume base while warehousing operators gain share at the steepest rate through digital procurement adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters extract premium pricing for REACH-compliant substrates while Indian suppliers compete on pharmaceutical serialization volume. This asymmetry shapes procurement patterns across chemical manufacturing corridors and export-oriented pharmaceutical clusters.
United States
OSHA HazCom mandates drive durable label specifications for chemical drum exports. EPA FIFRA rules tighten pesticide container marking requirements. Houston's petrochemical corridor consumes polyester and vinyl substrates for hazard communication labels serving Gulf Coast refineries.
Germany
Machinery OEMs in the Ruhr region specify thermal transfer-receptive layers for equipment identification. ECHA substrate toxicity reporting forces adhesive reformulation qualification. BASF's Ludwigshafen complex anchors demand for multi-language GHS-compliant labels serving EU chemical exporters.
China
MEE enforcement of volatile organic compound limits accelerates water-based adhesive adoption. NMPA pharmaceutical serialization rules expand tamper-evident label demand. Yangtze River Delta converters supply food processing exporters with EFSA-compliant constructions.
India
CDSCO track-and-trace mandates for exported medicines create variable-data label demand. DGFT pharmaceutical export incentives concentrate production in Gujarat and Maharashtra. Mumbai-Pune pharmaceutical clusters specify serialization-capable substrates for US and EU destination markets.
Japan
METI industrial safety standards mandate durable equipment marking for machinery exports. PMDA pharmaceutical labeling rules align with FDA UDI requirements. Chubu region automotive suppliers specify polyimide substrates for under-hood component identification.
Global Industrial Labels Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and adhesive supply. The market structures around three tiers: diversified materials conglomerates with coating capabilities, focused label converters with regional scale, and digital printing equipment suppliers extending into consumables. Consolidation pressure runs through adhesive formulation expertise concentration, while qualification bottlenecks protect incumbent positions. Strategic moves center on backward integration into film extrusion and forward integration into digital procurement platforms.
Within the materials science tier, Avery Dennison Corporation and 3M Company represent integrated substrate-adhesive platforms with coating and converting capabilities spanning multiple durability specifications. Brady Corporation exemplifies the safety identification specialist archetype, occupying a position focused on electrical and chemical environment applications. These three anchors demonstrate how competitive positioning splits between broad materials portfolios and targeted compliance-driven segments.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| 3M Company |
| CCL Industries Inc. |
| Zebra Technologies Corporation |
| Brady Corporation |
| UPM-Kymmene Corporation |
| Multi-Color Corporation |
| HID Global |
| Herma GmbH |
| Others |
Supply & Pricing Matrix
Adhesive formulation expertise concentrates among European and North American chemical suppliers, concentrating margin pools with substrate converters who qualify compliant constructions for REACH and OSHA mandates. This upstream concentration cascades downstream, where German machinery OEMs and chemical exporters absorb premium pricing for multi-language durable labeling while warehousing operators in North America squeeze margins through digital procurement channels.
Pricing Analysis
The customization-premium spread separates configured-to-order thermal transfer substrates from standard pressure-sensitive grades. Contract-based long-term offtake dominates manufacturing facility procurement, with price differentiation driven by certification level (REACH-compliant adhesive portfolios command substantial premia) and volume scale. Cost compression in standard grades is intensifying because digital platforms collapse distributor markups. Warehousing operators exhibit highest price sensitivity, while pharmaceutical manufacturers show lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for polyester film and adhesive resin flows. Manufacturing concentrates in Germany, China, and the United States, with raw material dependencies on purified terephthalate, vinyl chloride monomer, and acrylic adhesive polymers. Single-source vulnerability persists in pressure-sensitive adhesive formulation expertise. Distribution runs through direct-to-manufacturer digital platforms for standard grades and specialized converter networks for compliant constructions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital printing technology is reshaping competitive positioning in industrial labels, with variable-data capabilities and reduced setup waste capturing warehousing and quality control demand previously served by thermal transfer. This technological inflection, combined with tightening REACH and OSHA substrate disclosure mandates, creates a high-growth disruption window for positioned players.
For Market Incumbents: Harden adhesive formulation capabilities through backward integration into resin synthesis or exclusive supply partnerships with European chemical suppliers. Deepen certification moats by pre-qualifying constructions for simultaneous OSHA HazCom, REACH, and transport regulation compliance, insulating against emerging Asian converters with narrower regulatory scope. For New Entrants and Emerging Players: Pursue pharmaceutical serialization demand in India, where CDSCO track-and-trace mandates for exported medicines outpace domestic converter capacity. Target Gujarat and Maharashtra clusters with variable-data digital printing capabilities and regional production footprints, leveraging DGFT export incentives as customer acquisition anchor. For Investors and Strategic Acquirers: Capital is best deployed toward substrate converters with wash-off adhesive portfolios positioned for EU Green Deal circular economy requirements. Long-term viability centers on mono-material PET construction expertise and mass-balance certification capabilities. The signal to watch is ECHA substrate toxicity reporting threshold tightening, which will force adhesive reformulation and consolidate procurement with qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Resin Synthesis | Captures margin pools concentrated with European chemical suppliers serving REACH-compliant demand. |
| Digital Procurement Platform Launch | Disintermediates regional distributors for North American warehousing operators seeking rapid replenishment. |
| Wash-Off Adhesive Portfolio Expansion | Aligns with EU Green Deal circular economy requirements for recyclable mono-material PET constructions. |
| RFID-Thermal Transfer Convergence Development | Enables premium pricing for food processing and pharmaceutical packaging lines seeking combined visual and electronic identification. |
| Regional Production Footprint in India | Positions for CDSCO pharmaceutical serialization mandates with localized variable-data capabilities and reduced logistics exposure. |
Research Methodology
The analysis maps pressure-sensitive substrates, shrink sleeve constructions, in-mold labels, and thermal transfer technologies, each validated through procurement directors at chemical production facilities, plant engineers at machinery OEMs, regulatory affairs leads at adhesive suppliers, and distribution channel partners. Primary interviews combined with secondary validation from customs/trade data, ECHA substance registration databases, SEC 10-K filings, and OSHA enforcement records. Bottom-up and top-down triangulation cross-checked converter capacity estimates against end-use demand aggregation.
Assumptions held fixed include regulatory enforcement intensity for REACH and OSHA mandates, while petrochemical feedstock cost trajectories and digital printing adoption curves were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, printing technology, application environment, and end-user procurement behavior. CAGRs derived from historical volume progression analyzed against capacity expansion announcements and regulatory mandate implementation timelines. Industry-specific inputs included GHS pictogram standardization deadlines and pharmaceutical serialization phase-in schedules.
Sensitivities concentrate around ECHA substrate toxicity reporting threshold revisions and MEE enforcement intensity for volatile organic compound limits in China. Forecasts reflect these documented assumptions with acknowledged uncertainty from petrochemical input volatility and adhesive supply concentration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Freshness Indicator Label Market
Labels
Coated Wet Glue Label Market
Labels
Ethical Label Market
Labels
Non-Adhesive Tags Market
Labels
Healthcare and Laboratory Labels Market
Labels
Wet Glue Labels Market
Labels
Booklet Labels Market
Labels
In-Mold Labeling (IML) Market
Labels
Shrink Sleeve Label Applicator Market
Labels
Europe Self Adhesives Label Market
Labels
Self-Laminating Tags Market
Labels
Freezer Label Market
Labels
Pressure Sensitive Labels Market
Labels
APAC on-Demand Color Labels Market
Labels
Global Print and Apply Labeling and Labeling Equipment Market
Labels
Holographic Labels Market