
 In-Mold Labeling (IML) Market | 2026-2036
In-Mold Labeling (IML) Market Size, Share, and Industry Trends Forecast 2026-2036
In-Mold Labeling (IML) Market Foresight
Germany is fragmenting as injection molding capacity expands across Bavaria and Baden-Württemberg to serve pharmaceutical and personal care contract manufacturers. Multi-Color Corporation leverages its European decorating platform to anchor premium food packaging accounts. CCL Industries sustains R&D intensity in thin-film polypropylene substrates for high-speed blow molding lines. Huhtamaki Group competes through geographic dominance in emerging European dairy and ready-meal segments.
In-mold labeling fuses pre-printed polypropylene, polyethylene, or polystyrene films directly into thermoplastic containers during injection, blow, or thermoforming processes, achieving scratch-resistant decoration without post-mold adhesives. The technology eliminates secondary labeling stations, reduces material waste, and supports thin-wall packaging down to sub-millimeter film gauges for lightweight sustainability targets. Polypropylene dominates current substrate volumes due to compatibility with olefinic resins and superior heat resistance during high-cycle injection molding, while polyethylene is gaining fastest in dairy and household product blow-molded containers where flexibility and cost efficiency matter. Thermoforming technology occupies narrower but higher-margin niches in pharmaceutical blister packs and electronics trays where dimensional precision and cleanroom compatibility command premium positioning.
EMA medical device labeling requirements and EU Green Deal circular-economy mandates are forcing substrate suppliers to validate recyclability pathways and reduce fluorinated additives in IML films. REACH compliance and upcoming CSRD disclosure rules will extend traceability obligations through the decorating supply chain, favoring converters with certified material documentation systems. Stakeholders must monitor how ECHA substance restrictions evolve for pigments and adhesives, as this will determine which film suppliers retain formulation flexibility versus facing forced reformulation costs.
Market Dynamics
EU Green Deal circular-economy mandates and F-Gas Regulation compliance deadlines are compressing substrate formulation cycles and forcing simultaneous investment in recyclability validation and fluorinated additive elimination across European converter networks.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving pigment and adhesive limitations favor converters with certified material documentation systems, creating competitive separation between compliant and non-compliant suppliers.
- Food packaging premiumization:Branded consumer goods lines are accelerating IML adoption for shelf differentiation and scratch-resistant decoration that survives supply chain handling.
- Pharmaceutical contract manufacturing:Precision injection molding clusters in southern Germany are expanding capacity to serve EMA medical device labeling requirements with cleanroom-compatible thermoformed solutions.
Market Restraints
- Polypropylene resin volatility:Olefin feedstock price swings directly compress converter margins and complicate long-term contract pricing with food packaging accounts.
- Thin-film substrate concentration:Technical mastery of sub-millimeter polypropylene gauges remains concentrated among a limited set of European and East Asian specialty film suppliers.
- CSRD disclosure timelines:Upcoming traceability obligations extend compliance costs through the decorating supply chain before revenue benefits materialize.
Strategic Opportunities
- Dairy and ready-meal segments:Blow-molded polyethylene containers present underpenetrated volume potential where flexibility and cost efficiency outweigh heat resistance requirements.
- Electronics tray thermoforming:Pharmaceutical blister pack expertise transfers to high-margin electronics cleanroom applications demanding dimensional precision.
- EU Green Deal recyclability mandates:Validated closed-loop pathways for polypropylene substrates create first-mover positioning in sustainability-driven procurement criteria.
Industry Challenges
- Multi-material separation expertise:Converters lack sufficient technical personnel trained in compatible adhesive chemistry for recyclable film-container bonds.
- High-speed line integration:Legacy blow molding equipment requires substantial retrofit investment to achieve consistent IML placement accuracy at dairy industry volume scales.
- Dual certification timelines:Simultaneous EMA medical device and EU food contact compliance extends product validation cycles before commercial launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Mold Labeling (IML) Market |
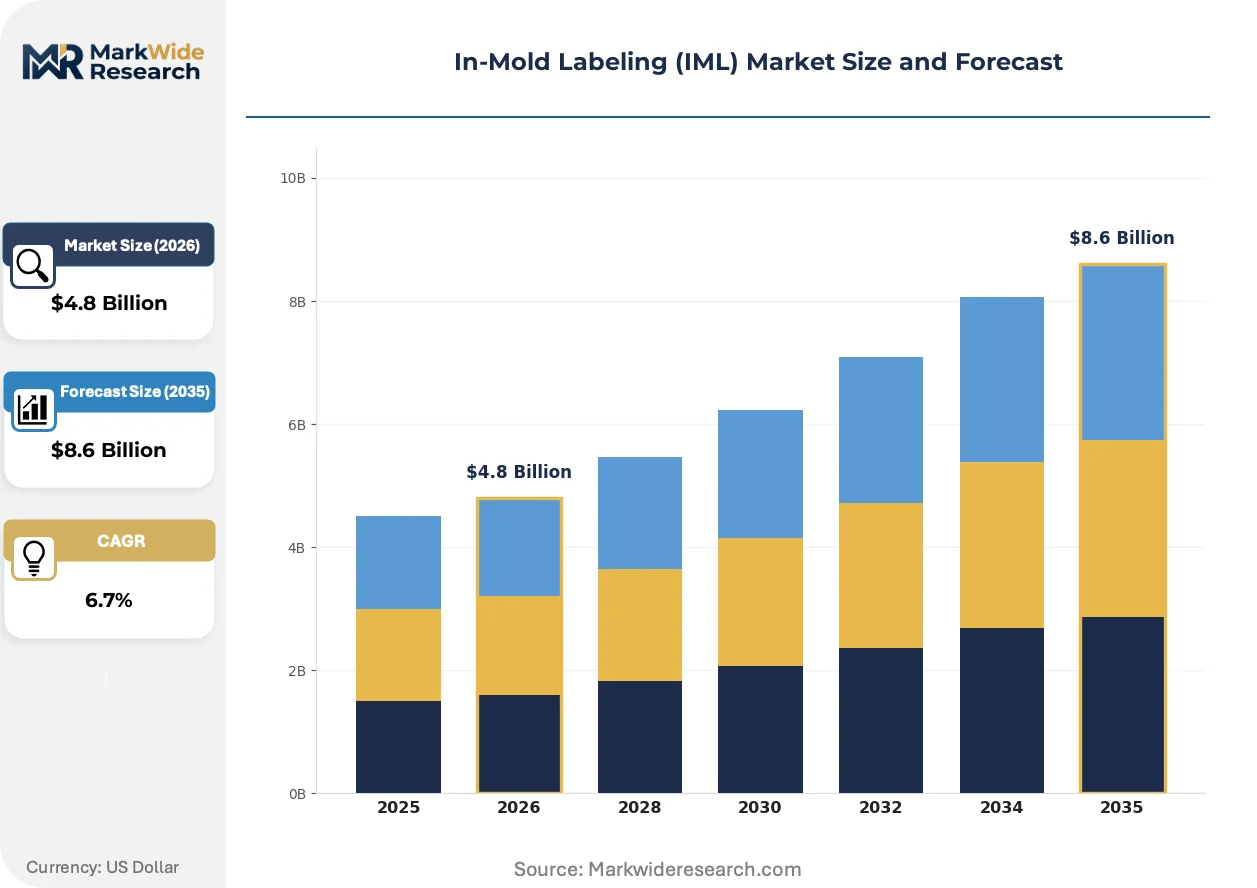
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, Polystyrene, PET Technology: Injection Molding, Blow Molding, Thermoforming, Extrusion Application: Food Packaging, Household Products, Personal Care, Pharmaceuticals End User: Consumer Goods, Automotive, Electronics, Healthcare |
| Companies Covered | Multi-Color Corporation, CCL Industries, Huhtamaki Group, Coveris Holdings, Constantia Flexibles, Fuji Seal International, Avery Dennison Corporation, Taghleef Industries, Inland Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Mold Labeling (IML) Market Shifts & Advancements
Digital printing integration and laser-etched registration systems are compressing changeover times and enabling economical short-run production that was previously uneconomical for IML economics.
Laser-etched micro-registration patterns on polypropylene films now enable sub-millimeter placement accuracy without mechanical guides. Pharmaceutical contract packagers in Germany and Switzerland are adopting these systems for small-batch personalized medicine packaging. Conventional mechanical registration pins are rendering obsolete in applications demanding frequent artwork changes and lot-level traceability.
EU F-Gas Regulation phase-down schedules are accelerating fluorinated additive elimination from IML substrate formulations. Film suppliers must validate alternative slip and release agents that maintain high-cycle injection molding performance. Personal care and cosmetics segments face the tightest compliance deadlines and are driving joint development programs with specialty chemical partners.
Brand procurement teams now specify recyclability certification as a gate criterion for label converter selection, displacing price-only sourcing models. Major European dairy and ready-meal producers have embedded these requirements into three-year supply agreements. This specification shift concentrates volume with converters possessing in-house material validation laboratories and documented closed-loop partnerships with resin reclaimers.
In-Mold Labeling (IML) Market Segmentation
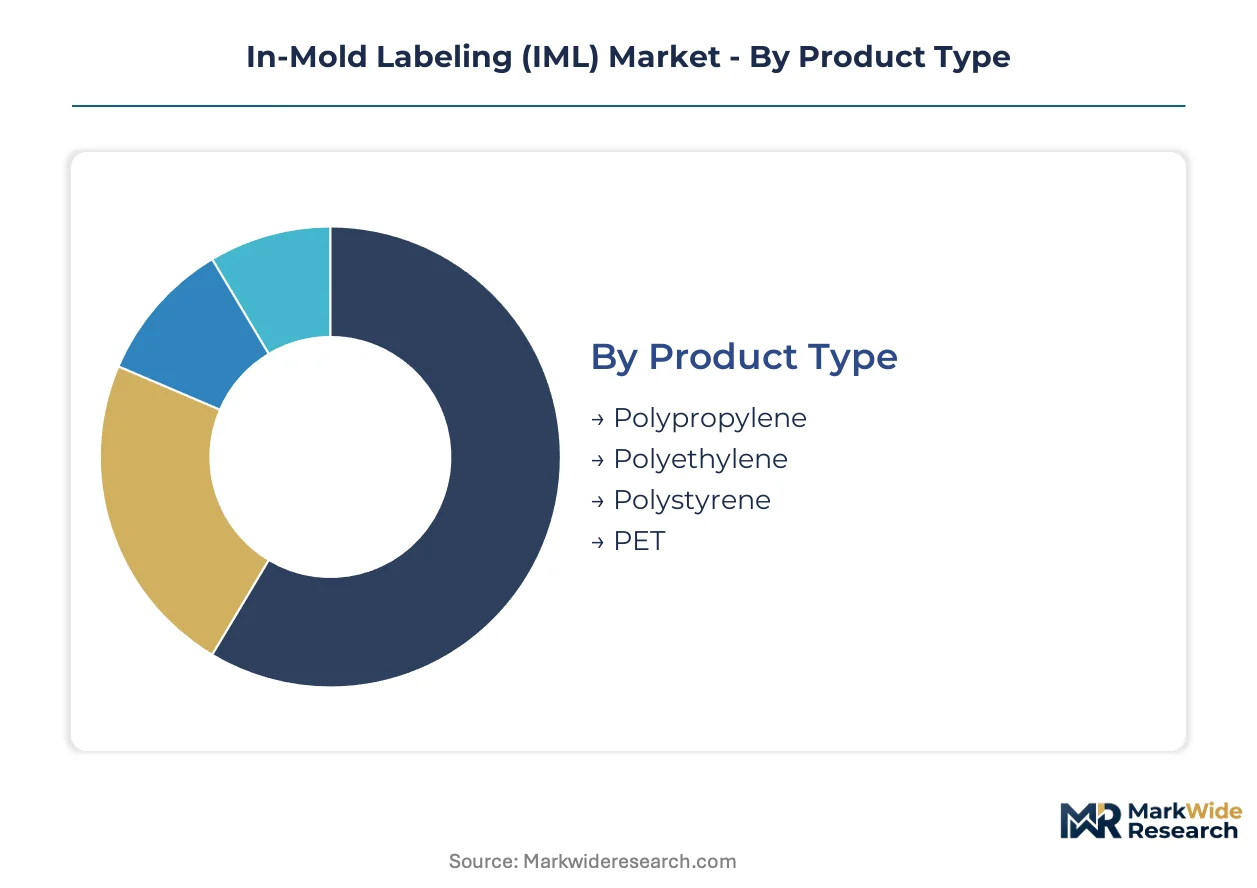
IML substrate selection and molding technology choices cascade through compliance obligations, equipment investment cycles, and end-use performance requirements. Segmentation clarity exposes where margin pools concentrate versus where volume commoditizes.
Product Type:
Polypropylene commands the shortest quoting cycles due to olefin resin standardization, while PET substrates face extended validation timelines from food-contact migration testing requirements.
- Polypropylene:Dominates current substrate volumes through compatibility with olefinic resins and superior heat resistance during high-cycle injection molding. Demand concentrates in Bavaria and Baden-Württemberg precision injection molding clusters serving EMA medical device labeling requirements.
- Polyethylene:Gaining fastest in dairy and household product blow-molded containers where flexibility and cost efficiency outweigh heat resistance requirements. REACH substance restrictions on pigments favor converters with certified material documentation systems for this substrate.
- Polystyrene:Occupies narrow niches in electronics tray thermoforming where dimensional precision and cleanroom compatibility command premium positioning.
- PET:Requires extended EU food contact compliance validation cycles, limiting adoption to premium personal care and pharmaceutical contract packaging with patient-safety critical labeling.
Polypropylene dominates installed base. Polyethylene is where expansion concentrates.
Technology:
Cost tier separation runs widest here: thermoforming equipment amortizes across small batches at premium pricing, while extrusion lines compete on throughput scale at compressed margins.
- Injection Molding:Fuses pre-printed films directly into thermoplastic containers during high-cycle production, eliminating secondary labeling stations. Southern Germany precision clusters expand capacity to serve pharmaceutical contract manufacturing with EMA-compliant cleanroom solutions.
- Blow Molding:Legacy equipment requires substantial retrofit investment to achieve consistent IML placement accuracy at dairy industry volume scales. EU Green Deal recyclability mandates are accelerating fluorinated additive elimination from substrate formulations used in this process.
- Thermoforming:High-margin niches in pharmaceutical blister packs and electronics trays where dimensional precision and cleanroom compatibility command premium positioning.
- Extrusion:Volume-scale production of thin-wall packaging down to sub-millimeter film gauges for lightweight sustainability targets.
Injection molding captures the steepest expansion trajectory. Thermoforming defends margin concentration.
Application:
Customer type stratification drives specification intensity: pharmaceutical buyers demand lot-level traceability, while household product procurement teams prioritize landed cost per thousand units.
- Food Packaging:Branded consumer goods lines accelerate adoption for shelf differentiation and scratch-resistant decoration that survives supply chain handling. CSRD disclosure timelines extend compliance costs through decorating supply chains before revenue benefits materialize.
- Pharmaceuticals:Dual certification timelines for simultaneous EMA medical device and EU food contact compliance extend product validation cycles. Laser-etched micro-registration patterns enable sub-millimeter placement accuracy for small-batch personalized medicine packaging in Germany and Switzerland.
- Personal Care:EU F-Gas Regulation phase-down schedules drive joint development programs with specialty chemical partners for fluorinated additive elimination.
- Household Products:Blow-molded polyethylene containers present underpenetrated volume potential where flexibility and cost efficiency outweigh heat resistance requirements.
Food packaging anchors volume procurement. Pharmaceuticals concentrate margin extraction.
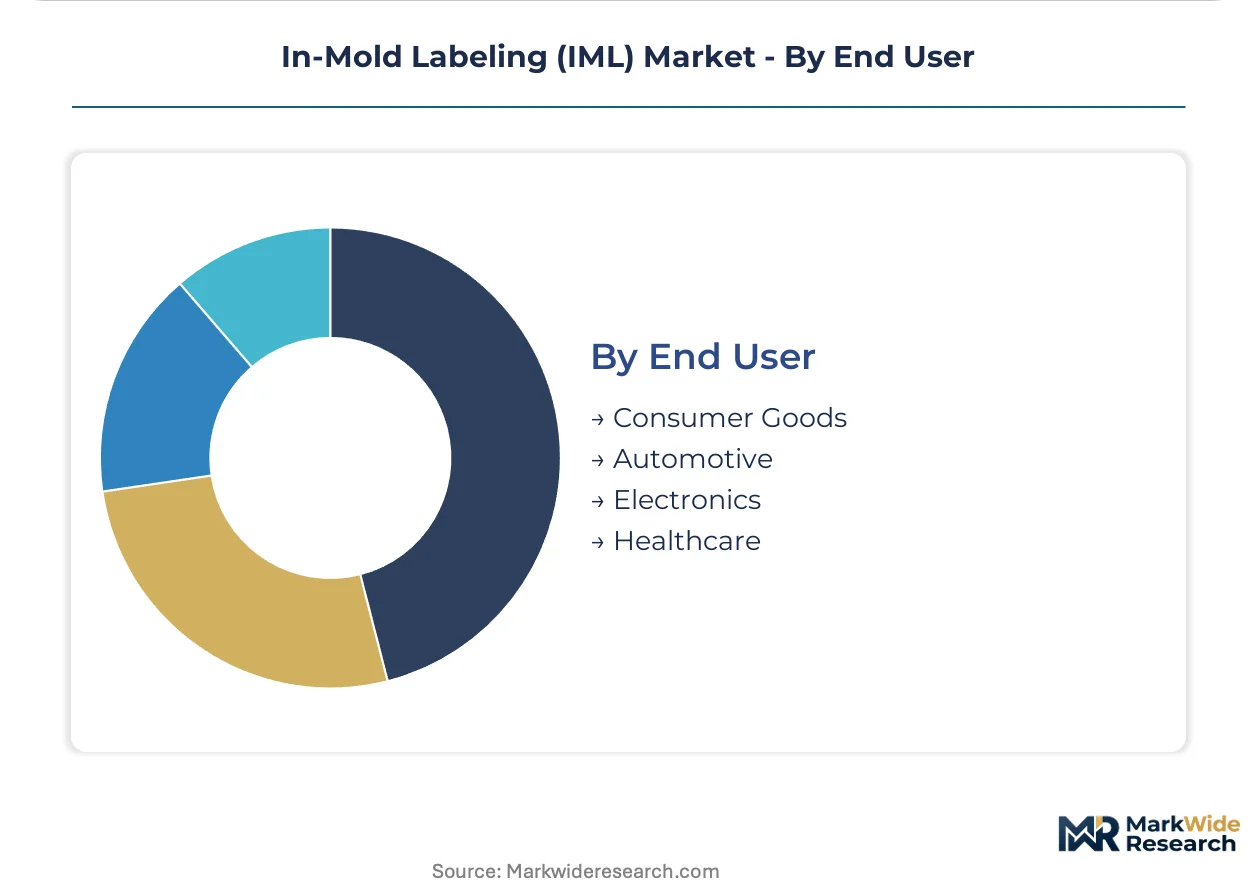
End User:
Maturity dispersion shapes competitive entry: automotive specifications are codified through tier-one supplier manuals, while electronics buyers negotiate custom validation protocols per program.
- Consumer Goods:Brand procurement teams specify recyclability certification as a gate criterion for label converter selection, displacing price-only sourcing models. Major European dairy and ready-meal producers embed these requirements into multi-year supply agreements.
- Healthcare:EMA medical device labeling requirements and EU Green Deal circular-economy mandates force substrate suppliers to validate recyclability pathways and reduce fluorinated additives in IML films.
- Electronics:Pharmaceutical blister pack expertise transfers to high-margin electronics cleanroom applications demanding dimensional precision.
- Automotive:Scratch-resistant decoration requirements align with IML's fused-film durability advantages, though cycle time requirements differ from packaging applications.
Consumer goods concentrate procurement volume. Healthcare commands specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters most densely in southern Germany, where precision injection molding serves pharmaceutical contract packaging. Bavaria and Baden-Württemberg host the steepest expansion trajectories for EMA-compliant cleanroom solutions.
Germany
Bavaria and Baden-Württemberg precision molding clusters anchor European pharmaceutical and personal care contract packaging. EMA medical device labeling requirements and EU Green Deal circular-economy mandates force substrate suppliers to validate recyclability pathways. Stuttgart and Munich metropolitan areas concentrate laser-etched micro-registration system adoption for small-batch personalized medicine packaging.
Switzerland
Swissmedic-regulated pharmaceutical packaging demands sub-millimeter placement accuracy for patient-safety critical labeling. EU F-Gas Regulation phase-down schedules accelerate fluorinated additive elimination from IML substrate formulations. Basel and Zurich pharmaceutical hubs drive joint development programs with specialty chemical partners for cleanroom-compatible thermoformed solutions.
United States
FDA food-contact compliance requirements and dairy industry volume scales attract blow-molded polyethylene container investment. EPA regulatory frameworks influence fluorinated additive substitution timelines for household product segments. Midwest injection molding corridors and Southeast dairy processing clusters expand IML retrofit capacity for branded consumer goods lines.
China
SAMR food-contact standards and dual carbon goals reshape substrate selection criteria for export-oriented packaging. GB standards compliance extends validation cycles for polypropylene and polyethylene film formulations. Yangtze River Delta and Pearl River Delta manufacturing belts concentrate thin-film substrate production for lightweight sustainability targets.
Japan
METI industrial policy supports high-speed line integration for electronics tray thermoforming applications. PMDA pharmaceutical regulations align with EMA requirements for medical device labeling traceability. Kanto and Kansai industrial corridors host precision thermoforming capacity for dimensional precision in cleanroom-compatible electronics packaging.
In-Mold Labeling (IML) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and equipment supply. The vendor base separates between consolidated decorating platforms with European reach and fragmented regional converters serving single-country food packaging accounts. Three archetypes dominate: film substrate specialists with certified material documentation systems, precision injection molding integrators with cleanroom capabilities, and geographic-focused dairy packaging converters. Competitive moves concentrate on M&A for decorating platform expansion and joint development programs for fluorinated additive substitution.
Within the platform integrator tier, Multi-Color Corporation and CCL Industries exemplify European decorating platform scale. Huhtamaki Group occupies a position in emerging segment geographic dominance. Fuji Seal International and Taghleef Industries represent substrate specialist archetypes with thin-film technical mastery. Constantia Flexibles and Coveris Holdings sit within flexible packaging converter consolidation patterns. Avery Dennison Corporation anchors adhesive and label material system integration. Inland Packaging exemplifies regional North American converter positioning.
| Leading Market Players |
|---|
| Multi-Color Corporation |
| CCL Industries |
| Huhtamaki Group |
| Coveris Holdings |
| Constantia Flexibles |
| Fuji Seal International |
| Avery Dennison Corporation |
| Taghleef Industries |
| Inland Packaging |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese thin-film substrate production is compressing European converter margins while simultaneously accelerating procurement shifts toward certified material documentation systems. Bavarian precision molding clusters exploit this dislocation to renegotiate long-term supply agreements with polypropylene film suppliers.
Pricing Analysis
EU Green Deal circular-economy mandates dictate the pricing tier structure across IML substrate procurement. Three-tier pricing structure across premium, standard, and economy levels separates EMA-compliant pharmaceutical-grade films from food-contact certified substrates and uncertified commodity grades. Price differentiation hinges on REACH documentation depth and fluorinated additive elimination status. Pricing pressure stems from olefin resin volatility eroding converter margins. Dairy procurement teams exhibit highest price sensitivity; pharmaceutical contract manufacturers prioritize compliance premiums over unit cost.
Supply Chain Analysis
Precision injection molding contract manufacturers in southern Germany and Swiss pharmaceutical packaging specialists hold the densest certified capacity clusters. Raw material flows draw from Saudi and South Korean polypropylene resin producers, German specialty chemical partners for slip agents, and Italian rotogravure cylinder suppliers. Single-source vulnerability concentrates in sub-millimeter film gauge production where East Asian specialists dominate technical mastery. Distribution runs through converter-direct relationships with branded consumer goods lines and pharmaceutical contract packagers, bypassing traditional distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IML market operates as a regulatory-moat business where EMA medical device certification and EU Green Deal compliance documentation create switching costs that entrench incumbent positions against price-only challengers.
For Market Incumbents: Entrench position through backward integration into polypropylene film production in Baden-Württemberg to capture margin pool compression from resin volatility. Deepen certification moats by pre-positioning fluorinated additive-free formulations ahead of F-Gas Regulation deadlines. Acquire distressed regional converters in dairy-heavy geographies to consolidate volume procurement leverage against thin-film substrate suppliers. For New Entrants and Emerging Players: Pursue white-space expansion in blow-molded polyethylene containers for European ready-meal segments where legacy equipment retrofit barriers deter incumbent reallocation. Target North American dairy processing clusters where FDA compliance pathways remain less codified than EMA requirements. Enter through laser-etched micro-registration system partnerships that compress pharmaceutical contract packaging changeover economics. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade thermoforming capacity as cleanroom validation timelines extend. Five-to-ten year viability favors platform integrators with multi-country decorating networks over single-site regional converters. Monitor ECHA substance restriction announcements as inflection signals for forced reformulation cost waves that will separate compliant from distressed asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorinated Additive Substitution Program | Joint development with specialty chemical partners accelerates F-Gas Regulation compliance ahead of personal care deadlines. |
| Laser-Etched Registration System Deployment | Sub-millimeter placement accuracy enables small-batch personalized medicine packaging in Stuttgart and Basel hubs. |
| Closed-Loop Recyclability Validation | Documented partnerships with resin reclaimers satisfy brand procurement gate criteria for multi-year dairy supply agreements. |
| Precision Molding Capacity Expansion | Bavarian and Baden-Württemberg clusters add cleanroom-compatible lines to serve EMA medical device labeling requirements. |
| Digital Printing Integration | Short-run production economics compress changeover times for frequent artwork changes in branded consumer goods lines. |
Research Methodology
A standing panel of IML substrate R&D directors, pharmaceutical contract packaging procurement managers, food brand sustainability officers, and precision injection molding plant engineers provided ongoing calibration against secondary validation. Primary interviews combined with customs trade data, ECHA substance restriction filings, SEC 10-K disclosures from listed converters, and EU food contact compliance databases enabled bottom-up and top-down triangulation.
Scenario-bracketing anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include substrate chemistry tier, molding technology type, end-use application intensity, and regional regulatory cluster. CAGRs derived from installed equipment capacity trajectories, brand procurement specification shifts, and compliance deadline phasing. Forecast inputs incorporated fluorinated additive elimination timelines and laser-etched registration adoption curves.
Macroeconomic conditions sit as an overlay; deviation in olefin feedstock pricing, euro-dollar exchange rates, or EU regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about EMA medical device labeling requirement evolution and REACH substance restriction scope expansion. Quarterly review of ECHA regulatory announcements, pharmaceutical contract manufacturing capacity utilization reports, and brand sustainability procurement criteria updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Security Labels Market
Labels
Sleeve Label Market
Labels
Future-Proof Pharma Labels Market
Labels
Wrap Around Labels Market
Labels
Industrial Label Printers Market
Labels
Linerless Labels Market
Labels
Wet Glue Labels Market
Labels
Coated Wet Glue Label Market
Labels
Global Waterproof Labels Market
Labels
Global Laminated Labels Market
Labels
Hot Melt Glue Labeler Market
Labels
Global Resealable Packaging Labels Market
Labels
Primary Packaging Labels Market
Labels
Oxygen Indicator Labels Market
Labels
High Gloss Labels Market
Labels
Healthcare and Laboratory Labels Market