
 APAC on-Demand Color Labels Market | 2026-2036
APAC on-Demand Color Labels Market Size, Share, and Industry Trends Forecast 2026-2036
APAC on-Demand Color Labels Market Outlook
Japanese thermal transfer ribbon manufacturers are pivoting toward aqueous inkjet-compatible coatings to serve Indonesia's expanding instant-noodle export sector. Avery Dennison Corporation leverages its Shanghai coating facility to anchor regional substrate supply for pharmaceutical serialization mandates. Brady Corporation competes through specialized chemical-resistant label portfolios targeting South Korean battery assembly lines. SATO Holdings dominates RFID-integrated color label niches across ASEAN automotive parts distribution networks.
APAC on-demand color labels are pressure-sensitive or linerless substrates engineered for digital printing at resolutions exceeding 600 dpi, utilizing pigment or dye-based ink systems compatible with paper, polypropylene, or polyethylene facestocks. Their primary purpose is enabling variable-data, short-run branding and regulatory compliance marking without plate-making lead times. Thermal technology leads installed base across Japanese electronics and pharmaceutical packaging plants where barcode durability requirements are stringent. Inkjet systems represent the fastest-growing segment as Chinese e-commerce platforms demand full-color shipping labels with promotional QR codes. Digital printing technology commands premium margin pools in Australia and New Zealand where pharmaceutical lot-tracking regulations necessitate serialized color-coded identifiers.
Japan's Ministry of Economy, Trade and Industry enforces JIS standards for label adhesives in food-contact applications, while Australia's Therapeutic Goods Administration mandates color-coded tamper-evident labeling for Schedule 8 pharmaceuticals. China's State Administration for Market Regulation applies GB standards restricting heavy metals in printed packaging substrates consumed domestically. Stakeholders must monitor evolving substrate recyclability mandates across Singapore, South Korea, and Thailand as extended producer responsibility frameworks expand beyond plastics into printed packaging materials.
Market Dynamics
China's e-commerce fulfillment infrastructure is compressing print-run lengths to single-digit quantities, forcing substrate suppliers to reconfigure coating lines for rapid changeovers between polypropylene and paper facestocks.
Growth Catalysts
- Pharmaceutical serialization mandates:Australia's TGA requires color-coded tamper-evident labels for Schedule 8 controlled substances, compelling domestic contract packers to install on-demand digital presses.
- Indonesia's instant-noodle export surge:Halal certification labels with variable lot codes must switch between Arabic and English text within the same production shift, favoring aqueous inkjet over thermal transfer.
- Japan's METI adhesive standards:JIS S 2053 compliance for food-contact labels restricts solvent-based systems, accelerating water-based pigment ink adoption in Tokyo-Osaka packaging corridors.
Market Restraints
- Petrochemical substrate volatility:Polypropylene facestock prices track naphtha spreads from Singapore refining hubs, squeezing converter margins on short-run orders.
- Coating capacity concentration:Thermal transfer ribbon coating lines cluster in Japan's Kansai region, exposing ASEAN label converters to yen-denominated input cost swings.
- Heavy metal substrate restrictions:China's GB standards limit cadmium and lead in printed packaging for domestic consumption, disqualifying legacy thermal ribbon formulations.
Strategic Opportunities
- Vietnam's underpenetrated pharmaceutical sector:Foreign-owned CMOs in Ho Chi Minh City industrial parks require GMP-compliant color labels for export to EU and US markets.
- RFID-inkjet convergence:Automotive parts distributors across Thailand and Malaysia seek combined EPC Gen2 inlays with full-color variable graphics for bin-level tracking.
- South Korea's battery assembly expansion:SK On and LG Energy Solution facilities demand chemical-resistant polyester labels with QR-coded cell genealogy data.
Industry Challenges
- Color management skill scarcity:Digital press operators across Southeast Asia lack ICC profile calibration expertise for matching brand Pantone specifications on synthetic substrates.
- BIS certification timelines:India's food-contact substrate approval process extends 14-18 months, delaying converter qualification for FMCG seasonal campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC on-Demand Color Labels Market |
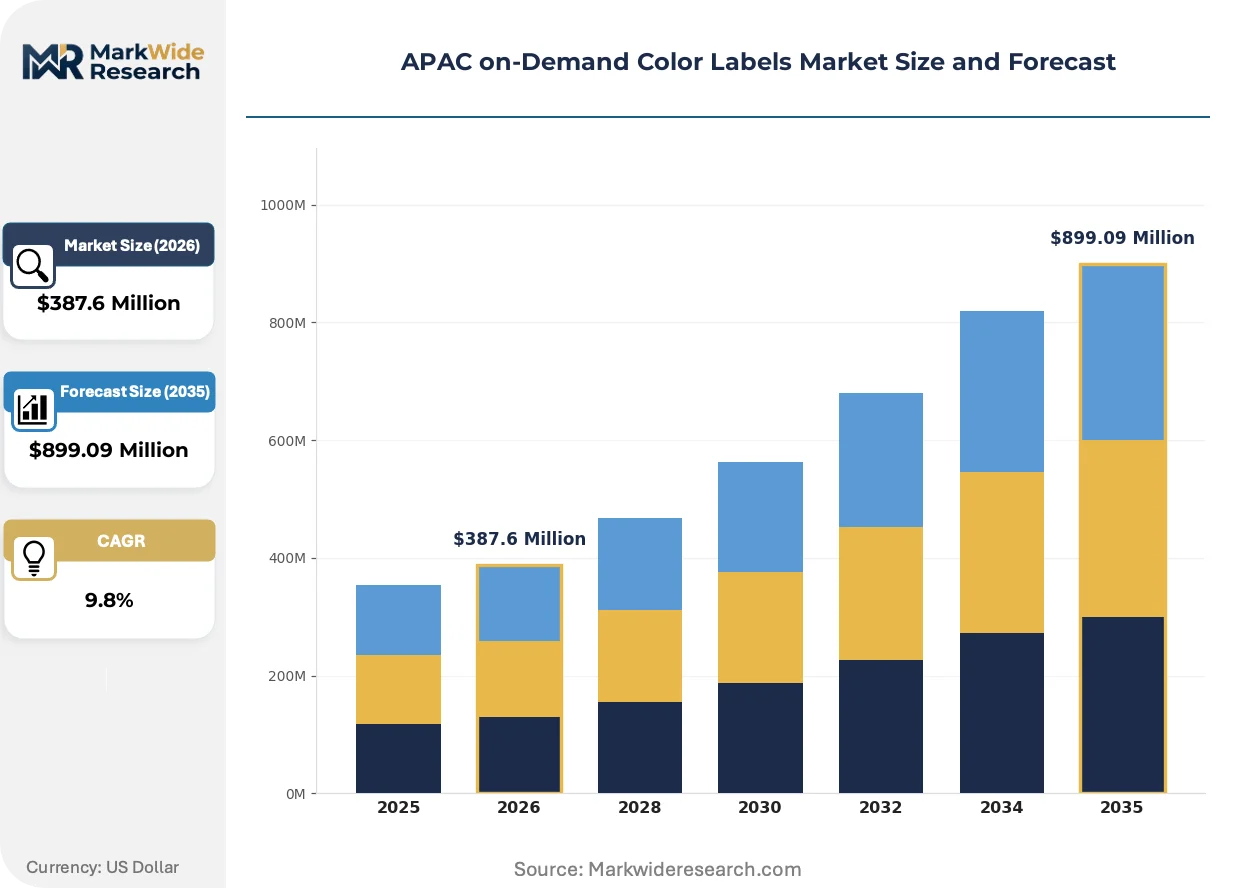
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $899.09 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet, Laser, Thermal, Direct-to-Print End User: Food & Beverage, Pharmaceuticals, Retail, Manufacturing Technology: Digital Printing, Flexography, Gravure, Lithography Application: Product Labeling, Shipping Labels, Asset Tags, Security Labels |
| Companies Covered | Avery Dennison Corporation, Brady Corporation, Lexmark International Inc., Fuji Seal International Inc., CCL Industries Inc., Zebra Technologies Corporation, HP Inc., Epson, SATO Holdings, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC on-Demand Color Labels Market Strategic Shifts
Water-based pigment ink systems are displacing solvent platforms across APAC food packaging, driven by METI and SAMR emissions restrictions. This substrate-ink convergence is compressing equipment replacement cycles.
Single-pass aqueous inkjet is decentralizing label production authority from centralized print shops to e-commerce fulfillment floors. Chinese platforms including JD Logistics and Cainiao Network deploy compact 600 dpi color label engines at warehouse pack stations. This topology eliminates pre-printed label inventory and enables real-time promotional QR code insertion.
Australia's TGA serialization rules for Schedule 8 pharmaceuticals mandate color-coded tamper-evident features with unique identifiers. Contract packers in Sydney and Melbourne retrofit digital presses with spectrophotometric verification modules. The compliance burden favors domestic converters over import-dependent competitors.
Brand owners in Japan's cosmetics sector now specify lot-specific ingredient disclosure on primary labels. Shiseido and Kao procurement teams require converters to deliver sub-48-hour turnaround on formula variant labels. This velocity specification favors digital-native suppliers over conventional flexographic houses in Osaka and Tokyo corridors.
APAC on-Demand Color Labels Market Segmentation
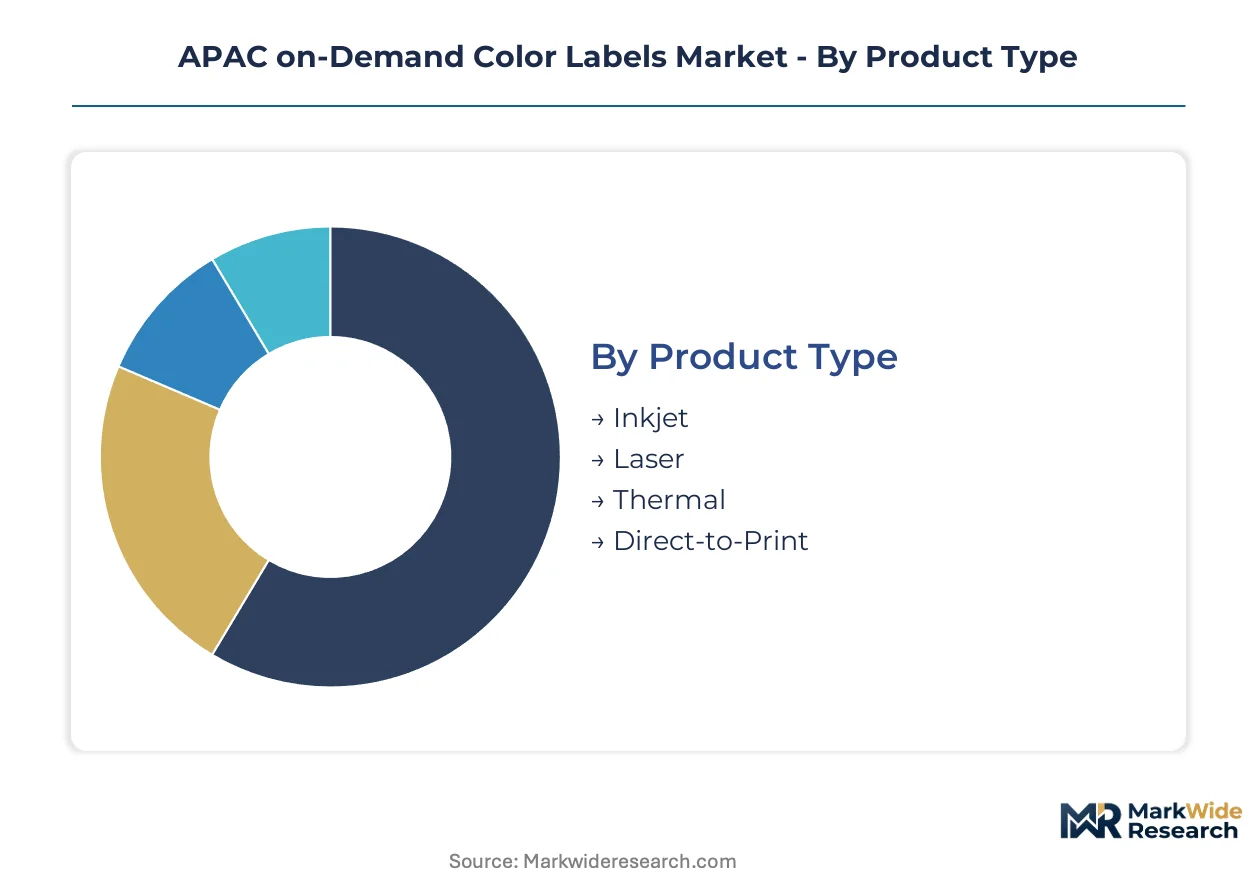
Equipment replacement cycles and substrate compatibility requirements create distinct upgrade pathways across APAC label converters. Segmentation reveals where capital deployment concentrates versus where technology transitions accelerate.
Product Type:
Replacement cycles diverge sharply between thermal legacy bases and inkjet greenfield installations across Japanese electronics corridors and Chinese e-commerce hubs.
- Thermal:Wax-resin and full-resin ribbon systems dominate installed bases in Osaka pharmaceutical packaging plants where JIS barcode durability mandates apply. METI adhesive standards restrict solvent-based thermal formulations, forcing water-based pigment ribbon upgrades in Tokyo-Osaka corridors.
- Inkjet:Single-pass aqueous systems achieve 600+ dpi resolution on polypropylene facestocks for JD Logistics and Cainiao Network fulfillment floors. Variable QR code insertion at pack stations eliminates pre-printed inventory across China's coastal manufacturing provinces.
- Laser:Toner-based systems serve Australian pharmaceutical contract packers requiring TGA-compliant tamper-evident serialization with spectrophotometric verification.
- Direct-to-Print:Linerless substrates reduce waste disposal costs for Indonesia's instant-noodle exporters switching between Arabic and English halal certification text within single shifts.
Volume placements concentrate in Thermal; the faster expansion belongs to Inkjet.
End User:
Margin structures vary by regulatory burden intensity and run-length compression patterns.
- Food & Beverage:BIS certification timelines of 14-18 months delay Indian converter qualification for FMCG seasonal campaigns. Southeast Asian producers expand short-run procurement for seasonal packaging with variable lot codes.
- Pharmaceuticals:Australia's TGA mandates color-coded tamper-evident labels for Schedule 8 controlled substances, compelling Sydney and Melbourne contract packers to install on-demand digital presses with verification modules.
- Retail:Private-label cosmetics in Japan's Kao and Shiseido supply chains demand sub-48-hour turnaround on formula variant labels, favoring digital-native converters.
- Manufacturing:South Korean battery assembly lines at SK On and LG Energy Solution facilities require chemical-resistant polyester labels with QR-coded cell genealogy data.
Revenue pools are deepest in Pharmaceuticals; Food & Beverage climbs fastest on e-commerce fulfillment expansion.
Technology:
Capital intensity thresholds and color management skill scarcity reshape competitive boundaries.
- Digital Printing:Inkjet and toner platforms command premium margin pools in Australia and New Zealand where lot-tracking regulations necessitate serialized color-coded identifiers. ICC profile calibration expertise remains scarce across Southeast Asian operator bases.
- Flexography:Plate-making lead times disqualify conventional flexo for Shiseido's sub-48-hour cosmetics label requirements in Tokyo-Osaka corridors.
- Gravure:Long-run cylinder-based systems retain position in Indonesia's mass-market instant-noodle exports where halal certification text remains static across production batches.
- Lithography:Offset platforms serve Australian pharmaceutical blister pack inserts with standardized regulatory text requiring no variable-data capability.
Installed capacity tilts toward Digital Printing; Gravure retains longest asset life cycles.
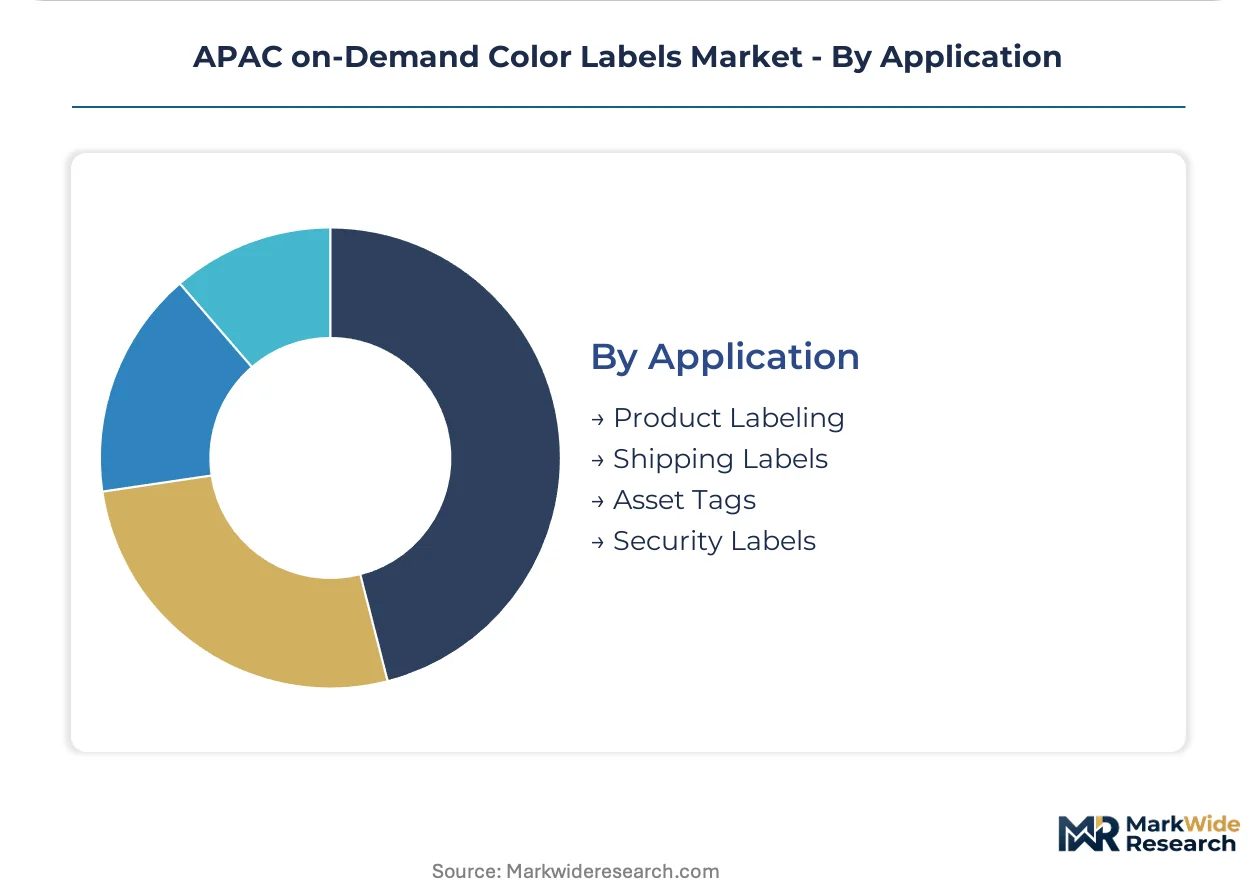
Application:
Function-specific durability requirements and data density needs segment substrate specifications.
- Shipping Labels:Full-color variable-data requirements from Chinese e-commerce fulfillment centers drive aqueous inkjet adoption on polypropylene facestocks with promotional QR codes.
- Product Labeling:Japan's cosmetics sector specifies lot-specific ingredient disclosure on primary labels with water-based pigment systems replacing solvent platforms under METI emissions restrictions.
- Asset Tags:ASEAN automotive parts distributors across Thailand and Malaysia seek combined RFID inlays with full-color variable graphics for bin-level tracking.
- Security Labels:TGA-mandated tamper-evident features with unique identifiers favor domestic Australian converters over import-dependent competitors.
Shipment velocity concentrates demand in Shipping Labels; Security Labels expand on pharmaceutical serialization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's naphtha refining hubs supply polypropylene feedstock to converters across Southeast Asia, anchoring substrate cost structures for the broader region.
China
JD Logistics and Cainiao Network deploy single-pass aqueous inkjet engines at warehouse pack stations across coastal provinces. SAMR applies GB standards restricting heavy metals in printed packaging for domestic consumption. Demand concentrates in Yangtze River Delta and Pearl River Delta manufacturing corridors where e-commerce fulfillment centers require variable-data shipping labels with promotional QR codes.
Japan
Shiseido and Kao procurement teams require sub-48-hour turnaround on cosmetics formula variant labels. METI enforces JIS S 2053 adhesive standards for food-contact applications, restricting solvent-based systems. Tokyo-Osaka packaging corridors accelerate water-based pigment ink adoption as thermal ribbon manufacturers pivot toward aqueous inkjet-compatible coatings.
Australia
TGA mandates color-coded tamper-evident labels for Schedule 8 controlled substances, compelling Sydney and Melbourne contract packers to install on-demand digital presses. Pharmaceutical serialization rules require spectrophotometric verification modules. Domestic converters capture margin premiums over import-dependent competitors serving lot-tracking regulations.
South Korea
SK On and LG Energy Solution facilities demand chemical-resistant polyester labels with QR-coded cell genealogy data. MFDS pharmaceutical regulations drive serialization compliance for export markets. Battery assembly lines in Seoul Capital Area and Busan-Ulsan industrial clusters anchor specialized label specifications.
India
BIS certification timelines of 14-18 months delay converter qualification for FMCG seasonal campaigns. FSSAI food-contact material standards tighten substrate compliance requirements. Maharashtra and Gujarat industrial parks concentrate demand from food and beverage producers expanding short-run label procurement for seasonal packaging campaigns.
APAC on-Demand Color Labels Market Competitive Environment
Global majors compete with regional champions across substrate coating capacity and digital press distribution networks. The vendor base stratifies between integrated materials suppliers, specialized printing equipment manufacturers, and niche RFID-integrated label providers. Three archetypes dominate: coating-integrated multinationals anchoring pharmaceutical compliance supply, hardware-focused technology vendors serving e-commerce fulfillment scale, and regional specialists capturing seasonal FMCG flexibility. Competitive moves concentrate on coating line reconfiguration for rapid facestock changeovers and strategic partnerships with e-commerce platform operators.
Within the coating-integrated multinational tier, Avery Dennison Corporation occupies a position exemplifying substrate supply anchoring for pharmaceutical serialization mandates. Brady Corporation represents the specialized chemical-resistant segment targeting industrial battery assembly applications. SATO Holdings sits within the RFID-integrated niche, serving automotive parts distribution networks across ASEAN markets. These three entities illustrate how competitive positioning diverges between compliance-driven pharmaceutical supply, industrial durability specifications, and track-and-trace integration requirements.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Brady Corporation |
| Lexmark International Inc. |
| Fuji Seal International Inc. |
| CCL Industries Inc. |
| Zebra Technologies Corporation |
| HP Inc. |
| Epson |
| SATO Holdings |
| Others |
Value Chain & Pricing Dynamics
Naphtha spreads from Singapore refining hubs feed polypropylene facestock costs that cascade through three downstream pricing tiers. Japanese thermal ribbon manufacturers absorb yen-denominated volatility while Chinese e-commerce platforms compress print-run economics to single-digit quantities.
Pricing Analysis
Warranty and calibration service bundling separates premium digital press suppliers from unbundled equipment vendors across Sydney pharmaceutical contract packers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales coverage breadth. Cost compression in economy-tier thermal ribbon supply is intensifying because ASEAN converters face petrochemical substrate volatility without hedging mechanisms. Small-batch cosmetics label buyers in Tokyo-Osaka corridors exhibit lowest price sensitivity due to sub-48-hour turnaround requirements.
Supply Chain Analysis
India's BIS domestic-content mandates for food-contact materials are reshaping sourcing patterns for Maharashtra and Gujarat converters. Coating capacity concentrates in Japan's Kansai region and China's Yangtze River Delta, with raw material dependencies spanning naphtha-derived polypropylene, aqueous pigment formulations, and RFID inlay substrates. Single-source vulnerability runs through yen-denominated thermal ribbon supply lines. Distribution runs through platform-integrated fulfillment networks at JD Logistics and Cainiao Network pack stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as substrate coating capabilities determine compliance access and margin capture across pharmaceutical serialization mandates.
For Market Incumbents: Anchor coating line reconfiguration capabilities for rapid polypropylene-to-paper facestock changeovers at Shanghai and Kansai facilities. Pursue captive aqueous ink formulation capacity to offset petrochemical substrate volatility threatening converter margins. Defend against emerging hardware-focused technology vendors through GMP certification depth at Australian TGA-compliant contract packers. For New Entrants and Emerging Players: Australia's TGA serialization rules for Schedule 8 pharmaceuticals open a window for domestic spectrophotometric verification module integration. Target Vietnam's underpenetrated pharmaceutical CMO sector where foreign-owned facilities require EU and US export-compliant color labels. Enter through RFID-inkjet convergence partnerships with Thai and Malaysian automotive parts distributors seeking bin-level tracking solutions. For Investors and Strategic Acquirers: BIS certification timeline compression from 14-18 months toward 8-12 months is the leading indicator that Indian converter consolidation will accelerate. Position for 5-10 year viability through coating-integrated multinationals with pharmaceutical compliance anchoring rather than pure-play hardware distributors. Monitor water-based pigment ink adoption rates across Tokyo-Osaka packaging corridors as inflection signal for substrate-ink convergence winners.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Line Reconfiguration | Enables rapid facestock changeovers for China's e-commerce single-digit print-run compression. |
| Aqueous Inkjet-Compatible Coating Development | Serves Indonesia's halal certification label switching between Arabic and English text within shifts. |
| RFID-Inlay Integration Partnership | Captures ASEAN automotive parts bin-level tracking demand across Thailand and Malaysia. |
| Spectrophotometric Verification Module Deployment | Meets Australia's TGA-mandated tamper-evident serialization for Schedule 8 pharmaceuticals. |
| GMP-Compliant Converter Qualification | Unlocks Vietnam pharmaceutical CMO export access to EU and US markets. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with label converter operations managers, pharmaceutical packaging procurement leads, e-commerce fulfillment platform engineers, and digital press distributor technical specialists combined with secondary validation from METI adhesive standard documentation, TGA serialization guidelines, and BIS certification records. Bottom-up equipment installation tracking and top-down substrate consumption estimates were triangulated to establish market sizing.
Data-stream reconciliation across equipment replacement cycles, substrate compatibility requirements, and end-user regulatory burdens shaped the analytical framework. Segmentation dimensions modeled include printing technology, end-use industry, application function, and regional regulatory cluster. CAGRs were derived from trend extrapolation of installed base transitions and greenfield adoption patterns. Forecast inputs incorporated naphtha price trajectory assumptions and e-commerce fulfillment center expansion pipelines.
The model assumes a particular technology adoption path; alternative pathways for thermal-to-inkjet transition timing would alter the outlook. Forecasts reflect assumptions about BIS certification timeline evolution and SAMR heavy metal restriction enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Wet Glue Labeling Machines Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
Wet Glue Labels Market
Labels
Foil Labels Market
Labels
Ampoule Sticker Labeling Machine Market
Labels
Booklet Labels Market
Labels
Ripeness Indicator Labels Market
Labels
Laser Printable Wristbands Market
Labels
Indicative Seals Market
Labels
Stand Alone Label Applicator Market
Labels
HAZMAT Labels Market
Labels
Inventory Tags Market
Labels
Wire Marking Labels Market
Labels
Foam Labels Market
Labels
Warning Labels and Stickers Market
Labels
Global Print and Apply Labeling and Labeling Equipment Market