
 Eco-Friendly Labels Market | 2026-2036
Eco-Friendly Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Eco-Friendly Labels Market Analysis
European adhesive label manufacturers are pivoting toward solvent-free production lines to meet tightening environmental mandates. Avery Dennison Corporation leverages its North American R&D footprint to develop bio-based adhesives, while CCL Industries anchors its competitive position through backward integration into recycled PET sourcing. Constantia Flexibles Group GmbH specializes in thin-film label structures that reduce material intensity without sacrificing print fidelity.
Eco-friendly labels are pressure-sensitive or sleeve constructions manufactured from paper, bioplastics, recycled PET, or cotton substrates using water-based inks and low-VOC adhesives, designed to decompose safely or enter closed-loop recycling streams after product use. Paper labels dominate unit volume due to established composting infrastructure and cost parity with conventional alternatives, though bioplastics represent the fastest-expanding material category as brand owners pursue marine-degradable solutions. Digital printing technology captures premium-margin work by enabling short-run customization with minimal setup waste, while flexography sustains economies of scale in food and beverage applications where heat resistance and moisture barrier properties remain non-negotiable.
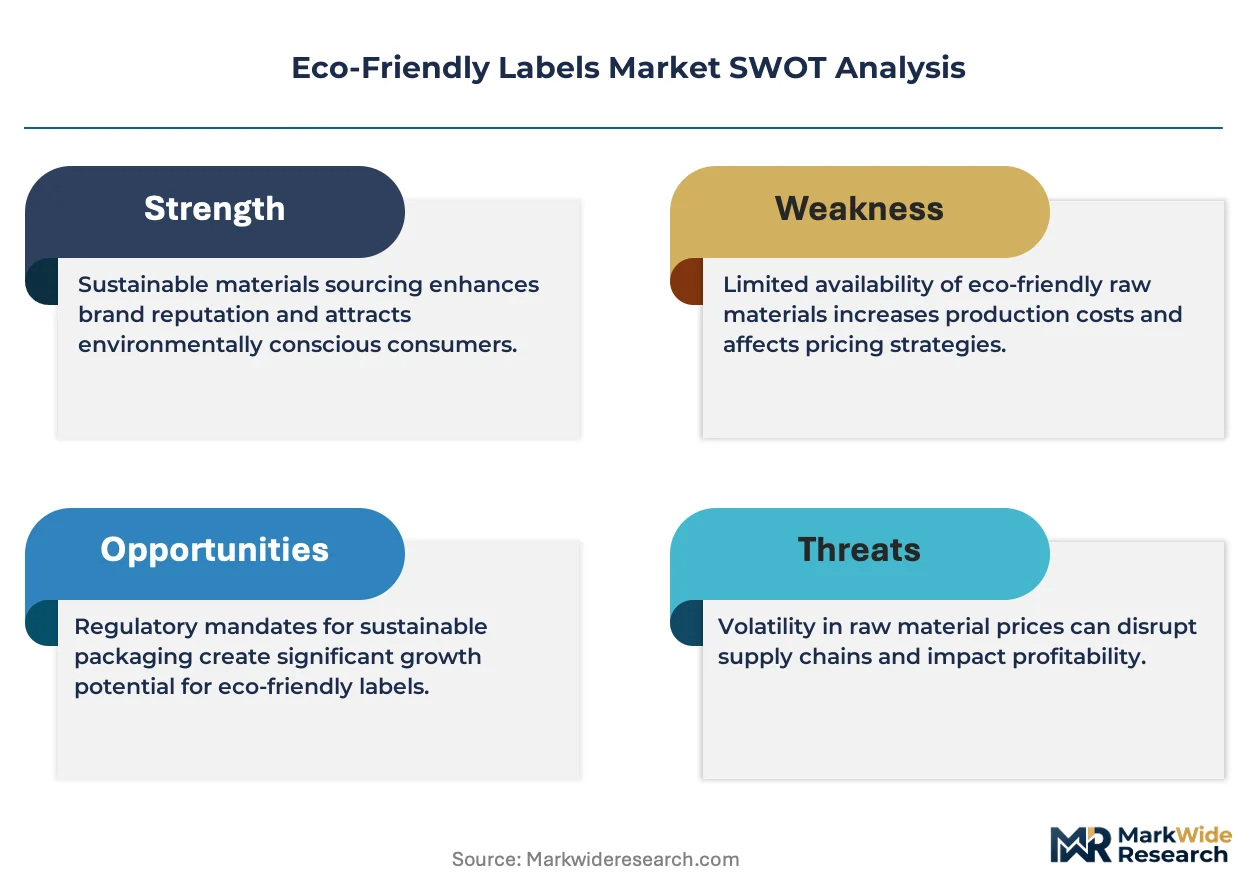
REACH restrictions on hazardous substances and the EU Green Deal's packaging waste directives are compelling substrate reformulation across the value chain, with ECHA substance evaluations now screening adhesive chemistries for persistent organic pollutant risk. FDA food-contact regulations in the United States and China's GB standards for packaging recyclability create parallel compliance obligations for multinational label converters. Stakeholders must monitor how extended producer responsibility schemes reshape cost allocation between brand owners, converters, and waste management operators.
Market Dynamics
REACH substance evaluations and EU Green Deal packaging directives are forcing substrate reformulation across adhesive label supply chains, converting environmental compliance from cost center to competitive differentiator.
Growth Catalysts
- EU Green Deal packaging waste directives:Mandates for recyclable and compostable packaging materials accelerate procurement of biodegradable label substrates across European food and beverage brands.
- Digital printing adoption:Short-run customization capabilities minimize setup waste and enable mass personalization for craft beverage producers and regional food brands.
- Marine-degradable bioplastics:Brand owners targeting ocean plastic reduction specifications drive fastest-expanding material category in coastal manufacturing clusters.
Market Restraints
- Recycled PET supply concentration:Backward integration by major converters limits spot market availability and creates input cost volatility for mid-tier label producers.
- Composting infrastructure gaps:Uneven municipal organic waste processing capabilities across US states and emerging economies restrict paper label end-of-life value proposition.
- Heat resistance limitations:Water-based inks and bio-based adhesives underperform in retort and hot-fill food applications, preserving solvent-based incumbent positions.
Strategic Opportunities
- Extended producer responsibility schemes:EU member state implementations reshape cost allocation between brand owners and converters, creating service revenue streams for compliance management.
- India FSSAI packaging regulations:Emerging mandatory recyclability standards for food contact materials open conversion demand in underpenetrated South Asian markets.
- Near-infrared sortable inks:Convergence of spectroscopic detection and water-based formulation enables closed-loop recycling of printed labels without de-inking.
Industry Challenges
- Adhesive chemistry reformulation:ECHA persistent organic pollutant screening forces R&D timeline compression as existing SKUs face substance restriction proposals.
- Certification backlog:FDA food-contact notification queue delays and BPI compostability verification timelines extend product commercialization cycles by 12-18 months.
- Legacy flexographic asset stranding:Capital-intensive solvent-based press fleets require write-down decisions as water-based and UV-LED conversion capex demands compete for limited investment budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eco-Friendly Labels Market |
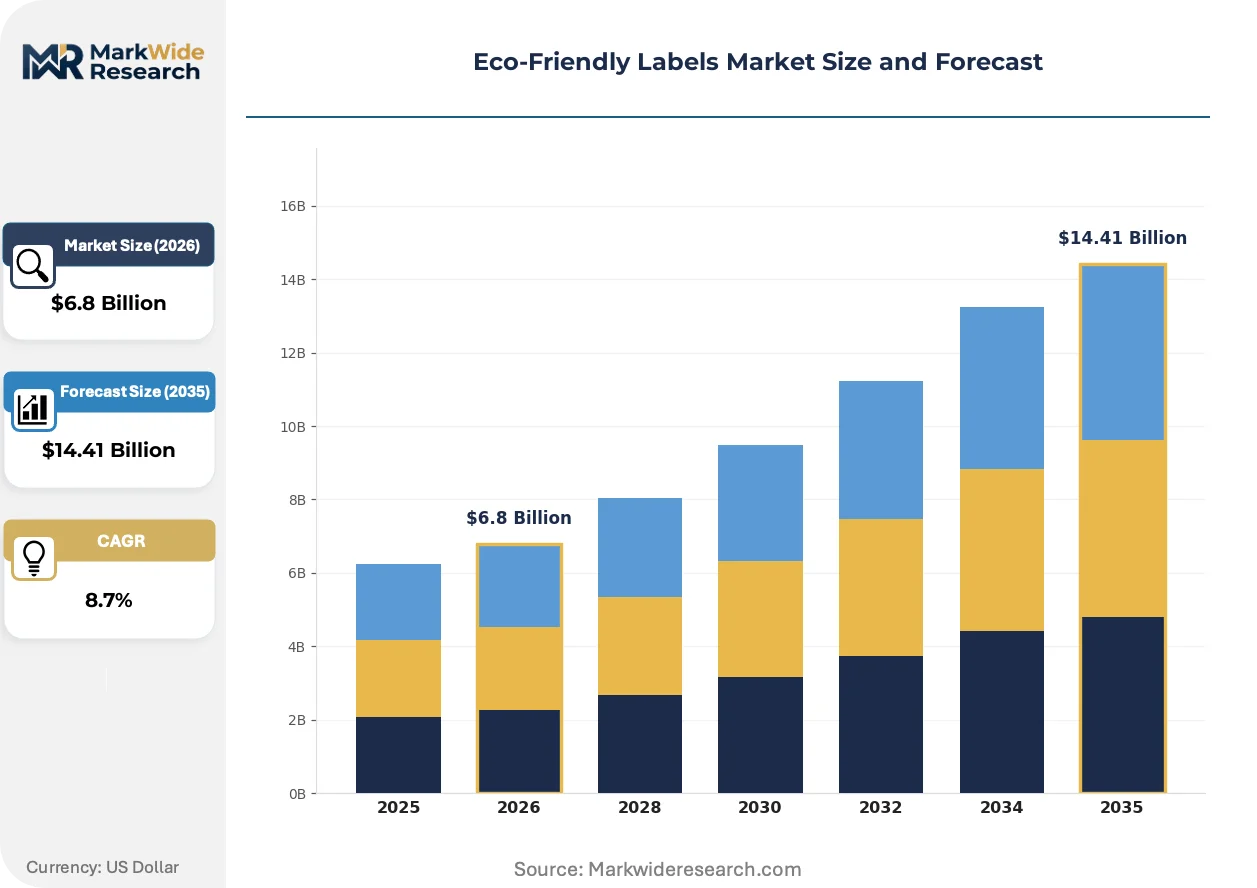
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paper, Bioplastics, Recycled PET, Cotton End User: Food & Beverage, Cosmetics, Healthcare, Retail Printing Technology: Flexography, Digital Printing, Gravure, Offset Printing Label Type: Pressure Sensitive, Heat Transfer, In-Mold, Sleeve |
| Companies Covered | Herma GmbH, All4Labels Group GmbH, Avery Dennison Corporation, Labels Plus, WestRock Company, CCL Industries, Constantia Flexibles Group GmbH, JK Labels, SATO Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eco-Friendly Labels Market Emerging Trajectories
Label manufacturing is experiencing simultaneous pressure from regulatory chemistry restrictions and brand-owner sustainability commitments, compressing acceptable material portfolios while expanding performance requirements.
Digital inkjet and toner systems are automating make-ready processes and enabling economic production runs below 5,000 linear meters. Craft distilleries and regional organic food brands adopt these platforms for seasonal and limited-edition SKUs. Variable data integration is automating regulatory compliance printing and traceability serialization without plate changeover delays.
REACH candidate list expansion and ECHA substance evaluations now screen adhesive polymers for microplastic and persistent organic pollutant characteristics. Industrial consequence includes mandatory substitution timelines for certain acrylate chemistries. Heat-resistant food applications face highest reformulation urgency as legacy adhesive families face sunset dates.
Brand technical specifications increasingly mandate third-party certifications such as FSC chain-of-custody, BPI compostability, or APR recyclability design recognition. Large retail and foodservice buyers consolidate supplier panels around pre-certified converters. European private-label food manufacturing exhibits tightest certification requirements, with North American CPG brands following 18-24 month lag.
Eco-Friendly Labels Market Segmentation
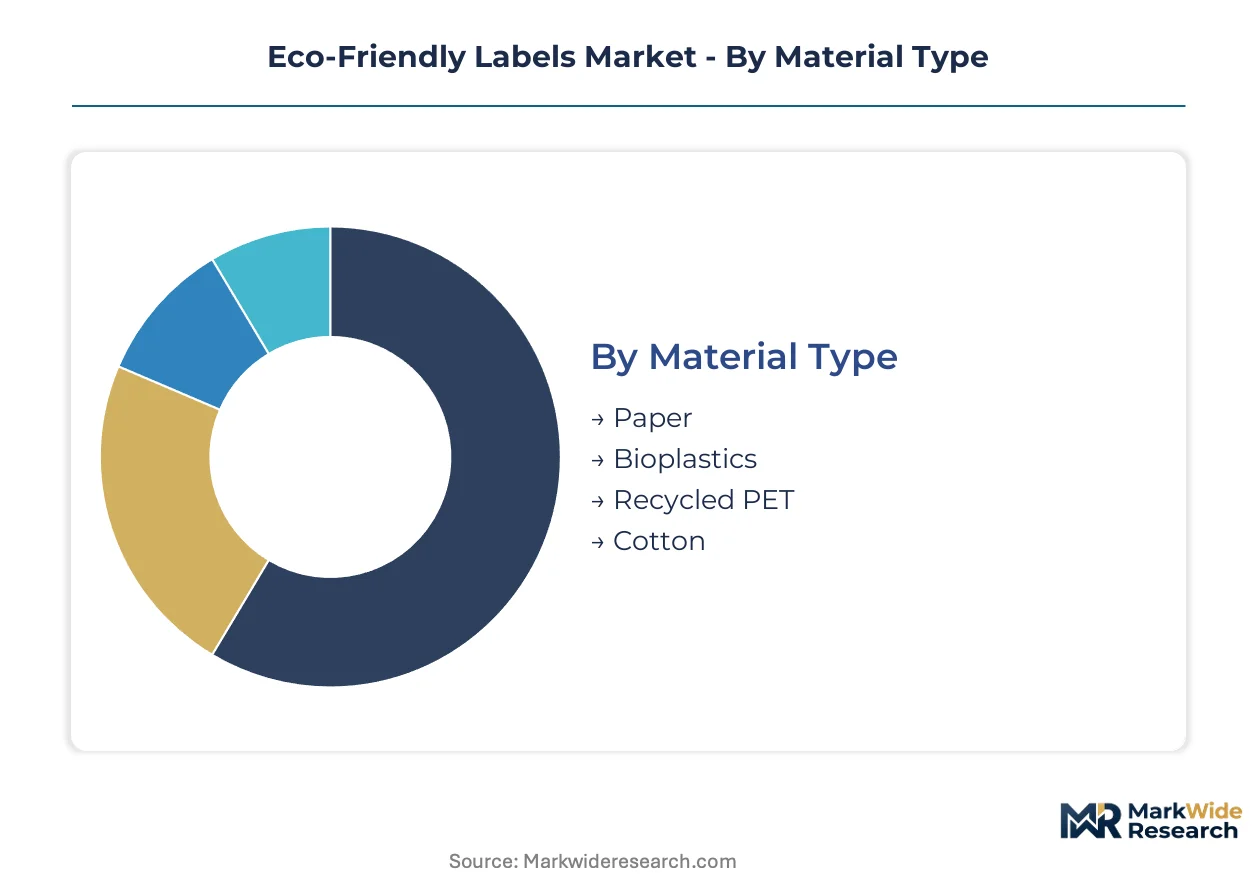
Material selection dictates capital allocation across substrate production, adhesive formulation, and printing infrastructure. End-use specifications from food-contact and healthcare applications impose certification burdens that reshape segment economics. Understanding how these dimensions intersect reveals where converter investments concentrate and where margin compression threatens.
Material Type:
Paper substrates demand the heaviest upstream investment in pulp sourcing and coating lines, while bioplastics require dedicated extrusion capacity and marine-degradation testing infrastructure.
- Paper:Cellulosic substrates using FSC-certified pulp with water-based barrier coatings dominate composting infrastructure in Germany and France. Food & Beverage procurement concentrates here due to cost parity with conventional labels and established municipal organic waste streams.
- Bioplastics:PLA and PHA polymers engineered for marine biodegradation carry premium raw material costs and specialized extrusion requirements. Coastal manufacturing clusters in the Netherlands and Spain drive specification intensity as brand owners target ocean plastic reduction commitments.
- Recycled PET:Post-consumer flake integration into film substrates requires wash-line partnerships and optical sorting investments.
- Cotton:Textile fiber labels serve premium cosmetics and apparel applications with limited volume scale.
Most installed capacity flows through Paper. Expansion is steepest in Bioplastics.
End User:
Application requirements split procurement between high-volume food packaging with strict regulatory compliance and premium cosmetics with certification-driven specification.
- Food & Beverage:Retort resistance and moisture barrier demands preserve solvent-based incumbent positions in hot-fill applications, though water-based ink migration is accelerating in ambient shelf-stable categories. German and Italian private-label manufacturers enforce the tightest certification requirements.
- Cosmetics:Premium positioning drives FSC chain-of-custody and BPI compostability mandates, with French and Swiss brand owners consolidating supplier panels around pre-certified converters.
- Healthcare:Sterilization compatibility and FDA food-contact notification queues extend commercialization cycles.
- Retail:Variable data printing for seasonal promotions favors digital adoption in regional distribution networks.
Volume concentrates in Food & Beverage. Margin expansion is strongest in Cosmetics.
Printing Technology:
Equipment selection locks converters into specific run-length economics and ink chemistry portfolios with divergent environmental compliance trajectories.
- Flexography:Solvent-based press fleets dominate heat-resistant food applications in high-volume beverage and canned goods production. Water-based and UV-LED conversion capex demands compete for limited investment budgets as REACH substance evaluations accelerate.
- Digital Printing:Inkjet and toner systems enable economic runs below 5,000 linear meters for craft distilleries and regional organic food brands. Short-run customization minimizes setup waste and automates regulatory compliance printing without plate changeover delays.
- Gravure:Cylinder engraving costs restrict adoption to ultra-high-volume commodity labels.
- Offset Printing:Sheet-fed systems serve folding carton integration for premium retail applications.
Legacy asset bases concentrate in Flexography. New investment flows predominantly to Digital Printing.
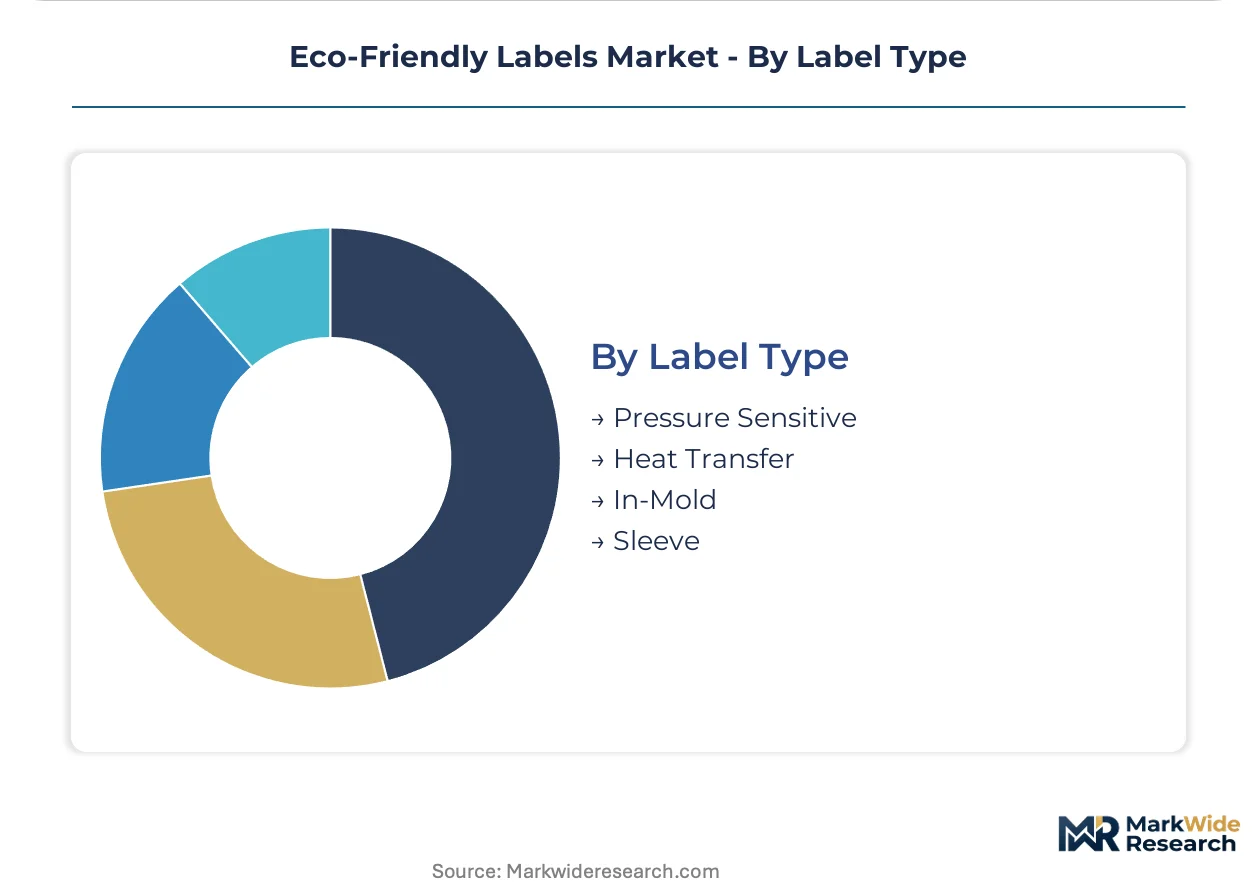
Label Type:
Application mechanics determine adhesive performance requirements and end-of-life recovery pathways, with pressure-sensitive formats commanding the broadest equipment compatibility.
- Pressure Sensitive:Self-adhesive constructions using silicone release liners span food, cosmetics, and healthcare with established dispensing infrastructure. ECHA screening of acrylate adhesive families for persistent organic pollutant characteristics forces reformulation timelines that compress R&D schedules.
- Sleeve:Shrink and stretch formats eliminate adhesive entirely, enabling closed-loop PET recycling when paired with compatible container resins. Beverage brand owners in Belgium and Austria specify sleeve labels to meet extended producer responsibility sorting requirements.
- Heat Transfer:Thermal activation systems serve durable goods with chemical resistance demands.
- In-Mold:Injection molding integration creates permanent decoration for automotive and durable container applications.
Production volume centers on Pressure Sensitive. Sleeve formats are gaining share fastest in beverage applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters migrate production toward jurisdictions where REACH compliance costs and extended producer responsibility fees create arbitrage opportunities, with Germany absorbing capacity from higher-cost EU neighbors while Asian exporters target North American markets with BPI-certified alternatives.
Germany
Private-label food manufacturers in Baden-Württemberg and Bavaria enforce the tightest FSC chain-of-custody requirements in Europe, driving procurement concentration among pre-certified converters. Herma GmbH and Constantia Flexibles Group GmbH anchor regional production capacity with solvent-free lines. The EU Green Deal packaging waste directives accelerate substrate reformulation timelines for exporters serving French and Italian buyers.
United States
Craft beverage producers in the Pacific Northwest and regional organic food brands across New England adopt digital printing platforms for seasonal SKU customization. FDA food-contact notification queues delay product commercialization cycles by 12-18 months for bioplastic label entrants. Avery Dennison Corporation leverages its North American R&D footprint to develop bio-based adhesives for ambient shelf-stable categories.
China
GB standards for packaging recyclability create parallel compliance obligations for multinational label converters operating coastal manufacturing clusters. NMPA and SAMR oversight of food-contact materials intensifies inspection protocols for exporters targeting European retail buyers. Zhejiang and Jiangsu provinces concentrate flexographic capacity serving heat-resistant applications where water-based inks underperform.
India
FSSAI packaging regulations mandating recyclability standards for food contact materials open conversion demand in underpenetrated South Asian markets. Maharashtra and Gujarat host emerging label manufacturing clusters serving domestic FMCG brands and Middle East export contracts. The PLI scheme for advanced manufacturing attracts investment in digital printing infrastructure for short-run regional brands.
Netherlands
Coastal manufacturing clusters around Rotterdam and Amsterdam drive specification intensity for marine-degradable bioplastics as brand owners target ocean plastic reduction commitments. ECHA substance evaluations screen adhesive chemistries for persistent organic pollutant risk, compressing R&D timelines for acrylate reformulation. Sleeve label formats gain share fastest among beverage exporters serving Belgian and Austrian extended producer responsibility schemes.
Eco-Friendly Labels Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue marine-degradable certification and near-infrared sortable ink specializations. The market structures around three tiers: integrated multinationals with captive recycled PET sourcing, mid-scale European specialists with solvent-free production lines, and regional digital converters serving craft beverage niche demand. Strategic moves concentrate on backward integration into wash-line partnerships and technology licensing for water-based adhesive formulations.
Among Germany-based specialists, Herma GmbH and Constantia Flexibles Group GmbH exemplify the integrated European archetype with thin-film label structures and regional production anchoring. Avery Dennison Corporation represents the multinational R&D-driven tier with North American bio-based adhesive development. These three occupy positions spanning premium certification requirements and scale-driven food and beverage procurement.
| Leading Market Players |
|---|
| Herma GmbH |
| All4Labels Group GmbH |
| Avery Dennison Corporation |
| Labels Plus |
| WestRock Company |
| CCL Industries |
| Constantia Flexibles Group GmbH |
| JK Labels |
| SATO Holdings Corporation |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Germany and the Netherlands anchor regional pricing discipline through solvent-free production lines, converting REACH compliance investments into premium positioning that resists spot-market volatility. Their concentrated ownership structures enable long-term substrate partnerships without quarterly margin pressure, stabilizing input costs for food and beverage buyers.
Pricing Analysis
Distributor margins for pressure-sensitive label stock compress as converters pursue direct relationships with private-label food manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified paper substrates from marine-degradable bioplastics and commodity-grade recycled PET. Cost compression in standard-tier paper labels is intensifying because backward integration by CCL Industries and Constantia Flexibles limits spot-market availability. Regional organic food brands exhibit highest price sensitivity, while Swiss and French cosmetics houses absorb premium positioning for BPI-certified constructions.
Supply Chain Analysis
Returns and end-of-life recovery flows are reshaping upstream sourcing as extended producer responsibility schemes mandate closed-loop PET collection in Belgium and Austria. Raw material supply concentrates in Germany, China, and India, with wash-line partnerships for post-consumer flake drawing from Dutch and Spanish coastal clusters. The supply chain rests on acrylate adhesive families facing ECHA substance restriction timelines. Single-source vulnerability in bio-based polymer feedstocks threatens capacity expansion plans. Distribution runs through converter-direct channels for high-volume beverage accounts and specialty distributors serving craft producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement is shifting toward certified sustainable specifications that command durable margin premiums. Food and beverage brands now mandate third-party validation as a baseline qualification, not a discretionary upgrade.
For Market Incumbents:Lock in backward integration into recycled PET wash-line partnerships before mid-tier competitors secure flake supply. Acquire solvent-free flexographic capacity in Baden-Württemberg to defend against digital converters encroaching on short-run food applications. ECHA persistent organic pollutant screening timelines compress reformulation windows; captive adhesive R&D preserves SKU continuity.
For New Entrants and Emerging Players:E-commerce-enabled direct sourcing platforms bypass incumbent distributor networks to reach regional craft distilleries and organic food brands in the Pacific Northwest. White-space concentrates in India FSSAI-compliant food-contact labels and near-infrared sortable ink specializations for Belgian extended producer responsibility schemes. Lead with BPI compostability pre-certification to collapse supplier qualification cycles.
For Investors and Strategic Acquirers:Valuations sit cheapest among mid-scale European specialists with solvent-free lines and pending FSC chain-of-custody upgrades. The five-to-ten-year viability thesis rests on regulatory chemistry restrictions accelerating substrate consolidation. Acquisition target archetype: German or Dutch converters with thin-film extrusion expertise and established retail buyer relationships. Monitor ECHA substance restriction proposal publication schedules as inflection triggers for adhesive reformulation capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled PET Sourcing | CCL Industries anchors margin stability through captive wash-line partnerships in North America. |
| Solvent-Free Production Line Conversion | Herma GmbH and Constantia Flexibles meet EU Green Deal mandates while preserving heat-resistant food applications. |
| Digital Printing Infrastructure Deployment | Short-run customization captures craft beverage procurement with minimal setup waste and automated compliance printing. |
| Marine-Degradable Bioplastic Certification | Coastal Netherlands manufacturers differentiate through ocean plastic reduction specifications for brand owners. |
| Near-Infrared Sortable Ink Development | Water-based formulations enable closed-loop recycling without de-inking, satisfying Belgian and Austrian sorting requirements. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with label converter operations directors, brand owner sustainability procurement leads, adhesive chemists at European manufacturers, and waste management operators running municipal composting facilities. Secondary validation drew from ECHA substance evaluation databases, EU Green Deal implementation progress reports, FDA food-contact notification queues, and FSC chain-of-custody certification registries. Bottom-up capacity assessments across German and Chinese production clusters were triangulated against top-down demand modeling from food and beverage packaging procurement data.
Segment-weighting approaches applied differential growth assumptions across material types, with bioplastics receiving accelerated coefficients reflecting marine-degradation specification intensity in coastal manufacturing clusters. End-use segmentation incorporated food-contact regulatory burden differentials and certification requirement lags between European private-label manufacturers and North American CPG brands. The analytical framework spanned the projection horizon without year-specific anchoring. CAGRs were derived from installed capacity expansion announcements, substrate price trajectory modeling, and brand owner sustainability commitment disclosure tracking.
The model assumes a particular technology adoption path; alternative pathways for water-based ink heat-resistance advancement would alter the outlook for solvent-based flexographic asset utilization. Forecasts incorporate assumptions regarding ECHA screening timelines, FSSAI implementation pacing, and municipal composting infrastructure deployment rates that could shift materially. Practitioners should monitor ECHA candidate list expansion announcements, FDA notification queue clearance velocities, and extended producer responsibility fee schedule publications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Safety Labels Market
Labels
Freshness Indicator Label Market
Labels
Wash Off Labels Market
Labels
Inventory Tags Market
Labels
Pin Feed Labels Market
Labels
BOPP Labels Market
Labels
Global Industrial Labels Market
Labels
Shrink Sleeve Labels Market
Labels
Metallic Labels Market
Labels
GCC Labeling Market
Labels
Primary Packaging Labels Market
Labels
Global in-Mold Labels Market
Labels
Screen Print Label Market
Labels
Fiber Optic Labels Market
Labels
Barcode Label Printer Market
Labels
Repositionable Labels Market