
 Asia-Pacific Aramid Fiber Market | 2026-2036
Asia-Pacific Aramid Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aramid Fiber Market Outlook
Steel reinforcement is restructuring demand patterns across protective equipment and ballistic applications as aramid fiber delivers equivalent strength at roughly one-fifth the weight. Teijin Ltd. anchors Japanese supply through para-aramid dominance in tire cord and aerospace prepregs. Hyosung Corp. leverages its position in South Korea to sustain captive demand from domestic automotive and defense contractors. Yantai Tayho Advanced Materials Co. Ltd. dominates Chinese meta-aramid output for electrical insulation and industrial filtration fabrics.
Aramid fiber comprises aromatic polyamide chains characterized by high tensile strength-to-weight ratios, thermal stability exceeding 400°C decomposition thresholds, and inherent flame resistance without halogenated additives. Manufacturers spin para-aramid variants through liquid crystal polymer solutions into highly oriented fibrillar structures optimized for ballistic and tensile applications. Para-aramid commands the largest value share across the Asia-Pacific region given its penetration in aerospace components and protective gear, where performance premiums justify material costs. Meta-aramid grows fastest in insulation materials as China's electrical grid expansion and India's railway electrification drive thermal barrier demand. Blends occupy a narrowing but technically critical niche in cables, where hybrid formulations balance cost and compliance with evolving fire safety codes.
China's SAMR enforces GB standards for flame-retardant textiles that effectively mandate aramid content in certified protective equipment for firefighters and electrical utility workers. Japan's METI coordinates JIS standards with PMDA safety protocols to govern aramid implantable medical devices and industrial filtration media. South Korea's MFDS and KOSHA jointly regulate chemical exposure limits in aramid manufacturing facilities, shaping production location decisions for multinationals. Stakeholders must track how China's dual carbon goals and India's PLI scheme for advanced materials redirect capital toward domestic aramid precursor synthesis versus finished fiber imports.
Market Dynamics
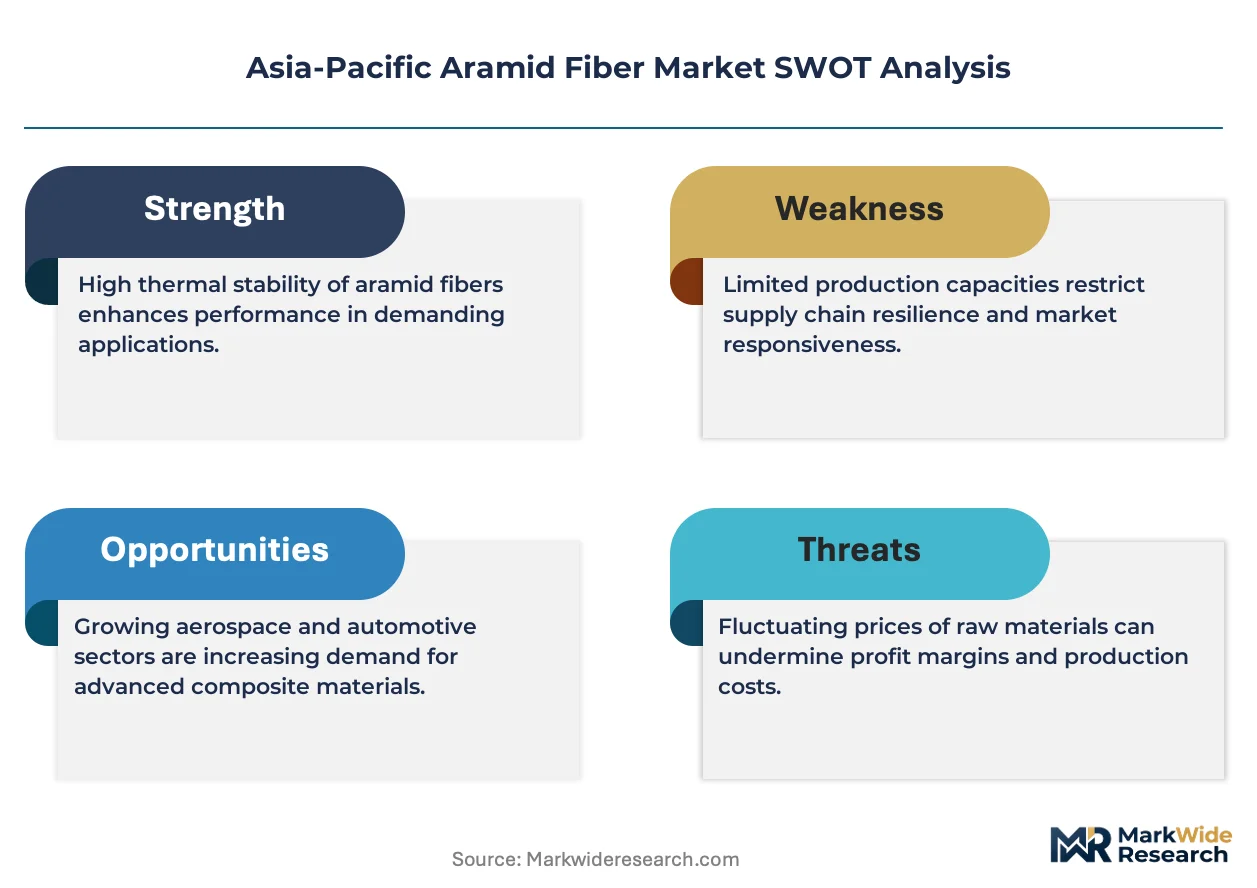
Steel-to-aramid substitution in protective equipment and ballistic applications is restructuring procurement patterns as end-users prioritize weight reduction without sacrificing tensile performance. China's tightening GB standards for flame-retardant textiles and Japan's aerospace composite certification requirements are accelerating material specification changes across the region.
Growth Catalysts
- GB Standards Mandate:China's SAMR enforces flame-retardant textile regulations that effectively require aramid content in certified firefighter and electrical utility protective equipment, creating structural demand pull.
- Aerospace Composite Adoption:Japanese and South Korean manufacturers are expanding para-aramid prepregs into fuselage panels and engine nacelles as weight reduction targets intensify.
- Jiangsu-Shandong Cluster Density:Eastern China's specialty chemical concentration enables integrated aramid-to-fabric production chains that compress lead times for domestic textile converters.
Market Restraints
- Precursor Supply Concentration:Meta-aramid polymer feedstock production concentrates among a limited set of Chinese and Japanese suppliers, exposing downstream spinners to allocation risk during demand surges.
- Para-aramid Cost Premium:Liquid crystal spinning technology and solvent recovery requirements sustain para-aramid pricing at multiples of meta-aramid variants, limiting penetration in cost-sensitive industrial filtration.
- Halogen-Free Substitution:Phosphorus-based flame retardants in engineered thermoplastics compete for electrical enclosure applications where thermal performance requirements have softened.
Strategic Opportunities
- India Railway Electrification:Thermal barrier demand from locomotive traction systems and grid infrastructure expansion outpaces domestic meta-aramid supply, creating import substitution potential.
- PLI Scheme Alignment:India's production-linked incentive scheme for advanced materials offers capital cost offsets for domestic aramid precursor synthesis facilities.
- Recycling Technology Convergence:Pyrolysis and solvent-based fiber recovery methods are advancing to address end-of-life composite waste from aerospace and ballistic applications.
Industry Challenges
- Spinning Technician Scarcity:Liquid crystal polymer solution spinning requires specialized expertise in dope preparation and coagulation control that outstrips regional vocational training output.
- Dual Carbon Compliance:China's MEE enforcement of carbon intensity targets forces solvent recovery system upgrades that extend capital payback periods for capacity expansions.
- Medical Device Certification:Japan's PMDA implantable device pathways for aramid-based surgical meshes impose multi-year clinical validation timelines that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aramid Fiber Market |
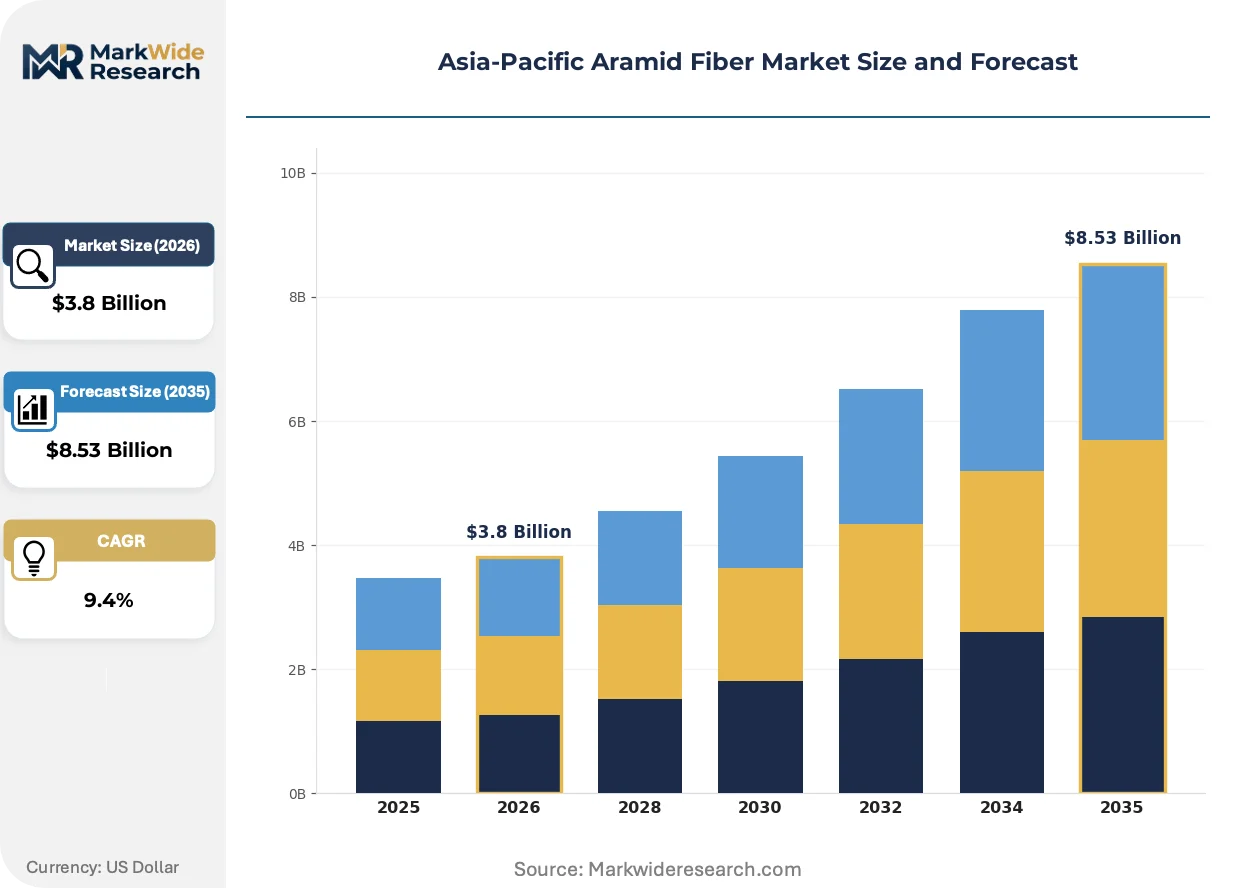
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meta-Aramid, Para-Aramid, Blends, Others End User: Automotive, Aerospace, Electrical, Construction Application: Protective Gear, Aerospace Components, Insulation Materials, Cables Form: Sheet, Fiber, Yarn, Fabric |
| Companies Covered | Hyosung Corp., Huvis Corp., Teijin Ltd., China National Bluestar (Group) Co. Ltd., Sinopec Yizheng Chemical Fibre Co. Ltd., Kolon Industries, Inc., Toray Chemicals South Korea, Inc., SRO Aramid (Jiangsu) Co. Ltd., Yantai Tayho Advanced Materials Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aramid Fiber Market Strategic Shifts
Multi-axial preform architectures and recycled fiber integration are compressing the performance-cost frontier for aramid composites. Manufacturers are repositioning around sustainability credentials and functional customization rather than commodity volume.
Hybrid thermoplastic-aramid prepregs are unifying the processing speed of thermoplastic matrices with the ballistic performance of para-aramid reinforcement. South Korean automotive suppliers are piloting these materials for electric vehicle battery enclosure panels. This convergence is compressing the traditional separation between aerospace-grade prepregs and industrial compression molding applications.
China's GB standards for flame-retardant protective equipment are tightening certification testing protocols for domestic textile suppliers. The SAMR now requires documented aramid content percentages in firefighter gear and electrical arc protection clothing. Domestic converters in Shandong and Jiangsu provinces are responding by securing long-term fiber supply agreements to ensure batch traceability.
Specification-driven procurement is displacing spot-market purchasing for critical safety applications. Japanese aerospace contractors and South Korean defense integrators now require fiber lot testing data and polymer chain orientation certificates before contract execution. This behavioral shift is most visible in ballistic panel and aerospace prepreg segments where performance liability exposure concentrates among tier-one system suppliers.
Asia-Pacific Aramid Fiber Market Segmentation
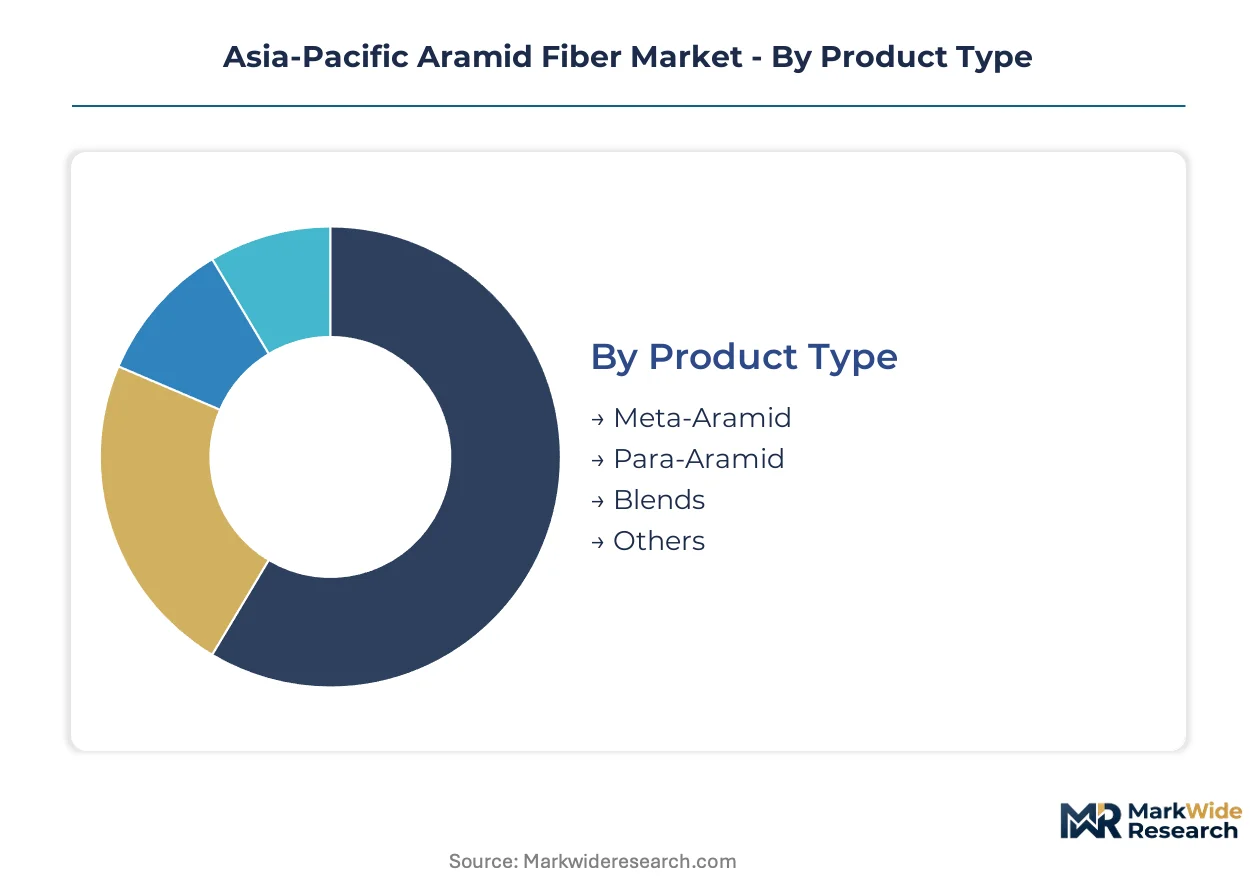
Aramid fiber segmentation in Asia-Pacific reflects divergent certification burdens across product grades and end-uses. GB standards for flame-retardant textiles and aerospace composite protocols create tiered compliance costs that reshape procurement patterns by segment.
Product Type:
GB standards for protective equipment and JIS aerospace protocols impose distinct certification timelines on each aramid variant, with para-aramid facing the most intensive qualification requirements.
- Para-Aramid:Liquid crystal polymer solutions spin into highly oriented fibrillar structures with tensile strength-to-weight ratios exceeding steel. Japanese and South Korean aerospace manufacturers specify para-aramid prepregs for fuselage panels and engine nacelles where METI and MFDS certification protocols govern material traceability.
- Meta-Aramid:Aromatic polyamide chains with thermal stability above 400°C decomposition thresholds serve electrical insulation and industrial filtration. China's Jiangsu and Shandong specialty chemical clusters feed integrated aramid-to-fabric production chains for domestic electrical grid expansion and railway electrification demand.
- Blends:Hybrid formulations balance cost and fire safety compliance in cable sheathing applications where halogen-free codes are tightening.
- Others:Copolymer variants and modified aramid structures address niche medical device and specialty filtration requirements under PMDA and CDSCO pathways.
Leading the category by volume: Para-Aramid. Growing fastest: Meta-Aramid.
End User:
Customer procurement scale and specification intensity vary sharply across end-use sectors, with aerospace and defense contractors demanding lot-level testing data.
- Aerospace:Fuselage panels, engine nacelles, and interior components require para-aramid prepregs certified to JIS and MFDS composite standards. Japanese manufacturers specify fiber lot testing data and polymer chain orientation certificates before contract execution.
- Automotive:Electric vehicle battery enclosures and tire reinforcement applications drive meta-aramid and para-aramid demand. South Korean automotive suppliers pilot hybrid thermoplastic-aramid prepregs for battery enclosure panels.
- Electrical:Transformer insulation, motor slot liners, and cable wrapping utilize meta-aramid for thermal barrier performance. India's railway electrification and grid infrastructure expansion outpaces domestic supply, creating import reliance.
- Construction:Reinforced concrete and geotextile applications represent cost-sensitive volume demand where meta-aramid competes with glass and carbon fiber alternatives.
Aerospace commands the highest specification premiums. Electrical is climbing the fastest as grid investments accelerate.
Application:
Functional performance requirements and liability exposure determine which applications mandate certified aramid content versus discretionary substitution.
- Protective Gear:Firefighter equipment and electrical arc protection clothing face mandatory GB standards in China that effectively require documented aramid content percentages. SAMR enforcement creates structural demand pull for certified textile converters.
- Aerospace Components:Prepreg and filament-wound structures for primary and secondary airframe elements carry the most intensive certification burdens. Japanese and South Korean tier-one system suppliers require complete polymer chain traceability.
- Insulation Materials:Thermal barriers for electrical equipment and industrial process equipment utilize meta-aramid felts and papers. China's dual carbon goals and MEE enforcement drive solvent recovery system upgrades that extend capital payback periods.
- Cables:Fire-resistant cable sheathing and insulation represent a narrowing but technically critical niche where hybrid formulations balance cost and evolving fire safety codes.
Protective gear dominates by shipment volume. Insulation materials are gaining share fastest on electrical infrastructure buildouts.
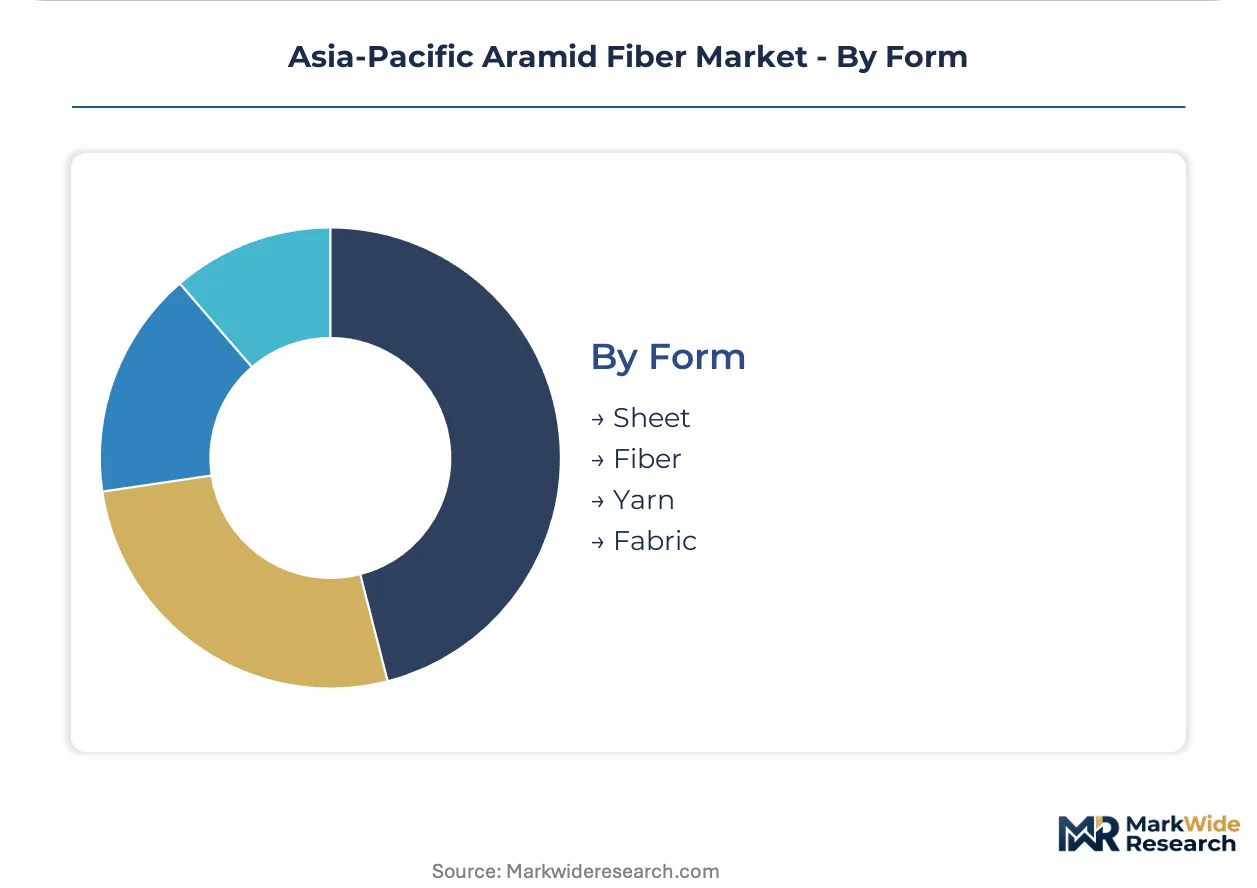
Form:
Downstream processing integration and lead time compression favor specific form factors in eastern China's production clusters.
- Fiber:Continuous filament and staple forms feed textile converters and composite manufacturers. Jiangsu and Shandong specialty chemical clusters enable integrated aramid-to-fabric production chains.
- Fabric:Woven, knitted, and non-woven textile structures serve protective clothing and industrial filtration end-uses. Chinese domestic converters secure long-term fiber supply agreements to ensure batch traceability for GB certification.
- Yarn:Twisted and plied constructions for tire cord, rope, and specialty textile applications where tensile performance requirements specify para-aramid content.
- Sheet:Pressed and calendered forms for electrical insulation laminates and gasket materials in industrial equipment applications.
Fiber leads by production tonnage. Fabric is expanding most quickly on integrated converter investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in eastern China's specialty chemical clusters and Japanese aerospace manufacturing corridors, with South Korean automotive and Indian electrical infrastructure emerging as secondary growth poles across the analysis window.
China
Jiangsu and Shandong provinces anchor domestic meta-aramid output for electrical insulation and industrial filtration fabrics. SAMR enforcement of GB standards for flame-retardant protective equipment mandates documented aramid content in certified firefighter gear. The Yangtze River Delta specialty chemical concentration enables integrated aramid-to-fabric production chains that compress lead times for textile converters.
Japan
Para-aramid prepregs penetrate fuselage panels and engine nacelles as aerospace manufacturers intensify weight reduction targets. METI coordinates JIS standards with PMDA safety protocols to govern aramid implantable medical devices and industrial filtration media. Kanto region aerospace contractors now require fiber lot testing data and polymer chain orientation certificates before contract execution.
South Korea
Domestic automotive and defense contractors sustain captive demand for tire cord and ballistic applications. MFDS and KOSHA jointly regulate chemical exposure limits in aramid manufacturing facilities, shaping production location decisions for multinationals. Busan-Ulsan industrial corridor suppliers pilot hybrid thermoplastic-aramid prepregs for electric vehicle battery enclosure panels.
India
Railway electrification and grid infrastructure expansion outpace domestic meta-aramid supply, creating import substitution potential. The PLI scheme for advanced materials offers capital cost offsets for domestic aramid precursor synthesis facilities. Maharashtra and Gujarat industrial zones attract investment targeting thermal barrier demand from locomotive traction systems.
Australia
Mining safety equipment and industrial protective gear drive specification-grade para-aramid imports for high-tensile applications. TGA pathways govern aramid-based medical device approvals, though penetration remains limited compared to Asian manufacturing centers. Western Australia resource sector procurement emphasizes certified flame-resistant textiles for underground operations.
Asia-Pacific Aramid Fiber Market Competitive Environment
Capacity expansion dominates the current landscape as regional players scale meta-aramid output to capture electrical infrastructure demand. The vendor base stratifies across three tiers: integrated chemical conglomerates with precursor control, specialty fiber spinners serving certified protective equipment markets, and downstream fabric converters securing long-term supply agreements. Two strategic archetypes define competitive positioning: upstream-integrated producers leveraging Jiangsu-Shandong cluster density, and specification-focused suppliers qualifying for aerospace and defense procurement channels. Geographic expansion and technology licensing represent the dominant competitive moves, with players establishing satellite spinning capacity near end-use concentrations.
Within the integrated chemical conglomerate tier, Teijin Ltd. and Hyosung Corp. exemplify upstream-controlled positioning through captive para-aramid supply chains. Yantai Tayho Advanced Materials Co. Ltd. occupies a specialist position concentrated in eastern China's production clusters. These three anchors demonstrate how regional players leverage distinct regulatory environments—Japan's METI aerospace protocols, South Korea's MFDS manufacturing standards, and China's SAMR certification requirements—to defend segment positioning without direct product overlap.
| Leading Market Players |
|---|
| Hyosung Corp. |
| Huvis Corp. |
| Teijin Ltd. |
| China National Bluestar (Group) Co. Ltd. |
| Sinopec Yizheng Chemical Fibre Co. Ltd. |
| Kolon Industries, Inc. |
| Toray Chemicals South Korea, Inc. |
| SRO Aramid (Jiangsu) Co. Ltd. |
| Yantai Tayho Advanced Materials Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between GB-standard protective equipment and commodity industrial filtration creates divergent pricing power across the Asia-Pacific aramid fiber landscape. SAMR-mandated aramid content percentages in Chinese firefighter gear sustain premium capture for certified suppliers, while uncertified meta-aramid for electrical insulation faces relentless cost compression from glass fiber substitutes.
Pricing Analysis
Volume shipments concentrate in standard-grade meta-aramid for transformer insulation and cable wrapping, but margin capture clusters in para-aramid prepregs qualified to JIS aerospace protocols. Three-tier pricing structure across certified protective, industrial specification, and commodity filtration levels reflects the cost of polymer chain orientation testing and lot-level traceability documentation. Pricing pressure stems from phosphorus-based flame retardants encroaching on electrical enclosure applications where thermal thresholds have softened. State-owned grid operators in China exhibit highest price sensitivity, while Japanese aerospace tier-ones accept performance premiums with minimal negotiation.
Supply Chain Analysis
End-of-life composite recovery flows from South Korean automotive battery enclosures and Japanese aerospace manufacturing scrap are emerging as secondary feedstock channels for regenerated para-aramid pulp. Precursor synthesis concentrates in China, Japan, and South Korea, with meta-aramid polymer feedstock drawing from aniline and m-phenylenediamine streams controlled by Jiangsu-Shandong chemical clusters. Single-source vulnerability pervades liquid crystal spinning equipment, where German and Japanese machinery suppliers command extended lead times. Distribution runs through captive supply agreements linking eastern Chinese fiber producers to domestic textile converters, compressing spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's GB standards for flame-retardant protective equipment function as a cost-of-compliance moat, elevating capital requirements for domestic certification and marginalizing unqualified imports. SAMR enforcement creates structural barriers that reward pre-existing regulatory relationships.
For Market Incumbents: Deepen backward integration into meta-aramid precursor synthesis to neutralize allocation risk during Jiangsu-Shandong demand surges. Secure long-term fiber supply agreements with Shandong textile converters to lock in batch traceability for GB certification renewals. Expand solvent recovery system capacity ahead of MEE carbon intensity enforcement timelines.
For New Entrants and Emerging Players: Specialty chemical distributors in India's Maharashtra and Gujarat industrial zones represent the most penetrable channel for import substitution targeting railway electrification thermal barriers. Target PLI scheme alignment for capital cost offsets on domestic aramid precursor facilities. Pursue qualification partnerships with state transmission utilities to bypass incumbent supply relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking Jiangsu-Shandong production cluster access. Long-term viability hinges on precursor control rather than spinning capacity alone. Monitor SAMR certification backlog processing rates as an inflection indicator for domestic supply discipline.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Captive aniline supply from Shandong chemical clusters neutralizes raw material allocation risk during demand spikes. |
| GB Certification Investment | SAMR-compliant firefighter gear qualification opens structural demand from Chinese state procurement channels. |
| PLI Scheme Alignment | India's advanced materials incentive offsets capital intensity for domestic meta-aramid polymer facilities. |
| Solvent Recovery System Upgrade | MEE carbon intensity compliance extends operational license continuity for Jiangsu spinning operations. |
| Hybrid Thermoplastic-aramid Prepreg Development | South Korean automotive battery enclosure adoption bridges aerospace performance with industrial processing speed. |
Study Parameters
Independent corroboration across plant managers at Jiangsu-Shandong spinning facilities, procurement leads at Japanese aerospace tier-ones, and distribution channel partners in South Korea's Busan-Ulsan corridor underwrites the qualitative findings. Technical R&D directors at meta-aramid insulation producers and regulatory affairs specialists navigating SAMR certification pathways provided primary perspective. Secondary validation drew from Chinese customs trade data, METI industrial production statistics, SEC 10-K filings of listed fiber producers, and GB standard revision notices. Bottom-up fiber shipment estimates triangulated against top-down end-use consumption models across protective equipment, aerospace, and electrical insulation segments.
Rate-of-change decomposition across the analysis window separates volume expansion in electrical infrastructure from value capture in certified protective applications. Segmentation modeling incorporates product type grade tier, end-use industry specification intensity, regional production hub regulatory environment, and application certification burden. CAGRs derive from iterative convergence between historical shipment trajectories and forward-looking capacity announcements. Forecast inputs include railway electrification project pipelines from Indian Railways and MEE enforcement intensity projections for solvent recovery mandates.
Several conditions sit outside the modeled scope, including sudden GB standard revision timelines, PMDA medical device pathway acceleration, and halogen-free substitution breakthroughs in engineered thermoplastics. Forecasts reflect documented assumptions regarding SAMR certification continuity and precursor supply stability. Practitioners should monitor PLI scheme disbursement rates and MEE carbon intensity audit frequencies for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
High Performance Polyester Market
Synthetic Fibers
Performance Fabric Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
Global Synthetic Spider Silk Market
Synthetic Fibers
Melt Spun Fibers Market
Synthetic Fibers
Designer Fiber Market
Synthetic Fibers
Polypropylene Fiber Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
Synthetic Sewing Thread Market
Synthetic Fibers
Europe Aramid Fiber Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
High End Synthetic Suede Market
Synthetic Fibers
Parachute Fabric Market
Synthetic Fibers
Polyimide Fiber Market
Synthetic Fibers
Polyester Straps Market