
 Europe Aramid Fiber Market | 2026-2036
Europe Aramid Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aramid Fiber Market Foresight
German para-aramid production capacity is rebalancing after energy-intensive spinning operations faced feedstock cost volatility. Teijin Aramid B.V. anchors European supply through its Netherlands-based polymerization and spinning assets, while DuPont leverages its integrated precursor chain to sustain specification-grade output for military and aerospace contractors. Kermel competes on meta-aramid purity grades suited to France's nuclear and chemical protection protocols, occupying a niche between bulk para-aramid and commodity flame-retardant alternatives.
Aramid fiber consists of aromatic polyamide chains linked by amide bonds, yielding tensile strengths exceeding five gigapascals alongside thermal stability above four hundred degrees Celsius; manufacturers spin these polymers into filaments via dry-jet wet spinning for ballistic panels, electrical insulation, and structural composites. Para-aramid dominates volume in protective clothing and ballistic applications where strength-to-weight ratios command premium positioning, while meta-aramid specializes in thermal insulation and fire-blocking textiles for aerospace and industrial settings. Prepreg forms capture widening margins as automated fiber placement spreads through European aerospace tier-one suppliers seeking labor-efficient composite layup.
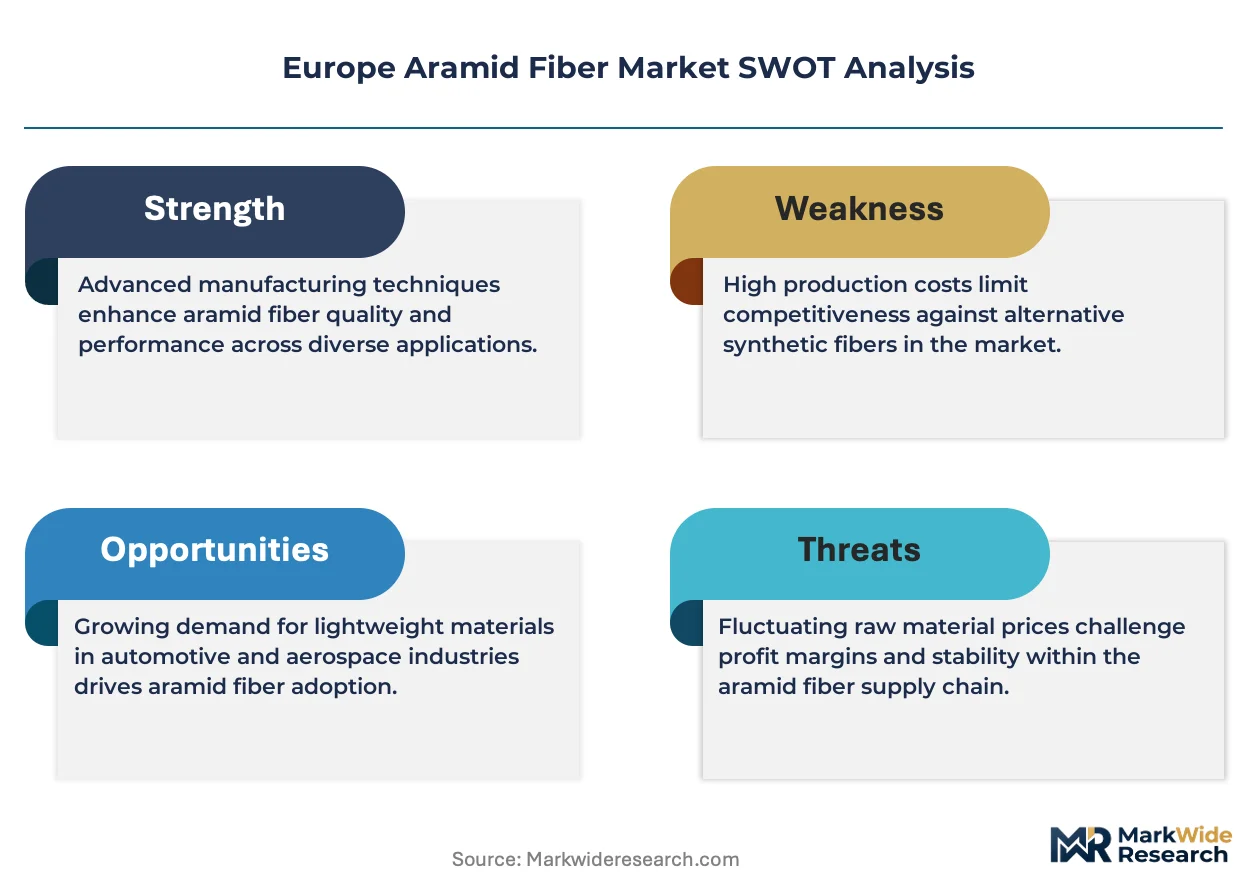
REACH compliance governs precursor chemical registration across EU manufacturing sites, while the EU Green Deal's carbon border adjustments reshape sourcing decisions for imported para-aramid intermediates. CE marking under the Personal Protective Equipment Regulation mandates third-party certification for ballistic and flame-resistant garments sold to European defense and emergency services. Stakeholders must track how ECHA's evolving substance restrictions affect alternative polymer chemistries and whether Germany's national hydrogen infrastructure plans alter energy costs for aramid polymerization facilities.
Market Dynamics
Energy-intensive spinning operations across Germany's Ruhr corridor face feedstock cost volatility, forcing polymerization facilities to rebalance capacity allocation between ballistic-grade para-aramid and industrial meta-aramid streams.
Growth Catalysts
- EU Green Deal industrial benchmarks:Tightening emissions standards for defense and automotive suppliers are mandating lighter composite materials that reduce vehicle and aircraft fuel consumption.
- Aerospace composite reinforcement:Northern European procurement of automated fiber placement systems is expanding specification-grade aramid offtake for structural components.
- Ballistic protection clustering:Concentrated demand in Germany's Ruhr industrial corridor draws sustained volume for para-aramid used in military and law enforcement protective systems.
Market Restraints
- Precursor chemical volatility:p-Phenylenediamine and terephthaloyl chloride feedstock prices fluctuate with energy costs, compressing margins at European polymerization facilities.
- Supply concentration risk:Netherlands-based polymerization assets anchor regional para-aramid availability, creating single-point vulnerability for continental ballistic and aerospace supply chains.
- High-performance polymer substitution:Ultra-high molecular weight polyethylene fibers compete on specific strength metrics for certain ballistic applications, pressuring para-aramid pricing in select segments.
Strategic Opportunities
- Eastern European industrial expansion:Poland and Czech Republic manufacturing bases remain underpenetrated for meta-aramid thermal protection in chemical processing and power generation facilities.
- Hydrogen infrastructure alignment:Germany's national hydrogen pipeline plans could reduce energy costs for aramid polymerization, improving cost competitiveness against Asian imports.
- Recycling technology convergence:Emerging chemical depolymerization methods paired with EU circular economy mandates create closed-loop feedstock potential for European fiber producers.
Industry Challenges
- REACH substance authorization timelines:ECHA's evolving restrictions on precursor chemistries delay new product introductions while compliance documentation absorbs technical resources.
- CE marking certification complexity:Third-party verification under the Personal Protective Equipment Regulation extends time-to-market for ballistic and flame-resistant garments bound for defense and emergency services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aramid Fiber Market |
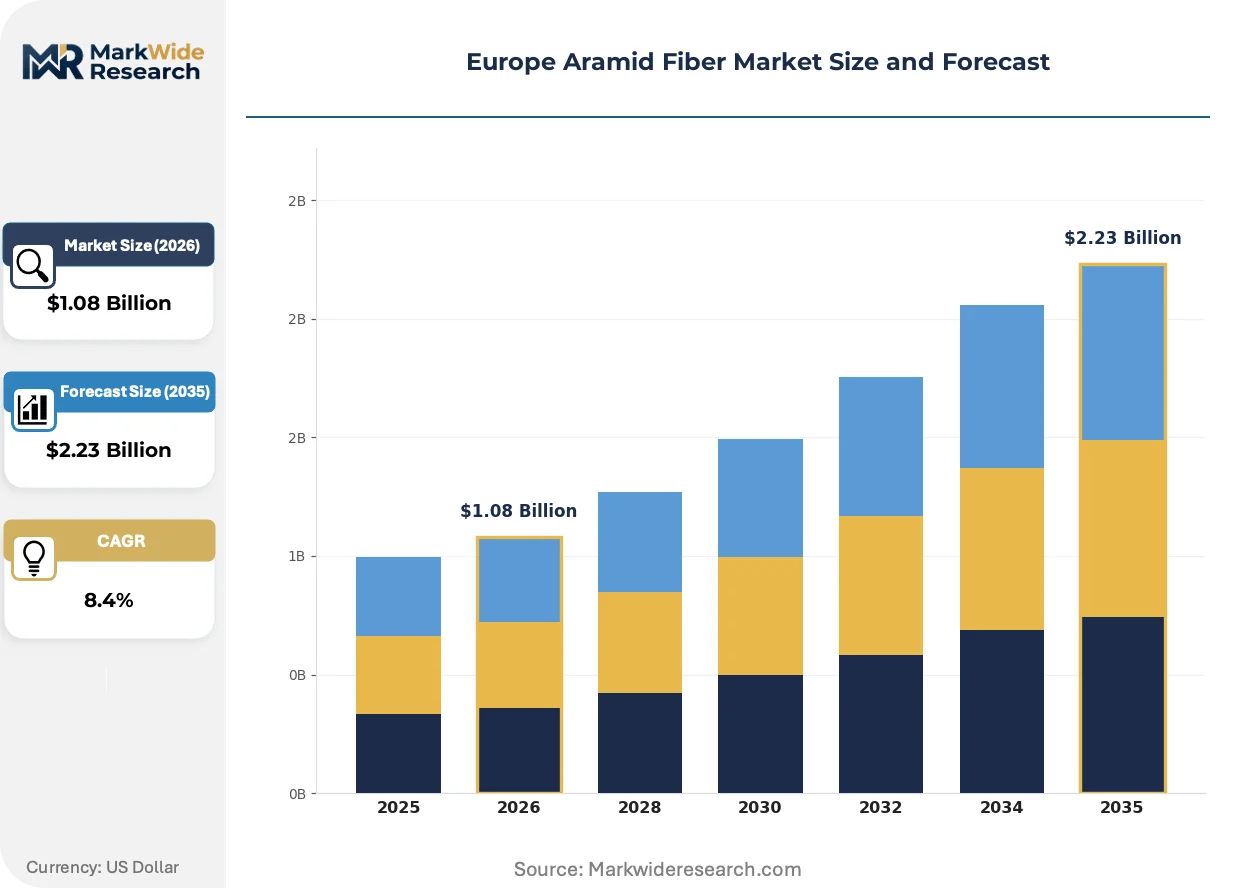
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Para-Aramid, Meta-Aramid, Blend Aramid, Others End User: Aerospace, Military, Automotive, Electronics Form: Filament, Staple Fiber, Fabric, Prepreg Application: Protective Clothing, Composites, Insulation, Cables |
| Companies Covered | DuPont, Teijin Aramid B.V., Hyosung, Toray Industries Inc., Kermel, Huvis, YF International bv, Kolon Industries Inc., DuPont de Nemours, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aramid Fiber Market Shifts & Advancements
Automated manufacturing systems and regulatory compliance technologies are restructuring how European aramid fiber reaches end-use markets, compressing traditional supply chain layers while elevating specification requirements.
Recyclable aramid composite technologies are decentralizing waste management responsibilities across European aerospace tier-one suppliers. Airbus and Safran manufacturing sites in France and Germany now pilot chemical depolymerization units that regenerate polymer feedstock from production scrap. This distributed recovery model reduces reliance on virgin precursor imports while aligning with EU circular economy implementation timelines.
REACH substance restrictions are tightening registration requirements for aromatic amine precursors used in para-aramid polymerization. ECHA's 2023-2025 evaluation window for high-volume chemicals is forcing Dutch and German manufacturers to submit extended toxicity dossiers. Meta-aramid producers face particular scrutiny on methylene diphenyl diisocyanate alternatives, compressing formulation flexibility for thermal insulation grades.
Specification-driven procurement now dominates European defense and aerospace channels, displacing commodity purchasing frameworks. Buyers in France's nuclear protection sector and Germany's automotive composite tier demand batch-level certification data that extends supplier qualification cycles. This behavioral shift concentrates contract awards among producers with captive testing laboratories, fragmenting market access for smaller spinning operations without in-house analytical capabilities.
Europe Aramid Fiber Market Segmentation
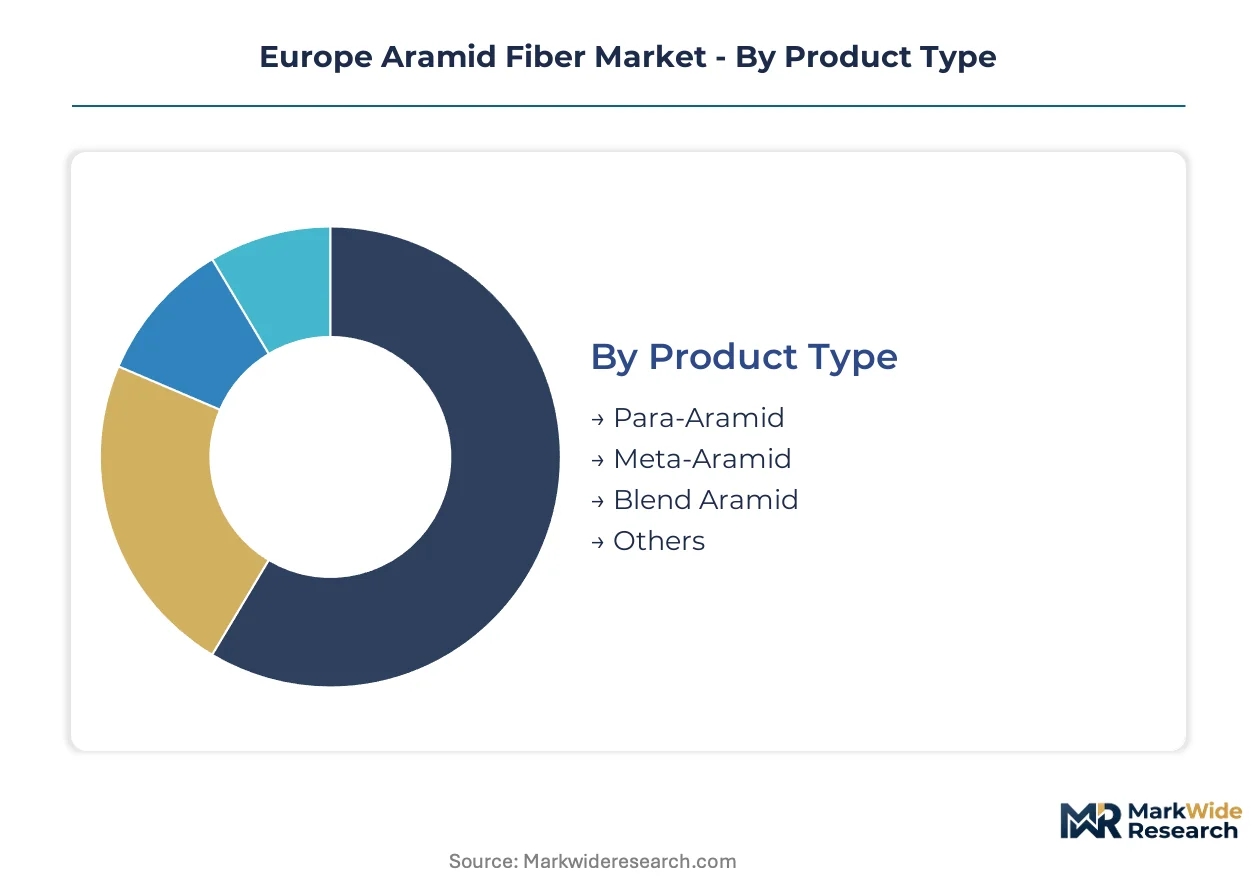
Aramid fiber segmentation in Europe reflects divergent technical specifications across defense procurement, aerospace qualification, and industrial safety mandates. Specification-grade requirements fragment demand into discrete product tiers where certification barriers lock out commodity producers.
Product Type:
Customization intensity varies sharply across this category, with military ballistic standards demanding batch-traceable para-aramid while industrial thermal applications tolerate broader meta-aramid specification ranges.
- Para-Aramid:High-modulus aromatic polyamide chains deliver tensile strength exceeding five gigapascals for ballistic panels and structural composites. Demand concentrates in Germany's Ruhr corridor for military protective systems, constrained by p-phenylenediamine feedstock volatility under REACH registration pressures.
- Meta-Aramid:Lower crystallinity yields thermal stability above four hundred degrees Celsius without the tensile performance of para grades. France's nuclear protection sector and aerospace fire-blocking applications in Northern Europe drive specification-grade offtake.
- Blend Aramid:Hybrid formulations balance cost and performance for industrial safety textiles where pure para-aramid economics exclude adoption.
- Others:Copolymer variants and modified aromatic polyamides serve niche electrical insulation applications in Central European automotive wiring harness production.
Leading the category by volume: Para-Aramid. Expanding most quickly: Meta-Aramid.
End User:
Customer-type segmentation reveals procurement concentration among state-funded defense programs versus dispersed industrial purchasing with shorter qualification cycles.
- Aerospace:Automated fiber placement systems at Airbus and Safran manufacturing sites in France and Germany consume specification-grade prepreg forms. Northern European procurement of composite reinforcements is accelerating as tier-one suppliers adopt labor-efficient layup technologies.
- Military:Ballistic protection systems under NATO standardization protocols mandate para-aramid with batch-level certification data. Germany's defense procurement office anchors continental demand for helmet and vehicle armor inserts.
- Automotive:Lightweight composite driveshafts and brake friction materials absorb meta-aramid volumes as EU Green Deal emissions benchmarks tighten material specifications.
- Electronics:Electrical insulation for high-voltage cables and transformer wraps draws staple fiber forms from Central European wire harness manufacturers.
Dominating procurement value: Aerospace. Gaining share fastest: Military.
Form:
Margin structure inverts across this category, with prepreg capturing widening premiums while staple fiber competes on throughput scale.
- Filament:Continuous spun yarns serve ballistic fabric weaving and composite roving applications where tensile integrity cannot tolerate fiber discontinuity.
- Staple Fiber:Cut-length discontinuous fibers blend with other polymers for thermal insulation felts and friction materials in automotive brake pad production.
- Fabric:Woven and knitted textiles undergo multi-stage finishing for flame-resistant garments certified under CE marking protocols for European emergency services.
- Prepreg:Resin-impregnated unidirectional sheets command specification premiums from aerospace tier-one suppliers seeking automated fiber placement compatibility.
Highest margin capture: Prepreg. Steepest volume expansion: Fabric.
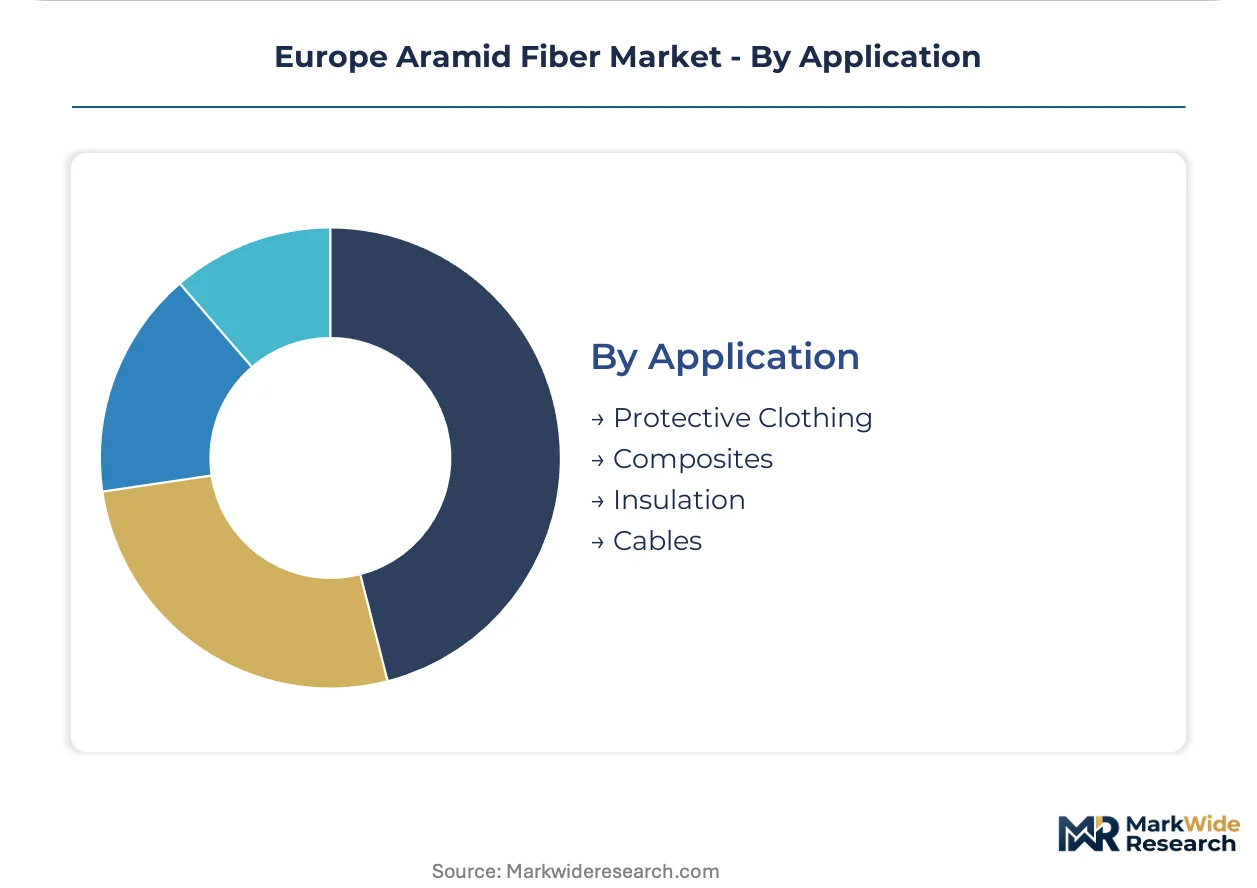
Application:
Application segmentation tracks regulatory enforcement intensity, with personal protective equipment mandates creating artificial demand floors absent in discretionary composite markets.
- Protective Clothing:Firefighter turnout gear and industrial thermal suits require meta-aramid purity grades certified under EU Personal Protective Equipment Regulation third-party verification protocols.
- Composites:Structural reinforcement in aerospace primary structures and automotive driveshafts absorbs para-aramid prepreg volumes where strength-to-weight ratios justify premium positioning.
- Insulation:Electrical and thermal barrier applications in power generation and chemical processing facilities consume meta-aramid staple and fabric forms.
- Cables:High-voltage electrical insulation for offshore wind and grid infrastructure draws filament and paper forms from Dutch and German polymerization assets.
Largest installed base: Protective Clothing. Climbing the fastest: Composites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
P-Phenylenediamine feedstock availability from German chemical complexes anchors European para-aramid polymerization. The Ruhr industrial corridor concentrates spinning capacity alongside ballistic protection manufacturing clusters. REACH compliance costs and EU Green Deal carbon border adjustments reshape sourcing decisions across continental supply chains.
Germany
Ballistic protection systems for military and law enforcement absorb specification-grade para-aramid volumes. The EU Green Deal's industrial emissions benchmarks tighten material specifications for automotive composite suppliers. The Ruhr corridor hosts concentrated polymerization and spinning operations facing feedstock cost volatility.
Netherlands
Teijin Aramid B.V. anchors regional para-aramid supply through integrated polymerization assets. ECHA's evolving REACH substance restrictions demand extended toxicity dossiers for aromatic amine precursors. Eindhoven-area manufacturing sites pilot chemical depolymerization for production scrap recovery.
France
Nuclear protection protocols and aerospace fire-blocking applications drive meta-aramid purity grade demand. CE marking under the Personal Protective Equipment Regulation mandates third-party certification for flame-resistant garments. Airbus and Safran manufacturing sites in Toulouse and Hamburg coordinate automated fiber placement procurement.
United Kingdom
Defense procurement under NATO standardization protocols sustains para-aramid offtake for vehicle armor and helmet inserts. The UK's post-BREXIT chemical regulatory framework diverges from REACH timelines, creating compliance documentation burdens. Northern England textile clusters adapt weaving capacity for ballistic fabric production.
Poland
Chemical processing and power generation facilities remain underpenetrated for meta-aramid thermal protection applications. EU circular economy implementation timelines create entry points for closed-loop feedstock technologies. Warsaw-area industrial zones attract secondary processing investments from Western European fiber distributors.
Europe Aramid Fiber Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty purification and recycling adjacent spaces. The vendor base concentrates around integrated polymerization assets with captive precursor supply, while smaller spinning operations fragment across regional textile clusters. Two archetypes dominate: specification-grade defense contractors with captive testing laboratories, and industrial meta-aramid specialists serving nuclear and chemical protection protocols. Competitive moves center on hydrogen infrastructure alignment for energy cost reduction and chemical depolymerization technology licensing for circular economy positioning.
Within the integrated multinational tier, DuPont and Teijin Aramid B.V. exemplify archetypes of upstream-controlled supply chains. Kermel occupies a position between bulk para-aramid and commodity flame-retardant alternatives, representing the specialty purity grade segment. These three anchors illustrate how geographic concentration of polymerization assets—American, Dutch, and French respectively—shapes competitive access to European defense and aerospace procurement channels without requiring dispersed manufacturing footprints.
| Leading Market Players |
|---|
| DuPont |
| Teijin Aramid B.V. |
| Hyosung |
| Toray Industries Inc. |
| Kermel |
| Huvis |
| YF International bv |
| Kolon Industries Inc. |
| DuPont de Nemours, Inc. |
| Others |
Supply & Pricing Matrix
Chemical depolymerization pilot programs at Eindhoven-area manufacturing sites are compressing virgin precursor requirements while redistributing cost structures across polymerization and spinning stages. This technology shift simultaneously reduces feedstock import exposure and concentrates margin capture among integrated producers with captive recovery capabilities.
Pricing Analysis
Warranty and certification bundling now separates specification-grade para-aramid from unbundled industrial meta-aramid tiers. Three-tier pricing structure across premium, standard, and economy levels reflects batch-traceable ballistic certification, CE marking compliance, and volume scale respectively. Cost compression in standard-grade meta-aramid is intensifying because of methylene diphenyl diisocyanate formulation scrutiny under REACH. Automotive composite buyers exhibit highest price sensitivity, while defense procurement offices prioritize specification adherence over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from NATO standardization protocols mandate multi-supplier qualification for ballistic-grade para-aramid, fragmenting contract awards across Dutch and German polymerization assets. Geographic supply concentrates in the Netherlands, Germany, and France. Raw material dependencies center on p-phenylenediamine, terephthaloyl chloride, and methylene diphenyl diisocyanate. Single-source vulnerability persists at Netherlands-based polymerization facilities. Distribution runs through aerospace tier-one suppliers and defense procurement offices with extended qualification cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Aramid Fiber Market sits in a technology-transition phase as chemical depolymerization methods displace virgin precursor dependence for circular economy compliance.
For Market Incumbents: Hedge against ultra-high molecular weight polyethylene substitution in select ballistic applications by deepening backward integration into p-phenylenediamine production and accelerating hydrogen infrastructure alignment for polymerization energy cost reduction. Secure captive testing laboratory accreditation to defend specification-grade contract access against emerging spinning operations. For New Entrants and Emerging Players: Capture underpenetrated meta-aramid thermal protection demand in Poland and Czech Republic chemical processing facilities where EU circular economy mandates create entry points for closed-loop feedstock technologies. Pursue joint development agreements with Eastern European power generation OEMs lacking incumbent supplier relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty purity grade producers occupying positions between bulk para-aramid and commodity flame-retardant alternatives. Long-term viability favors assets with integrated polymerization and captive precursor supply. Watch ECHA substance authorization timelines as inflection indicators for formulation flexibility compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive p-phenylenediamine supply insulates Teijin and DuPont from feedstock volatility under REACH pressures. |
| Hydrogen Infrastructure Alignment | German national pipeline plans could reduce polymerization energy costs for Ruhr corridor facilities. |
| Chemical Depolymerization Licensing | Distributed scrap recovery aligns Airbus and Safran manufacturing with EU circular economy implementation timelines. |
| CE Marking Certification Investment | Third-party verification capability concentrates contract awards among producers with in-house testing laboratories. |
| Eastern European Distribution Expansion | Warsaw-area industrial zones attract secondary processing investments for underpenetrated meta-aramid applications. |
Research Methodology
Trade databases, ECHA substance registration filings, and aerospace procurement records formed the secondary backbone for this analysis. Primary interviews with polymerization plant managers, defense procurement officers, and aerospace tier-one supplier technical directors validated capacity and demand assumptions. Bottom-up and top-down triangulation reconciled fiber production volumes against end-use consumption patterns.
Analytical lenses combined bottom-up segmentation modeling with top-down macroeconomic anchoring across the projection horizon. Segmentation dimensions included product type tier, end-use industry, form factor, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for hydrogen infrastructure development and REACH authorization timeline risks. Industry-specific forecast inputs incorporated automated fiber placement adoption rates and ballistic protection procurement cycles.
The model holds under stable REACH substance authorization timelines and continued EU Green Deal implementation; deviation in ECHA restriction severity or hydrogen infrastructure deployment pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Global Synthetic Spider Silk Market
Synthetic Fibers
Bio-Based Elastic Core-Spun Yarn for Denim Stretch Market
Synthetic Fibers
Asia-Pacific Lyocell Fibers Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Melt Spun Fibers Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Kevlar Fiber Market
Synthetic Fibers
Extruded PLA Fiber Market
Synthetic Fibers
Fiberglass Roving Market
Synthetic Fibers
Anti-Static Fibers Market
Synthetic Fibers
Fiber Blends Market
Synthetic Fibers
High Temperature Fiber Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
Carbon Fiber Strands Market