
 Glass Fiber Yarn Market | 2026-2036
Glass Fiber Yarn Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Fiber Yarn Market Foresight
Software-defined tensile monitoring and predictive maintenance subscriptions is broadening what composite fabricators purchase alongside raw yarn. Owens Corning leverages its North American logistics network to sustain just-in-time delivery for aerospace tier-one suppliers. China Jushi Co., Ltd. anchors global cost competitiveness through captive melt furnaces and integrated boron-free E-glass formulations. Taishan Fiberglass differentiates via specialized S-glass output for defense contractor specifications.
Glass fiber yarn consists of continuous filaments drawn from molten silica-alumina-borosilicate glass, typically ranging from 5 to 24 micrometers in diameter, and serves as the reinforcing backbone for polymer matrix composites requiring high strength-to-weight ratios. E-glass dominates volume throughput due to its cost-performance balance in construction and marine applications, while S-glass commands premium positioning in aerospace and defense end uses where tensile modulus thresholds exceed 86 GPa. Direct roving technology leads manufacturing efficiency for automated fiber placement, though braided yarn configurations are gaining traction in complex-curvature sports equipment fabrication.
EPA emissions guidelines and OSHA workplace exposure limits shape binder formulation choices and furnace operating permits for US-based producers, while REACH registration requirements in Europe restrict certain boron and fluorine compounds in glass melt recipes. China's GB standards and MIIT industrial policy directives govern domestic capacity expansion timelines and energy intensity benchmarks for new filament drawing installations. Stakeholders must monitor evolving dual carbon goals in China and potential EU carbon border adjustments that could restructure competitive cost hierarchies across supply regions.
Market Dynamics
Wind blade manufacturers are pulling high-modulus E-glass and S-glass yarn into longer turbine designs, while Chinese furnace expansions by Jushi and CPIC are compressing regional cost curves and redirecting trade flows.
Growth Catalysts
- Wind energy blade scaling:Turbine OEMs are specifying high-modulus glass fiber yarn for 100+ meter rotor designs, creating filament diameter and tensile specification pull-through.
- REACH compliance deadlines:ECHA registration requirements for boron-reduced formulations are accelerating binder chemistry R&D across European compounders.
- China's dual carbon policy:MIIT energy intensity benchmarks for new drawing installations are filtering capacity toward integrated producers with captive melt capabilities.
Market Restraints
- Fluorine compound restrictions:REACH Annex XVII limitations on fluorinated processing aids are raising formulation costs for European yarn finish suppliers.
- Chinese supply concentration:Jushi, CPIC, and Taishan Fiberglass control over 60% of global E-glass filament capacity, creating single-source exposure for non-integrated fabricators.
- Carbon fiber substitution in aerospace:Toray and Hexcel tow products are displacing S-glass in primary structural applications above 200 GPa modulus thresholds.
Strategic Opportunities
- India infrastructure buildout:GFRP rebar mandates in coastal highway projects are opening specification windows for alkali-resistant E-glass yarn.
- Software-defined tensile monitoring:Predictive maintenance subscriptions bundled with yarn offtake are converging with automated fiber placement systems.
- EU carbon border adjustment mechanism:CBAM phase-in for imported aluminum and steel is creating competitive repositioning for glass-reinforced polymer alternatives in construction.
Industry Challenges
- Specialized furnace engineering talent:Boron-free E-glass melt chemistry and platinum-rhodium bushing design expertise is concentrated among retiring European and Japanese technical specialists.
- OSHA silica exposure compliance:Yarn sizing and chopping operations in US facilities face tightening permissible exposure limits for respirable crystalline silica, requiring capital-intensive ventilation retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Fiber Yarn Market |
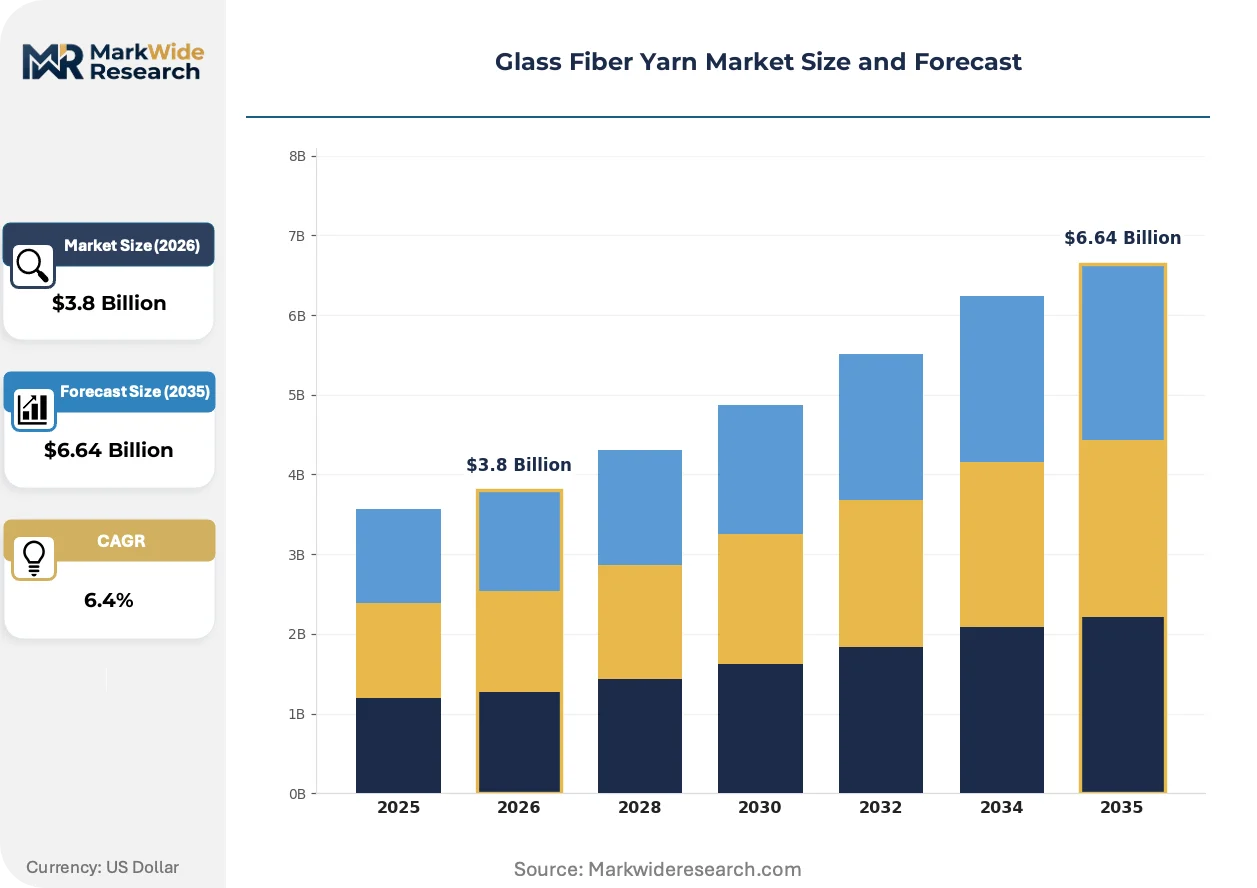
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: E-Glass, S-Glass, C-Glass, AR-Glass, R-Glass Technology: Direct Roving, Chopped Strand, Woven Roving, Braided Yarn Application: Composites, Construction Materials, Electrical Insulation, Textiles End User: Aerospace Manufacturers, Marine Fabricators, Sports Equipment Makers, Defense Contractors |
| Companies Covered | Owens Corning, China Jushi Co., Ltd., Chongqing Polycomp International Corporation, Saint-Gobain S.A., Nippon Electric Glass Co., Ltd., Taishan Fiberglass, CPIC, China Beihai Fiberglass Co., Ltd., Taiwan Glass Industry Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Fiber Yarn Market Shifts & Advancements
Digital thread technologies and predictive analytics are rewiring how fabricators specify, monitor, and pay for reinforcement materials across the value chain.
Direct roving automation is converging with robotic fiber placement systems in aerospace tier-one supplier networks. Boeing and Airbus structural subcontractors are adopting continuous filament feeding configurations that eliminate chopping and re-gathering steps. This convergence is compressing scrap rates and labor content in wing skin and fuselage barrel fabrication.
EPA emissions guidelines for hazardous air pollutants from glass melting furnaces are tightening stack monitoring and abatement requirements. US-based producers must install continuous emissions monitoring systems and demonstrate 99% destruction efficiency for volatile organic compounds from binder curing ovens. Small and mid-scale drawing operations in Ohio and South Carolina are consolidating or exiting rather than absorbing compliance capex.
Composite fabricators are unbundling yarn procurement from technical service contracts, pressuring traditional distributor margins. Tier-two boat builders and corrosion-resistant equipment manufacturers are sourcing direct from Chinese producers via bonded warehouse arrangements, bypassing North American master distributors. This channel compression is most visible in Florida marine clusters and Texas oilfield equipment fabrication yards.
Glass Fiber Yarn Market Segmentation
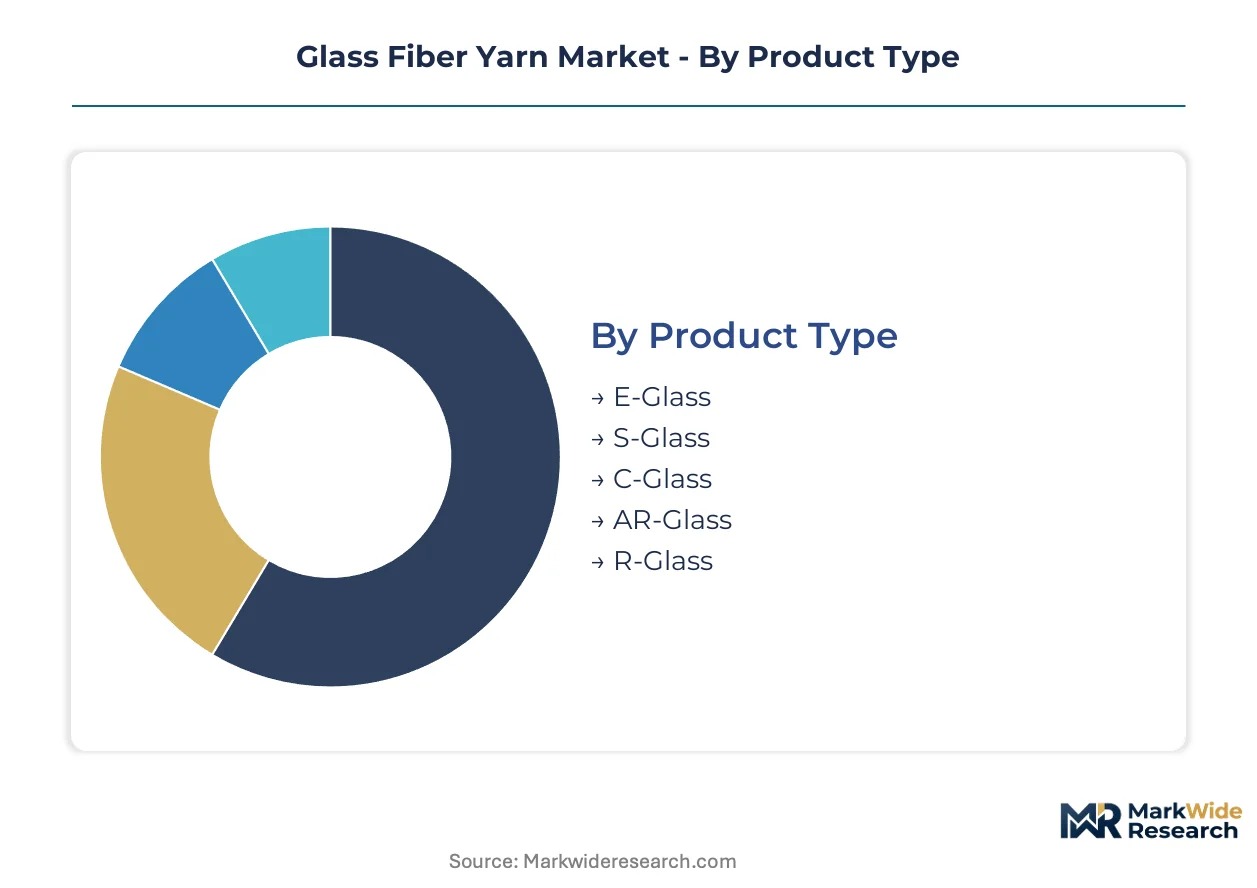
Glass fiber yarn segmentation reveals how technical specifications map to price-performance trade-offs across defense, wind energy, and infrastructure end uses. Understanding these splits enables fabricators to align melt chemistry investments with actual offtake concentration rather than assumed demand patterns.
Product Type:
E-Glass commands volume throughput while S-Glass captures margin premiums in modulus-critical applications.
- E-Glass:Continuous filaments drawn from silica-alumina-borosilicate glass with 5-24 micrometer diameters, delivering 72 GPa tensile modulus at the lowest cost per kilogram. Construction and marine fabricators in China absorb the majority of global E-glass filament output as domestic furnace expansions by Jushi and CPIC compress regional supply curves.
- S-Glass:Magnesia-alumina-silicate chemistry yielding 86+ GPa tensile modulus for primary structural applications where strength-to-weight thresholds exceed standard E-glass capabilities. Aerospace tier-one suppliers and defense contractors specify S-glass for missile radomes and pressure vessels despite 3-4x cost premiums over E-glass alternatives.
- C-Glass:Calcium-borosilicate formulation optimized for chemical resistance in corrosion-resistant equipment and battery box fabrication.
- AR-Glass:Zirconia-doped alkali-resistant grade specified for GFRP rebar in coastal highway infrastructure subject to chloride exposure.
- R-Glass:High-strength variant bridging E-glass cost structures with S-glass mechanical performance for wind blade spar cap applications.
Today's leader: E-Glass. Tomorrow's challenger: S-Glass.
Technology:
Manufacturing configuration determines labor content, scrap rates, and compatibility with automated fiber placement systems.
- Direct Roving:Continuous filament gathering eliminates intermediate chopping and re-gathering steps, feeding directly into robotic fiber placement heads for aerospace wing skin fabrication. Boeing and Airbus structural subcontractors specify direct roving to compress scrap rates below 3% in fuselage barrel production.
- Chopped Strand:Filaments cut to 3-50mm lengths and coated with sizing chemistry for thermoplastic compounding and sheet molding compound applications. Automotive underbody shield manufacturers specify chopped strand for compression molding cycles under 90 seconds.
- Woven Roving:Bidirectional fabric construction providing multi-axial reinforcement for hand lay-up and vacuum infusion in boat hull fabrication.
- Braided Yarn:Interlaced filament architecture conforming to complex curvature in hockey sticks, fishing rods, and bicycle frame joints.
Direct roving anchors aerospace procurement; braided configurations gain fastest in sports equipment specification.
Application:
End-use requirements for fire resistance, dielectric performance, and tensile modulus dictate glass chemistry and filament diameter selection.
- Composites:Polymer matrix reinforcement for structural components requiring high specific strength across transportation and industrial equipment. Wind blade manufacturers pull high-modulus E-glass and S-glass yarn into 100+ meter rotor designs, creating filament diameter and tensile specification pull-through.
- Construction Materials:GFRP rebar, geogrids, and facade panels replacing steel and aluminum in corrosive environments. India's coastal highway mandates specify alkali-resistant E-glass for rebar applications in marine exposure zones.
- Electrical Insulation:High-purity E-glass formulations with controlled alkali content for transformer boards and printed circuit substrate cores.
- Textiles:Fine-diameter filament weaving for filtration fabrics and thermal insulation blankets in industrial process equipment.
Composites dominate filament consumption; construction materials expand most quickly on infrastructure replacement cycles.
End User:
Customer technical sophistication determines whether procurement flows through master distributors or direct mill relationships.
- Aerospace Manufacturers:Tier-one suppliers to Boeing and Airbus requiring lot traceability, statistical process control documentation, and just-in-time delivery windows. Owens Corning leverages its North American logistics network to sustain JIT delivery for aerospace structural subcontractors.
- Marine Fabricators:Boat builders and corrosion-resistant tank manufacturers sourcing via bonded warehouse arrangements to bypass distributor markups. Florida marine clusters and Texas oilfield equipment yards increasingly source direct from Chinese producers.
- Sports Equipment Makers:Bicycle, hockey stick, and fishing rod manufacturers specifying braided yarn configurations for complex-curvature fabrication.
- Defense Contractors:Prime contractors and subcontractors requiring S-glass output meeting MIL-SPEC tensile modulus and filament diameter tolerances. Taishan Fiberglass differentiates via specialized S-glass production for defense contractor specifications.
Defense contractors sustain premium pricing; marine fabricators drive channel compression fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's furnace expansions are compressing regional cost curves faster than US producers can retrofit emissions abatement systems, while European compounders absorb REACH compliance premiums that Asian competitors largely bypass.
United States
Wind blade manufacturers in Iowa and Texas are pulling high-modulus E-glass and S-glass yarn into 100+ meter rotor designs. EPA emissions guidelines for hazardous air pollutants from glass melting furnaces are tightening stack monitoring and abatement requirements. Small and mid-scale drawing operations in Ohio and South Carolina are consolidating or exiting rather than absorbing compliance capex.
China
Domestic capacity additions by Jushi and CPIC are reshaping regional supply availability and redirecting trade flows across Asia. MIIT energy intensity benchmarks for new drawing installations are filtering capacity toward integrated producers with captive melt capabilities. The Yangtze River Delta and Shandong Peninsula host concentrated filament drawing clusters serving wind energy and electronics end uses.
Germany
Aerospace tier-one suppliers in Bavaria and Baden-Württemberg specify direct roving configurations to compress scrap rates below 3% in fuselage barrel production. ECHA registration requirements for boron-reduced formulations are accelerating binder chemistry R&D across European compounders. The Stuttgart industrial corridor sustains specialized furnace engineering expertise for boron-free E-glass melt chemistry.
India
GFRP rebar mandates in coastal highway projects are opening specification windows for alkali-resistant E-glass yarn in Maharashtra and Gujarat. BIS standards govern domestic quality certification for construction-grade fiberglass reinforcement. The Delhi-Mumbai Industrial Corridor is attracting bonded warehouse arrangements for direct mill procurement from Chinese producers.
Japan
Electronics substrate manufacturers in Kansai and Chubu regions require high-purity E-glass formulations with controlled alkali content for printed circuit board cores. METI industrial policy directives influence domestic capacity planning and energy efficiency benchmarks for filament drawing installations. The Nagoya manufacturing belt maintains precision filament diameter tolerances for aerospace and defense contractor specifications.
Glass Fiber Yarn Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated melt-to-yarn producers commanding cost advantages in volume-driven construction applications while specialized S-glass fabricators capture premium positioning in modulus-critical aerospace and defense end uses. The vendor base organizes around three strategic archetypes: captive furnace operators with backward integration into raw material supply, regional drawing specialists serving marine and corrosion-resistant equipment clusters, and technology licensors providing proprietary bushing designs and binder formulations. Capacity expansion and strategic partnerships represent the dominant competitive moves, as mid-scale producers seek scale efficiencies or technology access to defend position against Chinese supply concentration.
Among Chinese integrated producers, China Jushi Co., Ltd. and Chongqing Polycomp International Corporation exemplify the captive furnace archetype, while Owens Corning represents North American logistics-anchored positioning for aerospace tier-one supplier networks. Taishan Fiberglass occupies a specialist position within the S-glass premium tier serving defense contractor specifications.
| Leading Market Players |
|---|
| Owens Corning |
| China Jushi Co., Ltd. |
| Chongqing Polycomp International Corporation |
| Saint-Gobain S.A. |
| Nippon Electric Glass Co., Ltd. |
| Taishan Fiberglass |
| CPIC |
| China Beihai Fiberglass Co., Ltd. |
| Taiwan Glass Industry Corp. |
| Others |
Supply & Pricing Matrix
Platinum-rhodium bushing design expertise concentrated among retiring European and Japanese technical specialists widens labor-cost differentials between premium S-glass and economy E-glass tiers. This workforce scarcity amplifies price spreads as integrated Chinese producers capture margin through captive furnace operations while specialized Western fabricators absorb premium engineering premiums.
Pricing Analysis
Capacity additions in China are reshaping price floors across standard E-glass grades as Jushi and CPIC furnace expansions compress regional supply curves. Pricing stratifies across premium S-glass for aerospace modulus specifications, standard E-glass for construction and wind energy volume offtake, and economy C-glass for corrosion-resistant equipment. Price differentiation rests on certification grade for defense contractor MIL-SPEC compliance and geographic delivery cost for just-in-time aerospace tier-one networks. Cost compression in standard E-glass is intensifying because Chinese bonded warehouse arrangements bypass North American distributor markups. Marine fabricators in Florida and Texas oilfield equipment yards exhibit highest price sensitivity, while defense contractors sustain premium tolerance for lot traceability and statistical process control documentation.
Supply Chain Analysis
Scrap filament recovery and platinum-rhodium bushing refurbishment flows concentrate in Shandong Peninsula and Yangtze River Delta technical service clusters. Raw material sourcing draws from silica sand deposits in China's northern provinces, boron compounds subject to REACH Annex XVII restrictions, and alumina from Australian bauxite refining. Supply chain risk centers on single-source vulnerability for specialized S-glass melt chemistry expertise concentrated among retiring European and Japanese specialists. Distribution runs through bonded warehouse arrangements for direct mill procurement, bypassing traditional master distributor networks in North American marine clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass fiber yarn functions as a stable compounder anchored by wind blade scaling and infrastructure replacement cycles that sustain filament demand across economic conditions.
For Market Incumbents: Cement cost leadership through captive boron-free E-glass melt furnace integration and backward control over silica-alumina raw material supply. Carbon fiber substitution in aerospace primary structures above 200 GPa modulus thresholds threatens S-glass positioning, demanding accelerated R&D in R-glass formulations bridging E-glass cost structures with enhanced mechanical performance.
For New Entrants and Emerging Players: The 3-4x cost premium spread between S-glass and E-glass opens specification windows for R-glass and AR-glass intermediates in wind blade spar caps and coastal GFRP rebar applications. Target India's coastal highway infrastructure buildout where BIS certification requirements create barrier-filtered entry with lower capital intensity than Chinese furnace scale. Pursue bonded warehouse direct procurement partnerships with Maharashtra and Gujarat state project authorities.
For Investors and Strategic Acquirers: Wind energy OEMs and aerospace tier-one suppliers represent the most active acquirer category in this space, seeking captive filament supply security. Long-term viability favors integrated melt-to-yarn producers with MIIT-compliant energy intensity benchmarks and REACH-registered boron-reduced formulations. Monitor EPA stack monitoring enforcement intensity and EU carbon border adjustment mechanism phase-in for competitive repositioning signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica-Alumina Supply | Captive raw material sourcing anchors cost competitiveness against Chinese furnace expansions. |
| REACH-Registered Boron-Reduced Formulation Development | ECHA compliance accelerates binder chemistry R&D differentiation for European compounder supply. |
| Direct Roving Automation Convergence | Boeing and Airbus structural subcontractors specify continuous filament feeding to compress scrap rates below 3%. |
| Software-Defined Tensile Monitoring Subscription Bundling | Predictive maintenance convergence with automated fiber placement systems broadens fabricator procurement scope. |
| India Bonded Warehouse Direct Procurement Partnership | Delhi-Mumbai Industrial Corridor state projects bypass distributor markups for alkali-resistant E-glass yarn. |
Research Methodology
Bottom-up wind blade and aerospace composite modeling reconciled against top-down furnace capacity and trade flow tracking forms the analytical core of this study. Primary interviews with plant managers at integrated melt-to-yarn facilities, procurement leads at wind energy OEMs, distribution channel partners in marine clusters, and technical R&D directors at binder formulation specialists combined with secondary validation. Secondary sources include customs and trade data from major filament exporting jurisdictions, SEC 10-K filings from publicly traded glass manufacturers, MIIT industrial policy directives, and ECHA registration databases. Triangulation across these sources ensures filament diameter specification, tensile modulus thresholds, and regional cost curve positioning align with actual offtake patterns.
Input-output matrices map E-glass, S-glass, C-glass, AR-glass, and R-glass chemistry grades against wind energy, aerospace, construction, marine, and defense end-use applications across the projection horizon. Segmentation dimensions include product type chemistry, manufacturing technology configuration, application performance requirements, and end-user procurement sophistication. CAGRs derive from filament consumption intensity per megawatt of installed wind capacity, meter of GFRP rebar specified, and square meter of aerospace composite fabricated, cross-referenced against MIIT capacity expansion timelines and EPA emissions compliance capex absorption rates.
Caveats apply where Chinese dual carbon policy enforcement intensity, EU carbon border adjustment mechanism scope expansion, or fluorine compound restriction tightening could materially shift the outlook. Forecasts reflect assumptions regarding furnace engineering talent availability, boron-free E-glass melt chemistry scalability, and aerospace composite specification stability. Practitioners should monitor OSHA silica exposure limit revisions and REACH Annex XVII amendment proposals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Nylon Tire Cord Fabrics Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
Synthetic Textile Fiber Market
Synthetic Fibers
High End Synthetic Suede Market
Synthetic Fibers
Conductive Fibers Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
US Textile Market
Synthetic Fibers
Melt Spun Fibers Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
Long Fiber Thermoplastics Market
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
Anti-Static Fibers Market