
 Recycled Polyester (Rpet) Market | 2026-2036
Recycled Polyester (Rpet) Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Polyester (Rpet) Market Insights
Buyer concentration among large apparel brands is recalibrating procurement volumes across the rPET value chain. Indorama Ventures leverages its integrated PET resin platform to secure feedstock access across Southeast Asian recycling hubs. Unifi Inc. anchors its position through proprietary Repreve fiber technology, sustaining brand partnerships with performance-wear labels. Far Eastern New Century competes on filament-grade rPET capacity, dominating Taiwan's circular textile infrastructure.
Recycled polyester is polyethylene terephthalate reprocessed from post-consumer bottles or industrial waste, typically achieving intrinsic viscosity between 0.72 and 0.82 dL/g depending on re-polymerization conditions. Its primary purpose is to displace virgin fossil-based polyester in applications where mechanical properties and dye affinity must match conventional PET standards. Fiber-grade rPET leads volume throughput across the analysis window, though filament variants for technical textiles command superior margin pools. The automotive application segment is accelerating as seat fabric specifications harden around recycled content minimums, while granule formats for packaging face margin compression from competing bio-based polymers.
The EPA enforces recycled content thresholds in federal procurement under Buy Clean initiatives, while the EU Green Deal's circular economy action plan mandates extended producer responsibility for textile waste streams. China's MEE implements dual carbon goals that restrict virgin polyester capacity additions, redirecting investment toward chemical recycling infrastructure. Stakeholders must monitor feedstock traceability certification schemes and regional collection rate disparities to secure long-term polymer access.
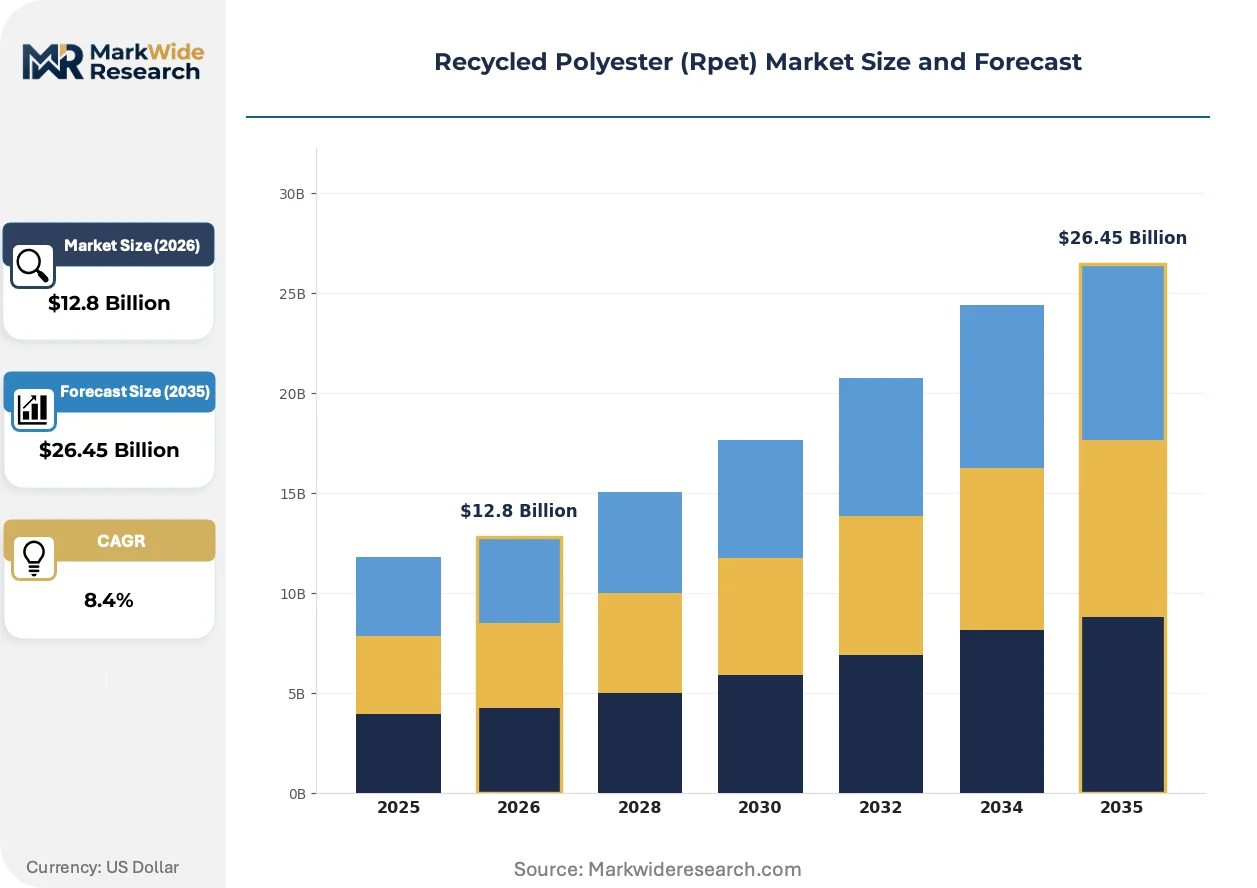
Market Dynamics
Brand-led procurement consolidation is compressing supplier margins while redirecting capital toward chemical recycling infrastructure. The EU Green Deal's extended producer responsibility mandates are forcing apparel manufacturers to secure certified rPET feedstock through long-term offtake agreements.
Growth Catalysts
- EU F-Gas Regulation:Tightening restrictions on virgin polymer production pathways are accelerating chemical recycling investments across European textile clusters.
- Automotive seat fabric mandates:Tier-1 suppliers are embedding recycled content minimums into technical textile specifications for interior applications.
- China's dual carbon goals:MEE restrictions on virgin polyester capacity additions are redirecting capital toward depolymerization infrastructure in Zhejiang and Jiangsu provinces.
Market Restraints
- Feedstock cost volatility:Post-consumer bottle collection rates fluctuate with oil-price-driven virgin PET spreads, squeezing mechanical recyclers during crude downturns.
- Collection infrastructure gaps:Southeast Asian hubs lack standardized curbside programs, forcing reliance on informal waste picker networks with traceability limitations.
- Intrinsic viscosity degradation:Mechanical recycling processes cap rPET at fiber-grade applications, blocking penetration into high-performance bottle-to-bottle loops.
Strategic Opportunities
- India's PLI scheme:Textile sector incentives are attracting chemical recycling investments to Tamil Nadu and Gujarat manufacturing corridors.
- Bio-based hybrid formulations:rPET blended with bio-PTA feedstocks is opening premium positioning in luxury apparel where carbon accounting transparency commands price premiums.
- Blockchain traceability platforms:Digital product passports are enabling direct brand-to-recycler contracting, disintermediating traditional resin traders.
Industry Challenges
- Depolymerization engineering talent:Chemical recycling scale-up is constrained by scarce process engineers with polyethylene terephthalate pyrolysis experience.
- GRS certification timelines:Multi-month audit backlogs at accredited bodies are delaying brand onboarding of new suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Polyester (Rpet) Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Fiber, Granule, Filament Application: Apparel, Upholstery, Automotive, Non-woven End User: Textile Industry, Packaging Industry, Automotive Sector, Consumer Goods Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Indorama Ventures, Unifi Inc., Reliance Industries Limited, Alpek Polyester, Far Eastern New Century, Sinopec Yizheng Chemical Fibre, Toray Industries, Zhejiang Jiaren New Materials, Polyfibre Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Polyester (Rpet) Market Trends and Innovations
Technology trajectories in rPET are bifurcating between mechanical efficiency gains and chemical recycling breakthroughs. Regulatory pressure is compressing the timeline for commercializing bottle-to-bottle quality regeneration.
Enzymatic depolymerization is converging with continuous processing reactor designs to lower energy intensity in rPET regeneration. Performance-wear labels in Germany and Japan are piloting fiber-to-fiber closed loops. This convergence is compressing the cost gap between virgin and recycled resin for food-contact applications.
REACH restrictions on microplastic shedding are forcing filament producers to reformulate yarn surface treatments. The EU Green Deal's textile strategy is accelerating testing protocols for synthetic fiber fragmentation. Outdoor apparel brands are responding by sourcing filament-grade rPET with modified cross-section geometries that reduce shedding rates during washing cycles.
Long-term offtake contracting is displacing spot market purchasing among large apparel groups. Direct partnerships between brands and chemical recyclers are eliminating resin trader margins. This pattern is most visible in Vietnam and Bangladesh, where vertically integrated textile mills are securing dedicated rPET flake supply from regional bottle-to-fiber processors.
Recycled Polyester (Rpet) Market Segmentation
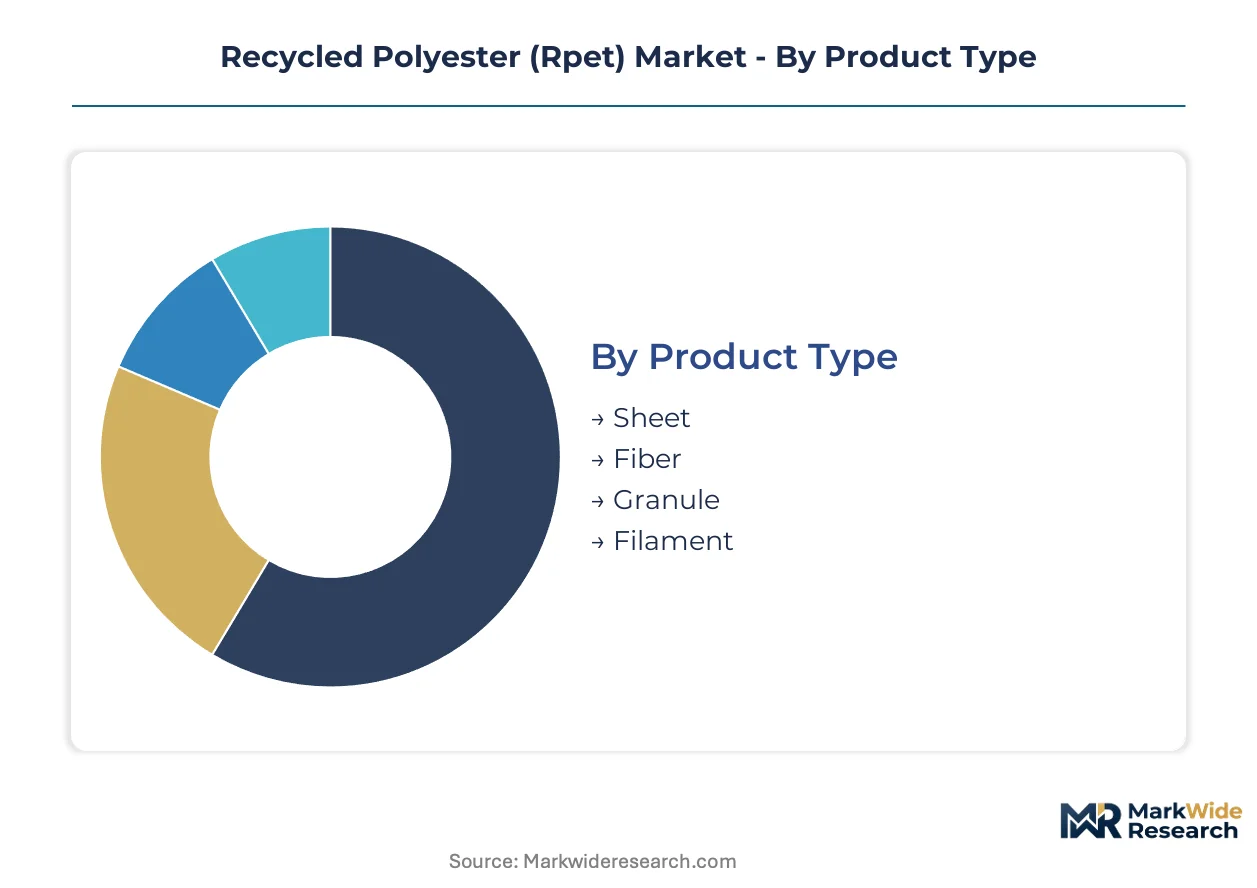
rPET segmentation reveals how polymer form factors and channel structures determine margin capture. Fiber and filament variants integrate directly into textile manufacturing, while granule formats serve as standalone feedstock for converters. Understanding these integration patterns exposes where pricing power concentrates across the value chain.
Product Type:
Integration depth varies sharply: fiber and filament embed directly into spinning operations, while sheet and granule formats require downstream conversion before end-use.
- Fiber:Staple fiber with denier ranges from 1.2 to 15 D dominates mechanical recycling output. Apparel brands in Vietnam and Bangladesh specify fiber-grade rPET for blended yarn production to meet EU Green Deal textile waste mandates.
- Filament:Continuous filament yarn achieves tenacities exceeding 4.5 g/d through solid-state polymerization. Automotive seat fabric specifications in Germany and Japan now embed recycled content minimums that favor filament-grade supply from Taiwan-based producers.
- Granule:Pelletized rPET serves as feedstock for packaging converters and injection molders.
- Sheet:Extruded sheet formats target thermoforming applications with lower viscosity requirements.
Fiber leads volumes today; filament is gaining share fastest.
Application:
Cost tier stratification separates premium-positioned automotive specifications from commoditized non-woven absorbents.
- Apparel:Performance-wear labels specify rPET for moisture-wicking base layers and outerwear shells. China's MEE dual carbon restrictions redirect virgin polyester investment toward chemical recycling capacity serving Zhejiang apparel clusters.
- Automotive:Tier-1 interior suppliers embed 30-50% recycled content minimums into seat fabric and headliner specifications. REACH microplastic shedding protocols are forcing reformulation of yarn surface treatments for European vehicle programs.
- Upholstery:Residential and commercial furniture applications prioritize cost-competitive staple fiber.
- Non-woven:Disposable hygiene and filtration applications absorb lower-grade mechanical recycling output.
Apparel commands absolute volume; automotive is climbing the fastest on value per kilogram.
End User:
Customer type determines contract structure: textile mills secure long-term offtake, while packaging converters buy spot.
- Textile Industry:Vertically integrated spinning-weaving-dyeing operations in Tamil Nadu and Gujarat source flake directly from regional bottle processors. India's PLI scheme incentives are accelerating chemical recycling investments to serve these manufacturing corridors.
- Automotive Sector:Just-in-time delivery requirements force Tier-1 suppliers into dedicated rPET supply agreements with certified traceability. ECHA restrictions on synthetic fiber fragmentation are hardening technical specifications for interior applications.
- Packaging Industry:Food-contact bottle applications face FDA and EFSA regulatory barriers to mechanical recycling routes.
- Consumer Goods:Brand owners in personal care and electronics accessories specify rPET for sustainability marketing claims.
Textile Industry leads volumes today; Automotive Sector is expanding most quickly on contract premiums.
Distribution Channel:
Supply concentration shapes channel choice: direct sales dominate large-volume textile contracts, while wholesale intermediaries serve fragmented packaging converters.
- Direct Sales:Brand-to-recycler contracting eliminates resin trader margins through blockchain-traceable digital product passports. Unifi Inc. and Far Eastern New Century anchor their positions through proprietary fiber technology partnerships with performance-wear labels.
- Wholesale:Regional resin traders aggregate flake supply from multiple mechanical recyclers for small-batch converters.
- Online:Spot market platforms facilitate price discovery for standardized granule grades.
- Retail:Limited to specialty sustainable materials boutiques serving craft and small-batch producers.
Direct Sales leads volumes today; Online is gaining share fastest on price transparency tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed rPET capacity worldwide, while Vietnam scales chemical recycling infrastructure at roughly twice the speed of neighboring Southeast Asian hubs. This divergence reflects how regulatory stringency and manufacturing cluster density reshape investment flows across the value chain.
China
Textile mills in Zhejiang and Jiangsu provinces absorb the majority of domestic fiber-grade rPET output. The MEE enforces dual carbon goals that cap virgin polyester expansion, redirecting capital toward depolymerization plants. Chemical recyclers in Shaoxing and Suzhou are commissioning enzymatic facilities to serve EU-bound apparel contracts.
United States
Automotive seat fabric mandates from Tier-1 suppliers in Detroit and South Carolina drive filament-grade demand. The EPA administers Buy Clean procurement thresholds that embed recycled content minimums in federal purchasing. Mechanical recyclers in the Southeast are expanding flake capacity to capture post-consumer bottle streams from municipal programs.
Germany
Performance-wear labels in Bavaria pilot fiber-to-fiber closed loops with certified traceability. ECHA enforces REACH restrictions on microplastic shedding that force yarn surface reformulation. Technical textile producers in Baden-Württemberg are qualifying rPET filament for premium automotive interior programs.
India
Vertically integrated spinning operations in Tamil Nadu and Gujarat source flake directly from regional bottle processors. The PLI scheme for textiles attracts chemical recycling investment to manufacturing corridors. Depolymerization projects in Coimbatore and Surat target export-grade chip production for EU apparel brands.
Vietnam
Export-oriented garment factories in Ho Chi Minh City and Binh Duong specify rPET blends to meet EU Green Deal textile waste mandates. Informal waste picker networks supply feedstock with traceability gaps that blockchain platforms attempt to close. Chemical recycling joint ventures in Dong Nai province target bottle-to-bottle quality for food-contact applications.
Recycled Polyester (Rpet) Market Competitive Landscape
Thai and Taiwanese producers anchor the integrated resin-fiber tier; US and Japanese specialists hold differentiated positions in branded fiber technology. The vendor base stratifies between commodity-scale mechanical recyclers and proprietary technology licensors. Three archetypes dominate: integrated petrochemical conglomerates with backward bottle-collection control, specialty fiber producers with brand-certified traceability platforms, and regional mechanical recyclers serving spot-market converters. Capacity expansion and long-term offtake contracting constitute the dominant competitive moves.
Within the integrated conglomerate tier, Indorama Ventures and Far Eastern New Century exemplify scale-driven positioning through captive feedstock access across Southeast Asian recycling hubs. Unifi Inc. occupies a differentiated niche as a specialty fiber producer with proprietary technology partnerships. These three entities represent how geographic concentration and technology differentiation split competitive advantage in rPET supply.
| Leading Market Players |
|---|
| Indorama Ventures |
| Unifi Inc. |
| Reliance Industries Limited |
| Alpek Polyester |
| Far Eastern New Century |
| Sinopec Yizheng Chemical Fibre |
| Toray Industries |
| Zhejiang Jiaren New Materials |
| Polyfibre Industries |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal extended producer responsibility mandates gate both qualified supply and premium-tier pricing access for recycled polyester, as certified traceability becomes a non-negotiable entry ticket for apparel brand procurement contracts. Buyers without GRS certification face automatic disqualification from EU-bound textile programs, compressing viable supplier pools and concentrating pricing power among accredited chemical recyclers.
Pricing Analysis
Capacity additions in Vietnam and India are reshaping price floors for fiber-grade rPET, intensifying cost competition among Southeast Asian mechanical recyclers. Three-tier pricing structure across premium filament, standard fiber, and economy granule levels stratifies by certification grade and intrinsic viscosity specifications. Pricing pressure stems from virgin PET spread compression during crude downturns, squeezing mechanical recyclers with fixed collection costs. Packaging converters exhibit highest price sensitivity, while automotive Tier-1 suppliers absorb premiums for traceability-guaranteed filament supply.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns, redirecting feedstock procurement toward Tamil Nadu and Gujarat manufacturing corridors. Supply concentrates in China, Vietnam, and India, with bottle flake flows drawing from informal waste picker networks across Southeast Asia. Raw material dependencies rest on post-consumer PET bottle collection rates, baled flake availability, and purified terephthalic acid pricing. Single-source vulnerability runs through China's Zhejiang chemical recycling cluster. Distribution runs through long-term offtake contracts between brand-certified recyclers and vertically integrated textile mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recycled polyester market reads as a late-cycle quality story, with specification premiums hardening around automotive seat fabric mandates and EU textile waste compliance requirements. Demand is shifting decisively toward filament-grade rPET with certified traceability, rewarding suppliers with chemical recycling capabilities and blockchain-verified digital product passports.
For Market Incumbents: Hedge feedstock exposure by securing backward integration into regional bottle collection networks across Vietnam and Indonesia, insulating margins from collection rate volatility. Accelerate enzymatic depolymerization capacity additions in Zhejiang and Jiangsu to capture automotive and food-contact premium tiers before technology diffusion erodes first-mover returns. Defensive consolidation around GRS-certified suppliers will accelerate as audit backlogs delay new entrant onboarding. For New Entrants and Emerging Players: Begin with India's PLI-incentivized chemical recycling corridor, where policy support and feedstock proximity create the most penetrable white-space for export-grade chip production. Target filament-grade supply for European automotive programs, where REACH microplastic protocols and recycled content minimums outpace incumbent capacity expansion. A go-to-market angle anchored to blockchain-traceable digital product passports enables direct brand contracting, disintermediating established resin traders. For Investors and Strategic Acquirers: Valuations sit cheapest among regional mechanical recyclers with informal feedstock networks and limited certification coverage, presenting consolidation targets for platform buildouts. Long-term viability over the next decade hinges on successful transition from mechanical to chemical recycling infrastructure, with enzymatic technology licensing as the critical capability differentiator. The signal to watch is automotive OEM adoption timelines for next-generation seat fabric specifications, which will determine premium-tier demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Depolymerization Scale-Up | Enables bottle-to-bottle quality regeneration for EU food-contact applications under EFSA scrutiny. |
| Backward Integration into Collection | Captures feedstock cost control across Southeast Asian informal waste picker networks. |
| Blockchain Traceability Platform | Supports GRS certification requirements for EU Green Deal textile waste compliance. |
| Long-Term Offtake Contracting | Locks in automotive Tier-1 demand under REACH microplastic shedding protocols. |
| Filament-Grade Capacity Expansion | Addresses premium specifications from German and Japanese performance-wear labels. |
Research Methodology
Multiple input streams — primary interviews with chemical recycling plant managers, apparel brand sustainability officers, and automotive Tier-1 procurement leads; secondary validation through customs trade data, SEC filings of listed polyester producers, and EU regulatory databases — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations captured operational realities across mechanical and chemical recycling facilities, while trade flow analysis traced bottle flake and chip movements between Southeast Asian collection hubs and textile manufacturing clusters.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation modeled by product form, application tier, end-user industry, and regional production hub. CAGRs were derived from supply-demand balance analysis incorporating capacity commissioning timelines, regulatory enforcement trajectories, and brand procurement commitment disclosures. Forecast inputs included virgin-to-recycled PET spread dynamics, enzymatic technology cost curves, and automotive recycled content specification adoption rates.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to EU Green Deal textile waste mandates, breakthroughs in competing bio-based polymer technologies, and geopolitical disruptions to Southeast Asian waste picker network operations. Forecasts reflect assumptions around chemical recycling engineering talent availability and GRS certification audit throughput. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled and Circular Textiles
United States Textile Recycling Market
Recycled and Circular Textiles
Post-Consumer Recycled Textiles Market
Recycled and Circular Textiles
Textile Recycling Market
Recycled and Circular Textiles
Recycle Yarn Market
Recycled and Circular Textiles
Reusable Period Panties Market
Recycled and Circular Textiles
Global Recycled Textiles Market
Recycled and Circular Textiles
Textile Waste Management Market
Recycled and Circular Textiles
Clothing Recycling Market
Recycled and Circular Textiles
PET Microfiber Fleece Garment Recycling Streams in Europe Market
Recycled and Circular Textiles
Automotive Seat Cover and Interior Textile Recycling in Europe Market
Recycled and Circular Textiles
Recycled Fibers Market
Recycled and Circular Textiles
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market
Recycled and Circular Textiles
Recycled Cotton Market
Recycled and Circular Textiles
Europe Textile Recycling Market