
 Neoprene Fabric Market | 2026-2036
Neoprene Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Neoprene Fabric Market Outlook
Capital-intensity divergence between integrated polymer producers and downstream fabric converters is unwinding traditional margin structures in neoprene supply chains. ARLANXEO leverages backward integration into chloroprene monomer production to sustain cost advantages across European and Asian markets. Monmouth Rubber & Plastics Corp. specializes in custom-calendered sheet goods, occupying niche medical and industrial channels where specification tolerance drives purchasing decisions.
Neoprene fabric denotes polychloroprene-based elastomeric sheets, typically 1.5–7 mm in thickness, manufactured through emulsion polymerization followed by vulcanization to impart oil resistance, thermal insulation, and tensile memory. Foam-grade neoprene leads volume consumption in diving and watersports applications where closed-cell buoyancy and thermal retention define functional performance. Solid sheet and coated variants command premium positioning in automotive gasket and aerospace seal segments where compression-set resistance and flame-retardant specifications govern material selection. Custom-finished goods capture disproportionate margin pools relative to raw material and semi-finished stages, reflecting specification engineering and lot-traceability requirements.
EPA oversight of chloroprene emissions in the United States and REACH substance restrictions in Europe are elevating compliance costs for neoprene manufacturers while accelerating substitution testing in sensitive applications. China's MEE enforcement of dual carbon goals is reshaping energy-intensive polymerization capacity decisions among domestic producers. Stakeholders must monitor regulatory divergence between jurisdictions to calibrate product portfolios and certification investments without assuming harmonized standards.
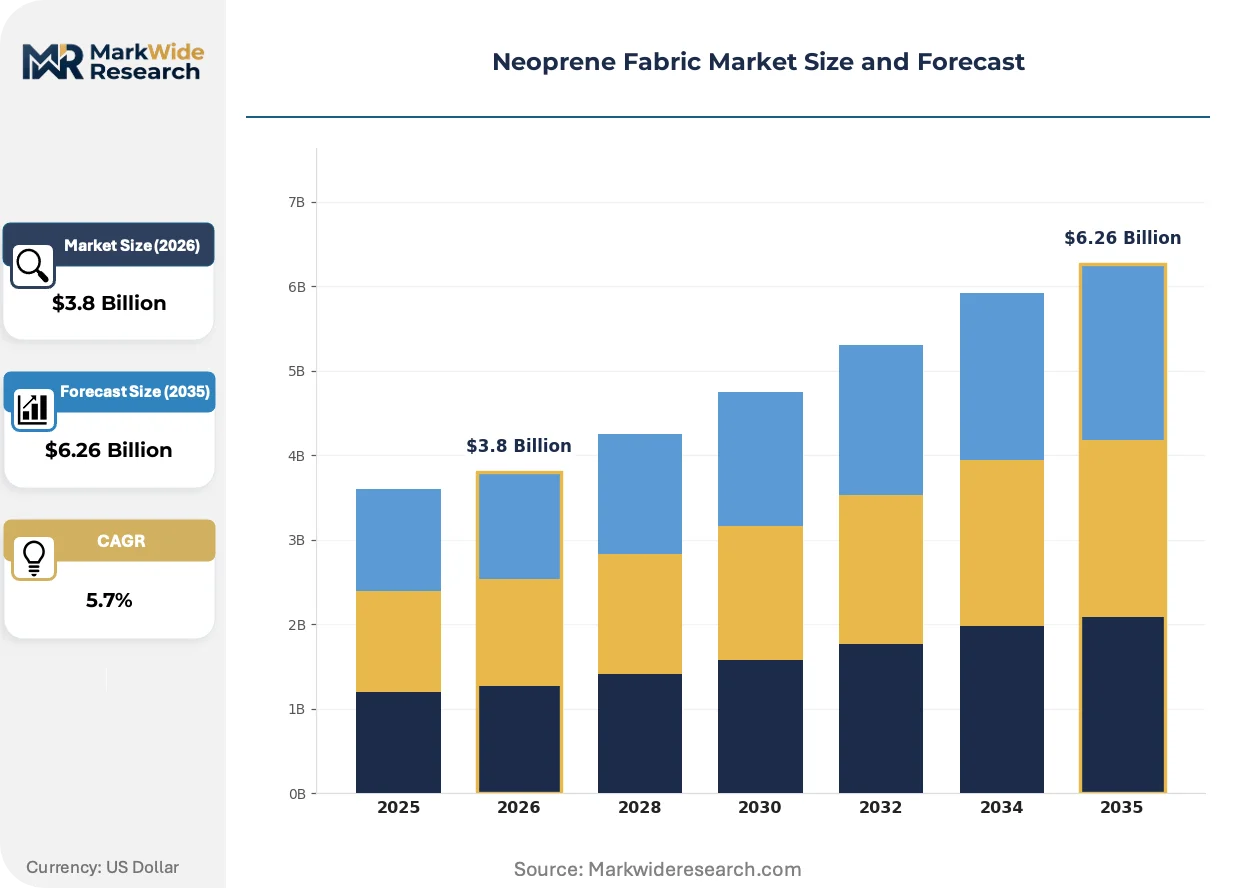
Market Dynamics
EPA chloroprene emission limits in Louisiana and Texas are forcing domestic manufacturers to reconfigure polymerization assets, while REACH substance restrictions in Europe accelerate substitution testing across medical-grade applications.
Growth Catalysts
- Watersports equipment procurement:Diving and surf apparel brands in Australia and California are expanding closed-cell foam orders for thermal retention performance.
- REACH SVHC disclosure mandates:European medical device manufacturers now require lot-traceable neoprene, creating specification premiums for compliant converters.
- China's dual carbon enforcement:MEE energy-intensity audits are consolidating polymerization capacity in Shandong and Zhejiang, tightening supply discipline.
Market Restraints
- Chloroprene monomer concentration:Over 60 percent of global chloroprene supply originates from integrated petrochemical complexes in China and Japan, creating geographic vulnerability.
- Natural rubber substitution:Guayule-derived bio-rubber from Arizona cultivation trials is displacing neoprene in select gasket applications where oil resistance is secondary.
- EPA compliance cost escalation:Louisiana facility upgrades to meet chloroprene emission caps are adding capital recovery premiums to domestic sheet goods.
Strategic Opportunities
- India industrial safety expansion:BIS certification requirements for protective equipment in Maharashtra and Gujarat chemical corridors are opening specification-grade demand.
- EU F-Gas Regulation phase-down:Blowing agent transitions in foam production are creating first-mover advantages for converters with HFO-compliant process lines.
- Digital textile printing integration:Sublimation-ready neoprene laminates are capturing premium positioning in custom wetsuit channels direct-to-consumer.
Industry Challenges
- Polymerization process engineering talent:Chloroprene production expertise concentrates among retiring cohorts at legacy US and European facilities.
- Multi-jurisdiction certification timelines:Simultaneous FDA, CE marking, and ISO 10993 biocompatibility testing for medical-grade sheets extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neoprene Fabric Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crumb Rubber, Solid Sheets, Foam, Coated Neoprene Application: Diving Suits, Wetsuits, Gaskets, Seals End User: Aerospace, Automotive, Medical, Sports Manufacturing Stage: Raw Material, Semi-Finished, Finished Goods, Custom Products |
| Companies Covered | Eastex Products, Inc., Voll Will Enterprise Co., Ltd., ARLANXEO, EKI, BRP Manufacturing, Macro International, West American Rubber Company, LLC., SEDO Chemicals Neoprene GmbH, Monmouth Rubber & Plastics Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neoprene Fabric Market Strategic Shifts
Material science advances and regulatory chemistry mandates are splitting neoprene production into divergent technical tracks, with sustainability specifications now dictating process investment priorities across converter networks.
Water-based adhesive lamination systems are displacing solvent-based bonding in European and North American finishing operations. Premium wetsuit brands in France and California have committed procurement volumes to aqueous polyurethane systems, eliminating VOC exposure in assembly. This transition is bifurcating the converter base between capitalized facilities with aqueous lines and legacy solvent-dependent operations facing stranded asset risk.
REACH restriction proposals for medium-chain chlorinated paraffins are extending to neoprene flame-retardant formulations. German automotive gasket suppliers are reformulating specifications to exclude restricted substances ahead of formal listing. Solid sheet producers serving Stuttgart and Wolfsburg supply chains are accelerating halogen-free alternative qualification programs.
Direct-to-brand procurement platforms are compressing traditional distributor markups in custom watersports channels. California and Queensland-based apparel labels now specify foam density and surface finish directly with Asian converters, bypassing regional wholesale intermediaries. Specification engineering services and rapid sampling capabilities are displacing inventory-holding as the core value proposition in these relationships.
Neoprene Fabric Market Segmentation
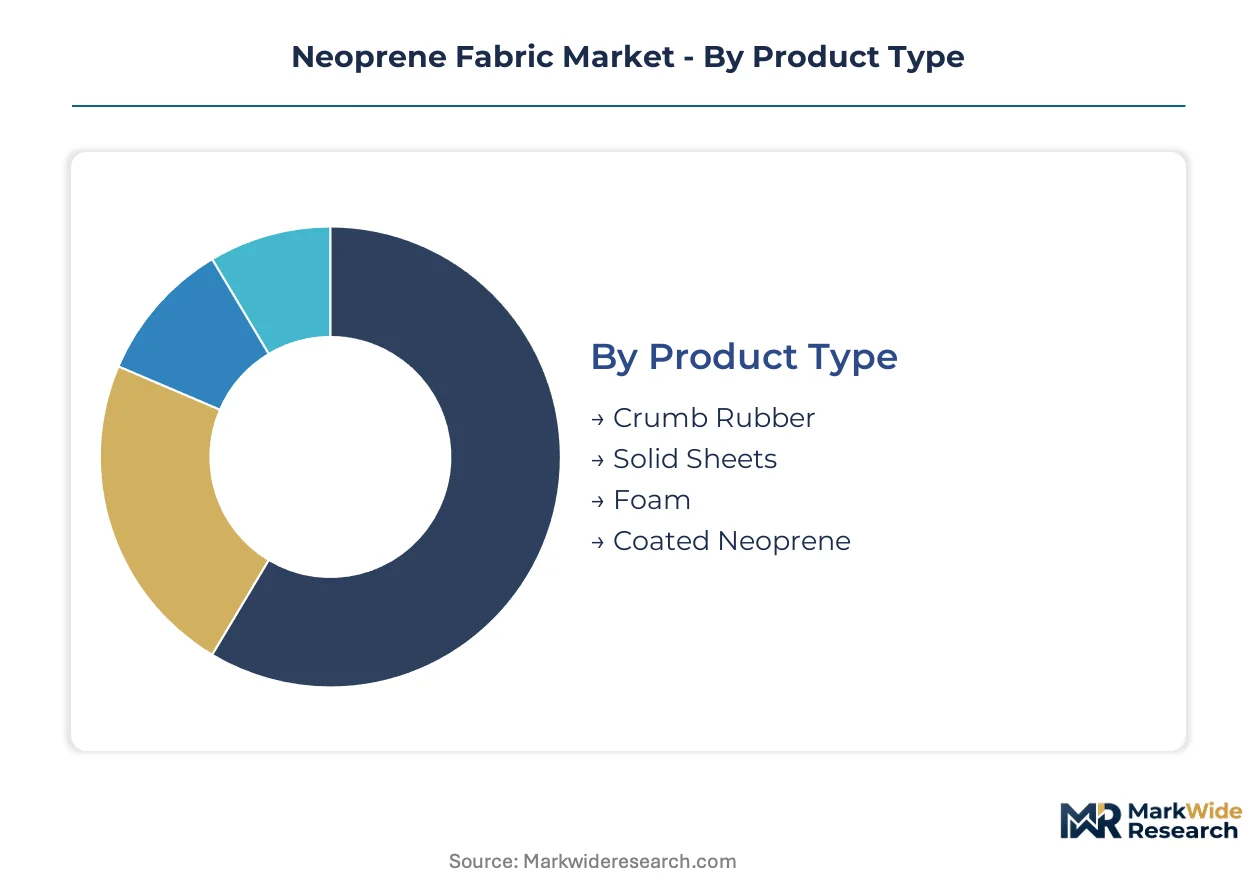
Neoprene fabric segmentation reveals divergent margin structures across the value chain, with custom-finished goods commanding premium positioning while raw material stages compete on chloroprene monomer cost. Specification engineering and lot-traceability requirements create distinct channel economics that reward converters with certification capabilities.
Product Type:
Foam-grade material flows primarily through watersports apparel channels, while solid sheet and coated variants serve industrial specification markets with longer qualification cycles.
- Foam:Closed-cell polychloroprene sheets deliver buoyancy and thermal retention through vulcanized emulsion polymerization. Australian and California diving brands are expanding procurement of 3–5 mm density grades for performance wetsuits, with REACH-compliant blowing agent formulations now mandatory for European export orders.
- Solid Sheets:Dense, non-cellular neoprene provides compression-set resistance for static sealing applications. Stuttgart and Wolfsburg automotive supply chains are accelerating halogen-free alternative qualification programs ahead of anticipated REACH restrictions on chlorinated paraffin flame retardants.
- Crumb Rubber:Recycled neoprene granules serve cost-sensitive industrial matting and vibration-dampening applications with lower specification tolerances.
- Coated Neoprene:Laminated surface treatments enhance chemical resistance for aerospace seal and medical device applications requiring biocompatibility certification.
By volume, foam leads consumption. By growth pace, coated neoprene is climbing the fastest on medical and aerospace specification demand.
Application:
Cost tier stratification separates recreational watersports from industrial sealing, with specification-grade medical and aerospace applications commanding 3–5x raw material multiples.
- Diving Suits:Thermal protection garments utilize 5–7 mm closed-cell foam with nylon or lycra laminates. Direct-to-brand procurement platforms in California and Queensland are compressing traditional distributor markups as apparel labels specify density and surface finish directly with Asian converters.
- Gaskets:Static seals for automotive and industrial equipment rely on solid sheet compression resistance. German automotive suppliers are reformulating specifications to exclude restricted substances ahead of formal REACH listing.
- Wetsuits:Surf and swim apparel employs thinner 1.5–3 mm foam grades with sublimation-ready surface treatments for digital textile printing integration.
- Seals:Dynamic sealing applications in aerospace and chemical processing demand fluoroelastomer-coated neoprene for extreme temperature and chemical exposure.
By volume, wetsuits and diving suits combined dominate. By margin capture, aerospace seals are expanding most quickly.
End User:
Customer type determines certification burden, with medical and aerospace sectors requiring simultaneous FDA, CE marking, and ISO 10993 testing that extends product launch cycles.
- Sports:Watersports equipment manufacturers in Australia and California represent the largest volume consumption segment, with procurement shifting toward aqueous adhesive lamination systems to eliminate VOC exposure.
- Automotive:Stuttgart supply chains drive specification-grade demand for gasket and seal applications, with reformulation mandates accelerating ahead of regulatory deadlines.
- Medical:Device manufacturers now require lot-traceable neoprene, creating specification premiums for compliant converters with ISO 13485 quality systems.
- Aerospace:Seal and insulation applications demand flame-retardant specifications governed by FAA and EASA certification requirements.
By volume, sports leads end-user consumption. By specification premium growth, medical is gaining share fastest.
Manufacturing Stage:
Margin pools concentrate disproportionately at finished and custom stages, reflecting engineering services and certification investments rather than commodity polymerization economics.
- Custom Products:Specification-engineered sheets with lot traceability and rapid sampling capabilities capture the highest value per kilogram. California and Queensland-based labels now bypass regional wholesale intermediaries through direct converter relationships.
- Finished Goods:Cut-and-sewn components and laminated assemblies serve medical device and watersports OEMs with documented compliance chains.
- Semi-Finished:Calendered sheet and block foam supply downstream converters, with Monmouth Rubber & Plastics Corp. occupying niche medical and industrial channels.
- Raw Material:Chloroprene monomer and unvulcanized polymer supply integrated producers like ARLANXEO with backward integration cost advantages.
By volume, semi-finished leads throughput. By value capture, custom products show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Australian and California watersports brands absorb specification premiums for REACH-compliant foam, while Indian industrial buyers prioritize cost-efficient grades for safety equipment. Chinese converters face margin compression from dual carbon enforcement even as export orders hold firm.
United States
EPA chloroprene emission caps in Louisiana and Texas are forcing polymerization asset reconfigurations. Domestic manufacturers face capital recovery premiums on sheet goods. California apparel labels now specify foam density directly with Asian converters, bypassing traditional wholesale intermediaries.
Germany
Stuttgart and Wolfsburg automotive supply chains drive halogen-free gasket reformulation ahead of anticipated REACH restrictions. German converters command specification premiums for lot-traceable medical-grade sheets. ECHA substance restriction proposals are accelerating substitution testing across flame-retardant formulations.
China
MEE energy-intensity audits are consolidating polymerization capacity in Shandong and Zhejiang provinces. Coastal manufacturing clusters supply both domestic apparel brands and export-oriented wetsuit producers. Dual carbon enforcement is tightening supply discipline among chloroprene monomer producers.
Australia
Queensland-based diving brands are expanding closed-cell foam procurement for thermal retention performance. Direct-to-brand platforms are compressing distributor markups as labels source directly from converters. TGA-equivalent certification requirements govern medical device applications.
India
BIS certification mandates for protective equipment in Maharashtra and Gujarat chemical corridors are opening specification-grade demand. Industrial safety expansion targets cost-sensitive segments where neoprene substitutes for natural rubber. Domestic converters lack REACH-equivalent traceability systems for export medical orders.
Neoprene Fabric Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the neoprene fabric value chain. Integrated polymer producers with backward integration into chloroprene monomer production compete on feedstock economics, while downstream converters compete on specification engineering and certification capabilities. Three archetypes dominate: petrochemical-integrated monomer suppliers, custom-calendered sheet specialists, and aqueous-adhesive laminators serving premium watersports channels. Competitive moves center on portfolio diversification into medical-grade certification and geographic expansion through direct-to-brand procurement platforms.
Among European-integrated producers, ARLANXEO anchors the monomer-supply tier with backward integration advantages across chloroprene production. Monmouth Rubber & Plastics Corp. occupies niche medical and industrial channels where specification tolerance drives purchasing decisions. California-based West American Rubber Company, LLC. exemplifies the custom-fabrication archetype serving specification-grade demand in aerospace and automotive sealing applications.
| Leading Market Players |
|---|
| Eastex Products, Inc. |
| Voll Will Enterprise Co., Ltd. |
| ARLANXEO |
| EKI |
| BRP Manufacturing |
| Macro International |
| West American Rubber Company, LLC. |
| SEDO Chemicals Neoprene GmbH |
| Monmouth Rubber & Plastics Corp. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Shandong polymerization facilities and Australian wetsuit brands lock in chloroprene monomer supply access while anchoring price visibility across volatile feedstock cycles. These arrangements insulate converters from spot market swings in naphtha-derived inputs yet embed fixed cost recovery obligations that resist downward price adjustment.
Pricing Analysis
After-sales certification maintenance and lot-traceability documentation drive lifetime value capture for REACH-compliant converters serving European medical device channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification status and blowing agent formulation compliance. Cost compression in foam-grade tiers is intensifying because MEE energy-intensity audits are raising polymerization overhead. Indian industrial safety buyers exhibit highest price sensitivity, while Stuttgart automotive gasket purchasers absorb specification premiums for halogen-free alternatives.
Supply Chain Analysis
China and Japan anchor global chloroprene monomer production through integrated petrochemical complexes in Shandong and coastal industrial zones. Downstream fabric conversion draws from naphtha feedstocks, vulcanization accelerators, and aqueous adhesive systems. Single-source vulnerability concentrates in Louisiana polymerization assets facing EPA emission cap compliance timelines. Distribution runs through direct-to-brand procurement platforms that bypass regional wholesale intermediaries for California and Queensland apparel labels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neoprene fabric market functions as a defensive-moat arena where regulatory entrenchment through REACH SVHC compliance and FDA biocompatibility certification creates switching costs that protect incumbent positioning.
For Market Incumbents: Consolidate aqueous lamination capacity in Vietnam and Indonesia to capture premium watersports procurement shifting away from solvent-dependent competitors. Deepen backward integration into chloroprene monomer production to offset feedstock volatility threatening margin stability. Accelerate halogen-free flame-retardant qualification ahead of ECHA restriction proposals to entrench Stuttgart automotive supply chain relationships.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for medical-grade coated neoprene open specification-grade segments where ISO 10993 testing burdens deter commodity converters. Target Maharashtra and Gujarat industrial safety corridors where BIS certification mandates are opening demand for cost-efficient grades. Deploy digital textile printing integration capabilities to capture custom wetsuit direct-to-consumer channels bypassing traditional distributor networks.
For Investors and Strategic Acquirers: Capital is best deployed toward converters with captive aqueous adhesive lines and REACH-equivalent traceability systems serving medical and aerospace certification tiers. Long-term viability hinges on regulatory compliance infrastructure rather than commodity polymerization scale. Monitor ECHA substance restriction timelines as inflection indicators for halogen-free formulation transition acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chloroprene Monomer | ARLANXEO leverages captive feedstock supply to sustain cost advantages across European and Asian markets. |
| Aqueous Adhesive Line Conversion | California wetsuit brands commit procurement volumes to eliminate VOC exposure in lamination operations. |
| Halogen-Free Flame-Retardant Qualification | Stuttgart automotive suppliers reformulate specifications ahead of anticipated REACH restriction listings. |
| Direct-to-Brand Procurement Platform | Queensland diving labels bypass wholesale intermediaries through direct converter relationships with rapid sampling. |
| ISO 13485 Quality System Certification | Medical device manufacturers require lot-traceable neoprene creating specification premiums for compliant converters. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with polymerization plant managers, procurement leads at watersports OEMs, distribution channel partners, and technical R&D directors; and secondary validation through customs trade data, ACC synthetic rubber reports, SEC 10-K filings, and ECHA substance restriction proposals. Bottom-up segment sizing triangulated against top-down market aggregation to ensure consistency across value chain stages.
Across the analysis window, the forecasting framework modeled grade tier, end-use industry, certification status, and regional production hub dimensions. CAGRs derived from elasticity-adjusted demand projections incorporating MEE enforcement intensity, EPA compliance timelines, and F-Gas Regulation phase-down schedules. Industry-specific inputs included chloroprene monomer capacity utilization rates and aqueous lamination line deployment trajectories.
Underlying assumptions cover sustained dual carbon enforcement in China, REACH SVHC list expansion, and EPA emission cap adherence, with deviation risk concentrated in substitution acceleration for bio-rubber alternatives and tariff exposure on Asian converter exports. Recalibration cycles align with material shifts in regulatory chemistry mandates and polymerization capacity consolidation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Extruded PLA Fiber Market
Synthetic Fibers
Fiberglass Roving Market
Synthetic Fibers
Asia-Pacific Lyocell Fibers Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Synthetic Textile Fiber Market
Synthetic Fibers
IMO Fiber Market
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Conductive Fibers Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Textile Fibers Market
Synthetic Fibers
Regenerated Fibers Market
Synthetic Fibers
Designer Fiber Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
Americas Spandex Market