

Embossed Polyester Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Embossed Polyester Fabric Market Insights
The embossed polyester fabric sector is pivoting on a widening gap between premium automotive-grade materials and commodity home-textile grades, with surface durability specifications and flame-retardant certifications now separating pricing tiers by a factor of three or more. Toray Industries leverages its polymer science heritage to anchor supply relationships with Japanese and European automotive OEMs requiring embossed textures with precise abrasion resistance. Gabriel competes through specialized coating and lamination capabilities that extend performance properties into marine and aviation interior segments. Haining FengCai Textile dominates the mid-market home furnishing channel with integrated weaving and embossing operations in China's Haining cluster.
Embossed polyester fabric is a thermoplastic textile produced by pressing heated rollers or engraved plates against woven or knitted polyester substrates to create raised, permanent surface patterns; typical constructions employ 75–150 denier filament yarns with embossing depths of 0.2–1.2 millimeters to achieve dimensional stability and tactile differentiation for upholstery and apparel applications. Plain embossed and twill embossed variants sustain the largest volume positions due to their compatibility with high-speed roll-to-roll processing and broad applicability across furniture and automotive seating programs. Satin embossed fabric occupies the highest margin pool within the texture pattern category, as its lustrous surface finish commands premium positioning in hospitality and executive office furnishing segments where visual sophistication drives procurement decisions.
The EPA's volatile organic compound emission limits for coated fabrics and California's Proposition 65 disclosure requirements are reshaping formulation choices for embossing lubricants and surface treatments in the US market, while REACH restrictions on phthalate plasticizers in Europe are forcing reformulation of soft-touch embossed coatings used in automotive interiors. China's GB standards for textile formaldehyde content and combustion performance, enforced by SAMR provincial offices, determine factory-level export eligibility for Zhejiang-based producers serving EU and North American buyers. Stakeholders must monitor accelerating regulatory divergence between jurisdictions, as compliance investments in one market may not transfer to another, complicating platform standardization strategies for multinational supply chains.
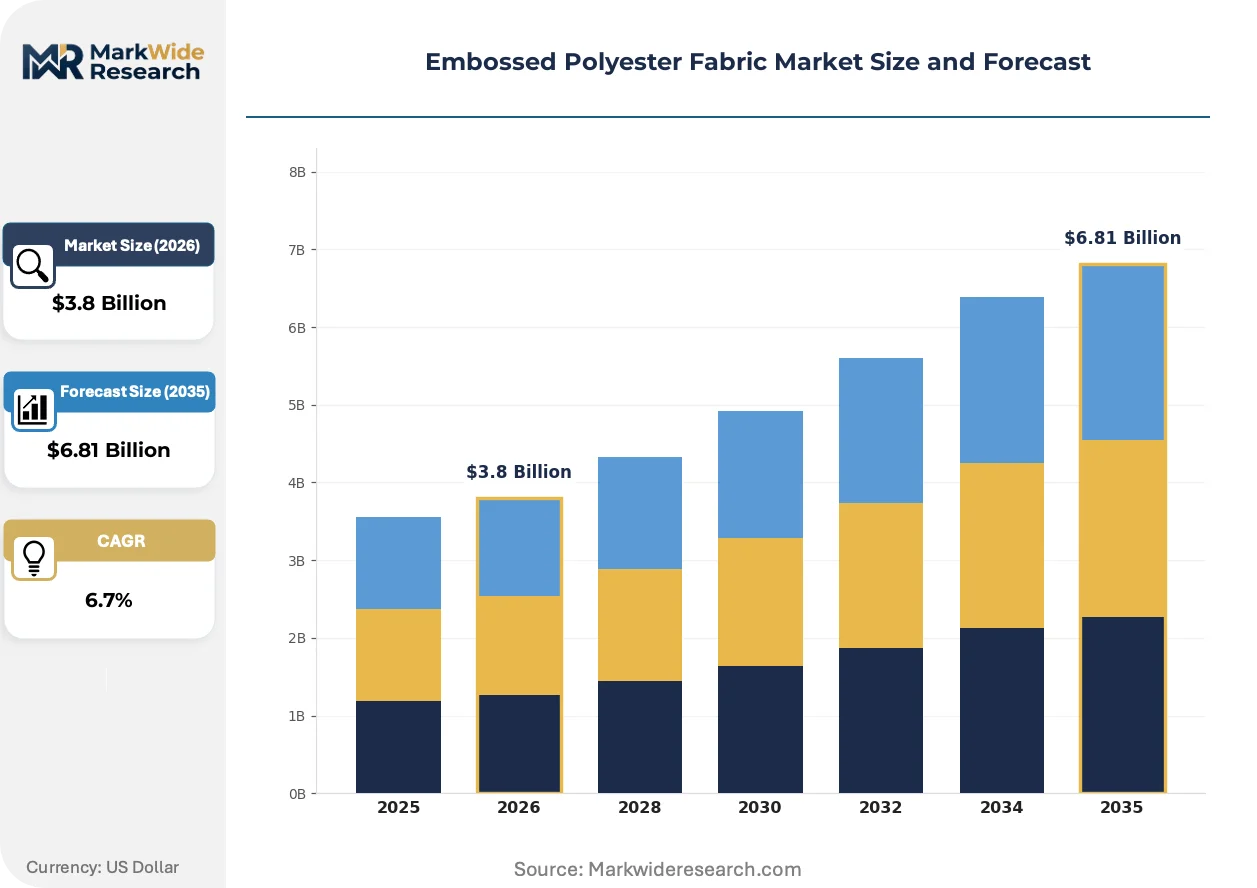
Market Dynamics
Automotive OEMs now specify embossed polyester with abrasion resistance thresholds exceeding 100,000 Martindale cycles, forcing fabric finishers to retool thermal calendering lines or exit premium supply tiers entirely.
Growth Catalysts
- REACH flame-retardant mandates:European automotive seating regulations now require halogen-free embossed substrates, pulling technical textile investment toward phosphorus-based coating systems.
- China's integrated Haining cluster:Proximity of warp knitting, dyeing, and embossing operations within 50-kilometer radii compresses lead times for export orders.
- Digital engraving roller technology:Laser-etched pattern cylinders enable 72-hour design-to-production turnaround for hospitality custom runs.
Market Restraints
- PTA and MEG feedstock volatility:Purified terephthalic acid prices swing with crude oil futures, compressing embossing house margins on fixed-price automotive contracts.
- Zhejiang-Jiangsu supply concentration:Sixty percent of global embossed polyester finishing capacity sits within flood-prone Yangtze River delta zones.
- Polypropylene substitution in marine:Solution-dyed PP fabrics with UV stabilizers displace embossed polyester in saltwater-exposed seating.
Strategic Opportunities
- India's PLI textile scheme:Duty drawbacks and capital subsidies for technical textile investments are drawing embossing equipment imports into Tamil Nadu and Gujarat.
- Aviation interior retrofit cycles:Post-pandemic narrow-body refurbishment programs specify lighter embossed fabrics to reduce seat weight.
- EU Green Deal public procurement:Recycled-content mandates for institutional furniture create certified demand pools for rPET embossed substrates.
Industry Challenges
- Skilled calendering operator scarcity:Temperature-pressure-nip speed optimization requires apprenticeship pipelines that Chinese vocational systems no longer prioritize.
- OEKO-TEX and bluesign certification lag:Six-to-nine-month audit timelines delay market entry for Southeast Asian embossing startups.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embossed Polyester Fabric Market Trends and Innovations
Thermal processing advances and chemical formulation shifts are compressing pattern replication tolerances while regulatory chemistry constraints force coating system redesigns.
Laser-engraved ceramic roller surfaces are rewriting precision benchmarks for micro-embossed automotive seating textures. Tier 1 suppliers in Stuttgart and Nagoya now specify ±0.05 millimeter pattern depth uniformity across 3,000-meter production runs. This precision threshold is squeezing mechanical engraving houses out of premium supply chains.
EPA volatile organic compound limits for coated fabrics are forcing water-based embossing lubricant adoption across US upholstery producers. Formulation houses in North Carolina and Los Angeles are phasing out solvent-borne release agents. California Proposition 65 disclosure requirements add compliance documentation burdens for imported textured substrates.
Automotive OEMs now mandate recycled-content certificates for embossed polyester in concept vehicle interiors. Procurement teams at BMW and Volvo audit filament yarn provenance back to bottle-sorting facilities. This traceability requirement is fragmenting supplier bases between certified rPET channels and virgin-only producers.
Embossed Polyester Fabric Market Segmentation
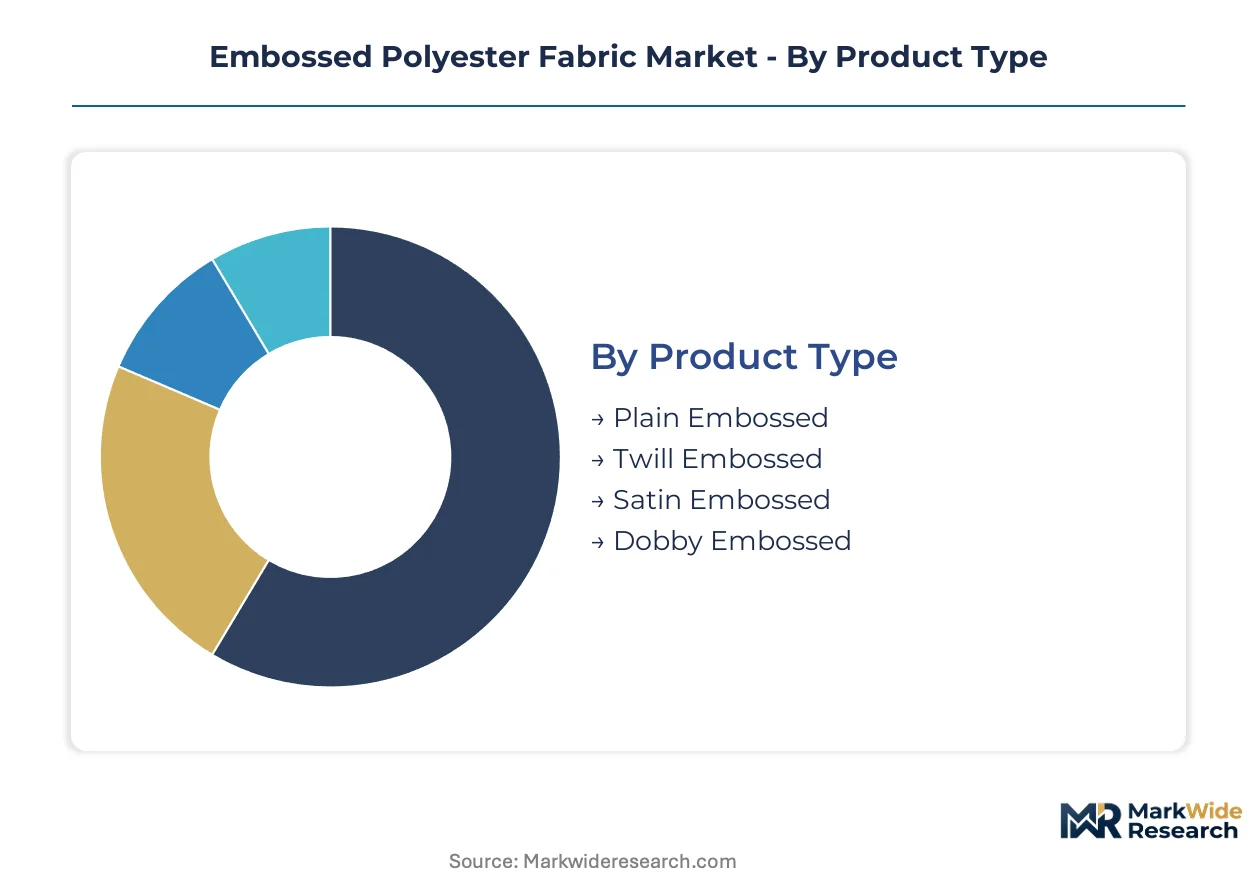
Embossed polyester fabric procurement hinges on surface durability specifications and flame-retardant certification tiers, with automotive OEMs and hospitality specifiers demanding divergent performance envelopes. Segmentation reveals how thermal calendering capabilities and pattern replication precision stratify supplier positioning across end-use verticals.
Product Type:
Automotive seating engineers and hospitality procurement teams prioritize abrasion resistance thresholds and surface luster when selecting embossed constructions.
- Plain Embossed:Simple raised patterns pressed into 75–150 denier woven substrates deliver cost-efficient dimensional stability for high-volume furniture programs. Demand concentrates in China's Haining cluster, where integrated warp knitting and embossing operations serve export-oriented home furnishing buyers requiring 50,000+ Martindale cycle ratings at mid-tier price points.
- Satin Embossed:Lustrous filament yarn constructions with micro-embossed textures command premium positioning in executive office and hospitality segments. German and Japanese automotive OEMs specify satin embossed fabrics for concept vehicle interiors, mandating recycled-content certificates and ±0.05 millimeter pattern depth uniformity that excludes mechanical engraving houses from supply chains.
- Twill Embossed:Diagonal rib constructions pressed with thermal calendering provide structural resilience for marine and aviation seating applications.
- Dobby Embossed:Small geometric patterns created via specialized loom attachments before final embossing serve niche decorator and event rental channels.
Volume sits with Plain Embossed; growth tilts toward Satin Embossed.
Texture Pattern:
Pattern selection correlates directly with end-use margin pools, as custom engraving roller investments amortize differently across hospitality custom runs versus automotive platform volumes.
- Geometric:Laser-etched linear and angular patterns enable 72-hour design-to-production turnaround for hospitality specification teams. Digital engraving technology in Stuttgart and Nagoya now achieves pattern depth uniformity across 3,000-meter production runs, compressing lead times for premium automotive seating programs.
- Floral:Botanical motifs require deeper embossing dies and specialized release agent formulations to prevent pattern distortion during thermal processing. European REACH restrictions on phthalate plasticizers force reformulation of soft-touch coatings used in floral-embossed automotive interiors, extending certification timelines for Zhejiang-based finishers.
- Abstract:Non-representational patterns accommodate rapid style cycling in fast-fashion upholstery channels with minimal tooling changeover.
- Striped:Linear embossed textures align with minimalist office furnishing aesthetics in Nordic and North American contract markets.
- Damask:Reversible figured patterns demand precise registration between embossing rollers and woven substrate grain, limiting viable supplier bases to vertically integrated operations.
Geometric patterns dominate current procurement volumes; Damask commands the steepest expansion trajectory in luxury hospitality retrofit programs.
Application:
Performance specifications diverge sharply between interior environments, with saltwater exposure and UV degradation creating substitution risks in marine segments.
- Automotive Interiors:OEM abrasion thresholds exceeding 100,000 Martindale cycles force fabric finishers to retool thermal calendering lines or exit premium supply tiers. BMW and Volvo procurement teams audit filament yarn provenance back to bottle-sorting facilities, fragmenting supplier bases between certified rPET channels and virgin-only producers.
- Home Furnishing:Mid-market upholstery programs in North America and Europe specify embossed polyester for durability-to-price ratios superior to natural fiber alternatives. EPA volatile organic compound limits and California Proposition 65 disclosure requirements reshape formulation choices for embossing lubricants across US upholstery producers.
- Outdoor Gear:Solution-dyed polypropylene fabrics with UV stabilizers increasingly displace embossed polyester in saltwater-exposed seating, constraining addressable market scope.
- Office Furnishing:Institutional procurement under EU Green Deal mandates creates certified demand pools for recycled-content embossed substrates in public sector furniture.
- Fashion Apparel:Lightweight embossed constructions for outerwear and accessories face margin pressure from synthetic leather alternatives.
Home Furnishing anchors volume; Automotive Interiors is gaining share fastest as electrification platforms prioritize interior material differentiation.
End User Industry:
Technical capability requirements and certification burdens stratify accessible customer segments for embossing houses.
- Textile Manufacturers:Integrated weaving and finishing operations in Zhejiang and Jiangsu provinces dominate global embossed polyester capacity, with 60 percent of finishing operations concentrated in flood-prone Yangtze River delta zones. SAMR enforcement of GB standards for formaldehyde content and combustion performance determines factory-level export eligibility.
- Upholstery Workshops:Small-batch custom operations in Italy and North Carolina drive demand for digital engraving flexibility and rapid pattern prototyping.
- Garment Producers:Apparel-focused buyers prioritize drape and hand-feel over abrasion resistance, accessing lower-specification embossing tiers.
- Event Decorators:Rental and staging companies specify disposable-price embossed fabrics for temporary installations, concentrating procurement in spot-market channels.
Textile Manufacturers capture volume concentration; Upholstery Workshops show the steepest growth curve as customization premiums expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Haining anchors global embossed polyester finishing capacity through its integrated warp knitting and embossing corridor, where proximity of dyeing, weaving, and thermal calendering operations within 50-kilometer radii compresses lead times for export orders.
China
Automotive OEMs in Stuttgart and Nagoya source halogen-free embossed substrates from Zhejiang and Jiangsu provinces. SAMR provincial offices enforce GB standards for formaldehyde content and combustion performance, determining factory-level export eligibility. The Yangtze River delta concentration leaves sixty percent of global finishing capacity exposed to flood-prone zones.
United States
EPA volatile organic compound limits for coated fabrics reshape formulation choices for embossing lubricants across North Carolina and Los Angeles upholstery producers. California Proposition 65 disclosure requirements add compliance documentation burdens for imported textured substrates. Domestic finishers phase out solvent-borne release agents under tightening federal emission thresholds.
Germany
REACH restrictions on phthalate plasticizers force reformulation of soft-touch embossed coatings used in automotive interiors. Stuttgart-based Tier 1 suppliers specify laser-etched pattern cylinders achieving ±0.05 millimeter depth uniformity. Bavarian upholstery workshops drive demand for rapid pattern prototyping through digital engraving flexibility.
Japan
METI-backed technical textile investments support Nagoya-area finishers serving premium automotive seating programs. JIS standards for abrasion resistance align with OEM thresholds exceeding 100,000 Martindale cycles. Kanto-based polymer science heritage anchors supply relationships requiring precise surface durability specifications.
India
PLI textile scheme duty drawbacks and capital subsidies draw embossing equipment imports into Tamil Nadu and Gujarat. DGFT regulations govern technical textile investment eligibility for domestic producers. Surat-based integrated operations target mid-market home furnishing export channels with compressed cost structures.
Embossed Polyester Fabric Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and precision thresholds, with automotive-grade suppliers commanding threefold pricing multiples over home-textile finishers. The vendor base stratifies into three tiers: polymer science heritage firms, specialized coating and lamination houses, and integrated weaving-embossing clusters. Consolidation pressure intensifies as thermal calendering line retooling costs exceed ten million dollars per installation. Dominant competitive moves include backward integration into filament yarn production and geographic expansion into India's subsidized textile zones.
Within the polymer science heritage tier, Toray Industries exemplifies premium-tier positioning through its Japanese automotive OEM relationships. Among China-based integrated producers, Haining FengCai Textile occupies a scale-driven position in the mid-market home furnishing channel. Specialists in coating and lamination capabilities include Gabriel, which represents the diversified performance properties archetype extending into marine and aviation interior segments.
| Leading Market Players |
|---|
| Toray Industries |
| Gabriel |
| Perfectextile |
| Cxdqtex |
| Ocean Textile |
| Sunlantex |
| Haining FengCai Textile |
| Changxing Yongxin Textile & Dyeing |
| Haining Juncheng Textile |
| Others |
Pricing and Supply Chain Analysis
Purified terephthalic acid and monoethylene glycol feedstock costs cascade through embossed polyester pricing tiers, compressing margins at mechanical engraving houses while laser-etched precision suppliers capture threefold premiums from Stuttgart and Nagoya automotive OEMs.
Pricing Analysis
Martindale cycle ratings anchor value-based pricing, with automotive-grade embossed fabrics commanding substantial premiums over home-textile grades based on abrasion resistance thresholds and flame-retardant certification tiers. Price differentiation rests on laser engraving precision and REACH compliance status, with halogen-free phosphorus-based coating systems extracting margin premiums. Pricing pressure stems from fixed-price automotive contracts confronting PTA and MEG volatility, eroding finishers lacking backward integration into filament yarn production. Home furnishing buyers exhibit highest price sensitivity, while aviation and premium automotive procurement teams prioritize performance specifications over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from BMW and Volvo procurement teams mandate multi-supplier qualification across certified rPET channels and virgin-only producers, fragmenting supplier relationships. Geographic supply concentrates in China, Germany, and Japan, with Zhejiang and Jiangsu provinces hosting sixty percent of global finishing capacity. Raw material dependencies draw from PTA and MEG petrochemical feedstocks, laser-engraved ceramic rollers, and phosphorus-based flame-retardant formulations. Supply chain risk centers on flood-prone Yangtze River delta concentration threatening production continuity. Distribution runs through Tier 1 automotive suppliers, hospitality specifiers, and integrated textile exporters serving institutional furniture channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH flame-retardant mandates and evolving GB standards construct a cost-of-compliance moat, with certification investments and audit timelines excluding Southeast Asian embossing startups from premium supply tiers.
For Market Incumbents: Anchor supply relationships through captive filament yarn provenance systems that satisfy BMW and Volvo traceability audits back to bottle-sorting facilities. Deepen thermal calendering precision capabilities to maintain ±0.05 millimeter pattern depth uniformity thresholds that exclude mechanical engraving competitors. Prioritize laser-etched ceramic roller investments over ten-million-dollar line retooling costs that force exit decisions from premium tiers. For New Entrants and Emerging Players: Enter via India's PLI textile scheme subsidy corridors in Tamil Nadu and Gujarat, where duty drawbacks and capital subsidies compress equipment import costs for technical textile investments. Target mid-market home furnishing channels in Surat-based integrated operations, leveraging compressed cost structures against Haining cluster incumbents. Pursue rapid pattern prototyping services for Bavarian upholstery workshops demanding digital engraving flexibility. For Investors and Strategic Acquirers: Six-to-nine-month OEKO-TEX and bluesign certification timelines are the leading indicator that compliant asset bases will command scarcity premiums as regulatory divergence accelerates between jurisdictions. Long-term viability favors polymer science heritage firms with backward integration into filament production and established automotive OEM relationships. Monitor aviation interior retrofit program specifications for lighter embossed fabric adoption as narrow-body refurbishment cycles intensify.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Engraving Precision Investment | Achieves ±0.05mm pattern depth uniformity required by Stuttgart Tier 1 suppliers. |
| Backward Integration into Filament Yarn | Captures rPET provenance control for BMW and Volvo recycled-content mandates. |
| Phosphorus-Based Coating System Adoption | Satisfies REACH halogen-free mandates pulling technical textile investment. |
| India PLI Scheme Geographic Expansion | Accesses Tamil Nadu and Gujarat capital subsidies for embossing equipment imports. |
| Aviation Interior Certification Pursuit | Captures narrow-body refurbishment programs specifying lighter seat fabrics. |
Research Methodology
Trade databases, automotive OEM technical specifications, and SAMR GB standards enforcement records formed the secondary backbone, supplemented by customs data on PTA and MEG feedstock flows. Primary interviews with thermal calendering line operators, automotive Tier 1 procurement managers, hospitality specification consultants, and Zhejiang textile cluster plant directors validated demand assumptions. Bottom-up triangulation across embossing house capacity utilization and top-down reconciliation against end-use consumption patterns anchored volume estimates.
Historical trendline analysis of automotive seating content per vehicle, hospitality retrofit cycle timing, and institutional furniture procurement volumes established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, texture pattern, application vertical, and end-user industry dimensions. CAGRs derived from elasticity analysis against vehicle production forecasts, construction spending indices, and aviation fleet renewal schedules. Industry-specific inputs included Martindale cycle specification trends and laser engraving technology adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme weather events affecting Yangtze River delta production zones or abrupt REACH formulation bans. Deviation in PTA and MEG feedstock pricing volatility would shift margin compression patterns materially across fixed-price automotive contract tiers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.